


Carbon permits in the European Union have recently climbed to their highest levels since August 2023. The rise reflects tighter supply, policy decisions, and shifting market demand under the EU Emissions Trading System (ETS).
The ETS is the world’s largest cap-and-trade system for greenhouse gas emissions. It mandates large emitters to buy allowances for the carbon dioxide they emit. These allowances are known as EU Allowances (EUAs).
EUAs are now trading at a price over €92 per tonne — the strongest level in about 18 months. This rise shows that companies and markets expect fewer allowances to be available in the future as the EU tightens its emissions cap.
What Is the EU Emissions Trading System?
The EU ETS began in 2005 as a tool to reduce greenhouse gas emissions through market forces. It sets a cap on total emissions from major sectors such as power generation, manufacturing, and aviation. Companies must hold enough allowances to cover their emissions each year.
The cap reduces over time, meaning fewer EUAs are issued. This creates scarcity. As allowances become scarcer, their price tends to rise, which increases costs for polluters. In theory, this pushes companies to reduce emissions or invest in cleaner technology.
In 2026, the system also overlaps with the Carbon Border Adjustment Mechanism (CBAM), a tax on imported carbon-intensive goods. CBAM began to apply in January 2026 and makes carbon costs visible on imports like steel and cement. The measure aims to cut down on “carbon leakage.” This happens when industries move production to areas with cheaper carbon prices.
Recent Price Moves: Highest Since August 2023
In early January 2026, EU carbon permits climbed as high as about €91.82 per tonne on EU markets, up from lower levels earlier in 2025. Now, it’s trading at over €92 per tonne, showing 27% increase from January 2025 prices. The rise represents a fourth consecutive weekly gain in allowances for the December 2026 contract.

The price rise reflects tightening supply — fewer allowances are available through auctions and free allocations. Reduced supply increases competition among companies that must surrender EUAs to match their emissions. This dynamic pushes the price higher.
Market analysts also note that colder weather and more heating needs in winter often boost industrial energy demand. This can lead to higher carbon prices during the season.
Why Prices Have Risen?
The recent uptick in EU carbon prices is driven by several key factors:
- Reduced Supply of Allowances:
The EU continues to tighten its emissions cap and reduce the number of new allowances issued. Estimates from the European Exchange auction calendar and Market Stability Reserve show that auction volumes will drop. They are expected to fall from about 588.7 million EU Allowances in 2025 to around 482.4 million in 2026. A stronger cap reduces the total pool of tradable EUAs, creating scarcity and upward pressure on prices.
- Policy Signals and Reform Expectations:
Investors and companies anticipate future regulatory tightening. The EU’s long-term climate goals include cutting net emissions by 90% by 2040 compared with 1990 levels. Such policy signals can strengthen confidence that carbon costs will rise further.
- Market Confidence and Funds:
Investment funds have increased their holdings of EU carbon futures. Trading positions and speculation can also influence price momentum, especially as market sentiment shifts toward tighter futures.
- Compliance Demand:
Industries covered by the ETS are required to surrender allowances to match their emissions by compliance deadlines. As deadlines near, buying activity can increase, adding short-term upward pressure on prices.
- Carbon Border Adjustment Mechanism:
With CBAM now active, imported products from outside the EU face carbon costs similar to domestic industries. This mechanism can reduce free allowance allocations and tighten supply further.
Looking Back and Ahead: Carbon Price Trends and Forecasts
Carbon prices in the EU ETS have fluctuated over recent years. Prices surged above €100 per tonne in early 2023. Then, they eased back in 2024 and 2025. This decline was due to shifting market conditions and wider economic factors.
In 2024, the average price of EU ETS carbon permits was around €65 per tonne, down from €84 per tonne the year before. High prices in 2023 reflected strong policy signals from the Fit for 55 climate package and global energy disruptions.
Looking ahead, analysts and forecast models expect prices to continue rising over the coming decade:
- A survey of market participants predicts that the average EU ETS carbon price will rise to almost €100 per tonne from 2026 to 2030. This increase will happen as demand exceeds supply.
- Energy market analysts predict that the average price could hit about €126 per tonne by 2030. This rise is due to stricter caps and wider emission coverage.
- Under the EU ETS II framework, starting in 2027, more sectors will be included, like buildings and transport. In some scenarios, prices might average €99 per tonne from 2027 to 2030.
- BNEF’s EU ETS II Market Outlook projects carbon prices reaching €149 per metric ton ($156/t) by 2030, driving substantial emissions reductions.

Overall, these forward estimates imply that allowance prices may continue to rise as the EU strengthens its emissions targets to meet climate goals.
Emissions Reductions Under the ETS
The EU ETS has contributed to measurable emissions reductions. In 2024, emissions under the system were roughly 50% lower than in 2005. This progress is set to help the EU meet its 2030 goal of a 62% reduction from 2005 levels. The decline was driven mainly by cuts in the power sector, with increased renewable energy and a shift away from coal and gas.
Renewable energy growth, including wind and solar, played a role. Increases in renewables helped lower emissions by reducing reliance on fossil fuels.
The drop in emissions may lead to higher demand for allowances in the long run. With fewer emissions, companies will need more allowances to meet the cap.
What Higher Carbon Prices Mean for Industry
Higher carbon prices affect the European economy in many ways. For polluting industries, rising carbon costs increase operating expenses. Companies may invest more in cleaner technologies to reduce their allowance needs. This can accelerate decarbonization technology adoption.
Policy makers face the challenge of balancing climate goals with economic competitiveness. Some EU governments, like France, want price limits in the ETS. This could stop big swings in carbon costs. It would also help industries plan better.
The Market Stability Reserve (MSR), a mechanism to absorb excess allowances, also plays a role. It intends to reduce surplus permits and stabilize prices. Combined with the tightening cap, the MSR tends to push prices higher over time.
The ETS’s expansion to include more sectors — such as maritime transport and potentially buildings and road transport under EU ETS II — expands the share of emissions subject to carbon pricing. This broadening can further tighten supply and push prices up.
Why EU Carbon Prices Matter Beyond Europe
The EU ETS remains the largest carbon market in the world. According to global carbon pricing data, carbon pricing instruments currently cover about 28% of global greenhouse gas emissions, up from about 24% previously. The EU’s system is a key driver of this trend.

Many national and regional carbon markets have prices much lower than the EU’s. This shows differences in climate policies and economic situations. The ETS’s tightening emissions cap, reduced auction volumes, and shifting market sentiment all play roles in supporting higher carbon prices.
Forecasts suggest that prices may continue upward in the years to come, potentially averaging over €100 per tonne by the end of the decade. Meanwhile, the ETS continues to help reduce emissions in key sectors and supports the EU’s broader climate targets.
These price trends and policy developments make the EU carbon market a central piece of Europe’s climate strategy and an important bellwether for global carbon pricing efforts.
The post EU Carbon Prices Hit Highest Since August 2023: What Causes The Surge? appeared first on Carbon Credits.

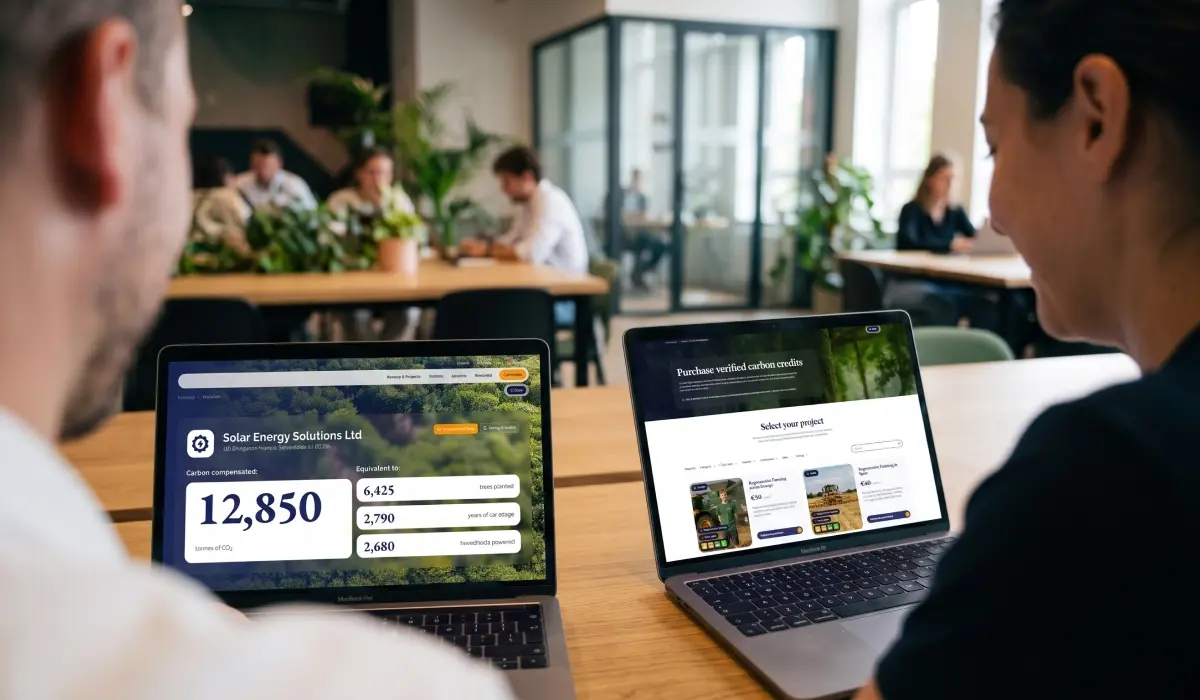
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits