

Sasol Ltd., a South African energy and chemicals firm, is gaining attention. They reported stronger earnings and are shifting their strategy to buy more carbon credits. The move comes as the company, the second-biggest emitter of greenhouse gases in the region, boosts coal production and grows its renewable energy portfolio.
Investors, regulators, and climate observers are watching closely to see how Sasol balances its reliance on fossil fuels with its stated commitment to reaching net-zero emissions.
Earnings Power: Fueling a Dual Strategy
In its latest earnings report, Sasol posted a year-on-year improvement supported by stable product prices and efficiency gains. The company’s operating profit rose due to stronger chemical sales.
However, this was partly offset by higher costs in its coal division. Earnings were strong, giving Sasol the money to invest in fossil fuels and low-carbon projects.
For the fiscal year ending June 30, the company earned 10.60 rand per share. This is a turnaround from a loss of 69.94 rand per share. Asset write-downs fell sharply to 20.7 billion rand, down from 74.9 billion rand last year.
Sasol gained from a 4.3 billion rand settlement with Transnet over oil transport fees. Capital expenditure dropped 16% to 25.4 billion rand. This helped improve the company’s financial profile.
Management highlighted that a resilient balance sheet is critical as the company continues its transition journey.
Sasol has steady cash flows. This helps support its short-term coal operations. It also funds longer-term projects like renewable energy growth and carbon reduction efforts.
Sasol’s renewed profit helped lift investor sentiment. Following the earnings, the company’s shares climbed 7% in pre-market trading. Its stock on the Johannesburg Stock Exchange (JSE: SOL) surged by 44% over the last quarter.
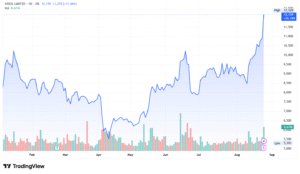
Analysts predict that earnings per share will increase by 20% year-on-year. This shows rising confidence in the company’s ability to balance profit and sustainability.
Rising Carbon Credit Purchases: Flexibility or Delay?
One of the biggest headlines is Sasol’s decision to boost its purchase of carbon credits.
- In the fiscal year that ended in June 2025, Sasol’s carbon credit purchases increased to R723 million, a 25% increase year-on-year.
- This amount was nearly triple the value of the credits it bought in 2023.
- Since 2019, Sasol has acquired more than 11 million South African carbon credits, which has reduced its carbon tax liability by more than R650 million.
Most of these credits come from international renewable energy and reforestation projects, while some are linked to African-based carbon offset programs. Sasol plans to grow its carbon credit portfolio, showing its commitment to climate responsibility.
- Wonderbag: In 2021, Sasol announced it would use carbon credits generated by the Wonderbag project, which provides non-electric heat-retention cookers to reduce household emissions.
- Bethlehem Hydro: In 2020, Sasol purchased over 100,000 credits from Bethlehem Hydro, a 7MW hydropower plant that was the first Independent Power Producer in South Africa.
- Nitrous oxide abatement: As far back as 2007, Sasol received credits for a nitrous oxide abatement project at its nitric acid plants in Sasolburg and Secunda.
However, it recognizes that cutting emissions from its own operations is tough in the near term. The company plans to steadily increase reliance, but acknowledges that credits are a temporary solution.
The use of credits has generated debate. Supporters say it gives companies flexibility to meet interim targets while low-carbon technologies scale.
Critics argue it can delay direct emissions cuts. Sasol’s growing use of offsets shows the urgent climate pressures and the challenges of moving away from coal.
Coal’s Grip: South Africa’s Energy Dilemma
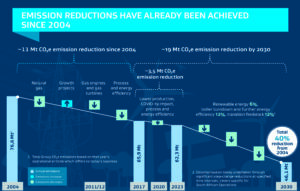
Sasol is one of South Africa’s top coal users. It relies on coal for power and to make synthetic fuels and chemicals. Its Secunda plant is one of the single largest point sources of carbon dioxide globally, emitting more than 56 million tons of CO₂ equivalent each year.
The world’s biggest producer of fuels and chemicals from coal emits around 63 million tons of CO₂ equivalent each year. This makes it one of Africa’s largest industrial polluters.
The company believes coal is still essential for South Africa’s energy and industry right now. This is especially true due to the country’s electricity shortages and its dependence on Eskom, the state utility. Sasol knows that relying on this can lead to risks such as regulatory pressure, investor scrutiny, and possible costs from future carbon pricing.
Counting Carbon: Sasol’s Net-Zero Targets and Progress
Despite its coal footprint, Sasol has stepped up efforts to diversify its energy mix. The company is putting money into renewable energy projects. This includes solar and wind farms. These efforts will help provide cleaner electricity for its operations.
Moreover, partnerships with independent power producers are helping Sasol shift portions of its energy use away from coal-generated power.
In addition, Sasol is advancing work in green hydrogen and sustainable aviation fuel (SAF). Its Fischer-Tropsch technology, long used for coal-to-liquids production, is being adapted for cleaner feedstocks, such as natural gas and green hydrogen. The company announced pilot projects to produce low-carbon chemicals for local and global markets.
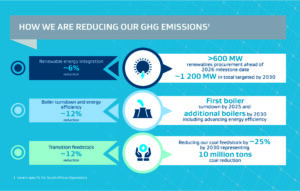
Sasol aims to cut its Scope 1 and 2 emissions by 30% by 2030. This goal uses a 2017 baseline, which is about 72 million tons of CO₂e. Progress: current emissions are down about 13% from baseline.
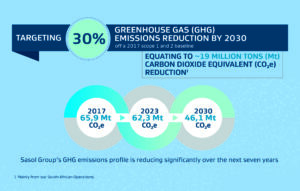
It aims for net-zero emissions by 2050. However, it admits that success relies on policy support, technological progress, and available funding.
In summary, Sasol’s key emission reduction initiatives are:
-
Green hydrogen projects – Developing hydrogen production in South Africa through partnerships to support cleaner fuels and power.
-
Renewable energy procurement – Securing up to 1,200 MW of renewable electricity (wind and solar) to replace coal-based power at operations.
-
Energy efficiency improvements – Implementing process optimization and equipment upgrades to reduce energy use across its facilities.
-
Coal-to-gas transition – Shifting part of its feedstock mix from coal toward natural gas, which has a lower carbon footprint.
-
Carbon capture and utilization (CCU) – Exploring technologies to capture CO₂ from operations for use in chemicals or fuels.
-
Sustainable aviation fuel (SAF) development – Advancing projects to produce low-carbon jet fuel from sustainable feedstocks.
-
Offsets and carbon credits – Expanding purchases of carbon credits to compensate for hard-to-abate emissions.
Markets in Motion: Offsets, Renewables, and Risks
Sasol’s strategy reflects broader challenges facing energy and industrial companies worldwide. Carbon credits are gaining popularity. The voluntary carbon market was worth over $2 billion in 2024. It’s expected to grow to nearly $50 billion by 2030, under the best-case scenario.

However, the credibility of offsets is under scrutiny, and investors are demanding more transparency on how credits are used.
At the same time, global coal demand remains strong, particularly in emerging markets. South Africa’s energy system still relies heavily on coal, which generates about 80% of the country’s electricity. This makes decarbonization complex, as companies like Sasol must balance energy security with climate commitments.
Meanwhile, renewable energy costs continue to fall. According to the International Renewable Energy Agency (IRENA), solar and wind are now the cheapest forms of new power generation in most regions. For Sasol, scaling renewables not only helps reduce emissions but also lowers long-term energy costs.
Balancing Growth, Risk, and Climate Goals
Sasol’s higher earnings give it the financial strength to follow its dual-track strategy. This means it can keep expanding coal operations and invest in low-carbon solutions. The company’s growing purchase of carbon credits shows its urgent need to meet climate goals. It also reflects the challenge of cutting emissions from coal-heavy operations.
Sasol’s future will depend on whether it can scale up renewable energy, develop viable low-carbon technologies, and manage the risks tied to its coal reliance. Its net-zero commitment remains a long-term goal. Yet, the company’s latest moves suggest it is trying to walk a fine line between financial performance and climate responsibility.
The post Sasol’s (SSL) Stock Rises on Profits, Carbon Credit Surge, and Net-Zero Push appeared first on Carbon Credits.

Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
CCC’s MRV and Additionality article explains the separate evidence questions a project reviewer will ask.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Sources
[1] GHG Protocol, Land Sector and Removals Standard, version 1.1, and companion Guidance, June 2026: https://ghgprotocol.org/land-sector-and-removals-standard ; https://ghgprotocol.org/land-sector-and-removals-guidance
[2] Science Based Targets initiative, Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, especially pp. 16–17, 37, and 41: https://sciencebasedtargets.org/resources/files/SBTiFLAGGuidance.pdf
[3] Accountability Framework initiative, Accountability Framework and guidance for companies: https://accountability-framework.org/
[4] GHG Protocol, Frequently Asked Questions: Land Sector and Removals Standard, questions 10 and 18: https://ghgprotocol.org/blog/frequently-asked-questions-land-sector-and-removals-lsr-standard
Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
CCC’s guide to finding nature-based solutions in your supply chain explains where to look. Here, the next task is to turn a broad concern into a testable proposal.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3 Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
Discuss a sourcing opportunity with CCC
Carbon Credit Capital’s nature-based supply-chain investment service uses its Dual-Value Model to examine supply-chain economics alongside potential sustainability outcomes.
Schedule a consultation to discuss your sourcing exposure and the questions to resolve before allocating capital.
Sources
- Intergovernmental Panel on Climate Change (IPCC), Climate Change 2022: Mitigation of Climate Change, Chapter 7, Agriculture, Forestry and Other Land Uses, section 7.4.3.3 (Agroforestry).
- World Business Council for Sustainable Development (WBCSD), Nature-based Solutions Blueprint, 5 June 2024.
- Science Based Targets initiative (SBTi), Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, section 3.1.4, pp. 37–38.
- United Nations Environment Programme (UNEP), State of Finance for Nature 2023, 2023.
