

The installation of solar panels and heat pumps in UK homes soared in 2023, driving the country to its highest-ever level of domestic low-carbon technology upgrades.
Registered solar photovoltaic (PV) installations rose nearly 30% to a post-subsidy record of 189,826 in 2023, according to the Microgeneration Certification Scheme (MCS).
Similarly, heat-pump installations were up 20%, reaching a record 36,799.
This growth drove a UK record for the total number of domestic renewable electricity and low-carbon heat technologies installations registered by MCS, which reached 229,618.
This brings the total MCS-certified installations of solar PV overall to 1,441,753 since 2009, equivalent to more than 5% of all UK households.
The near-record figure for home solar in 2023 is particularly significant because it came without any government support, whereas previous growth was driven by deadlines under the Feed-in-Tariff (FiT) subsidy scheme, which ended in 2019.
Below, Carbon Brief looks at MCS’s installation figures for 2023, picking out some of the most significant domestic developments.
Record clean energy growth
The UK had already recorded its “best-ever” year for renewable energy and low-carbon heat installations before 2023 came to end, as Solar Power Portal reported in December.
While solar PV and air-source heat pumps (ASHP) saw growth in their installation rates in 2023, other clean technologies dropped off somewhat.
By the end of the year, a record total of 229,618 MCS certified installations had been registered (there is the potential for a small change to the total, due to a lag with registrations, MCS told Carbon Brief).
This included a post-subsidy record 189,826 solar PV installations, up by a third from the 138,020 seen in 2022.
Solar Energy UK chief executive Chris Hewett said in a statement:
“Setting a post-subsidy record of almost 190,000 smaller-scale solar PV installations, and approaching the all-time record of 203,000, is truly a moment to celebrate. The solar industry is on a roll, particularly as we start to conclude work on the government-industry Solar Taskforce, whose roadmap for delivering 70GW [gigawatts] of capacity is due to be published in a couple of months.”
The number of MCS-registered ASHP installations grew to a record 36,799 in 2023 from 29,490 a year earlier. (The real number of heat pumps installed in the UK is likely to be higher, as there is currently no mandate for all low-carbon technology deployments to be certified, or reported in a single place.)
Bean Beanland, director for growth at trade association the Heat Pump Federation, tells Carbon Brief the growth in demand for ASHPs was being driven by increasing activity from “early movers”, as well as by the boiler upgrade scheme (BUS) subsidy, which was introduced in 2022 and increased in 2023.
The BUS initially offered a £5,000 grant for those installing an ASHP or biomass boiler and £6,000 for a ground-source heat pump (GSHP). This was raised to £7,500 for both ASHPs and GSHPs in October 2023.
Beanland adds:
“[Following the increase in the grant] one of our members went back to all the consumers who they had quoted during 2023, detailing the increase, but where they had not converted the opportunity. The result was a significant number of contracts, so the additional £2,500 has certainly made a difference.
“In parallel, the whole visibility of the technology is being driven by the likes of Octopus, Good Energy and OVO, with their very high-profile campaigns and the advent of time-of-use tariffs that improve the financial benefits considerably.”
Customers who are able to afford to deploy solar PV, a battery and a heat pump can use such tariffs to reduce operational cost, allowing the heat pump to compete with gas, he adds.
The number of GSHP installations fell from 3,420 to 2,469, while solar-thermal installations nearly halved, falling from 615 to 311.
Beanland says:
“The value of the BUS for ground-source is just far too low. Government has made a conscious decision to go for numbers rather than the highest efficiency by supporting air-source to a much greater extent. This has been compounded now that the BUS levels for air- and ground- are the same.”
The surge in ASHP means that low-carbon heating technologies still saw an overall increase in 2023, rising by 20% year-on-year, as reported by BusinessGreen.
Despite this growth, however, the installation of heat pumps remains a long way from hitting the UK government target of 600,000 installations per year by 2028.

While the MCS dashboard does not provide data on battery storage installations, a recent release from the company states that 2023 was a record-breaking year for the technology. MCS says batteries were the third most popular technology type to be installed in homes by its certified contractor base.
Of the 4,700 certified batteries registered with MCS, 4,400 were installed in 2023, it adds.
With the energy price cap on average domestic energy bills now sitting below £2,000 per year and installation costs having increased with inflation, it is unclear whether the high levels of solar PV installations in 2023 will be maintained this year.
Solar Energy UK’s chief communications officer Gareth Simkins says:
“Speculation is always a dangerous game. I think it is reasonable for current deployment rates – around 15,000 a month – to continue. This will not just be retrofits of course – we expect more newbuild homes to carry solar, too.”
Monthly solar installations hit highs
Last year saw monthly installations of rooftop solar PV start to hit the levels seen in 2015, when government subsidies were still available, as shown by the red bars in the figure below.
March 2023 saw 20,073 registered solar PV installations, putting it in the top 10 months seen in the UK. Both 11th and 12th places were claimed by months in 2023 too, with June seeing 18,049 installations and May seeing 17,787 installations.
The rest of the top 10 installation months are dominated by 2011, 2012 and 2015. This was driven largely by subsidy deadlines, with a rush seen ahead of cuts leading to record-high installation periods.

In 2012, the FiT subsidy for solar was cut in half, reducing from 43.3p per kilowatt hour (kWh) to just 21p per kWh. This cut returns from solar electricity from around 7% to 4%, according to the Guardian.
In doing so it almost doubled the payback period for households, with some seeing their £10,000-12,000 solar panels only being in credit after 18 years rather than 10, the Guardian reported at the time.
This change followed then-climate change minister Greg Barker launching a consultation into the subsidies in an effort to avoid the industry falling victim to “boom and bust“.
Following the change, installations fell by nearly 90%, according to Department of Energy and Climate Change figures reported in the Guardian.
Installations dropped from 26,941 in March 2012 to 5,522 in April 2012, according to MCS figures, although there was a further surge later that year.
Throughout 2013, installations remained relatively subdued, growing through 2014 before peaking again in 2015. Installations hit 25,614 in December 2015, but this came ahead of further FiT reduction in February 2016, which sent “shockwaves” through the sector and saw installations drop dramatically
The FiT came to an end in 2019, with the solar export guarantee brought in 2020, which sets a minimum price for electricity exported to the grid.
Following the resulting lull in installations, domestic solar PV has once again been growing. The difference this time is that there is no underlying subsidy driving growth, with rising energy bills and longer-term falls in technology costs making the technology increasingly appealing.
Speaking to Carbon Brief, Solar Energy UK’s Simkins says:
“Oddly enough, it shows the success of FiTs in creating a market for solar in the first place, with the industry now standing entirely on its own two feet without government support.”
Installation costs rise
The inflationary impacts of the Covid-19 pandemic and the subsequent energy crisis led to an increase in solar technology costs in 2023.
Consequently, installation costs have risen over recent years, according to MCS. Across every month in 2023, average installation costs sat above £10,000 – the only time in more than a decade that they have reached that level, as shown in the figure below.
This has been impacted by the scale of the installations to a certain extent, with the installation cost per kilowatt (kW) seeing a more limited increase. Across 2022, the average cost of installing solar per kW was £1,804 and in 2023 this rose to £2,020.
Moreover, in some months, solar was actually cheaper per kilowatt (kW) in 2023 than in 2022, MCS data shows.
It is also worth noting that the increase in the cost of solar installations has not been as dramatic as the increase in energy bills over the past couple of years.
The energy crisis drove up domestic energy bills from late 2021, as supply chain squeezes driven in part by the Russian invasion of Ukraine sent gas prices to record highs.
As a result, the default tariff price cap for consumers jumped from £1,277 per year in the six months to March 2022, to £1,971 over that summer, and then to £3,549 over the winter of 2022.
It then surged again to £4,279 over the first quarter of 2023, before it began to fall (the energy price guarantee came into force in October 2022, superseding the rate of the price cap, and limiting domestic energy bills to £2,500 initially).
The surge in domestic energy prices highlighted the exposure of the British energy system to fluctuations in international gas markets. In doing so, it is likely it helped drive uptake of domestic solar – as shown in the figure below – as households looked to cushion themselves from potential future surges.

Speaking to Carbon Brief, solar wholesaler Midsummer’s commercial director Jamie Vaux says installation costs are now coming down.
The high installation costs and long installation lead times in 2022, were driven by demand exceeding supply, he says. With new installers entering the market and mortgage rates and inflation hitting consumer spending, this has started to ease, he adds.
Average installation prices per kW peaked at £2,111 in April 2023, before slowly falling throughout the year.
Vaux explains:
“Essentially, those who had the funds available when the energy crisis hit have already had their installations, and while many still want solar, the rate stopped climbing so steeply and the curve flattened at the same time as more installers were there to meet the demand. It has become more competitive at the installation level, and installation costs have (gradually) fallen as a result.”
There is also currently a glut of solar modules, which could help prices continue to fall and stimulate further update of solar, according to Vaux.
There is currently “a year’s worth of modules already sitting in EU warehouses, and devaluing daily”, Vaux adds, meaning top-tier modules can be bought for a fraction of prices seen in 2022.
Solar Scotland
The area with the overall highest share of households with solar PV installations since the start of MCS data in 2009 is Stirling in Scotland, where 16.7% of households have solar PV (6,994 households).
Perhaps surprisingly, given their poorer insolation rates relative to other parts of the UK, Scottish local authorities appear four times in the top 10, as shown in the figure below.
Scotland’s housing policy means it is mandatory for solar to be fitted on all new build properties, helping to boost installation rates.

In terms of installations completed during 2023, the Isle of Anglesey came out on top, with 1,083 systems added, amounting to 3.5% of households.
The top 10 for last year is dominated by Welsh and Scottish local authorities, with just one English local authority making it into the list – South Cambridgeshire in ninth place.
There are five Scottish local authorities (Dumfries and Galloway, East Lothian, Perth, Moray and Kinross and Midlothian) and four Welsh local authorities (Isle of Anglesey, Ceredigion, Powys and Pembrokeshire).
The 10 local authority areas with the lowest percentage of solar PV installations since 2009 are all in London, with Kensington and Chelsea coming out on top with just 0.4% (or 297) of households having registered solar PV installed, according to MCS.
It is worth noting that due to the density of the households in London and other major cities, they are over-represented in the lowest percentage list for solar installations.
For example, Wandsworth – which comes out as having the tenth lowest rate of just 1.1% of households having solar PV – only has 1,496 installations.
Meanwhile, Torridge in Devon – which has the eighth highest rate of installations in the UK at 12.8% – has 3,899 solar PV installations. While this is more than double the number is Wandsworth, the much larger difference in percentage terms highlights the impact of population size in each local authority area.
The same is broadly true of 2023. While the area last year with the lowest installation rate was Derry City and Strabane, with just 73 installations (0.1% of households), the bottom ten is still dominated by London boroughs, which made up eight of the list.
Detached properties are the most common when it comes to solar PV installations, with 50,8193 of the MCS registered solar PV installations since 2009 (35.2%) having been fitted on detached properties, versus 447,415 on semi-detached, 288,886 on terraced, 187,131 on flats and apartments and 10,100 on other properties.
This means detached properties – which tend to be larger, with more roof area – are over-represented in terms of their share of solar installations, as shown in the figure below.


The post Analysis: Surge in heat pumps and solar drives record for UK homes in 2023 appeared first on Carbon Brief.
Analysis: Surge in heat pumps and solar drives record for UK homes in 2023

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
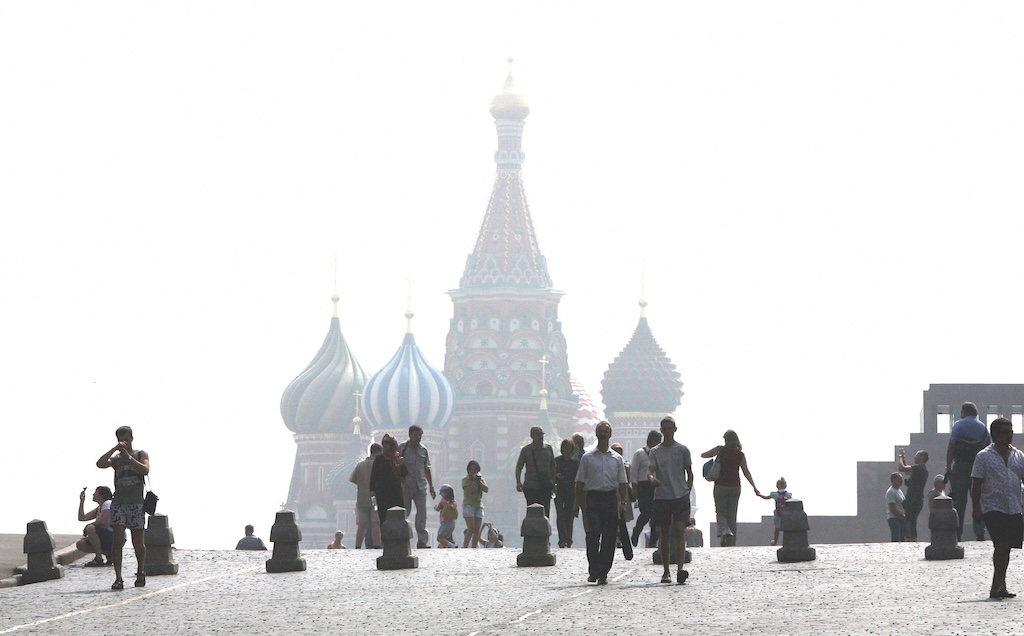
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
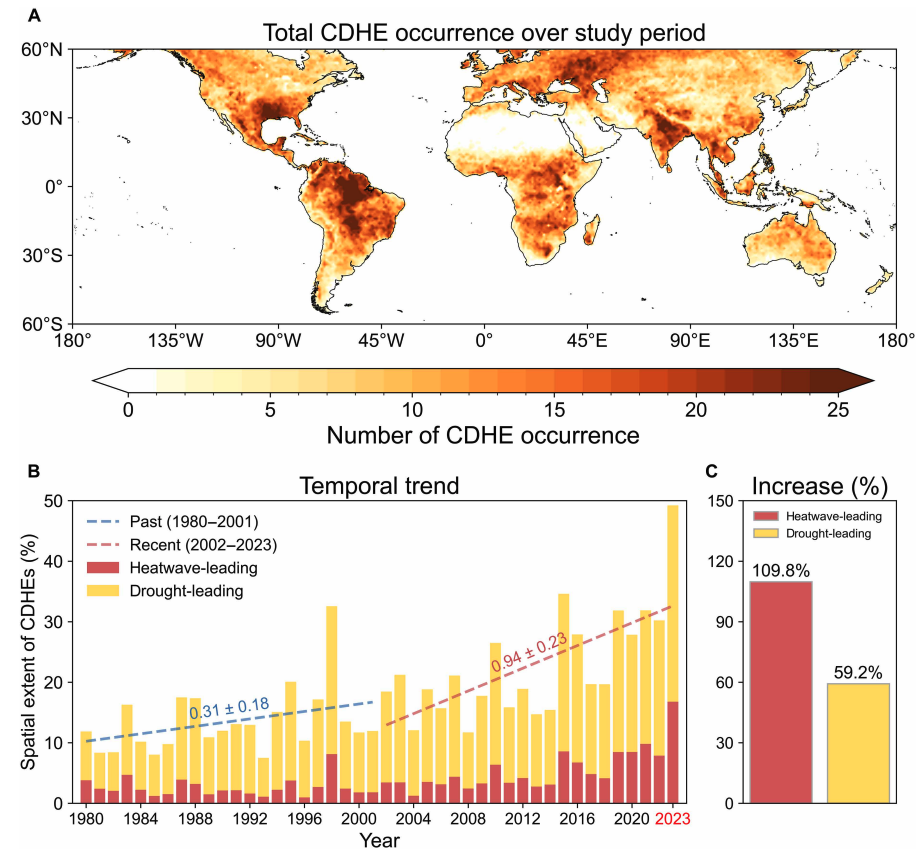
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to