

A boom in Chinese solar power construction drove another record-breaking year of renewables growth in 2023, according to the International Energy Agency (IEA).
Carbon Brief analysis of figures in the IEA’s Renewables 2023 report show that the world is now on track to build enough solar, wind and other renewables over the next five years to power the equivalent of the US and Canada.
Rapid growth has also pushed the IEA to once again significantly upgrade its renewables forecast, adding an extra 728 gigawatts (GW) of capacity to a five-year estimate it made just a year ago. This is more than the electricity capacity of Germany and India combined.
The agency attributes this growth to plummeting costs of solar power and favourable policy regimes, particularly in China. New solar and onshore wind now provide cheaper electricity than new fossil fuel power plants almost everywhere, it says, as well as being cheaper than most existing fossil fuel assets.
Despite such accelerated expansion, the world is not currently on track to achieve the COP28 target of tripling renewables capacity by 2030, according to the IEA.
However, it proposes various measures to further increase deployment, including more finance for developing countries.
‘Step change’
Last year was a “step change for renewable power growth” as the world built an extra 507GW of renewable capacity, primarily solar and wind power, according to the IEA.
This was a 49% increase on the previous year’s construction. It marked the 22nd year in a row that renewable capacity addition reached record levels.
Over the six-year period 2023-2028, an additional 3,684GW of renewables is expected to come online under the IEA’s “main” forecast. This is double the current total of renewable capacity installed globally.
In 2023, solar power both at utility-scale and on rooftops amounted to three-quarters of capacity additions, primarily due to growth in China. Over the next five years, 73% of the 3,174GW of new capacity will be solar, again driven largely by China. (See: China leads.)
By Carbon Brief’s calculations, this 2024-2028 period is on track to see an extra 4,963 terawatt-hours (TWh) of electricity generation from renewable sources.
This amounts to one-sixth of the world’s electricity output in 2022. As the chart below shows, this is equivalent to covering the entire electricity demand of the US and Canada with newly-built renewables.

By 2028, the IEA forecasts that renewables will account for 42% of global electricity generation, with wind and solar power making up 25%. Despite showing no growth across this period, hydropower is still expected to be the largest single source of renewable power.
Taken together, the agency says renewables will overtake coal power as the largest source of power in “early 2025”. (A year ago, the agency said renewables would become the world’s largest electricity source within three years.)
One major driver of this growth is the plummeting cost of renewables, especially solar photovoltaics (PV). Spot prices for solar modules declined by almost 50% in 2023 compared to the previous year, according to the IEA.
Last year, 96% of newly installed utility-scale solar and onshore wind capacity generated cheaper electricity than new coal and gas plants, according to the IEA.
Moreover, three-quarters of new wind and solar power plants provided cheaper power than even existing fossil-fuel facilities.
The other key driver is the strong policy support that renewables enjoy in “more than 130 countries”, the IEA says. It notes that “policies remain key for attracting investment and enabling deployment”, with roughly 87% of the utility-scale renewable growth between 2023 and 2028 “expected to be stimulated by policy schemes”.
At the same time, the report highlights the impact of the “new macroeconomic environment” on the renewables sector, with inflation and high interest rates raising costs. Offshore wind has been hardest hit, with the IEA’s forecast for its growth outside China dropping by 15%.
The report also examines renewable heat consumption and the use of biofuels. Both are set to grow considerably in the coming years, but the IEA says neither are currently on track for the trajectories seen in its net-zero scenario, which aligns with the Paris Agreement.
Record revision
As a result of this growth, the IEA has again significantly raised its forecast for renewables capacity expansion, by a record amount.
It now sees an additional 728GW being built in the 2023-2027 period compared to its forecast from 2022 – a 33% increase. This is notable considering that, last year, the agency described a five-year 424GW adjustment as its “largest ever upward revision”.
The chart below shows the 120GW divergence between actual renewables growth in 2023 – some 507GW – and the forecast for that year of 387GW, made by the IEA in 2022.

The IEA has a long history of making relatively conservative predictions for renewable growth that are subsequently outstripped by reality, due to a combination of more favourable policy conditions and faster-than-expected cost reductions.
Forecasts from previous IEA renewables reports issued in 2020 and 2021 showed annual renewable growth rates remaining fairly stable at around 200GW and 300GW per year for the following five years, respectively.
However, these forecasts have not been included in the chart above as, for the first time, the agency has converted all of its solar power values to direct current, resulting in slightly different GW values. This means previous forecasts are not directly comparable, although the 2022 forecast figures have been converted for this purpose.
China leads
A key conclusion from the IEA’s new report is the global dominance of China in deploying solar and other renewables, which is set to increase in the coming years.
In the period 2005-2010, China built 39% of the world’s new renewable energy capacity. This increased to 47% in the 2017-2022 period and the IEA expects it to rise to 59% between 2023 and 2028. This can be seen in the chart below.
By 2028, the agency estimates that nearly half of China’s electricity will be generated by renewables. According to Ember, as of 2022 only around 30% of China’s electricity was from renewables.
During this period, the nation is set to deploy four times more renewables than the EU and five times more than the US.

This growth is being driven by the nation’s success in solar power manufacture and installation, according to the IEA. In “almost all provinces”, generation costs for new utility-scale solar and onshore wind are now lower than for coal, which is generally used as the benchmark for electricity prices, the agency says.
The IEA attributes this progress to policy measures, including power market reforms, green certificate systems and province-level financial support to support rooftop solar installation. It also points to a “supply glut” that has helped solar module costs “plummet drastically”.
As China accounts for 90% of the upwards revision in the IEA’s forecast out to 2028, it notes that the nation’s solar achievements actually “hide slower progress in other countries”.
There have been a number of significant supportive policy changes in other countries and regions, however.
The US and the EU are expected to see renewable installation rates double across 2023-2028, compared to the previous six-year period – in both cases due primarily to solar expansion. The IEA attributes this to the US Inflation Reduction Act and supportive national policies – such as government renewable power auctions – across European nations.
The report also highlights the success of supportive policies in India and Brazil. It notes that while renewables are set to expand rapidly in sub-Saharan Africa – particularly South Africa – the region “still underperforms considering its resource potential and electrification needs”.
Tripling renewables
At COP28, nearly every government in the world agreed to a target of tripling global renewables capacity by 2030. This would bring the total to 11,000GW, which is in line with the IEA’s own net-zero scenario.
As it stands, the new report concludes that under the IEA’s “main case” forecast, shown in yellow in the chart below, renewable capacity would increase to 7,339GW in 2028.
Following that trajectory, capacity would reach around 9,000GW in 2030 – roughly an increase to 2.5 times current levels.
This forecast is based on existing policies and takes into account “country-specific challenges that hamper faster renewable energy expansion”, the IEA says.
By contrast, the IEA’s “accelerated case” involves governments “overcom[ing] these challenges and implement[ing] existing policies more quickly”.
In this scenario, shown in red below, renewables growth is around 21% higher. Capacity increases to 8,130GW in 2028, putting the world on track for the tripling by 2030 target.

The IEA lists a handful of broad measures that governments could take to achieve an “accelerated” trajectory.
These include: improved policy responses to the “new macroeconomic environment” such as higher inflation; more investment in grid infrastructure; and dealing with “cumbersome administrative barriers and permitting procedures and social acceptance issues”.
The IEA notes that “the lack of affordable financing remains the most important challenge to renewable project development in most EMDEs [emerging markets and developing economies], especially in countries where renewable policy uncertainties also increase project risk premiums”.
It emphasises the need to boost financing for EMDEs to overcome this barrier. Last year, renewable growth was concentrated in just 10 nations and tripling renewables requires “a much faster deployment rate…in numerous other nations”, the IEA says.


The post Analysis: World will add enough renewables in five years to power US and Canada appeared first on Carbon Brief.
Analysis: World will add enough renewables in five years to power US and Canada

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
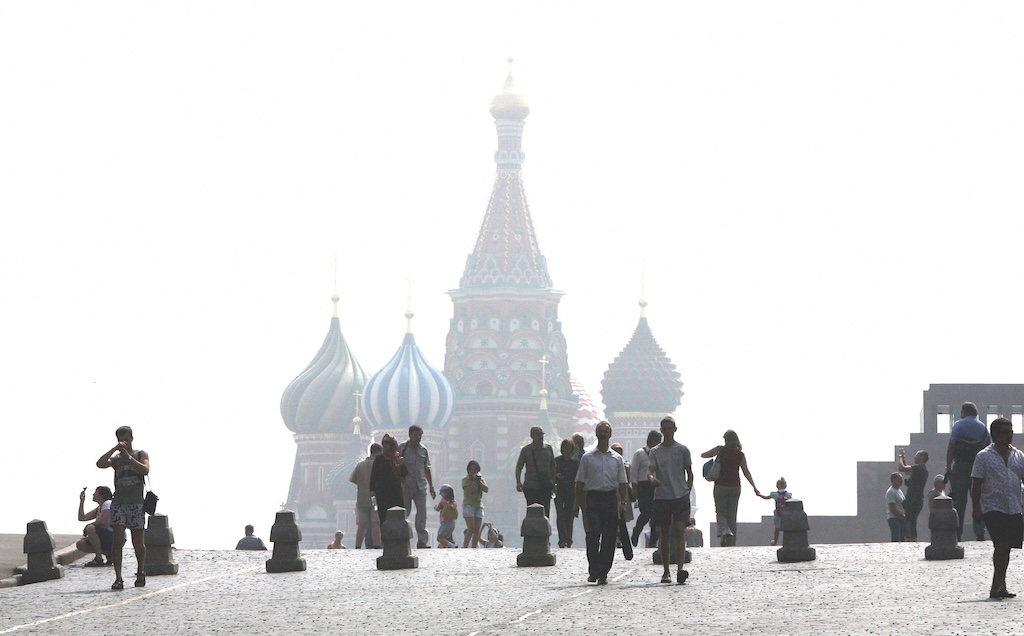
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
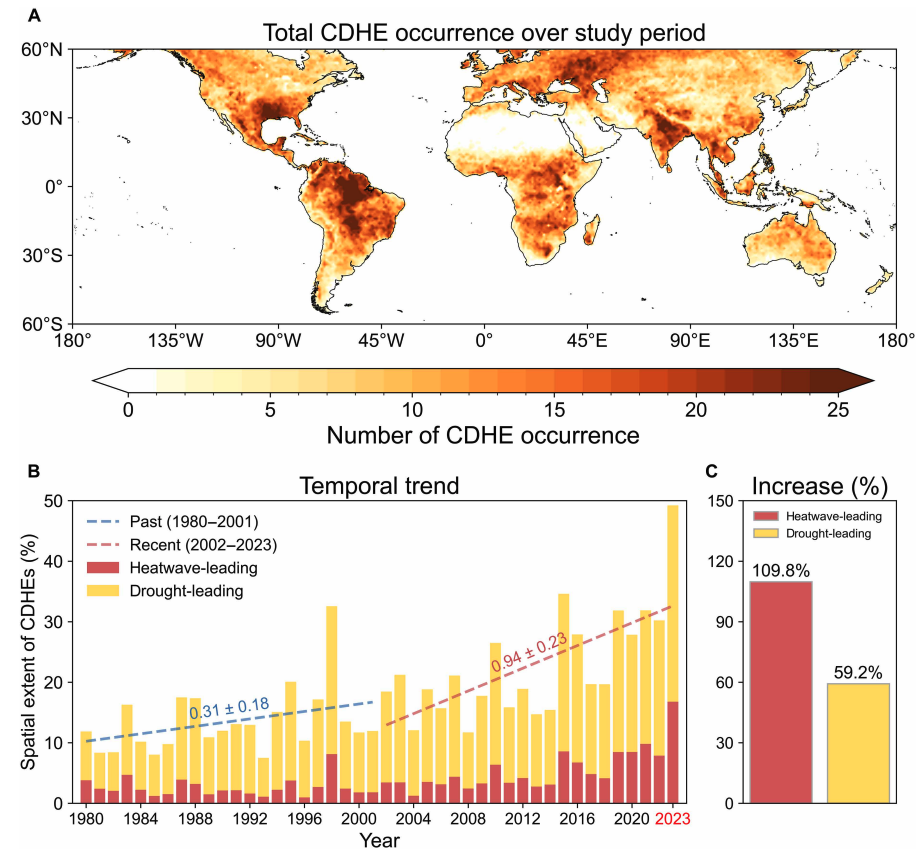
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: Bloomberg reported on increases in diesel prices in Europe and the US, speculating that rising fuel costs could be “a risk for president Donald Trump”. US gas producers are “poised to benefit from the big disruption in global supply”, according to CNBC. Indian government sources told the Economic Times that Russia is prepared to “fulfil India’s energy demands”. China Daily quoted experts who said “China’s energy security remains fundamentally unshaken”, thanks to “emergency stockpiles and a wide array of import channels”.
‘ESSENTIAL’ RENEWABLES: Energy analysts said governments should cut their fossil-fuel reliance by investing in renewables, “rather than just seeking non-Gulf oil and gas suppliers”, reported Climate Home News. This message was echoed by UK business secretary Peter Kyle, who said “doubling down on renewables” was “essential” amid “regional instability”, according to the Daily Telegraph.
China’s climate plan
PEAK COAL?: China has set out its next “five-year plan” at the annual “two sessions” meeting of the National People’s Congress, including its climate strategy out to 2030, according to the Hong Kong-based South China Morning Post. The plan called for China to cut its carbon emissions per unit of gross domestic product (GDP) by 17% from 2026 to 2030, which “may allow for continued increase in emissions given the rate of GDP growth”, reported Reuters. The newswire added that the plan also had targets to reach peak coal in the next five years and replace 30m tonnes per year of coal with renewables.
ACTIVE YET PRUDENT: Bloomberg described the new plan as “cautious”, stating that it “frustrat[es] hopes for tighter policy that would drive the nation to peak carbon emissions well before president Xi Jinping’s 2030 deadline”. Carbon Brief has just published an in-depth analysis of the plan. China Daily reported that the strategy “highlights measures to promote the climate targets of peaking carbon dioxide emissions before 2030”, which China said it would work towards “actively yet prudently”.
Around the world
- EU RULES: The European Commission has proposed new “made in Europe” rule