


The UK government recently announced a massive £22 billion investment into carbon capture and storage (CCS) projects over the next 25 years. The technology aims to capture carbon emissions from power plants and heavy industries before storing them underground. While this move aligns with the UK’s ambition to achieve net zero by 2050, experts question whether this strategy will lock the country into fossil fuel dependence for decades.
Prime Minister Keir Starmer recently reaffirmed the government’s commitment to CCS.
“Today’s announcement will give industry the certainty it needs – committing to 25 years of funding in this groundbreaking technology – to help deliver jobs, kick-start growth, and repair this country once and for all.”
UK’s Reduced Vision for Carbon Capture and Storage
The government initially planned to fund eight CCS projects to help the UK reach its net zero emissions target by 2050. However, due to escalating supply chain costs, only three projects will now receive government support. According to The Department for Energy Security & Net Zero (DESNZ), the first two of the Track 1 project are:
- BP Plc and Equinor ASA will lead the East Coast Cluster in eastern England, focusing on carbon capture projects.
- HyNet will serve industrial sites in western England and Wales, advancing carbon capture initiatives in those regions.

Source: DESNZ
While this investment shows the government’s dedication to decarbonization, the reduced scale of the program highlights the financial challenges that CCS technology faces.
- According to Bloomberg, these three projects will remove around 3 million tons of CO₂ per year—far below the 20 to 30 million tons that were initially projected.
(DESNZ’s) five criteria for cluster selection – Track-1 of its Carbon Capture, Usage and Storage program.
- RECENT: The “Northern Lights” Shines: Shell, Equinor, and TotalEnergies JV Powers the Norway CCS Project
A Risky Bet on Unproven Technology
The UK bets on carbon capture and storage as a viable means to achieve its net zero target. For tough industries like cement, steel, and fertilizer, CCS is a potential lifesaver. By capturing emissions and storing CO₂ underground, this process prevents greenhouse gases from entering the atmosphere.
On the downside, CCS remains largely untested on the scale needed to make a significant impact. Furthermore, The National Audit Office (NAO) has expressed concerns about the UK’s heavy reliance on CCS and has warned stating,
“Slower progress with getting Track-1 up and running means that DESNZ will struggle to achieve its 2030 ambitions for carbon capture.”
They have highlighted rising costs and the technology’s inconsistent track record. For instance, over the last 20 years, many CCS projects in the UK have failed to meet expectations, which raises uncertainty about whether this large investment will pay off.
Notably, the biggest challenges include the huge cost of CCS and massive supply chain expenses which have forced the government to step back on its original ambitions. Previously industries also tried to integrate CCS with natural gas and coal power plants but the idea was not feasible.
Additionally, the projects are already facing delays. In this case, investment decisions for the first two clusters were initially set for last year but have been postponed multiple times. The NAO has warned that continued delays could force the government to renegotiate contracts with suppliers, which could further increase costs.
The Climate Change Committee’s (CCC’s) assessment of how much CCUS will need to be deployed under its Balanced Net Zero pathway, 2020 to 2050

Source: DESNZ
Locking in Fossil Fuel Dependence
One of the most significant criticisms of the government’s CCS plan is that it could lock the UK into a reliance on natural gas for generations. Natural gas, primarily composed of methane, is a potent greenhouse gas with significant emissions occurring upstream during extraction, processing, and transportation. Relying on natural gas for energy—even with carbon capture—means the UK will continue importing it, exposing the country to volatile global energy markets.
On the contrary, renewables do not have these risks. Wind and solar power are generated locally and are not subject to fluctuating international prices. By investing heavily in CCS, the government may unintentionally slow down the transition to a fully renewable energy grid. After scrutinizing all these factors, industrialists opine that the UK should prioritize renewable energy development and energy efficiency measures to meet its climate goals more sustainably.
The Global Outlook
Currently, only two commercial-scale coal plants globally operate with CCS—Boundary Dam in Canada and Petra Nova in the US. Both projects have struggled with consistent underperformance, technical setbacks, and cost overruns. Moreover, these plants represent a tiny fraction of global power generation, raising doubts about the feasibility of scaling up CCS in time to meet the UK’s net-zero goals by 2050.
Additionally, media agency, The Conversation reported that 80% of captured CO₂ is currently used to enhance oil recovery, which further contradicts the aim of reducing fossil fuel use. Critics argue that the focus on CCS may deter investment in renewable energy projects like wind and solar, which are both cheaper and proven to be effective.
The UK is not alone in grappling with these issues. Worldwide, carbon capture projects have encountered similar problems with high costs and technical challenges.
In summary, while carbon capture technology is essential for cutting emissions from heavy industries, its limitations and rising costs pose significant challenges. The UK’s current CCS projects are already struggling with delays and escalating expenses, leading to doubts about their long-term viability. As the country pushes forward with its net-zero goals, finding a balance between ambition and practicality will be crucial in determining the success of CCS.
Balancing CCS While Embracing Renewables
Despite these challenges, the UK government remains optimistic about CCS’s role in reducing the nation’s carbon footprint. Along with £8 billion in private investment, the government’s funding will help create 4,000 jobs and build the necessary infrastructure to support carbon capture.
 Source: IEA
In conclusion, the UK government will have to carefully balance its investment in CCS with the development of renewable energy to ensure it stays on track for net-zero emissions by 2050. While carbon capture offers a way to reduce emissions from industries that are hard to decarbonize, it is not the perfect solution. The government must continue to invest in wind, solar, and other renewable technologies to create a truly sustainable energy future.
Even though the government’s £22 billion bet on CCS may seem a promising decarbonization effort, only time will tell whether it leads to a truly sustainable energy future or simply prolongs the use of fossil fuels.
Data sources:
- UK to Spend £22 Billion on Carbon Capture Sites as Costs Rise – BNN Bloomberg
- The UK’s £22 billion bet on carbon capture will lock in fossil fuels for decades (theconversation.com)
________________________________________________________________________
The post UK’s £22 Billion Carbon Capture and Storage Plan: A Bold Step or A Fossil Fuel Trap? appeared first on Carbon Credits.

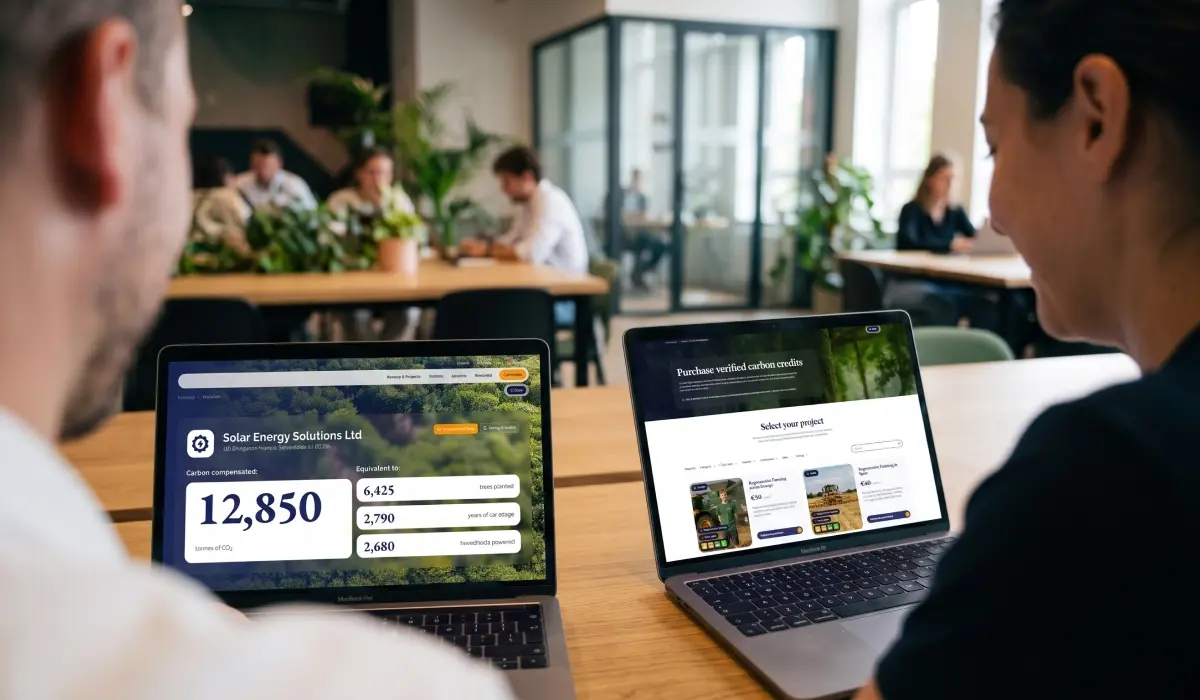
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits