

The rate at which atmospheric CO2 is increasing is now outpacing the pathways set out by the Intergovernmental Panel on Climate Change (IPCC) that limit global warming to 1.5C.
This is what the latest data shows from the Mauna Loa observatory in Hawaii, where measurements of CO2 levels in the atmosphere have been collected for more than 60 years.
In 2024, the rise in atmospheric CO2 was one of the fastest on record.
Emissions of CO2 and other greenhouse gases from human activity have so far caused human-caused global warming to reach about 1.3C above pre-industrial levels.
If warming is to be limited to 1.5C, as set out in the Paris Agreement, the build-up of CO2 and other greenhouse gases in the atmosphere will need to slow to a halt and then go into reverse.
And, yet, the rise in atmospheric CO2 concentrations is still showing no signs of slowing.
Pathways to 1.5C
The third working group report of the IPCC’s sixth assessment report (AR6), published in 2022, presented a set of seven “illustrative pathways” that highlight how different mitigation choices across major economic sectors translate into future greenhouse gas emissions and global temperatures.
In the three most-ambitious pathways, global warming has a 50% chance of either staying below 1.5C, or overshooting it by only 0.1C (for up to several decades) before then returning to below 1.5C:
- Shifting pathways (IMP-SP): Illustrates mitigation in the context of a broader shift towards sustainable development, including by reducing inequality and with a phase-out of fossil fuels.
- Low demand (IMP-LD): Illustrates a strong emphasis on energy-demand reductions, and with a phase-out of fossil fuels.
- Renewables (IMP-Ren): Illustrates a future with a heavy reliance on renewable energy.
As the table below shows, the build-up of atmospheric CO2 in these three scenarios slows from the 2010s average of 2.41 parts per million per year (ppm/year) to 1.33-1.79ppm/year in the 2020s.
It then slows still further and goes into reverse either in the 2030s or 2040s – in other words, the level of CO2 in the atmosphere actually begins to fall.
| Decade | Projected average CO2 rise (ppm/year) in scenarios limiting global warming to1.5C | ||
| C1-IMP-LD | C1-IMP-REN | C1-IMP-SP | |
| 2020s | 1.33 | 1.75 | 1.79 |
| 2030s | -0.14 | 0.13 | 0.57 |
| 2040s | -0.53 | -0.46 | -0.7 |
| 2050s | -0.65 | -0.61 | -0.41 |
Large CO2 rise in 2024
Yet, not only are atmospheric CO2 concentrations still rising, the rate of rise is accelerating.
The build-up of CO2 in the atmosphere has been monitored at the Mauna Loa observatory in Hawaii since 1958.
As illustrated by the iconic Keeling Curve below, the increase has been accelerating over the decades (blue line) due to ongoing emissions of CO2 from burning fossil fuels and changing land use.
So while the curve needs to rapidly bend in the other direction to hold warming to 1.5C (light red line), the rate of rising CO2 marches onwards and upwards.
chart

Monthly CO2 concentrations at Mauna Loa from observations up to 2024 (blue) and the IPCC C1-IMP-SP scenario consistent with limiting global warming to 1.5C (light red). Also shown is the Met Office forecast for 2025 (red).
The table below sets out decadal averages of the annual rise in CO2 concentrations at Mauna Loa. The first half of the 2020s has seen an average CO2 rise of 2.58ppm/year, which is 44-94% higher than it needs to be to track the IPCC 1.5C-compatible scenarios.
| Decade | Observed average CO2 rise (ppm/year) |
|---|---|
| 1960s | 0.86 |
| 1970s | 1.22 |
| 1980s | 1.58 |
| 1990s | 1.55 |
| 2000s | 1.91 |
| 2010s | 2.41 |
| 2020s (2020-2024) | 2.58 |
In fact, the annual rise of 3.58ppm/year between 2023 and 2024 at Mauna Loa was the fastest on record.
The global average, which has been monitored by satellite since 2003, also showed a large rise last year – and, at 2.9ppm/year, this was the second largest on record after 2015-16.
(While the rise at Mauna Loa mirrors the global rise over long periods, in the short term it can also be affected by localised effects, such as fires upwind or in the same hemisphere, before the CO2 disperses more evenly across the globe.)
Global CO2 emissions were also at a record high in 2024, but a further key factor was that natural land carbon “sinks” were substantially weaker, allowing more of the emitted CO2 to remain in the atmosphere.
At least some of this weakening of land carbon sinks was associated with the El Niño conditions in the first part of the year. El Niño events shift weather patterns around the globe, leading to hotter, drier conditions in many parts of the tropics. This means that vegetation grows less well and more carbon is released from decay in soils and from wildfires, leading to land ecosystems removing less carbon from the atmosphere than usual.
With the El Niño now subsided and conditions shifting more towards the opposite pattern of La Niña, natural land carbon sinks can be expected to recover again, at least to some extent.
As a result, in our Met Office forecast of the CO2 rise at Mauna Loa, we predict a slower rate of rise between 2024 and 2025 than between 2023 and 2024. The projected increase is 2.26ppm (with an uncertainty range of ±0.56ppm) – slightly slower than it would have been without the effects of La Niña.
However, even this is still too fast to stay on track with the IPCC 1.5C-compatible scenarios. This is highlighted in the chart below, which shows the annual change in CO2 levels at Mauna Loa since 1995 (blue lines) and how our forecast for 2025 (red point) exceeds a pathway consistent with 1.5C (grey plume).

Faster rise than expected
The specific reasons for the very large increase in CO2 in 2024 are not yet completely clear, although weaker land carbon sinks appear to be implicated.
We had forecast the 2023-24 CO2 rise at Mauna Loa to be 2.84ppm (±0.54) – faster than the average of the previous decade due to the El Niño. We had also highlighted the possibility that it could be the fastest annual rise on record.
However, the actual CO2 rise of 3.58ppm was even faster than expected. This was above the upper limit of our uncertainty range, which should include the forecast value 95% of the time.
Although carbon emissions from fossil fuel burning and deforestation were also at a record high in 2024, this does not fully explain the shortfall in our forecast.
Our forecast method uses the global emissions from the previous year as one of the inputs. The emissions in 2024 were estimated to have been 11.3bn tonnes of carbon (GtC), slightly higher than the 2023 value of 11.1GtC used in our forecast.
This 0.2GtC difference is equivalent to about 0.09ppm of CO2 in the atmosphere. So, even if we had used the larger value in our forecast, the observed rise would still have been beyond our uncertainty range.
Therefore, the origin of the discrepancy must be related to natural carbon sinks, which must have been even weaker than the expected weakening that occurred as a result of the 2023-24 El Niño.
Weaker land carbon sinks
Scientists had already established that land carbon sinks were exceptionally weak in 2023, with very high temperatures worldwide playing a part in this.
2024 was then even hotter than 2023 – and indeed was the first calendar year where warming exceeded 1.5C above pre-industrial levels. It can be expected that the climatic conditions this warmer year once again led to weaker global land carbon sink.
Both North and South America saw high temperatures and exceptionally severe fires in 2024, including in regions not normally affected by El Niño such as Canada, and extending beyond the season of El Niño influence.
Global fire emissions were estimated as 1.6-2.2GtC over January-September 2024, 11-32% above the 2014-23 average for the same months.
Moreover, fire emissions in the northern hemisphere were 0.5-0.6 GtC per year, which was 26-44% above the average of 2014-23. Since Mauno Loa is in the northern hemisphere, this may explain why the local rise there was even larger than the global average.
A portion of these fire emissions may already be accounted for in the above estimate of land-use emissions, but it is not possible to quantify this. Nevertheless, widespread fire activity likely contributed to the large rise in atmospheric CO2 concentrations in 2024. Further analysis is needed to quantify the size of this contribution.
Climate change itself may have played a role in enhancing fire emissions. For example, human-caused warming made the “unprecedented” wildfires that spread across Brazil’s Pantanal wetlands in June 2024 between four and five times more likely.
Although land carbon sinks are generally increasing as a result of rising CO2, Earth system model projections have long indicated that ongoing global warming would reduce this effect, leading to a greater proportion of human-caused emissions remaining in the atmosphere.
Calculations suggest that this has already been occurring in recent years, so a key question is whether the last two years have seen an acceleration. If natural carbon sinks weaken more than already expected, this would further increase the difficulty of slowing the rise in atmospheric CO2 concentrations.
Alternatively, there are a number of historical years for which our CO2 forecast procedure gives almost as large departures between predictions and outcomes as for 2024. For example, 2003 saw a large rise at Mauna Loa despite not being an El Niño year, due to large fires in Siberia. It will therefore be important to see whether there is a higher-than-expected rise in CO2 in 2025, or whether the large exceedance in 2024 is a temporary phenomenon.
With global warming ongoing, extremely high temperatures will continue to occur more frequently and severely, so events such as those seen in 2023 and 2024 could play an ever more important role in the global carbon cycle.
The contribution of fires attributed to climate change is consistent with model simulations which suggest that global fire activity will already be weakening land carbon sinks. Further monitoring of the global carbon cycle will help to reveal whether this is indeed the case.


The post Met Office: Atmospheric CO2 rise now exceeding IPCC 1.5C pathways appeared first on Carbon Brief.
Met Office: Atmospheric CO2 rise now exceeding IPCC 1.5C pathways

China’s carbon dioxide (CO2) emissions fell by 3.1% in the third quarter of 2026, as the Hormuz crisis continued to hit oil demand and coal use also dropped.
This guest post is by:
Lauri Myllyvirta, lead analyst at the Centre for Research on Energy and Clean Air
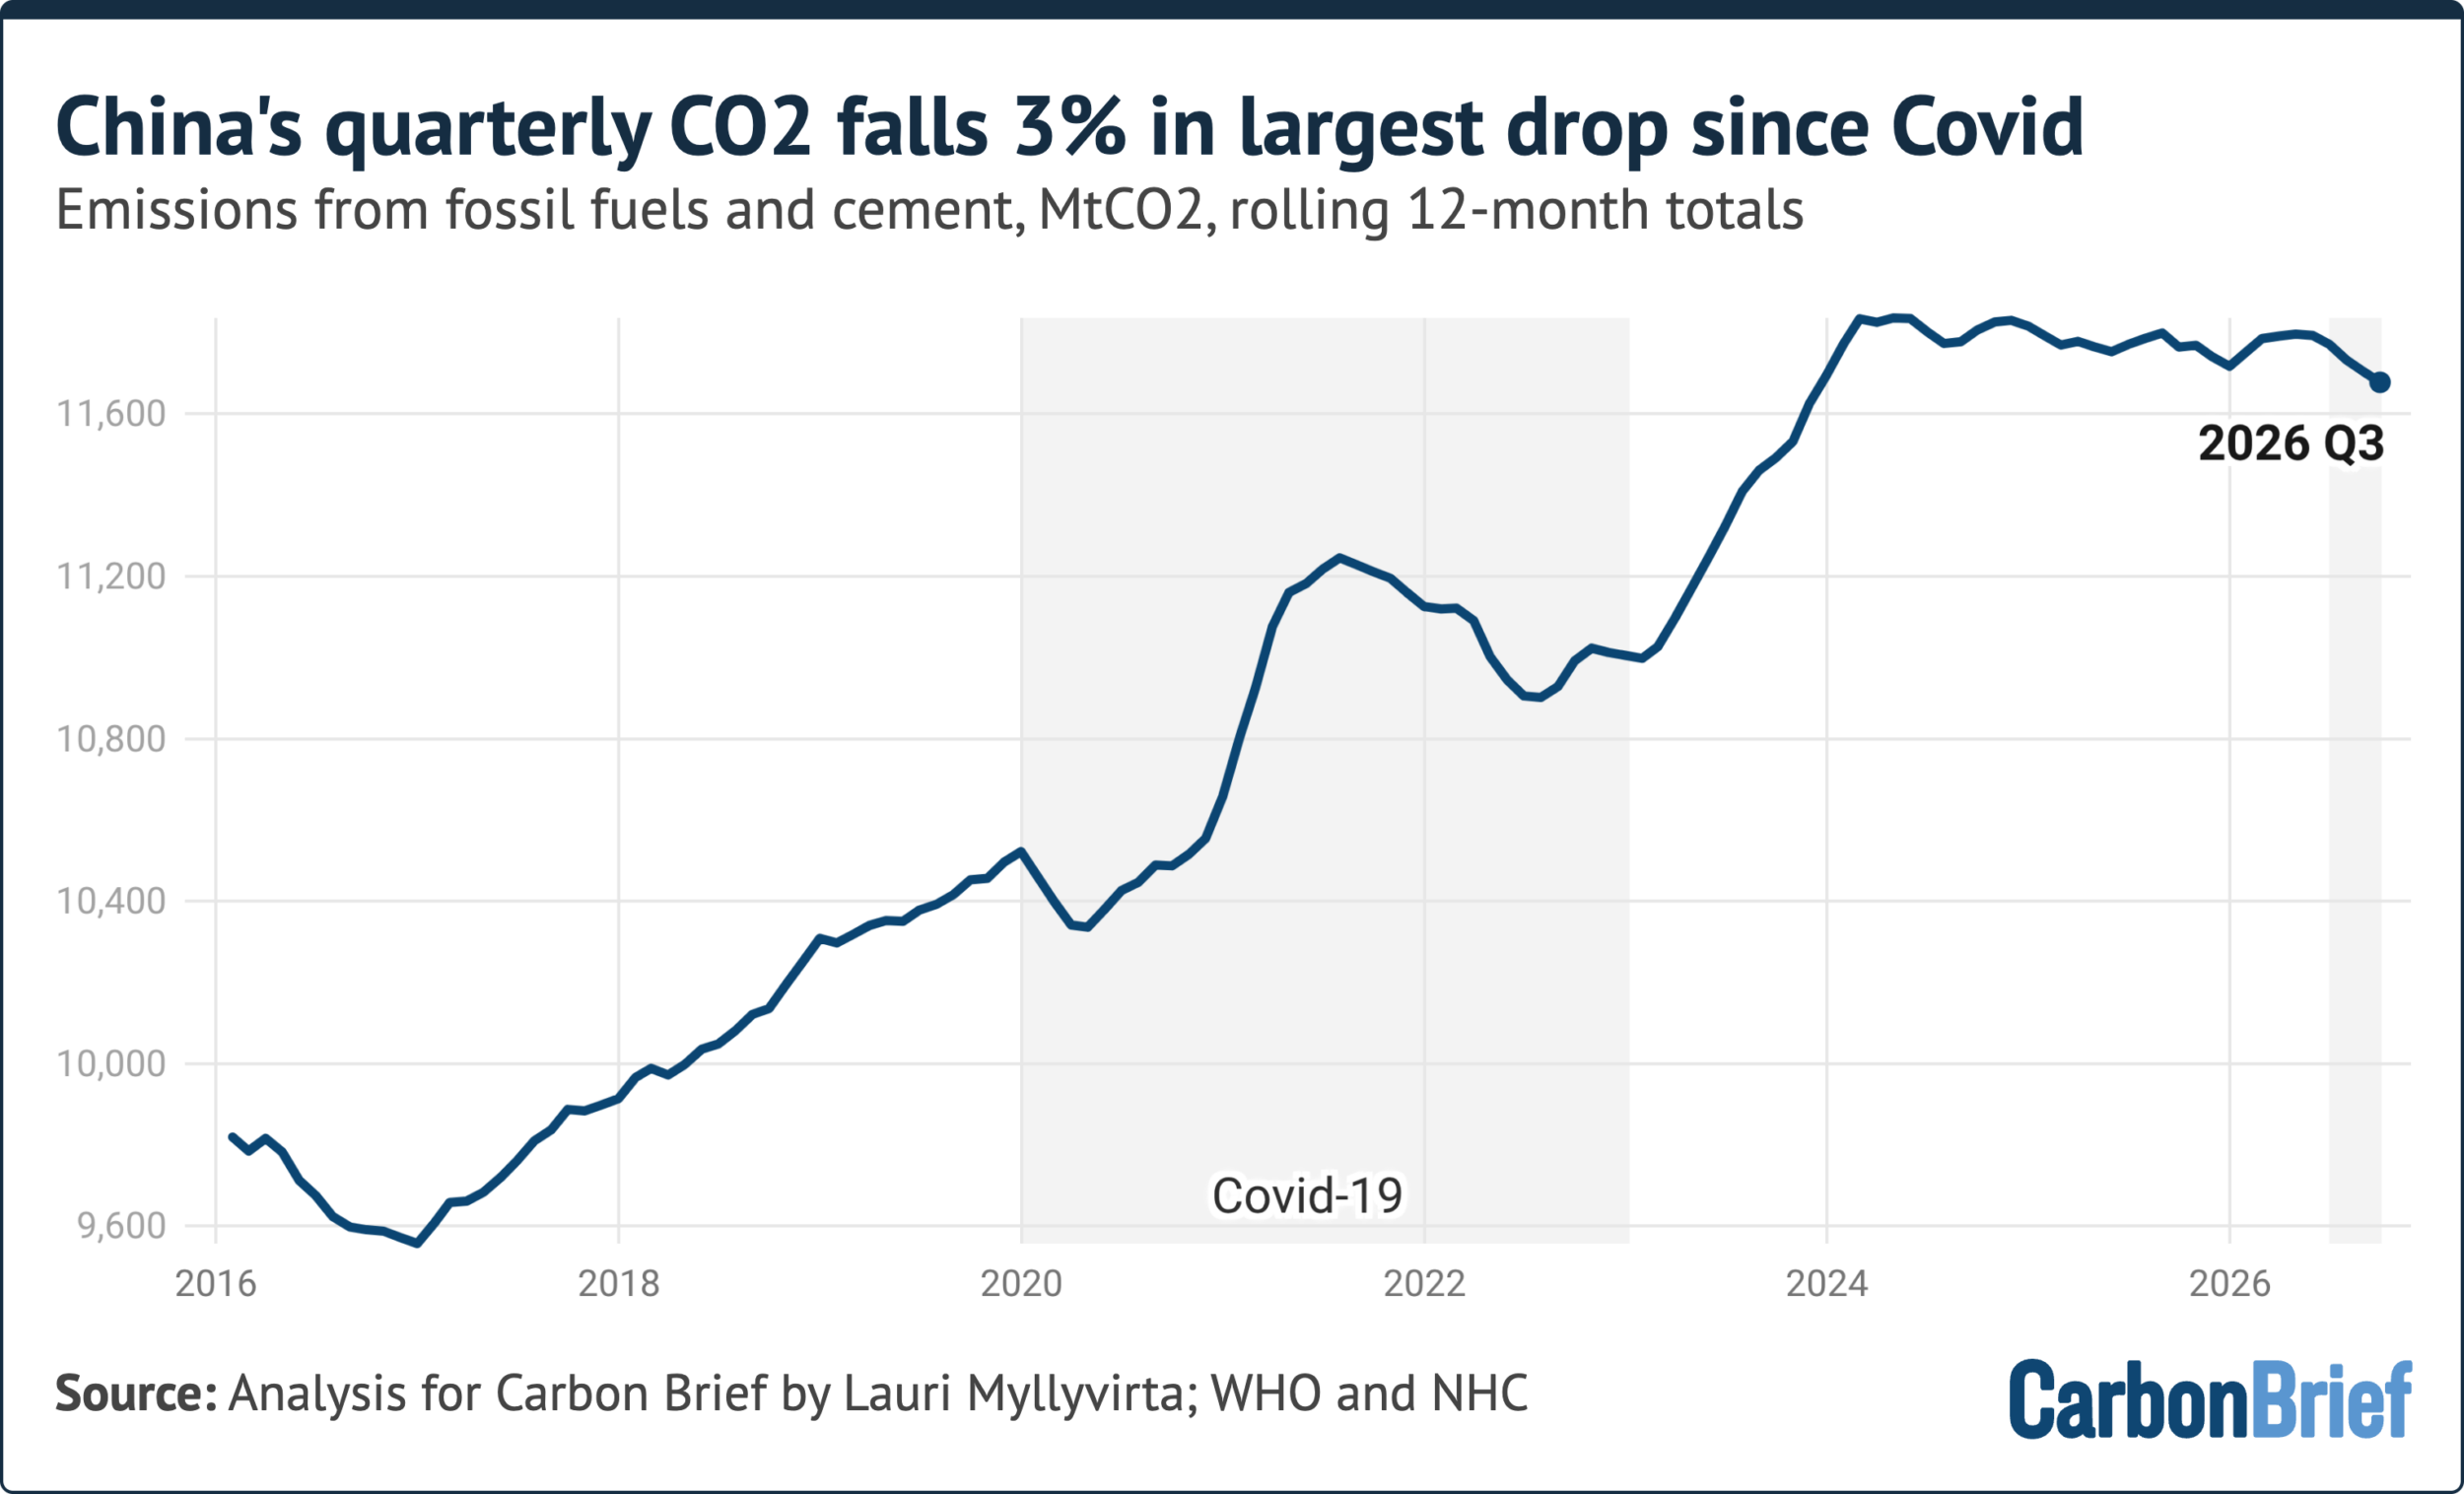
This was the largest quarterly reduction since the 2022 Covid lockdowns and means that China’s CO2 emissions have now fallen by an estimated 0.5% in the year to date.
The new analysis for Carbon Brief, based on official figures and commercial data, shows that coal use fell by 3% year-on-year in the third quarter of 2026, while oil was down 4%.
The main drivers were a fall in power-sector coal consumption, a continued sharp reduction in transport oil consumption and slowing growth in the coal-to-chemical industry.
The sharp decline in China’s CO2 emissions extends a “flat or falling” trend that began in March 2024 and has now lasted more than two years, as shown in the figure below.
The outlook for China’s CO2 emissions depends on the balance between rising energy demand, clean-energy growth and the government response to a GDP slowdown.
Decline drivers
Key drivers of the fall in CO2 in the third quarter of 2026 included a 3.3% drop in coal-power generation, after demand growth slowed and the amount of “wasted” wind and solar fell.
Power generation from solar, wind and nuclear increased by 110 terawatt hours (TWh) year-on-year, more than twice as much as the growth in total electricity demand. This added clean-power generation equal to Germany’s total power output in the same time period.
The fall in coal-power output and CO2 emissions came despite the fact that China continues to build new coal-power capacity at near-record rates. This means that average running hours for coal plants are falling even faster than total generation, eroding their profits.
Meanwhile, transport oil consumption continued to fall sharply, down 9% year-on-year in the third quarter of 2026. Electric vehicles (EVs) continued to gain market share, hitting a record 67% of passenger car sales and 50% of heavy trucks in September.
The amount of electricity used by EVs grew by 53%, much faster than the number of EVs on the road, showing increased usage of the existing fleet in preference to fuelled vehicles.
Elsewhere, growth in the coal-to-chemical industry continued to slow down in the third quarter of 2026. The sector has been a key source of emissions growth, but high coal prices have weakened profitability and higher output prices hurt downstream demand.
Finally, CO2 emissions from cement and steel production continued to fall in the third quarter, as the contraction in construction volumes accelerated.
Outlook for emissions
Energy consumption growth has been falling after a period of exceptionally high growth during Covid, while clean-power growth has been robust.
This makes it likely that the growth in clean-power generation will exceed total energy demand growth this year, maintaining the structural fall in fossil-fuel use.
Looking ahead, this balance also relies on progress in removing barriers to new solar and wind power being added to the grid, which result in some clean electricity being “wasted”.
The recent slowdown in energy demand growth is partly – but not fully – explained by exceptionally mild weather in the third quarter.
Another key factor is weaker GDP growth. Since reported GDP growth remains within target, however, there is reduced pressure for further stimulus policies.
The focus of the economic stimulus announced to date is “six networks”, which includes the power grid and the transportation network.
These networks are highly relevant for energy and emissions – and they are already covered by policies that emphasise “green” and zero-carbon solutions.
The post Analysis: China’s quarterly CO2 falls 3% in largest drop since Covid appeared first on Carbon Brief.
Analysis: China’s quarterly CO2 falls 3% in largest drop since Covid
Climate Change
Coles, Woolworths grilled as beef buyers receive fail grade on new deforestation scorecard
MELBOURNE, Friday 6 November 2026 — As Coles holds its Annual General Meeting today, Greenpeace Australia Pacific has branded the major supermarkets with a fail grade on their commitment to source deforestation-free beef, with an updated scorecard revealing none of the major beef buyers are following through on forest sustainability commitments.
It comes after Woolworths’s AGM last week where the board copped a grilling by environmentalists and shareholders over its failed sustainability commitments. Both Coles and Woolworths committed to eliminating deforestation in their supply chains by the end of 2025, but a year past the deadline, neither company could guarantee that their beef was not sourced from deforested pastures.
From outside the Coles AGM, Adele Chasson, Nature Policy Lead at Greenpeace Australia Pacific, said:
“This is a report card Coles and Woolworths should be ashamed to take home. While all major beef buyers had promised to take deforestation off the shelves, none of them followed through. Shareholders and the public demanded answers from Woolworths last week and from Coles today, and we will continue to hold their feet to the fire on their promises.
“Beef is the leading cause of deforestation in Australia, and Coles and Woolworths keep putting off action while koalas continue losing their homes. Aussies must be able to get their groceries without having to worry if their dinner is contributing to the bulldozing of forests or driving extinction of iconic Australian animals.
“Without strong, rapid implementation plans, these companies continue with business as usual, flying in the face of Australia’s deforestation crisis. Big beef buyers like Coles and Woolworths must stop the bulldozers now, make good on their sustainability promises and play their part in stopping Australian forest destruction.”
The scorecard assesses how eight of Australia’s largest beef buyers stack up against a conversion and deforestation-free target. It charts whether the major supermarkets, Aldi, McDonalds, Hungry Jacks, Teys, Metcash/IGA and JBS are taking proper action to end Australia’s deforestation crisis. They all failed.
-ENDS-
Media contact: Kimberley Bernard on 0407 581 404 or kbernard@greenpeace.org
Coles, Woolworths grilled as beef buyers receive fail grade on new deforestation scorecard