

Companies are increasingly focusing on the emissions associated with their supply chains to reduce overall emissions. Integrating both the supplier’s organizational and product specific emission factors is key to understanding the company’s environmental situation as well as how to drive change.
The Best of Both Worlds: Product and Organizational Data
By integrating product-specific carbon data with broader organizational emissions figures, companies can achieve a granular understanding of their environmental impact. This means organizations should pay attention to detail in the collection and analysis of data for product-specific emissions, starting from raw material extraction up to end-of-life disposal. For example, Volvo, a luxury car manufacturer, has agreed to buy near zero emission steel from H2 Green Steel from their new factory in Sweden starting in 2026. They have also partnered with Norsk Hydro to supply and increase use of near zero aluminum before 2030. This product data is just as important as more holistic emission metrics of the supplier and is vital for painting a complete picture of an organization’s environmental impact.
Organizational data includes not just the direct emissions from company-owned or controlled sources, but also the indirect emissions from the generation of purchased electricity, and, importantly, all other indirect emissions that occur in the company’s value chain, such as those from business travel, transportation, and waste generated in operations. For example, Nestlé, a global food corporation, moved half its shipping operations to use low-carbon fuels made from waste such as cooking oil. This switch will reduce around 200,000 metric tons of CO2 which is equal to 500,000 barrels of crude oil. This type of data gives a bigger picture of the suppliers’ progress to reducing their company-wide carbon footprint.
Integration
The integration process typically employs digital tools and platforms designed to manage and analyze large datasets. This comparison between product and service emission data through these technologies will help make it very easy and, in turn, guide the organization to understand high-impact areas that need immediate attention. This will also allow the data within the supply chain to be combined, hence realizing a full organizational view of the carbon footprint.
Using These Data to Reduce Emissions
By integrating these emission data, companies can improve sustainability among suppliers. An organization that thoroughly understands what the carbon footprint of its products and services is empowers it to engage suppliers meaningfully in conversation about sustainability and is ready to actually make change.
This includes setting clear, measurable sustainability targets and using the integrated data for tracking progress towards them. The data allows organizations to easily determine the areas on which their reduction efforts need to be focused—process improvements, material substitutions, or other sustainability initiatives.
DitchCarbon’s API can find both product and organization data when queried. This integrated data is used for supplier engagement and emission reduction, which reduces your Scope 3 emissions.
Learn how DitchCarbon can provide both product and organizational data on your suppliers!



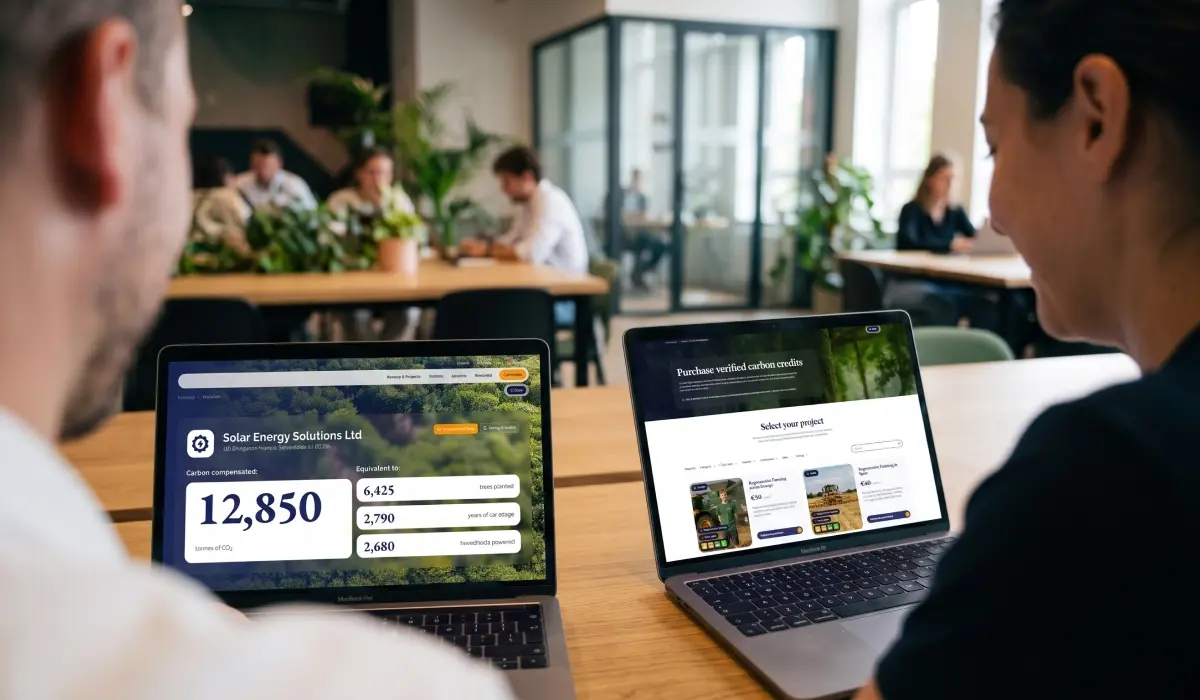
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits