

China’s carbon dioxide (CO2) emissions fell by 1% in the second quarter of 2024 in the first quarterly fall since the country re-opened from its “zero-Covid” lockdowns in December 2022.
The new analysis for Carbon Brief, based on official figures and commercial data, shows China remains on track for a decline in annual emissions this year.
This annual outlook depends on electricity demand growth easing in the second half of the year, as expected in projections from sector group the China Electricity Council.
However, if the latest trends in energy demand and supply continue – in particular, if demand growth continues to exceed pre-Covid trends – then emissions would stay flat in 2024 overall.
Other key findings from the analysis include:
- China’s energy demand grew by 4.2% year-on-year in the second quarter of 2024. This is slower than the growth seen in 2023 and in the first quarter of this year, but is still much higher than the pre-Covid trend.
- CO2 emissions from energy use and cement production fell by 1% in the second quarter. When combined with a sharp 6.5% increase in January-February and a monthly decline in March, there was a 1.3% rise in CO2 emissions across the first half of the year, compared with the same period in 2023.
- Electricity generation from wind and solar grew by 171 terawatt hours (TWh) in the first half of the year, more than the total power output of the UK in the same period of 2023.
- China’s carbon intensity – its emissions per unit of GDP – only improved by 5.5%, well short of the 7% needed to meet the country’s intensity target for 2025.
- This was despite a one-off boost from China’s hydropower fleet recovering from drought.
- Compared with a year earlier, the increase in the number of electric vehicles (EVs) on China’s roads cut demand for transport fuels by approximately 4%.
- Manufacturing solar panels, EVs and batteries was only responsible for 1.6% of China’s electricity consumption and 2.9% of its emissions in the first half of 2024.
A slew of recent policy developments, summarised below, hint at a renewed focus in Beijing on the country’s energy and climate targets.
Yet the precise timing and height of China’s CO2 emissions peak, as well as the pace of subsequent reductions, remain key uncertainties for global climate action.
First post-Covid fall in CO2
China’s CO2 emissions fell by 1% in the second quarter of 2024, the first quarterly fall since the country re-opened from zero-Covid, as shown in the figure below.
Within the overall total, power sector emissions fell by 3%, cement production fell by 7% and oil consumption by 3%.
The reduction in CO2 emissions was driven by the surge in clean energy additions, which is driving fossil fuel power into reverse. (See: Clean energy additions on track to top 2023 record.)
However, rapid energy demand growth in sectors such as coal-to-chemicals diluted the impact of changes in the electricity sector. (See: Rapid energy demand growth.)
Clean energy additions on track to top 2023 record
The additions of new clean power capacity in China have continued to boom this year.
China added 102 gigawatts (GW) of new solar and 26GW of wind in the first half of 2024, as shown in the figure below. Solar additions were up 31% and wind additions up 12% compared with the first half of last year, so China is on track to beat last year’s record installations.

As a result of the strong capacity growth – and despite poor wind conditions – solar and wind covered 52% of electricity demand growth in the first half of 2024 and 71% since March. (The fall in wind speeds can be seen from NASA MERRA-2 data averaged for all of China.)
Indeed, the increase in power generation from solar and wind reported by the National Energy Administration in the first half of the year, at 171 terawatt hours (TWh), exceeded the UK’s total electricity supply of 160TWh in the first half of 2023.
Rapid demand growth in January–February, at 11%, had outpaced even the clean energy additions. But combined with a rebound in hydropower generation, the increase in non-fossil electricity supply exceeded power demand growth in the March to June period.
These shifts are shown in the figure below, illustrating how clean power expansion started to exceed electricity demand growth in recent months, pushing coal and gas power into reverse.

After stopping the publication of capacity utilisation data by technology in May, the National Energy Administration released data in July on power generation by technology for renewable sources – solar, wind, hydro and biomass.
The NEA’s data shows renewable electricity generation covering 35% of demand in the first half of 2024 and growing 22% year-on-year. This is much higher than the previously-published National Bureau of Statistics numbers – which under-report wind and particularly solar power generation – but is closely aligned with estimates previously published by Carbon Brief.
In terms of other clean energy technologies, the production of electric vehicles, batteries and solar cells – the so-called “new-three” due to their recently acquired economic significance – continued to grow strongly in the first half of the year, at 34%, 18% and 37%, respectively.
This growth in production indicates strong demand from China and overseas. The growth of solar cell production halted in June, however.
Rapid energy demand growth
While clean technologies continue to surge in China, energy consumption has also continued to grow at a fast rate relative to GDP. This indicates that the energy-intensive growth pattern that China followed during zero-Covid is continuing.
In the second quarter of 2024, total energy consumption increased by 4.2%, while GDP grew by 4.7%, marking an energy intensity gain of only 0.5%. This energy demand growth is much faster than the pre-Covid trend.
China’s target is an annual improvement of 2.9%, a rate that was exceeded consistently until Covid-era economic policies shifted the country’s growth pattern. Economic growth during and after zero-Covid has been reliant on energy-intensive manufacturing industries.
The main structural drivers of recent energy consumption growth were the coal-to-chemicals industry, and industrial demand for power and gas.
The coal-to-chemicals industry produces petrochemical products from coal instead of oil, supporting China’s energy security goals but at a great cost to climate goals, as the coal-based production processes have far higher carbon footprints.
China’s energy security drive and falling coal prices relative to oil prices have driven a boom in this industry. When coal supply was tight in 2022–23, the government was controlling coal use by the chemical industry to increase supply to power plants. As the coal supply situation has eased in 2024, this has enabled coal-to-chemicals plants to increase production, with coal consumption in the chemical industry growing 21% in the first half of the year.
Gas consumption increased 8.7% in the first half of the year, with industrial and residential gas consumption rising strongly, even as power generation from gas fell. Residential demand was driven up by extreme cold in the winter, however, rather than by structural factors.
On the flipside, the demand for oil products continued to fall, with a 3% drop in the second quarter that accelerated in the summer.
There are multiple factors driving the reduction: the shift to electric vehicles is contributing to the drop, with the share of EVs in cumulative vehicle sales over the past 10 years – an indicator of the mix of vehicles on the road – reaching 11.5% in June, up from 7.7% a year ago. This means that the increase in EVs cut the demand for transport fuels by approximately 4%.
The ongoing contraction in construction volumes, which is apparent in the fall in cement production, also affects oil demand, as the construction sector is a major source of demand for oil products for freight and machinery.
Another key driver is weak demand for oil as a petrochemical feedstock, which the rapidly increasing coal-to-chemicals production attempts to displace with the use of coal, albeit at a cost of increased CO2 emissions.
The contraction in construction volumes, caused by a slowdown in real estate that began in 2021, is weighing on the demand for cement and steel. Besides the direct effect of less real estate construction, local government revenues are dragged down by a fall in land sales, affecting their ability to spend on infrastructure construction.
These changes in demand for energy can been seen in the figure below, which shows contributions to the change in China’s CO2 emissions in the second quarter of this year.

While CO2 emissions did fall in the second quarter, the rate of CO2 intensity improvements fell short of the level needed to meet China’s 2025 carbon intensity commitment.
The country’s goal is to reduce emissions relative to GDP by 18% from 2020 to 2025, with progress until 2023 falling far short of the target.
As reported GDP growth slowed to 4.7% in the second quarter, and CO2 emissions fell by 1%, CO2 intensity improved by 5.5%, short of the 7% annual improvement needed in 2024-25 to get back on track.
Improvements are also easier to achieve this year than they will be in 2025, as the rebound of hydropower from the low availability in 2022–23 helps reduce emissions. This is a one-off tailwind that is not likely to be present in 2025.
One part of the energy-intensive industry that China has been relying on to drive economic growth is the manufacturing of clean energy technologies. In response, some commentators have exaggerated the CO2 impact of Chinese factories making solar panels, EVs and batteries.
In reality, however, the manufacturing of these goods was responsible for 1.6% of China’s electricity consumption and 2.9% of its emissions in the first half of 2024, based on calculations using publicly available data.
The same calculations show that their CO2 emissions and electricity consumption increased by approximately 27% in the same period, contributing a 0.6% increase in China’s total fossil CO2 emissions and 0.4% increase in electricity consumption.
Looking ahead to the rest of this year, energy consumption growth is expected to cool. The China Electricity Council projects electricity demand growth of 5% in the second half of the year, compared with 8.1% in the first half, and the National Energy Administration expects full-year gas demand growth to moderate to 6.5–7.7%, from 8.7% in the first half.
If these projections are accurate, then the continued growth of clean energy consumption would be sufficient to push China’s CO2 emissions into decline this year.
However, the faster-than-expected energy demand growth in the first half of the year dilutes the emission reductions from the country’s record clean energy additions, and adds uncertainty to whether China’s emissions will indeed fall in 2024 compared with 2023.
If the growth rates of energy demand, by fuel and sector, seen in the second quarter of this year continue into the third and fourth quarter, with similar continuity in the growth rates of non-fossil electricity generation, then China’s emissions would stay flat in 2024 overall.
Recent policy developments
Energy consumption growth could also be moderated by a renewed policy focus on energy and climate targets. In May of this year, the State Council, China’s top administrative body, issued an action plan on energy conservation and CO2 emission reductions in 2024–25.
This plan is notable both for the unusual time period, covering the last two years of the five-year plan period, and for its high-level nature – energy conservation would normally fall under the jurisdiction of the energy and environmental regulators, rather than the State Council.
This suggests that the government recognises the shortfall against the 2025 carbon intensity and energy intensity targets. The action plan calls for meeting both of these targets, and lists numerous measures to be undertaken in response.
Yet the plan did not set numerical targets for 2024 that would be consistent with meeting the 2025 targets, which could be seen as taking a hedged approach of pushing for more action but not guaranteeing that sufficient results will be achieved.
Another State Council plan, released in late July, calls for speeding up the creation of a “dual control system” to control total CO2 emissions and emissions intensity. (Historically, China has never set numerical targets for total CO2 emissions, only aiming to limit CO2 intensity.)
According to the July release, the 15th five-year plan will set a binding carbon intensity target in the 2026-30 period, in line with previous five-year plans. For the first time, there will also be a non-binding, “supplementary” target for China’s absolute emissions level in 2030. Then, for each of the following five-year periods, there will be a binding absolute emissions target.
After the shortfall against the 2025 intensity target, the 15th five-year plan period would need to set a demanding intensity target to fulfil China’s 2030 commitments under the Paris Agreement.
The most important political meeting of the year, the “third plenum” of the Central Committee of the Communist Party, took place in July. The readout of the meeting mentioned carbon emissions reduction for the first time, but did not signal a shift to stimulating consumption. This could have driven less emissions-intensive economic growth, reducing reliance on higher-carbon manufacturing or infrastructure expansion.
The key focus of the meeting was promoting “new quality productive forces”, meaning advanced manufacturing and innovation. In practice, this likely implies a continued emphasis on manufacturing, with the potential for the energy-intensive economic growth pattern to continue.
Another indication that carbon emissions are receiving more policy emphasis is that the government appears to have stopped permitting new coal-based steelmaking projects since the beginning of 2024.
Hundreds of coal-based “replacement” projects were permitted in previous years, preparing to replace up to 40% of China’s existing steelmaking capacity with brand-new furnaces.
The shift away from new coal-based capacity is consistent with China’s target of increasing the use of electric arc furnaces – but progress towards that target had been lagging.
On coal-fired power, the government issued a new policy on “low-carbon transformation” of coal plants, aiming to initiate “low-carbon” retrofitting projects of a batch of coal power plants in 2025, with the target of reducing the CO2 emissions of those plants 20% below the average for similar plants in 2023, and another batch in 2027 aiming for emission levels 50% below 2023 average.
Under this transformation plan, emissions reductions at targeted coal plants are supposed to be achieved by “co-firing” coal with either biomass or “green” ammonia derived from renewables-based hydrogen, or by adding carbon capture, utilisation and storage (CCUS).
However, there are no targets for how many coal plants should be retrofitted, or what the incentives will be to do that, which will obviously determine the direct impact of this policy.
The impact could be small as biomass supply is limited, while the costs of ammonia and CCUS are high. For example, the International Energy Agency – among the more optimistic on power generation from biomass – sees its share rising from 2% in 2022 to 4.5% in 2035, if China meets its pledges on energy and climate IEA’s.
Furthermore, much of China’s coal-fired generation is already unprofitable, with almost half of the firms in the sector operating at a loss – even before taking on costly new measures.
The policy does however constitute Beijing’s first attempt at reconciling the recent permitting spree of new coal-fired power plants with its CO2 peaking goal for 2030, and looking for alternatives to early closure or under-utilisation of at least a part of the coal power fleet.
Prospects for a 2023 emissions peak and beyond
China’s emissions fell year-on-year in March and in the second quarter, as expected in my analysis for Carbon Brief last year.
Faster-than-expected growth in coal demand for the chemical industry, however, as well as industrial demand for power and gas, has diluted the emission reductions from the power sector, making the fall in emissions smaller than expected.
Nevertheless, China is likely still on track to begin a structural decline in emissions in 2024, making 2023 the peak year for CO2 emissions.
In order for this projection to bear out in reality, clean energy growth would need to continue and the expected cooling in energy demand growth in the second half of the year would need to materialise, with the new policy focus on energy savings and carbon emissions proving lasting.
The trends that could upset this projection include the economic policy focus on manufacturing, and the expansion of the coal-to-chemicals industry.
The surge in coal use for coal-to-chemicals is also a demonstration that even if power sector emissions begin to fall, as long as China’s climate commitments allow emissions to increase, there is the potential for developments that increase emissions in other sectors.
China has committed to updating its climate targets for 2030 and releasing new targets for 2035 early next year. These targets will be key in cementing the emissions peak and specifying the targeted rate of emission reductions after the peak – both of which have seismic implications for the global emissions trajectory and the level at which temperatures can be stabilised.
About the data
Data for the analysis was compiled from the National Bureau of Statistics of China, National Energy Administration of China, China Electricity Council and China Customs official data releases, and from WIND Information, an industry data provider.
Wind and solar output, and thermal power breakdown by fuel, was calculated by multiplying power generating capacity at the end of each month by monthly utilisation, using data reported by China Electricity Council through Wind Financial Terminal.
Total generation from thermal power and generation from hydropower and nuclear power was taken from National Bureau of Statistics monthly releases.
Monthly utilisation data was not available for biomass, so the annual average of 52% for 2023 was applied. Power sector coal consumption was estimated based on power generation from coal and the average heat rate of coal-fired power plants during each month, to avoid the issue with official coal consumption numbers affecting recent data.
When data was available from multiple sources, different sources were cross-referenced and official sources used when possible, adjusting total consumption to match the consumption growth and changes in the energy mix reported by the National Bureau of Statistics for the first quarter and the first half of the year. The effect of the adjustments is less than 1% for all energy sources, and the conclusion that emissions fell in the second quarter holds both with and without this adjustment.
CO2 emissions estimates are based on National Bureau of Statistics default calorific values of fuels and emissions factors from China’s latest national greenhouse gas emissions inventory, for the year 2018. Cement CO2 emissions factor is based on annual estimates up to 2023.
For oil consumption, apparent consumption is calculated from refinery throughput, with net exports of oil products subtracted.


The post Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19 appeared first on Carbon Brief.
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19

Efe Baysal leads the Türkiye team of global climate advocacy group 350.org.
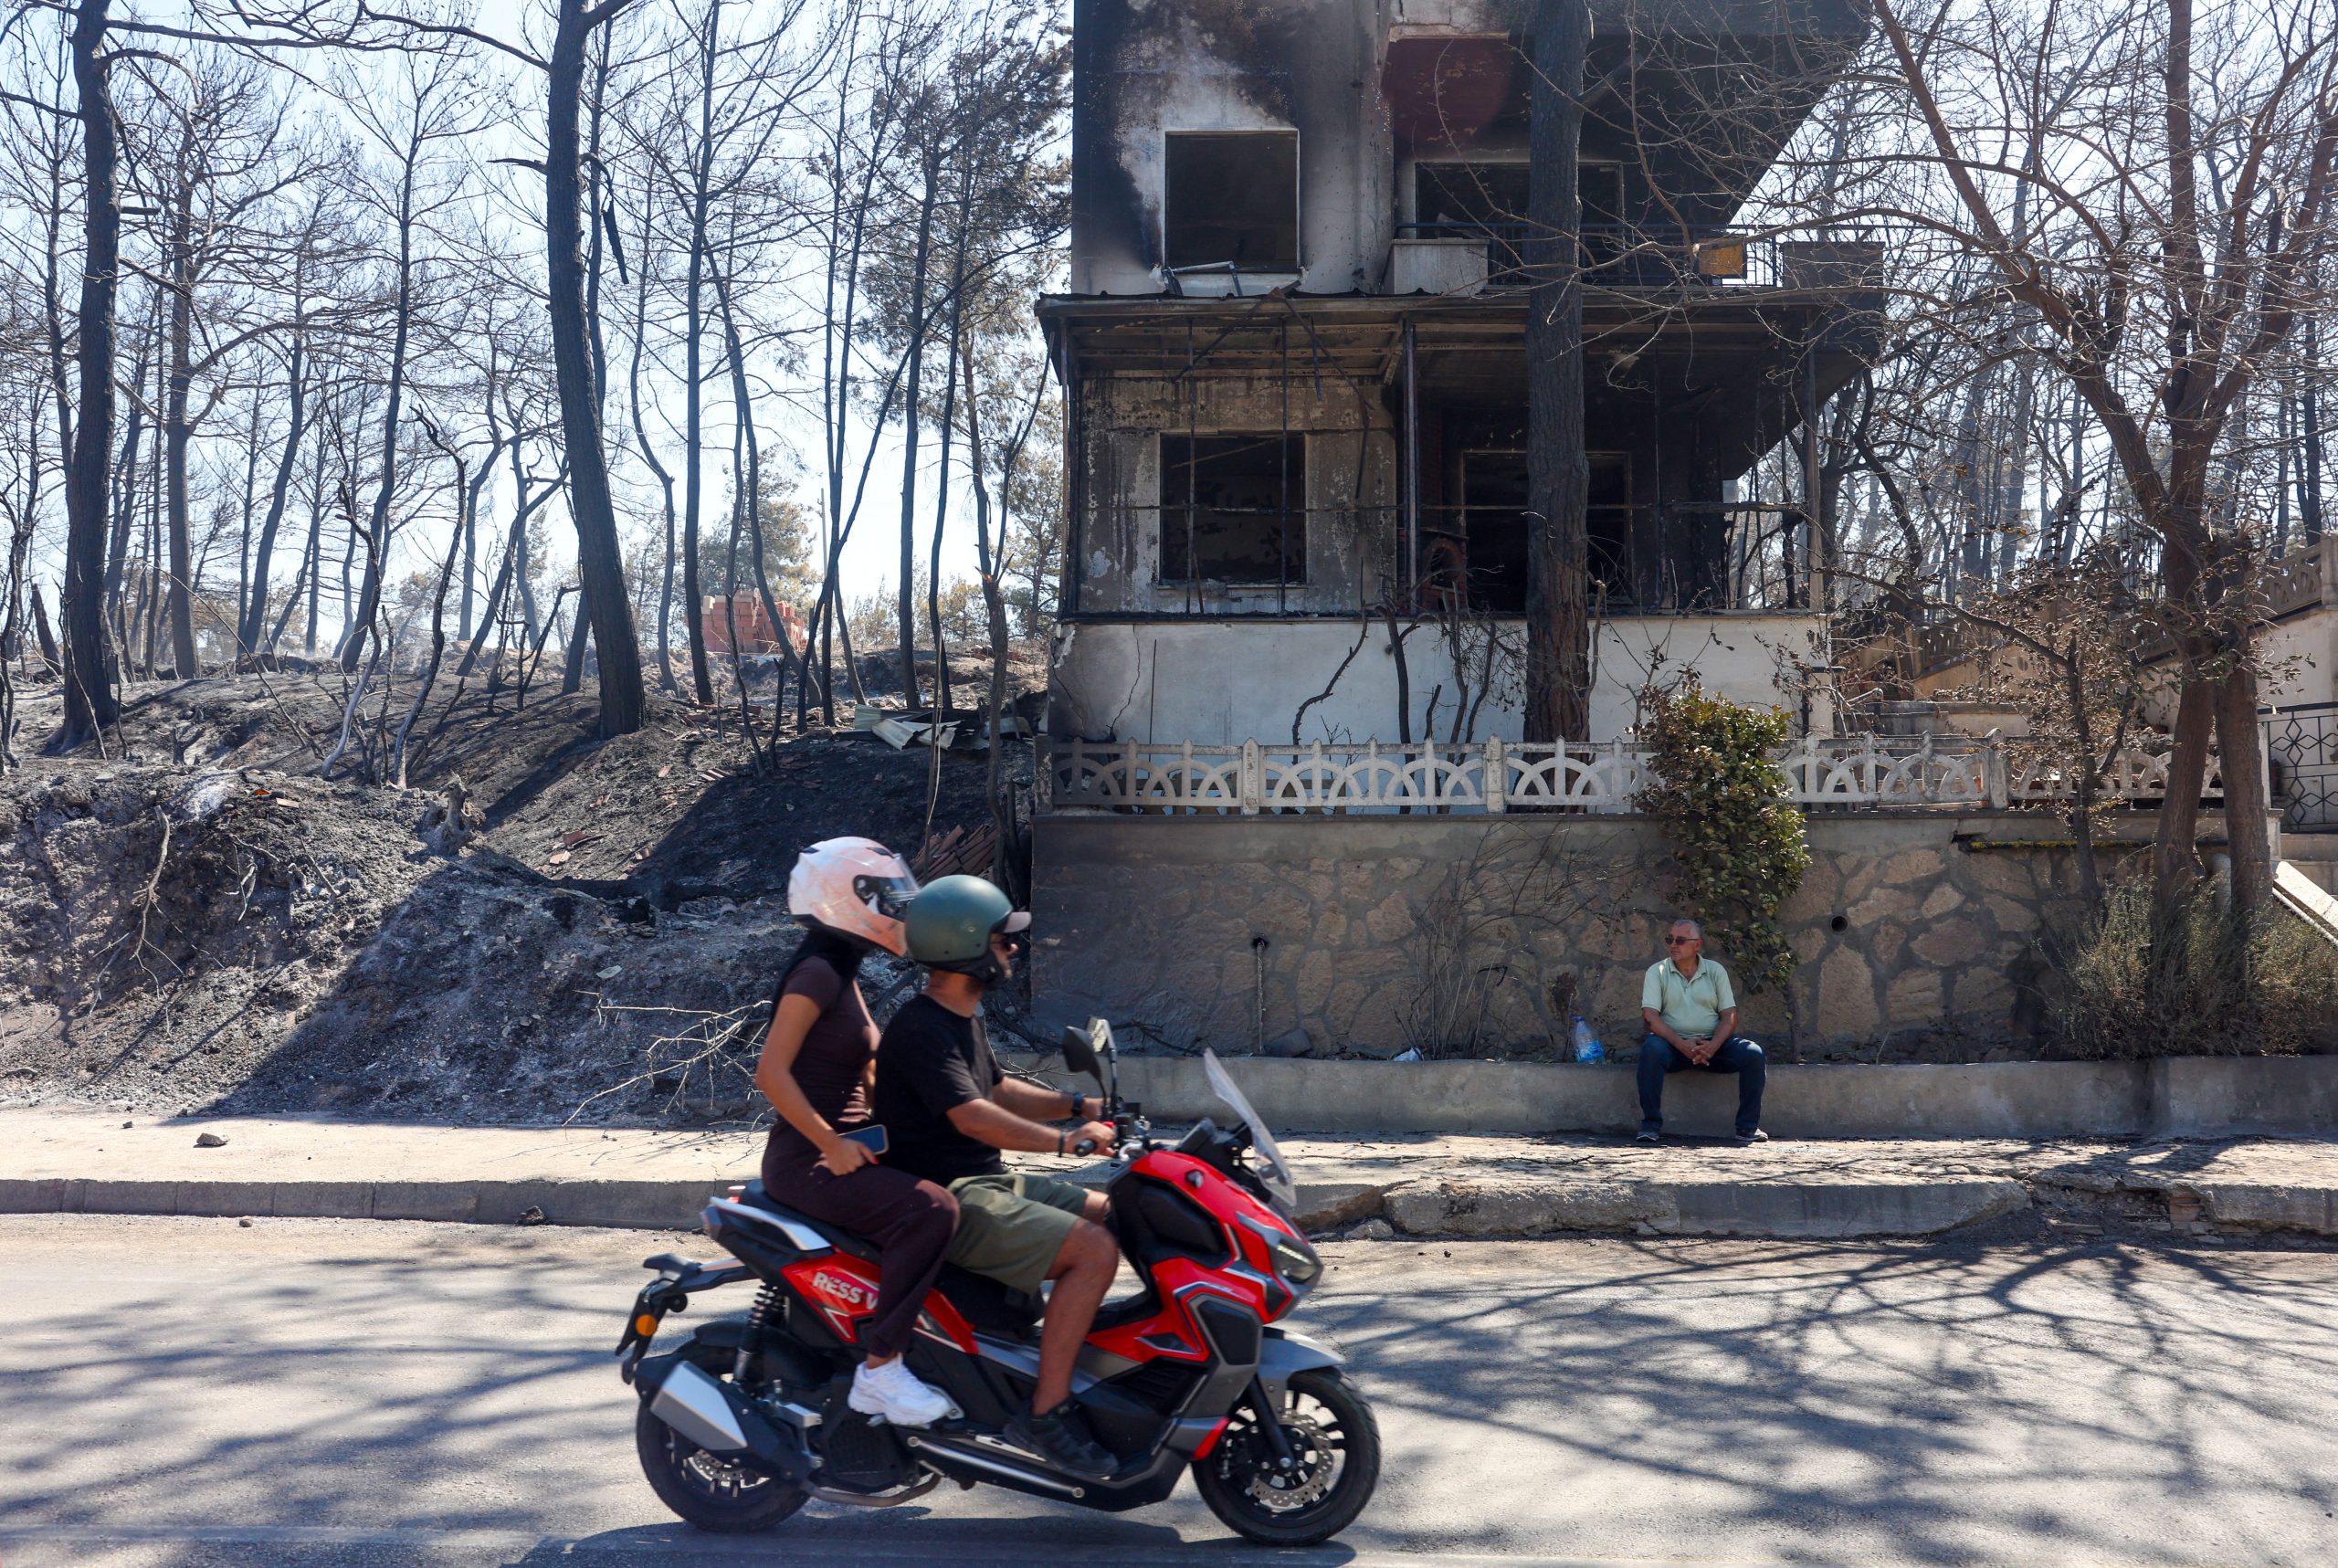
As Türkiye welcomed world leaders in Antalya during the first week of the UN climate summit, few were probably aware that wildfires raged just a few kilometres from the COP31 venue in September, injuring several people and forcing hundreds to flee their homes.
Wildfires are one of the signs of a rapidly heating planet. Prolonged heatwaves and drought create ideal conditions for fires to start and to spread. In the coastal province of Antalya, 8,000 hectares have already been lost to forest fires this year alone.
It is a crucial moment for climate diplomacy. This year we have seen the human cost and mounting economic damage of climate impacts, from Europe’s heatwaves to Nepal’s deadly glacial floods. Scientists warn that the world will breach the 1.5C temperature limit within a few years.
-
Turkish giant sponsoring COP31 cut climate goals then cashed in on oil boom
COP31 sponsors should be screened for “climate integrity”. Yet Koç Holding has become a top partner while its oil refiner runs flat out and its climate targets slip -
Africa wants adaptation finance on COP31 agenda, raising risk of a fight
The African Group wants dedicated space on tripling adaptation finance, the Green Climate Fund and trade, setting up a possible clash -
European nations signal support for fossil fuel roadmap, says COP30 president
André Corrêa do Lago told Climate Home News that it’s up to other nations to decide how the fossil fuel and deforestation roadmaps are used


The stakes have never been higher as the Turkish government takes its turn hosting the Conference of the Parties (COP) to the UN climate convention. Türkiye has a lot riding on the summit, and not only its ability to stage one. Many in the country hope COP31 will put a spotlight on its own climate and environmental crisis.
Extreme weather in Türkiye is becoming far more frequent. In 2011, the country recorded more than 300 extreme weather events. By 2023, according to the Turkish State Meteorological Service, the figure had reached almost 1,500.
Dried-up lakes and sinkholes
For a semi-arid country, drought is a particular threat. Half of Türkiye’s population is at risk of water shortages by 2030, and last year brought the lowest rainfall in 61 years.
Perhaps the starkest sign of this is the alarming rate at which Türkiye’s lakes are vanishing. Three-quarters of its lakes have dried up in the past 50 years, many of them just in the last decade, marking the loss of ecological systems that have sustained generations of farmers and fishermen.
An example is Lake Iznik, the country’s fifth-largest natural lake and the site of the Byzantine Basilica of Saint Neophytos, a fifth-century site whose ruins were first discovered underwater. When Pope Leo visited last year, they stood exposed on dry land as the shoreline had dramatically retreated.
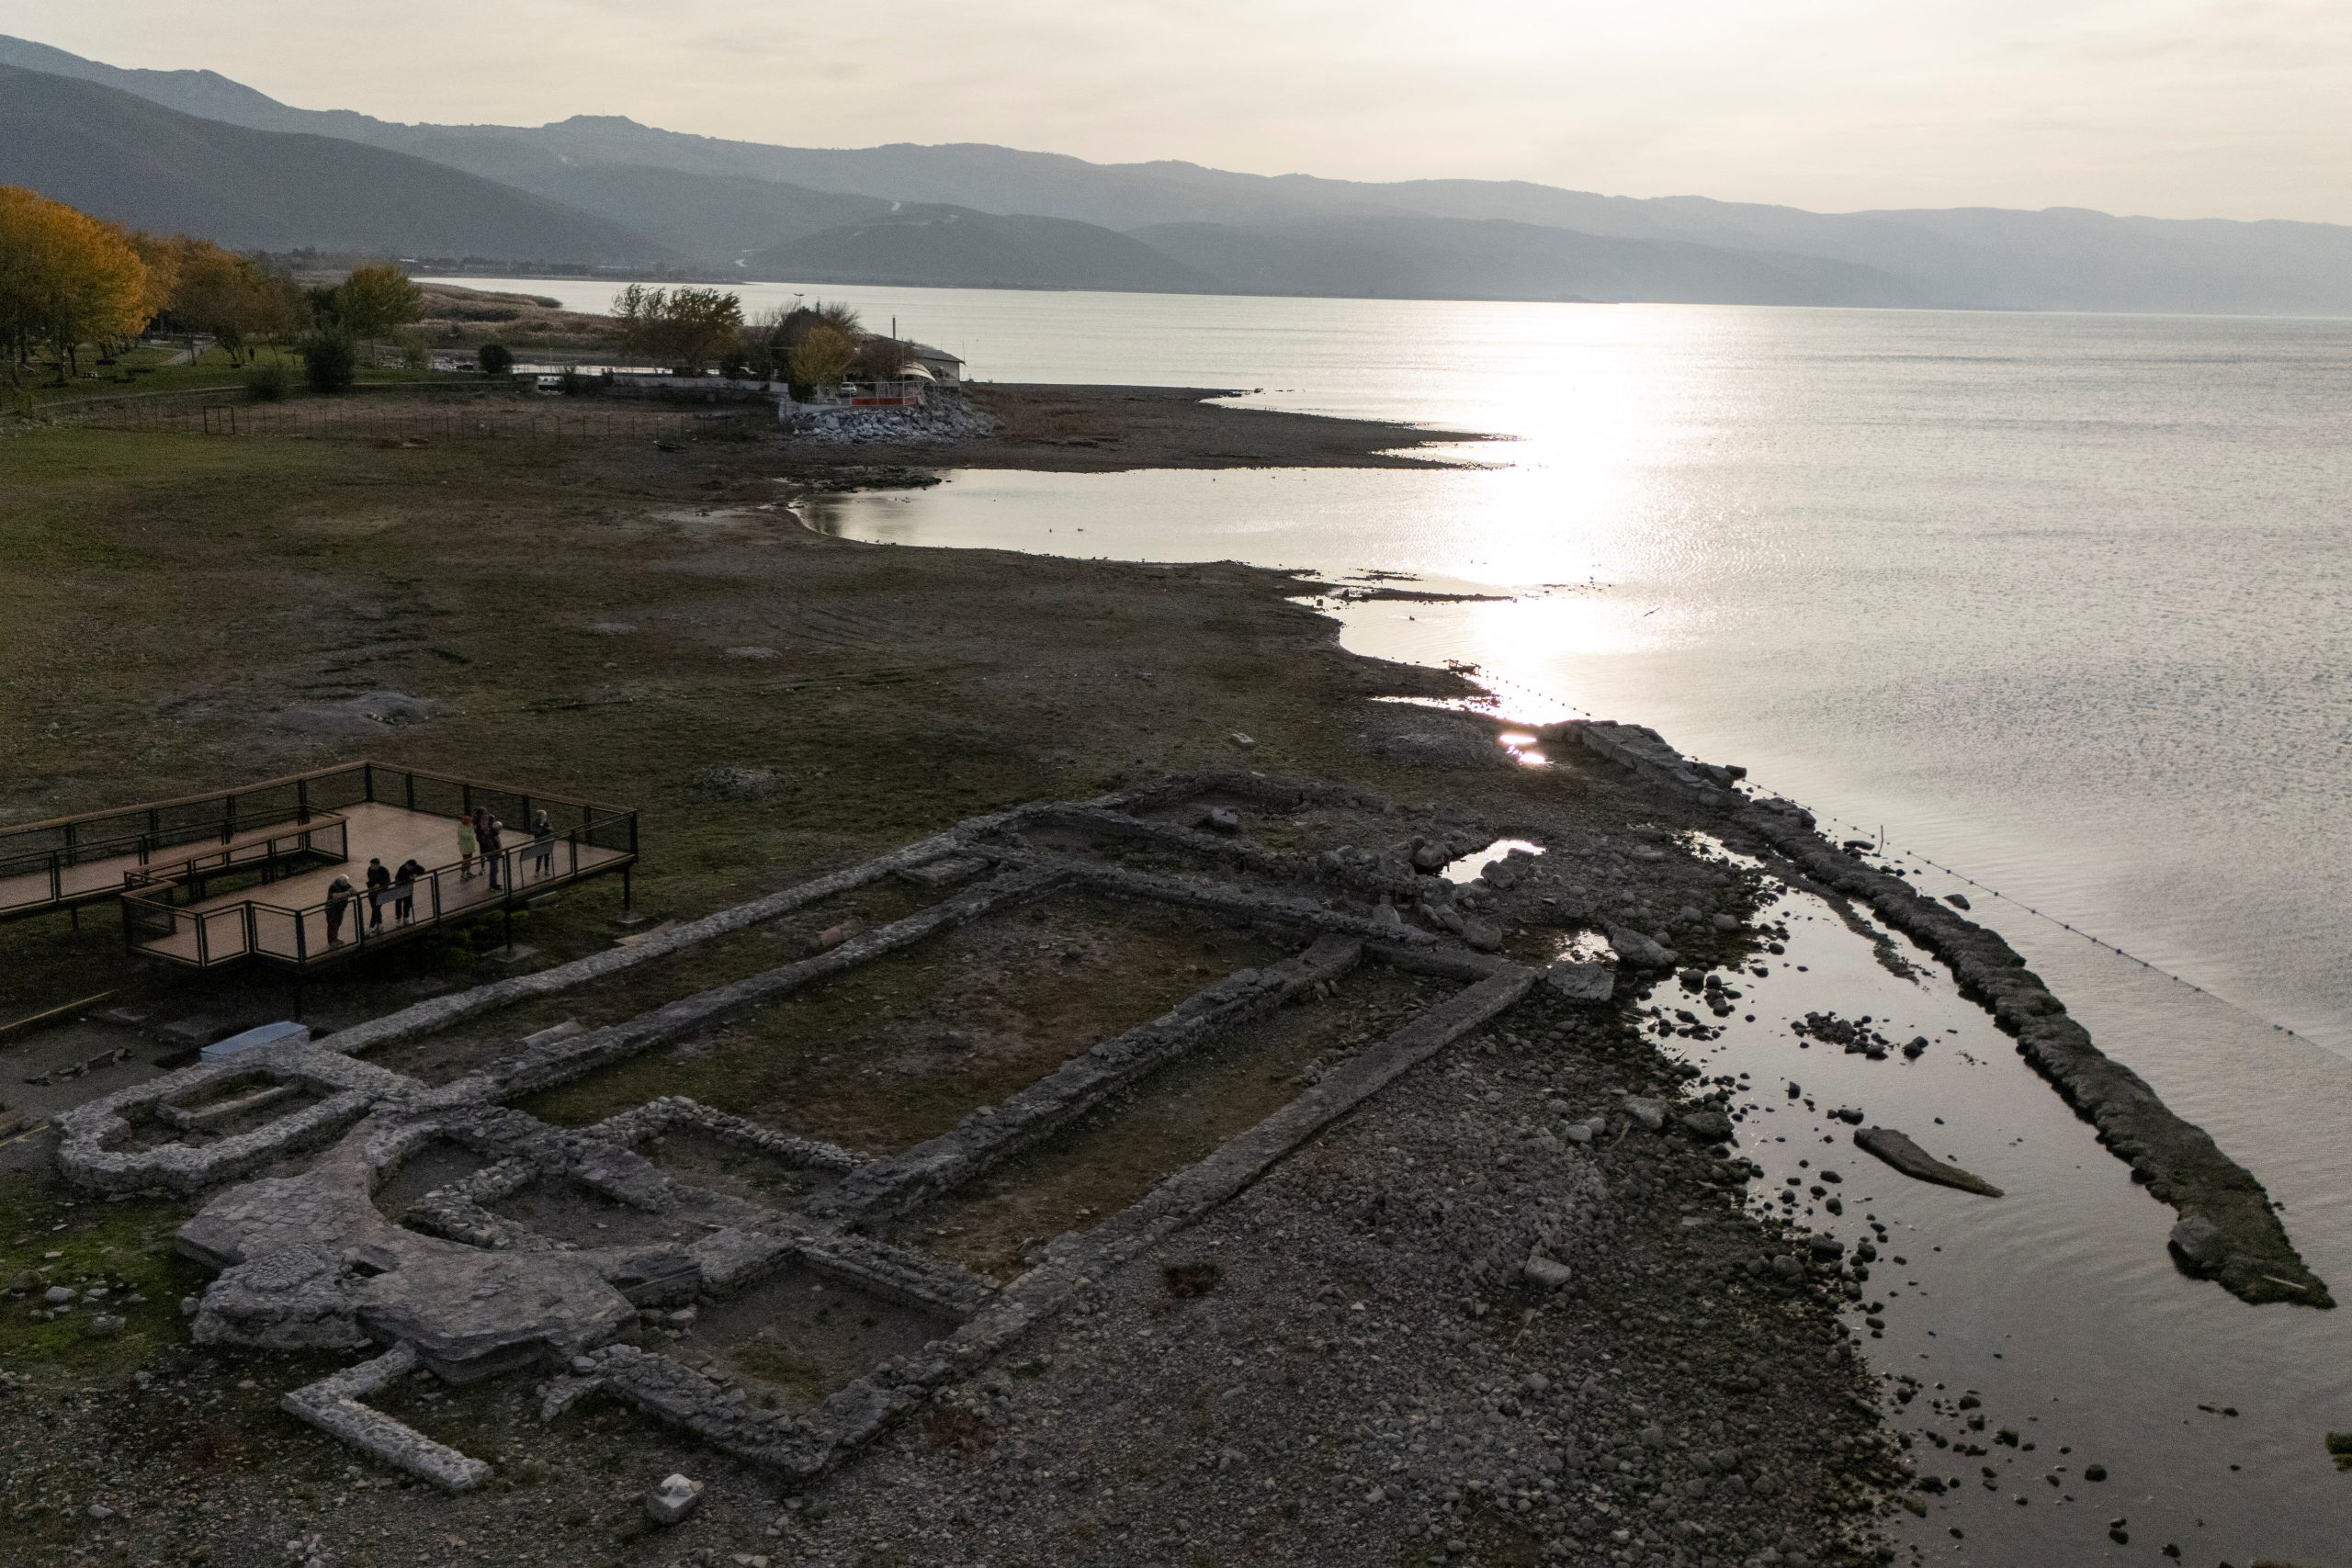
Locals fear that due to drought, as well as the pumping of large volumes of water by big agricultural companies, Lake Iznik will disappear. As Iznik recedes, the coastal water wells that irrigate olive groves have run dry.
“Everyone stands over their phones waiting for weather forecasts, wondering, ‘Will it rain today?’,” one 65-year-old olive farmer told me. “It used to snow waist-deep, and roads would remain closed for weeks. Today, children have forgotten what snow is.”
Agricultural stress isn’t limited to Iznik. In 2025, Türkiye’s crop and field production fell by 9%, while fruits, beverage and spice plants lost nearly a third of their output. According to the agriculture ministry, drought and frost were the main causes.
Visible scars of climate crisis
Sinkholes are also rapidly increasing, now numbering more than 1,000. Most of them are located in the Konya Basin, where groundwater levels fall by about 2 metres a year due to reduced rainfall and excessive extraction.
Türkiye’s sinkholes aren’t just a hazard to human life and infrastructure. They’re a graphic representation of how two human-made phenomena – groundwater exploitation and the climate crisis – combine to weaken the land, causing it to collapse upon itself.
Burnt forests, disappearing lakes, gaping sinkholes: many of these reminders of the climate crisis will remain hidden from visitors in Antalya this month. But the clamour for action will be on full display.
Since last year’s climate summit, a growing number of countries have rallied around a way forward: roadmaps to transition away from fossil fuels. More than just emission-reduction targets, these transition roadmaps are concrete plans on how to end dependence on fossil fuels, the main driver of climate change, in a just and orderly way.
As the Hormuz crisis has shown, not having to rely on oil and gas is no longer just about saving future generations from climate catastrophe – it’s also about saving next month’s household budget.
Electrification milestone
Türkiye is highly dependent on imported fossil fuels, spending an average of $42 billion annually on oil, gas, and coal over the last 10 years. The Hormuz crisis has increased these costs, with Turkish households and businesses losing an additional $3 billion in just two months’ worth of fossil fuel price spikes.
In launching the “35 by 35” electrification target, Türkiye’s COP President Murat Kurum acknowledged the need to protect citizens from high energy prices. This new global target for electricity to meet 35% of final energy demand by 2035 is shaping up to be one of the milestones of this year’s climate talks.
It’s a good target because electrifying transport, buildings and industry significantly cuts not just pollution, but daily expenses too. But electrification alone is not enough. Without an accompanying fossil fuel phase-out, electrification won’t be able to stop further climate and economic catastrophe.
Comment: Turkey must make COP31 a turning point for global climate action
A case in point is Türkiye’s new National Energy Plan 2040. The plan’s emphasis on electrification and the expansion of renewable energy capacity is welcome – these are positive steps that align with the messages coming from Türkiye’s COP31 presidency. However, for the plan to represent genuinely ambitious climate action, it must include a clear commitment and timeline to phase out coal.
Türkiye still relies on mostly imported coal for around one-third of its energy. A 350.org report has revealed that the coal trade between Türkiye and Australia – with which it shares the COP31 presidency – has been responsible for roughly 75 million tonnes of carbon emissions since the Paris Agreement was signed. Neither country has a coal phase-out date.
COP31 is an opportunity to change course. The Turkish government has made good progress on expanding solar and wind energy. In 2025, Türkiye surpassed its solar target as capacity had more than doubled in recent years. It must now build on this progress.
The world will be watching Türkiye as the climate summit heads into its second week. The Turkish government must ensure that global leaders implement real solutions that won’t leave its own citizens high and dry.
The post Behind the COP31 fanfare, Türkiye is worried about water appeared first on Climate Home News.
Scientists behind a landmark UN report on overshooting the 1.5C warming limit have defended its credibility, after Saudi Arabia and other large developing countries questioned its scientific legitimacy and sought to keep it out of the main political decision expected from COP31.
The UN Environment Programme’s (UNEP) Limiting Overshoot report, published in September, examines how to minimise an almost certain breach of the Paris Agreement’s temperature goal, what crossing it will mean for people and ecosystems and how temperatures could be brought back down.
The European Union, the UK, the Least Developed Countries (LDCs) and small island states are among those pushing for COP31 to make the response to overshoot of 1.5C one of the summit’s priorities.
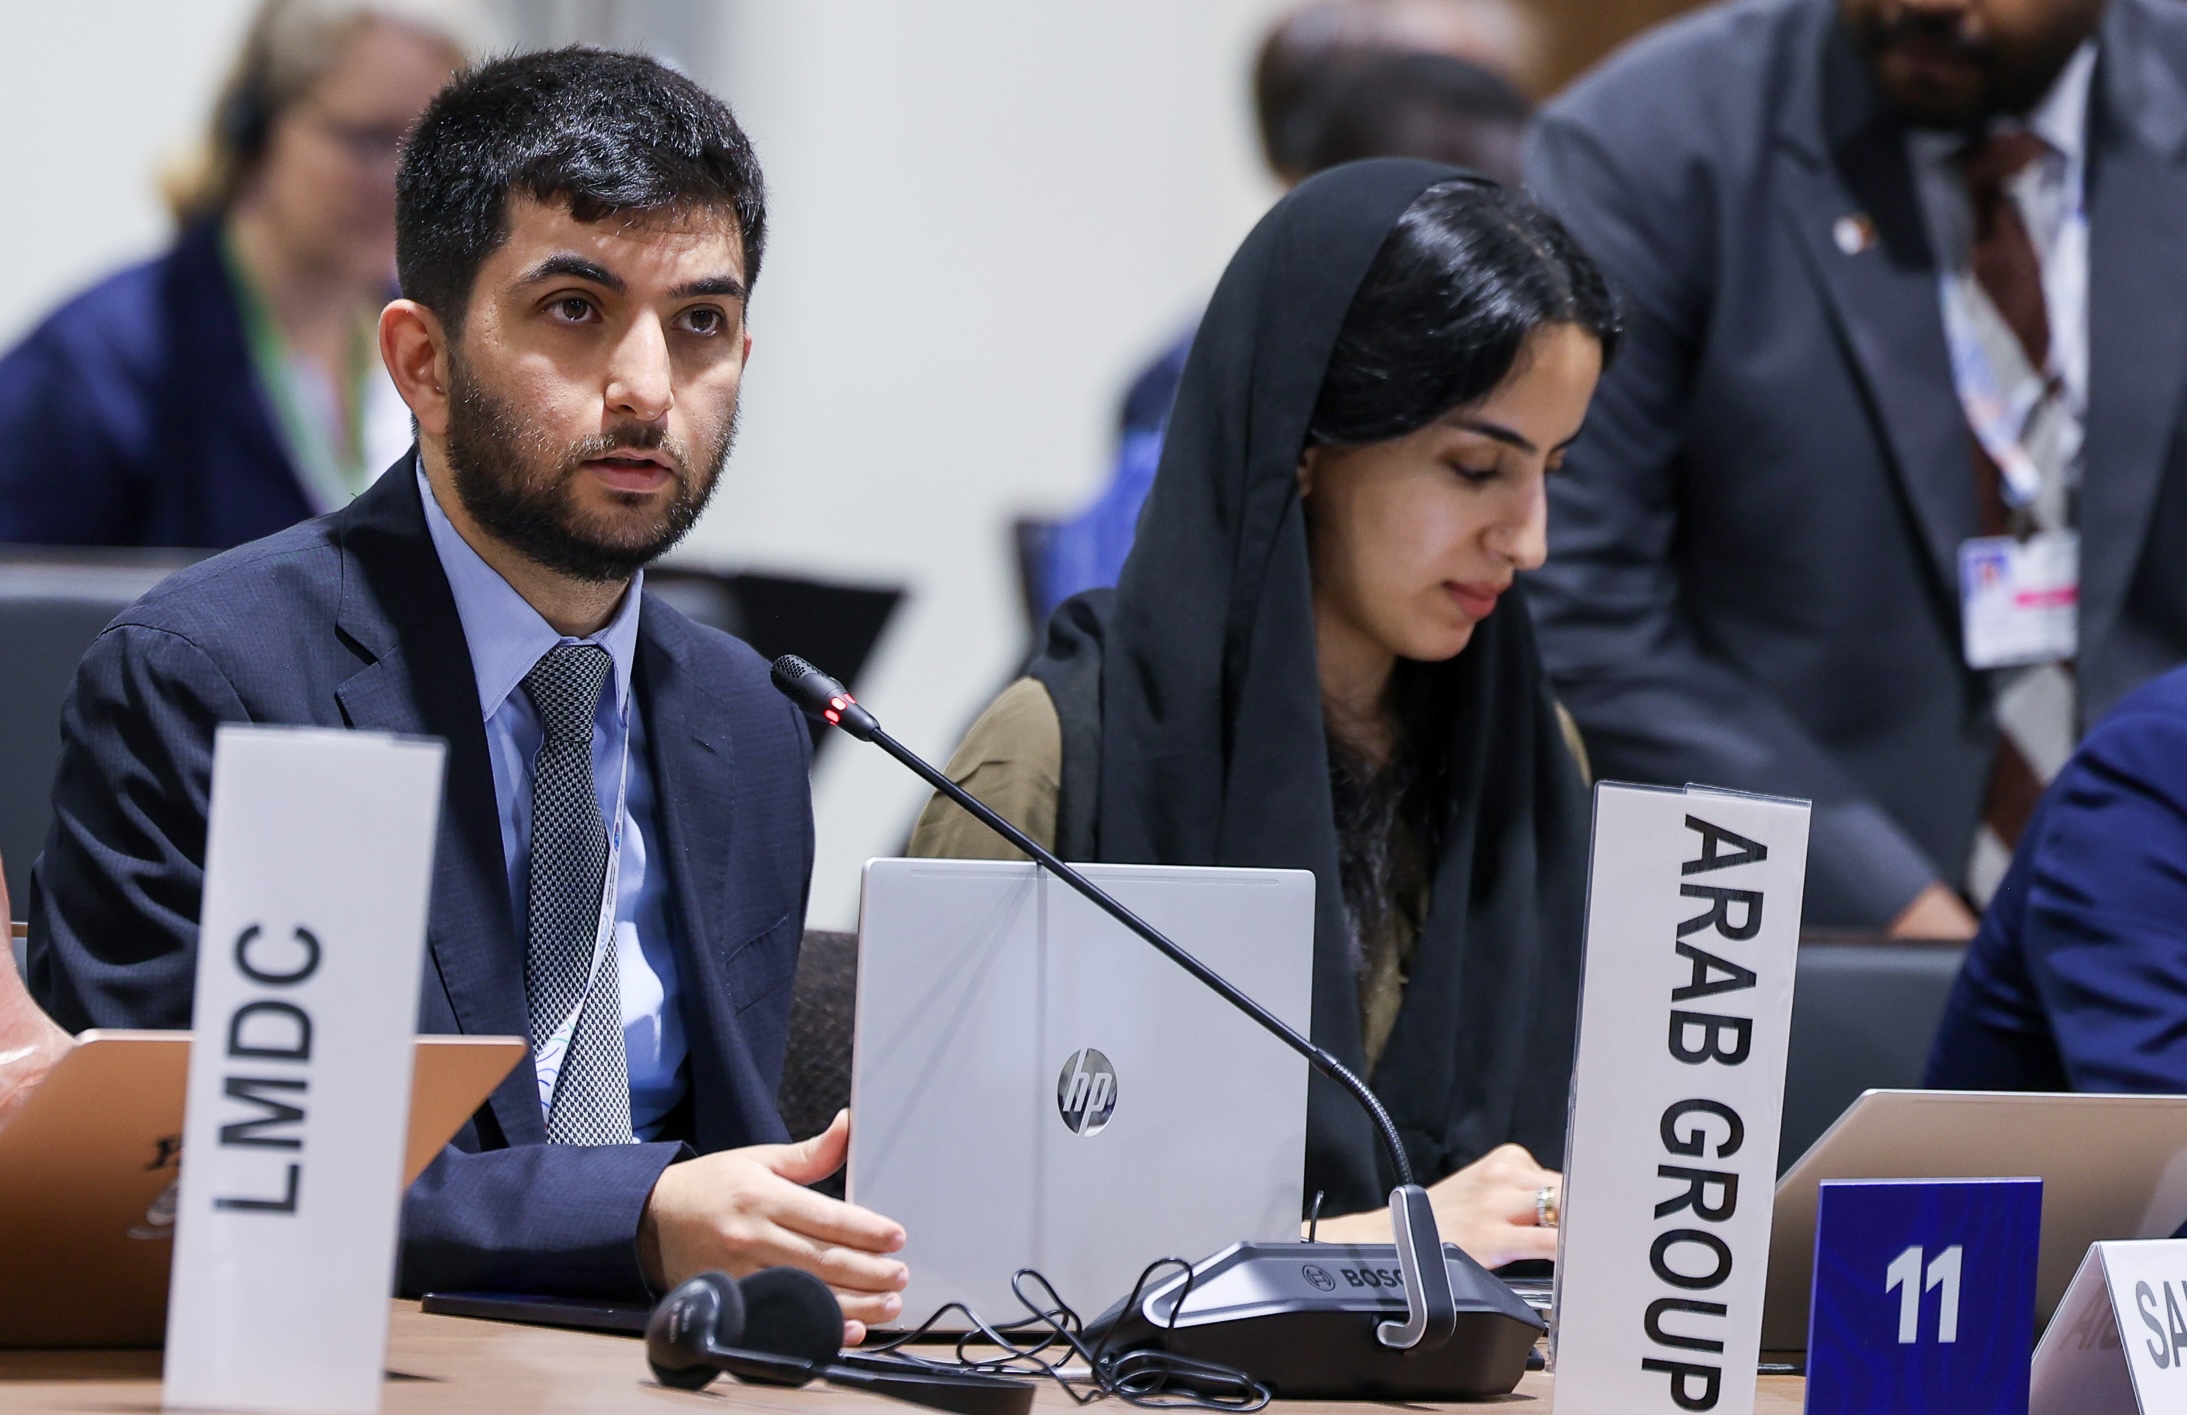
But during closed-door consultations on the cover decision this week, the Arab Group, led by Saudi Arabia, have tried to cast doubt on the report’s scientific rigour, arguing it had not been peer-reviewed, according to sources familiar with the discussions.
Meanwhile, the bloc of Like-Minded Developing Countries (LDMCs), which included India and China, called for the cover decision to avoid references to reports produced outside the UN climate process, seen by observers as a thinly-veiled reference to the UNEP report.
Laurence Tubiana, CEO of the European Climate Foundation and one of the key architects of the Paris Agreement, said the overshoot report “tells us a truth some would rather hide”.
“We are on course to exceed 1.5C and limiting how far and for how long is a matter of survival for us all,” she told Climate Home News. “The attacks on climate science are an attempt to delay action. They target intergovernmental institutions that give countries a shared scientific basis for acting together.”
-
Science ‘under attack’ from fossil fuel interests at UN climate talks
A coalition of some rich nations and the world’s most vulnerable have vowed to protect climate science in UN negotiations -
Framing the climate science debate as a binary battle isn’t just wrong – it’s dangerous
Achieving the Paris Agreement goals requires robust science that fully integrates the experiences, economic realities and academic contributions of the Global South

Rigorous approach
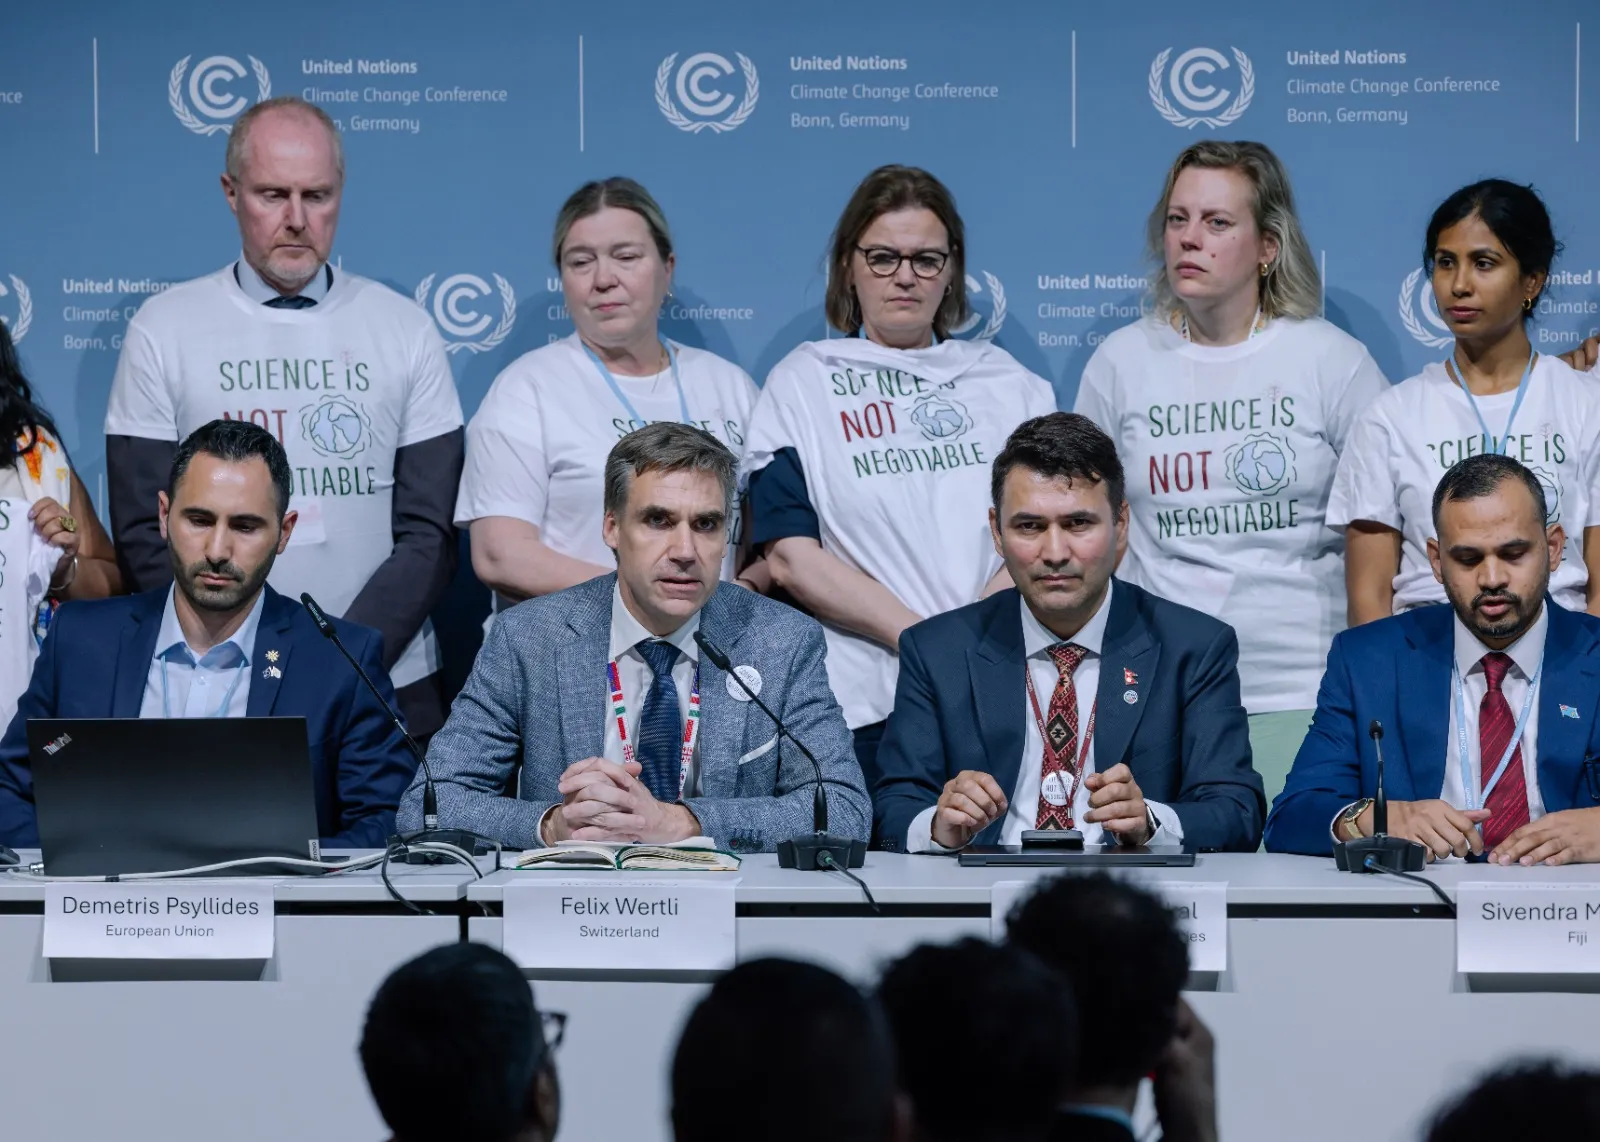
Speaking at an event in Antalya on Saturday, scientists involved in the report also pushed back.
Debra Roberts, a South African scientist who co-chaired the IPCC’s Working Group II in its last assessment cycle and was part of the UNEP report’s core coordinating team, said the authors had followed the standard process for a global assessment of existing science, in line with the practices of the Intergovernmental Panel on Climate Change (IPCC). The only difference, she said, was that governments did not review the outputs.
“It was certainly reviewed internally by the authors, external peer-reviewers were brought into the process, and UNEP also reviewed it,” she told Climate Home News.
Forty-four experts from across the globe authored the report, which largely synthesises existing literature, and their work was scrutinised by a further 44 reviewers in a year-long exercise.
“Let’s be straightforward here: the reports are being attacked because some people don’t like the conclusions and it’s fairly obvious why,” Bill Hare, CEO of Climate Analytics and one of the report’s reviewers, told Climate Home News.
“If you as a government are basing your economy on burning and selling fossil fuels, then the last thing you want to do is accept that we are overshooting 1.5C, because then obviously you will take on some responsibility for paying for the damage,” he added.
“Grey literature” debate
In Antalya, some big emerging economies have also called for “grey literature”, including the overshoot report, to be kept out of the cover decision. The term refers to scientific products that are published outside of traditional academic journals.
While that applies to the UNEP report, some of its authors said it should not mean “grey literature” is of lower quality and cannot be used to inform policy-making.
They added that other forms of “grey literature”, including the UNEP Emissions and Adaptation Gap reports or the work of the International Energy Agency (IEA), are routinely used in the IPCC climate science assessment cycles and sometimes referenced in COP decisions.
Manjeet Dhakal, a Nepalese advisor to the LDCs, told Climate Home News those reports have previously been very useful to inform policy-makers. He added that the overshoot report is comprehensive and countries should be guided by it in Antalya.
‘A distraction’ amid bigger science spat
One of the UNEP report authors said the attempts by some countries to cast doubt on the overshoot report is just “a distraction”.
Clashes over climate science and its role in policy-making have escalated over the last few years amid a long-running stand-off at the IPCC. Most governments want the panel to produce all of its key assessment reports in time to inform the next UN Global Stocktake of climate action, due to be completed in November 2028.
But a smaller group of countries, led by Saudi Arabia, India and Russia, have resisted, claiming that timeline would be too rushed for scientists and governments from developing countries to contribute to and review the reports.
The IPCC will reconvene in an online meeting in early December in a last-ditch effort to find a solution.
As well as the IPCC assessments, Tubiana said the findings of the overshoot report must also inform the next global stocktake.
The post Scientists defend UN overshoot report after Saudi-led push to sideline it at COP31 appeared first on Climate Home News.
Scientists defend UN overshoot report after Saudi-led push to sideline it at COP31
As technical negotiators race to lay the ground for the big political fights coming in the second week of COP31, delegates will spend their Saturday night at a stocktaking plenary presided over by Türkiye and Australia, where countries’ first red lines are expected to emerge.
Countries will have to decide whether to move forward with a cover decision as the main outcome from the Antalya talks. Some large developing countries have pushed back on it all week, as well as on any inclusion of sectoral targets, including a flagship new pledge to increase electrification to 35% by 2035.
UN climate chief Simon Stiell told a press conference on Saturday morning that progress so far has been “constructive” and praised the fact that negotiations were able to start on time as countries avoided what had seemed to be shaping up as a fight over the agenda.
He added that Saturday’s plenary will provide a sense of the most controversial issues, which government ministers now flying will have to take up and settle.
As of now, most issues on the formal agenda still need a lot of work. The cover text is more a wishlist of every proposal tabled and still needs to be worked up into a draft – expected by early next week.
An informal note on the Mitigation Work Programme (MWP), which tackles cutting planet-heating emissions, is heavily bracketed. The EU has said one of its priorities is to extend the MWP, with current options for a timeline going up to 2030, 2031 or 2040 (at COP45!). The MWP has so far delivered weak outcomes, but the current fight is over whether to expand its scope and task it with informing the next Global Stocktake of climate policies in 2028.
-
COP31 Bulletin Day 5: Cover decision wishlist issued as China bows out of COP33 hosting
Governments must start narrowing down what a political decision could look like in Antalya, while the conversation buzzes around who will host 2028’s important COP -
Push for ocean roadmap that informs next global stocktake grows at COP31
A group of countries including African nations, European Union, and small island states wants COP31 to deliver an ocean roadmap towards 2028 -
COP31’s electrification pledge wins support, with caveats on clean power and finance
At least 14 countries have endorsed the voluntary pledge so far, but island nations warn it must not distract from the shift away from fossil fuels
A separate draft text on the global goal on adaptation released overnight is set to become the main battleground for Africa’s top priority to triple adaptation finance to “at least $120 billion per year by 2035”, based on a previous goal set in 2021 – a figure it wants agreed in Antalya.
Another option in the text proposes starting a process to review several elements of this finance target – which was adopted in the final deal at COP30 – including the baseline, the total amount and its scope. It requests this to be reflected in a report that would then be considered at a later summit. African countries are likely to push back on this idea.
An informal note that includes the set-up of a new Just Transition Mechanism also came out late on Friday and has been condemned by civil society groups for the limited scope of what it would be expected to achieve.
In the meantime, the Turkish and Australian co-presidency has continued consultations on a number of issues, including on how to strengthen the UN climate process itself. Some countries – including Arab nations, Mexico, Korea and Switzerland – have proposed switching COPs to a biennial format, instead of the current yearly summits.
Brazil says it wants to host third fossil fuel phase-out conference
Brazilian President Lula da Silva told civil society in Antalya this week that his country should host the third global conference on Transitioning Away from Fossil Fuels (TAFF), which would likely fall in 2028.
“We have the moral obligation,” Lula said at a meeting before heading off to the Philippines for the ASEAN summit. The Brazilian president told the event he came to Antalya to demonstrate that “no country has more credibility on climate” than his.
The first conference on TAFF was held in Santa Marta by a coalition of around 60 governments that decided to take voluntary measures to wean their economies off coal, oil and gas. The next conference is expected to take place mid-next year in Tuvalu, with a pre-conference event for academics, subnational governments and civil society in Dublin.
In Antalya, Brazil’s COP30 presidency held a big launch event for a voluntary global roadmap it produced to help countries shift off fossil fuels, proposing a build-up of clean energy systems followed by a push to start phasing out coal, oil and gas production and consumption after 2031.
Currently, a proposal to welcome the Brazil-led roadmap in the formal UN negotiations is included in the COP31 cover decision, as well as an option for “ongoing implementation” of a COP28 landmark deal to transition away from fossil fuels in energy systems.
The post COP31 Bulletin Day 6: Limited progress as ministers arrive in Antalya appeared first on Climate Home News.
https://www.climatechangenews.com/2026/11/14/cop31-bulletin-day-6-limited-progress-as-ministers-arrive-in-antalya/



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Green Living2 years ago
Our Picks for the Top 2024 Black Friday and Cyber Week Sales From Sustainable Brands
-
Renewable Energy1 year ago
US Grid Strain, Possible Allete Sale
-

 Renewable Energy5 months ago
Send a Bible to a Starving Child