


The Voluntary Carbon Market (VCM) has been a vital tool for combating climate change, enabling organizations to offset emissions by funding projects that reduce or remove greenhouse gases (GHGs). Once viewed as a cornerstone for corporate sustainability efforts, the market is now at a critical juncture.
Challenges such as fraudulent practices, questionable project integrity, and waning buyer confidence have sparked concerns about its future. However, amid these setbacks lies an opportunity for transformation. Is the VCM truly on its last leg, or is it evolving to meet the demands of a more discerning global audience?
A Look Back: The Voluntary Carbon Market’s Evolution
What Are Carbon Credits?
Carbon credits represent the reduction or removal of one metric ton of CO₂-equivalent emissions. They are typically achieved through projects such as renewable energy, reforestation, and sustainable agriculture.
These credits are often purchased by companies to offset emissions they cannot reduce internally, allowing them to claim progress toward carbon neutrality.
The VCM differs fundamentally from compliance markets, which are regulated by governments and operate on a cap-and-trade basis. The unregulated nature of the VCM has allowed it to thrive, providing flexibility for buyers and enabling the development of innovative project categories. However, this lack of regulation has also led to vulnerabilities in accountability and standardization.
Exponential Market Growth and Who Drives It
From its origins as a niche market, the VCM has grown exponentially. By 2022, it was valued at $2 billion, driven by rising corporate commitments to net-zero targets.
Projections estimate the market could balloon to up to $25 billion by 2030, representing a 15-fold growth from its current size. This expansion has been fueled by increasing pressure on businesses to address climate change and the growing adoption of sustainability frameworks.

Initially, the VCM emerged as a voluntary alternative to compliance markets, allowing companies to take responsibility for emissions beyond regulated requirements. Over the years, major corporations like Microsoft, Google, and Starbucks have leveraged the VCM to achieve ambitious net-zero goals.
Key participants in the VCM include:
- Project Developers – These entities create carbon credits through verified environmental projects.
- Consumers – Private companies, governments, and individuals purchase credits to offset emissions.
- Retail Traders and Brokers – They bundle and market credits to buyers.
- Third-Party Verifiers – Organizations like Verra and Gold Standard ensure projects meet stringent standards for emissions reduction. These also include carbon rating agencies that provide more transparency and authenticity to carbon projects.
While plenty of companies operate in the VCM, some names stand out because of their major contributions to the space.
For example, Xpansiv operates the world’s largest voluntary carbon exchange through its CBL platform, offering transparent, efficient trading of carbon credits and renewable energy certificates. The platform connects over 1,000 verified projects and partners with major carbon standards like Verra and Gold Standard.
Xpansiv’s technology enables same-day settlement and reduces delivery risks, enhancing market accessibility and liquidity. It also bridges voluntary and compliance markets, facilitating products under programs like the Regional Greenhouse Gas Initiative (RGGI) and California Cap-and-Trade.
Another key player, Laconic Global, operates at the intersection of technology and the VCM, offering solutions that improve transparency and functionality. They utilize their proprietary SADAR Natural Capital Monetization (NCM) platform to provide real-time carbon market data, including live pricing, trade analysis, and portfolio valuation tools.
Finally, in the realm of carbon credit ratings, a London-based company, BeZero Carbon offers high specialization. It provides transparency and risk assessments for carbon markets through its BeZero Carbon Ratings. It evaluates the quality and risks of individual carbon credits, covering factors such as additionality, permanence, leakage, and policy risks.
These companies’ works are crucial to keeping the market alive and striving, despite mounting issues and challenges.
VCM’s Current Challenges and Setbacks
Integrity Under Scrutiny
The VCM has faced intense criticism for the questionable integrity of some projects. For example, certain REDD+ initiatives—aimed at reducing deforestation—have been accused of inflating baselines, leading to overestimated carbon savings. High-profile scandals, such as funds from Zimbabwe’s Kariba REDD+ project failing to reach local communities, have further eroded trust.
This scrutiny has translated into financial losses. In 2023, transaction volumes dropped by 56% from the previous year, and the market’s value plummeted to $723 million—a stark contrast to its 2021 peak of $2 billion.
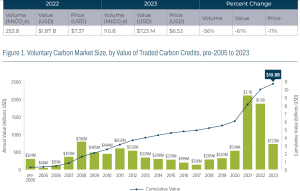
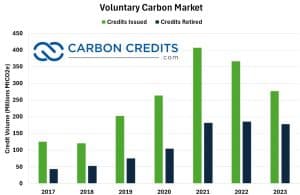
In effect, average credit prices fell to $6.53 per ton, a decline that reflects reduced buyer confidence. The chart below shows dampened market sentiment since 2021 when criticisms began, with number of credits demanded (retired) and produced (issued) decreased.
Media coverage has amplified the market’s vulnerabilities, highlighting instances of greenwashing and low-quality credits. This negative attention has deterred corporate buyers, many of whom fear accusations of insincere climate action. Companies are increasingly seeking transparency and accountability in the credits they purchase, placing additional pressure on the VCM to reform.
Signs of Recovery: Building a Stronger Market
Better Standards, Better Confidence
Despite these challenges, the VCM is evolving. The introduction of integrity frameworks such as the Core Carbon Principles by the Integrity Council for the Voluntary Carbon Market (ICVCM) and the Claims Code by the Voluntary Carbon Markets Integrity Initiative (VCMI) aim to restore buyer confidence.
These initiatives emphasize project transparency, robust verification processes, and adherence to high environmental and social standards.
Standards organizations are addressing past shortcomings. Verra, for example, introduced revised baseline calculations for REDD+ projects in 2023, aimed at resolving overestimation issues. These updates signify a shift toward greater accuracy and accountability, which could help rebuild trust among stakeholders.
More Than Just Carbon: Focus on Co-Benefits
In 2023, 28% of VCM transactions involved projects offering co-benefits such as biodiversity conservation or alignment with Sustainable Development Goals (SDGs). This reflects a growing buyer preference for credits that deliver tangible environmental and social outcomes in addition to carbon reductions.
Why the VCM Still Matters
Amid all the setbacks, the long-term outlook for the VCM remains optimistic.
Echoing this outlook, Xpansiv’s COO Ben Stuart remarked that:
“Despite ongoing challenges in the Voluntary Carbon Market (VCM), recent indicators suggest continued growth and renewed signs of market confidence. Notably, total retirements have increased year-on-year from 2023 to 2024, signaling a steady commitment from existing participants and an increase in new stakeholders engaging with the market.”
He further noted that the VCM is gaining validation through various international frameworks, which is helping to address concerns about market integrity, highlighting:
Last month, at COP29, countries reached a landmark agreement on the adoption of Article 6.4… In parallel, the International Civil Aviation Organization (ICAO) has approved standards…At the national level, the VCM continues to gain traction, with countries such as South Africa, Japan, and Singapore incorporating the VCM into their domestic carbon schemes. These are renewed signs of market confidence…”
Projections indicate a compound annual growth rate (CAGR) of 31% from 2023 to 2028. Key drivers include global net-zero commitments, regulatory alignment under frameworks like the Paris Agreement, and technological advancements in carbon removal.
Technological innovations help the market bounce back as advanced data gathering and sophisticated technologies produce more transparent and reliable verification processes.
Carbon removal technologies, such as direct air capture, are gaining traction. These solutions, which physically extract CO₂ from the atmosphere, are increasingly favored for their clear and measurable impact.
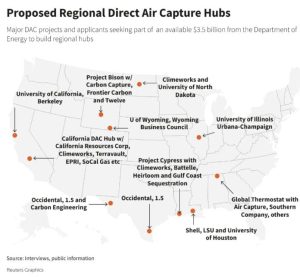
In 2023, removal credits commanded a 245% price premium over reduction credits, underscoring their value in meeting net-zero targets.
Emerging Trends in the VCM
Increased Demand for High-Quality Credits and Market Integration
Buyers are increasingly prioritizing quality over quantity, focusing on credits that are rigorously verified and offer co-benefits. The share of transactions from projects with co-benefits grew from 22% in 2022 to 28% in 2023, indicating a shift toward more impactful solutions.
Moreover, the VCM is becoming increasingly segmented, with distinct markets emerging for engineered solutions, nature-based projects, and co-benefit-driven initiatives. This differentiation allows buyers to tailor their investments to align with specific climate goals and organizational values.
More notably, as regulatory frameworks under Article 6 of the Paris Agreement are finalized, the boundaries between voluntary and compliance markets are becoming increasingly blurred. This integration offers opportunities for scaling the VCM while addressing systemic issues such as double counting and project accountability.
COP29: A Turning Point for Carbon Markets
The 2024 COP29 in Baku proved pivotal for the future of carbon markets, especially after the uncertainty surrounding the potential re-election of Donald Trump. Despite this looming challenge, the outcomes at COP29 gave a much-needed boost to the climate conversation, particularly following the disappointing results at COP28.
Progress on Article 6.2 and Article 6.4
Article 6 negotiations remained a focal point, with texts on both Article 6.2 and 6.4 evolving through the first week. After extensive deliberations, the final texts were ratified late on the second Saturday of the conference. These decisions provided much-needed clarity and a clear framework for the implementation of carbon markets, marking a significant step forward after COP28’s lack of progress.
One of the most significant achievements was the establishment of clear rules for the transfer and tracking of carbon credits under Article 6.2. This mechanism, which allows for carbon credit trade between countries, is expected to drive substantial investment in climate action, particularly in developing nations.
A Historic Milestone for Carbon Markets
The final adoption of the Article 6 texts was hailed as a historic milestone for climate finance. These decisions provide developers, investors, and countries with much-needed certainty regarding how carbon credits are created and traded. The text’s adoption also set a path for the effective scaling of carbon markets, intending to contribute billions in funding for climate initiatives by the end of the decade.
Despite some pushback from carbon market skeptics, who argue that the system could provide a lifeline for the fossil fuel industry, the global community remains optimistic. The new rules aim to ensure greater transparency, reduce double counting, and enhance the accountability of carbon credits.
The next major milestone for Article 6 is expected in 2025 when the Supervisory Body for Article 6.4 meets to discuss further refinements. By then, the geopolitical landscape may have shifted, with a new US president potentially influencing the direction of international climate negotiations.
According to some accounts, 2025 will be the “moment of reckoning” for the VCM. Yet, given the past criticisms and current market challenges, the market has to overcome some major hurdles to move forward, as recommended by market experts.
Barriers to Address for Sustained Growth
- Regulatory Alignment: Clearer rules are needed to integrate voluntary and compliance markets seamlessly.
- Market Liquidity: Addressing the low liquidity of certain credit types is essential for maintaining market functionality.
- Trust and Transparency: Rebuilding buyer confidence through improved verification processes and independent oversight is crucial.
- Education: Buyers and the public need greater awareness of the nuances of carbon credits to combat misconceptions and rebuild trust.
Looking Ahead: Is the VCM Dead?
While the VCM has faced undeniable setbacks, it is far from dead. Instead, it is undergoing a critical transformation, driven by the need for enhanced quality and transparency. If integrity initiatives, gain traction, the VCM could emerge stronger and more impactful.
Tommy Ricketts, CEO and Co-Founder of BeZero Carbon, perfectly highlighted this, saying that:
“Carbon markets are restructuring after a turbulent couple of years. Carbon ratings, insurance, and accounting are working together to raise the bar for carbon credit quality…Market actors must recognize carbon credits for what they are: valuable but imperfect mechanisms to channel finance towards climate action. Bolstering the market for credits means buyers and market players must lean on the tools that exist to manage this risk.”
The market’s challenges underscore the importance of vigilance, innovation, and collaboration. As stakeholders refine frameworks and methodologies, the VCM holds the potential to bridge the gap between ambition and action, giving corporations and individuals the tools to fight climate change.
- FURTHER READING: COP29 Breakthrough: UN-Backed Global Carbon Market Takes Shape
The post Is the Voluntary Carbon Market Dead? appeared first on Carbon Credits.

Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
CCC’s guide to finding nature-based solutions in your supply chain explains where to look. Here, the next task is to turn a broad concern into a testable proposal.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3 Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
Discuss a sourcing opportunity with CCC
Carbon Credit Capital’s nature-based supply-chain investment service uses its Dual-Value Model to examine supply-chain economics alongside potential sustainability outcomes.
Schedule a consultation to discuss your sourcing exposure and the questions to resolve before allocating capital.
Sources
- Intergovernmental Panel on Climate Change (IPCC), Climate Change 2022: Mitigation of Climate Change, Chapter 7, Agriculture, Forestry and Other Land Uses, section 7.4.3.3 (Agroforestry).
- World Business Council for Sustainable Development (WBCSD), Nature-based Solutions Blueprint, 5 June 2024.
- Science Based Targets initiative (SBTi), Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, section 3.1.4, pp. 37–38.
- United Nations Environment Programme (UNEP), State of Finance for Nature 2023, 2023.
A plastic credit funds the collection of plastic waste in places where no formal system exists to collect it. Each credit represents a measured, independently audited quantity of plastic taken out of the environment or returned to use, tracked on a public registry.

EU carbon credit claims changed on 27 September 2026, the day the Directive (EU) 2024/825 began to apply across the European Union. The change is narrow. It changes how a company can talk about the credits it buys. A product can no longer be called neutral on the strength of compensation alone; however, every specific, evidenced statement about what a company measured, reduced, and funded stays fully available.




