

The first three months of 2026 have been the fourth warmest on record, with each successive month surpassing historical averages by a greater margin.
While weak La Niña conditions pushed down temperatures at the start of the year, scientists expect the development of a strong – and potentially “super” – El Niño event by early autumn.
El Niño and La Niña are the warm and cool phases of the El Niño-Southern Oscillation (ENSO), a recurring climate pattern in the tropical Pacific that shapes global weather patterns.
Based on temperature datasets from five different research groups, Carbon Brief predicts that 2026 is likely to be the second-warmest year on record.
The year is virtually certain to be one of the four warmest on record and, currently, has a 19% chance of surpassing 2024 as the warmest year on record.
However, the development of a strong El Niño event later this year would substantially increase the chance that 2027 will be the warmest year on record.
In addition to near-record warmth, the start of 2026 has seen record-low sea ice cover in the Arctic, with the year tying with 2025 for the lowest winter peak in the satellite record.
Fourth-warmest start to the year
In this latest quarterly state of the climate assessment, Carbon Brief analyses records from five different research groups that report global surface temperature records: NASA, NOAA, Met Office Hadley Centre/UEA, Berkeley Earth and Copernicus/ECMWF.
The figure below shows the annual temperatures from each of these groups since 1970, along with the average over the first three months of 2026.
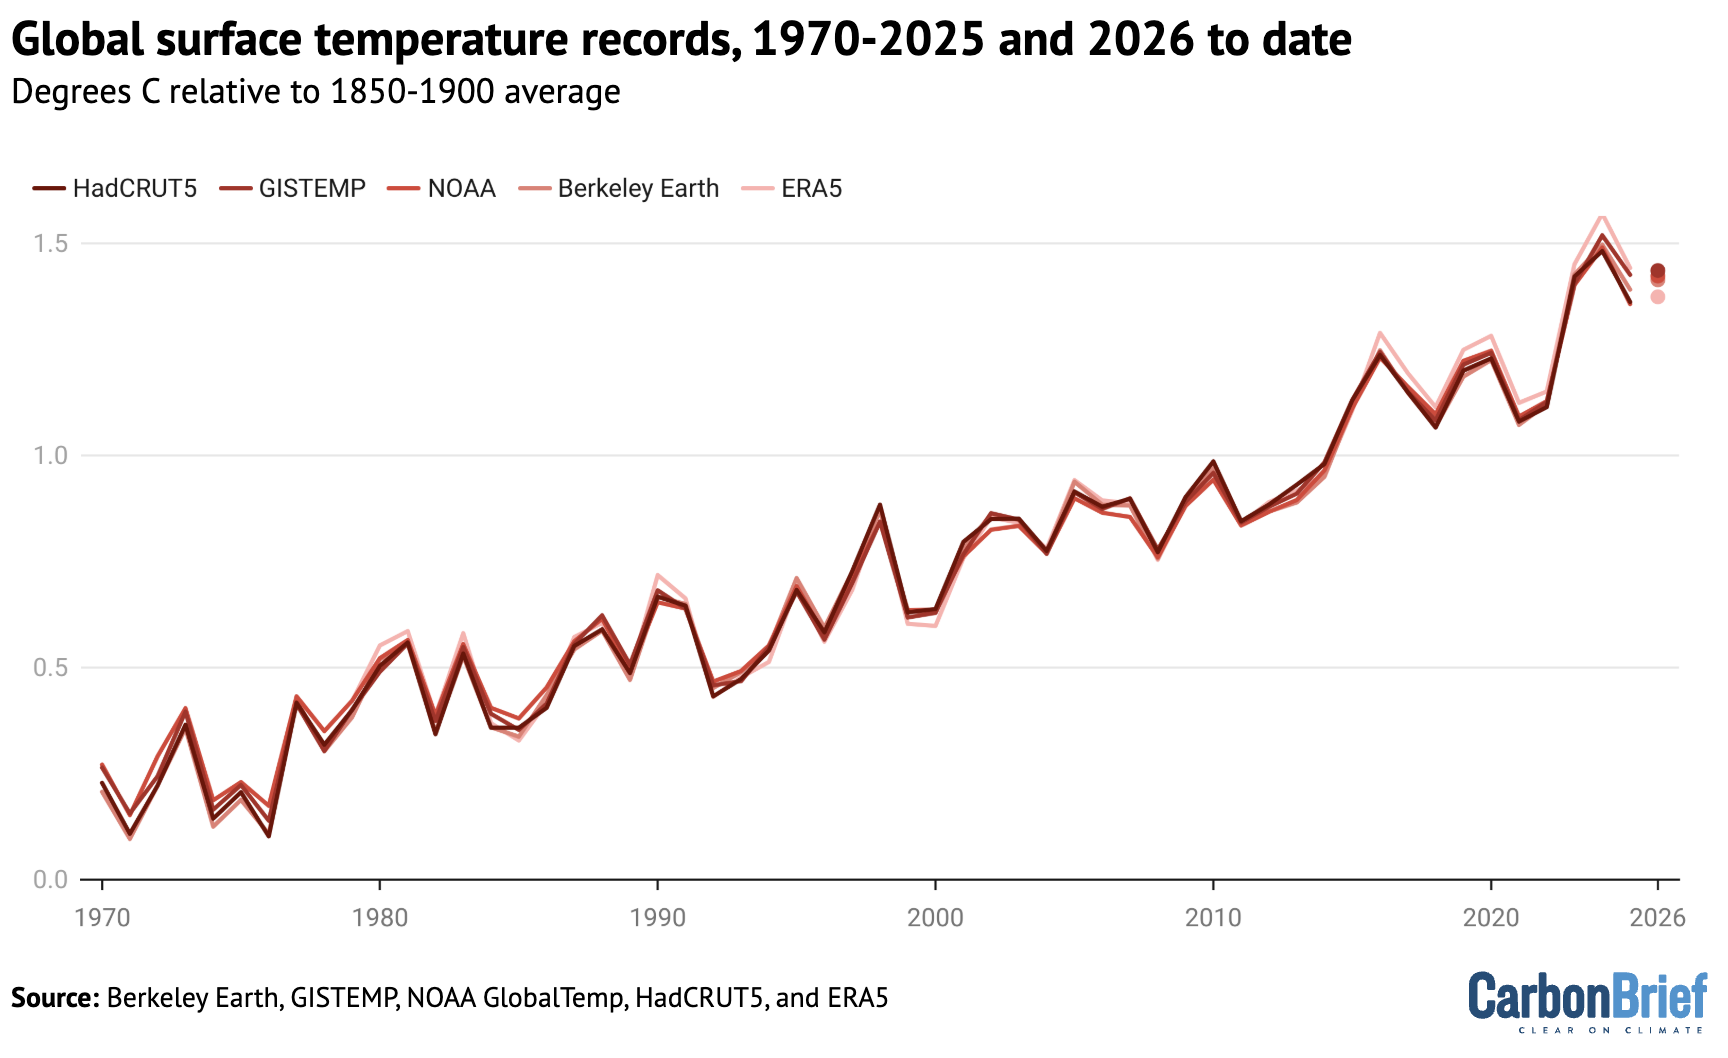
(It is worth noting that warming in the first three months may not be representative of the year as a whole, as temperatures relative to pre-industrial levels tend to be larger in the northern hemispheric winter months of December, January and February.)
Carbon Brief provides a best estimate of global temperatures by averaging the different records using a common 1981-2010 baseline period and then adding in the average warming since the pre-industrial period (1850-1900) across the datasets – NOAA, Hadley and Berkeley – that extend back to 1850. (This follows the approach taken by the World Meteorological Organization in its state of the climate reports.)
The figure below shows how global temperature so far in 2026 (black line) compares to each month in different years since 1940 (lines coloured by the decade in which they occurred).
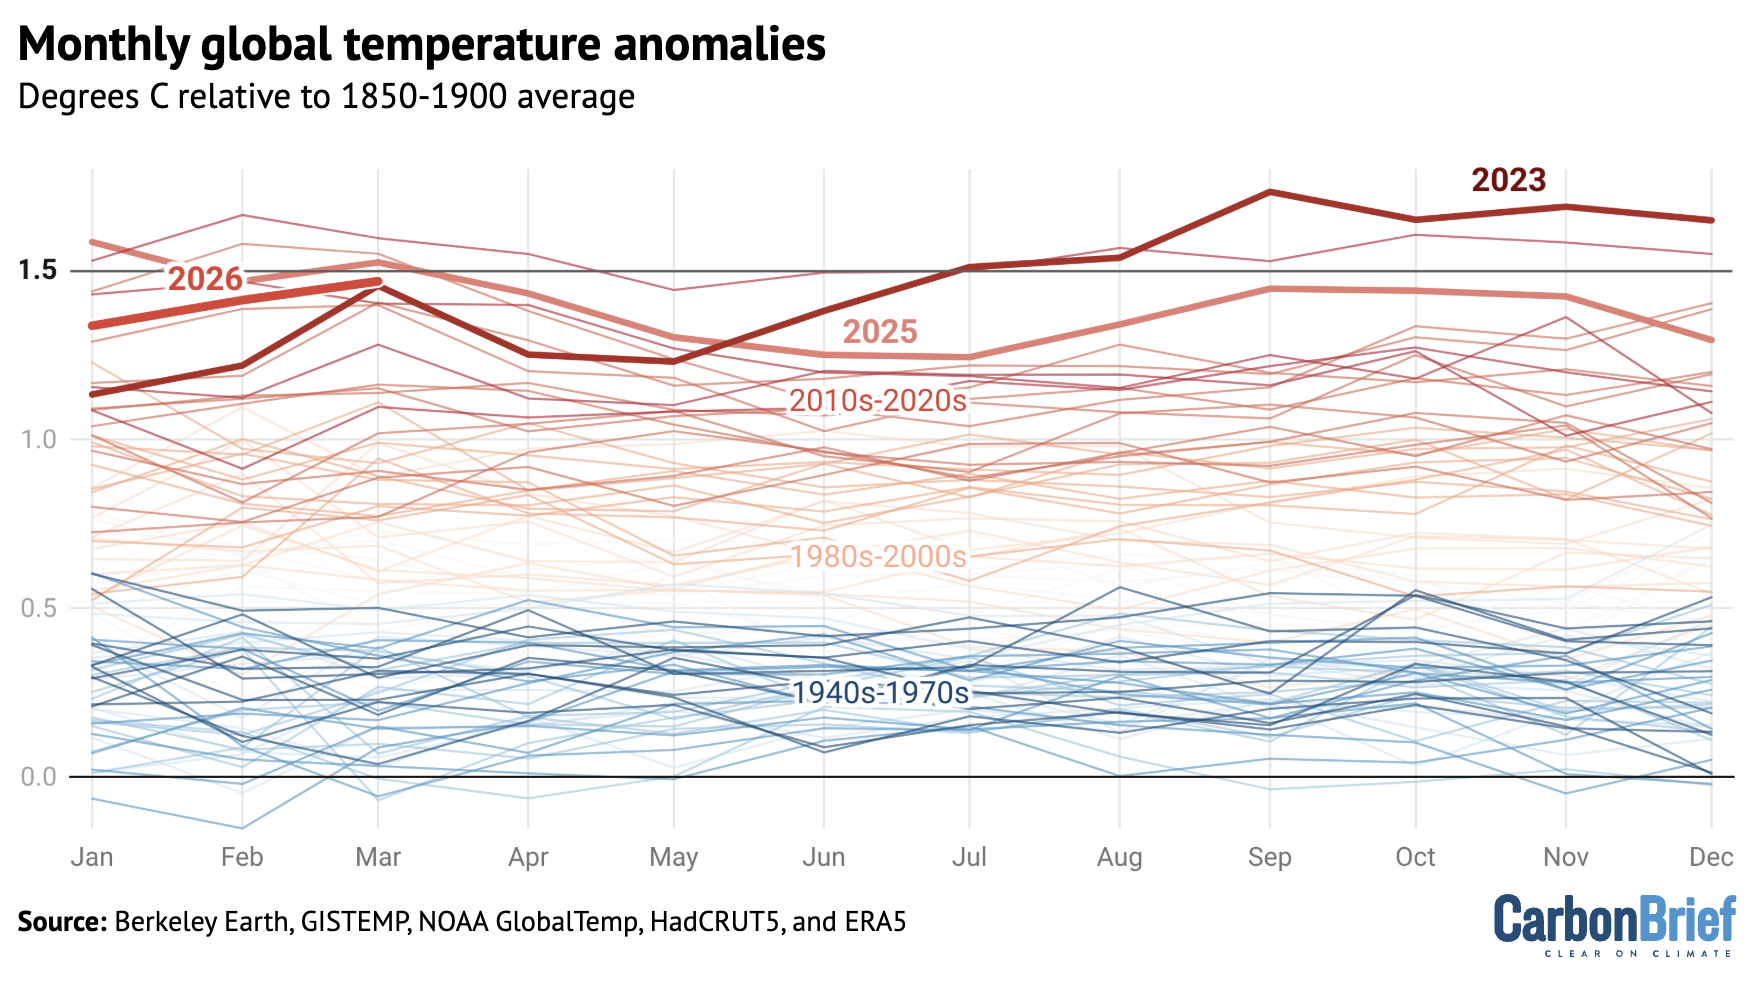
The first three months of 2026 have been relatively warm, coming in in the top-five warmest on record across all the different scientific groups that report on global surface temperatures. This is despite the presence of weak La Niña conditions in the tropical Pacific at the start of the year, which typically suppress global temperatures.
January 2026 was the fourth- or fifth-warmest January on record across all the groups, February was the fourth- to sixth-warmest and March was between the second and fourth warmest.
| Dataset | January | February | March |
|---|---|---|---|
| HadCRUT5 | 5th | 6th | Yet To Report |
| NOAA | 5th | 5th | 2nd |
| GISTEMP | 5th | 4th | 4th |
| Berkeley Earth | 4th | 4th | 4th |
| Copernicus ERA5 | 5th | 5th | 4th |
Global temperature anomalies have been steadily increasing since their low point in January, as La Niña conditions have faded.
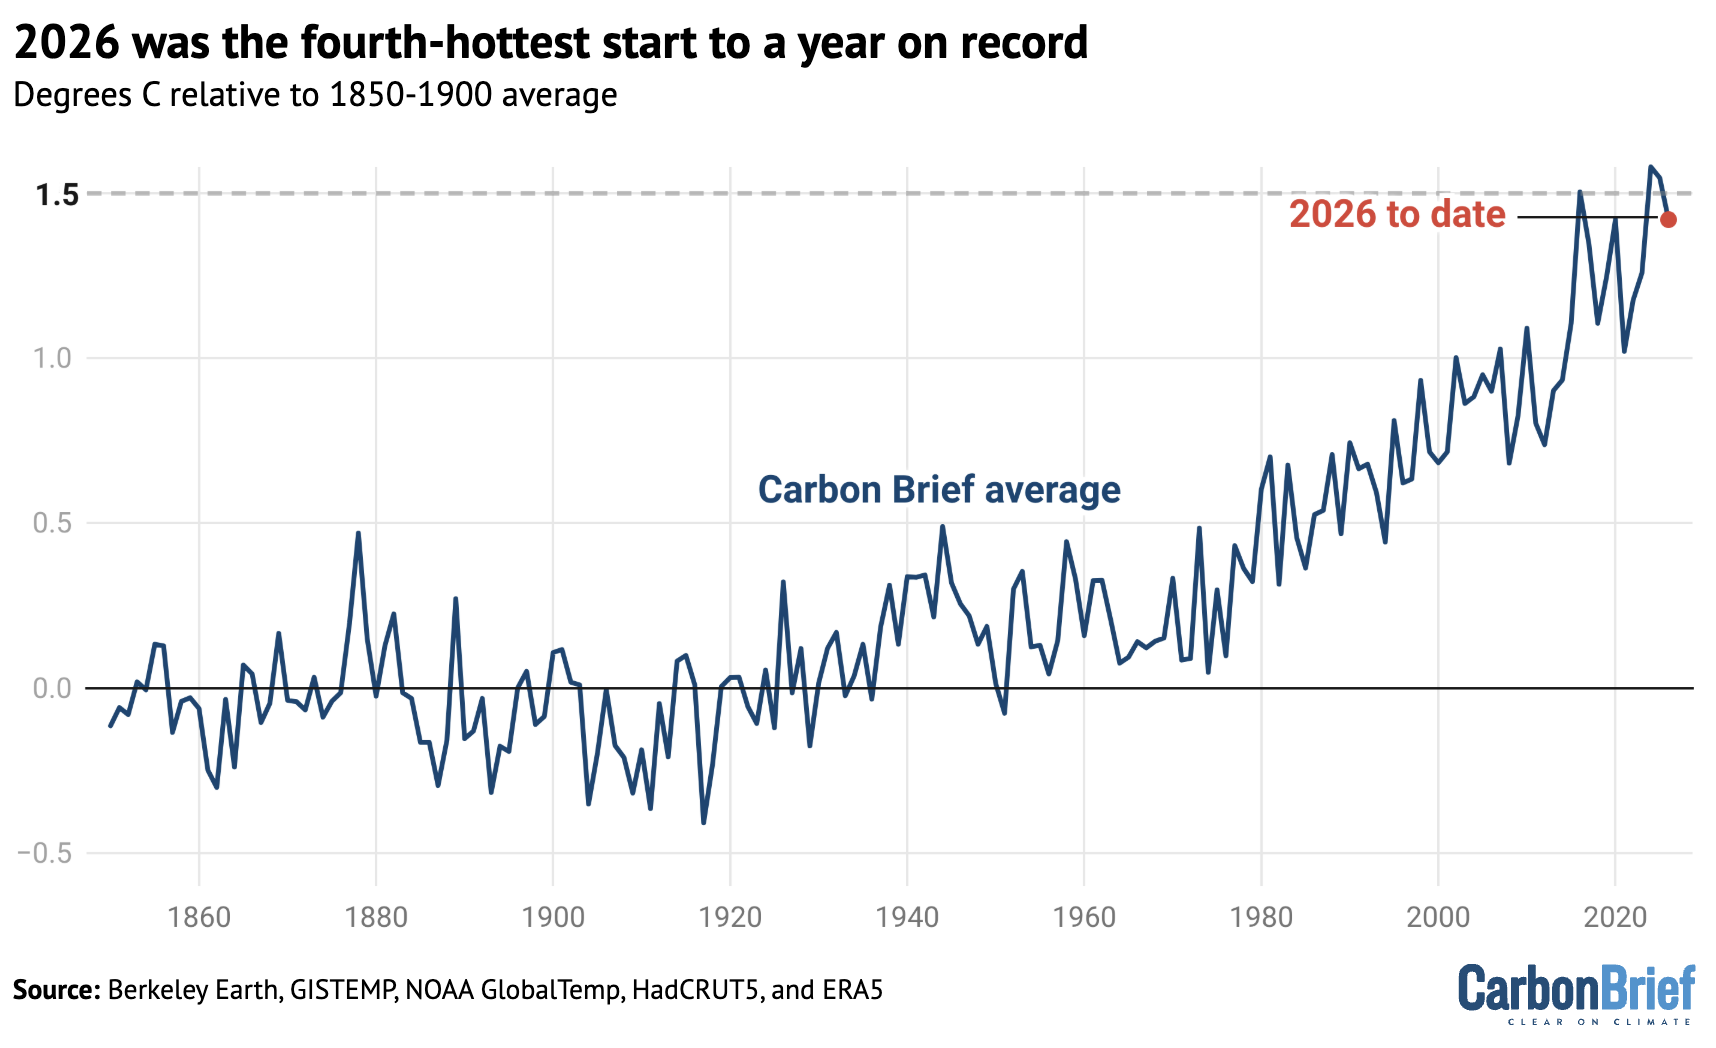
When combined, the first three months of the year in 2026 were the fourth-warmest in the historical record, below only 2024, 2025 and 2016.
A potential ‘super’ El Niño
There is reason to expect that global temperatures will continue to increase over the remainder of the year, as a strong – or even “super” – El Niño event is expected to develop later in the year.
Since the start of April, 13 different modelling groups have published estimates of future El Niño strength through at least September. These, in turn, contain 637 different model runs, as each model is run multiple times to better characterise the range of potential El Niño development.
There are a number of different ways to assess the strength of an El Niño or La Niña event.
The most common is the temperature anomaly in the “Niño3.4” region of the tropical Pacific. In addition, these temperatures have the human warming signal removed from changes over time in that part of the Pacific.
There are other approaches to assessing the strength of El Niño, including the newly released relative Oceanic Niño Index (RONI), which may be more accurate. However, RONI data is not readily available from all models today.
The figure below shows a distribution of Niño3.4 temperature anomalies across all of the runs of all of the models (top panel), as well as the range of runs across each of the individual models (bottom panel). Sustained sea surface temperatures in excess of 0.5C indicate an El Niño event, temperatures above 1.5C represent a strong El Niño event and above 2C is often referred to as a “super” El Niño event.

The latest climate models give a central (median) estimate of 2.2C warming by September – a scenario which would put the world firmly in “super” El Niño territory.
Warming would likely strengthen after September, as El Niño conditions generally peak between November and January.
However, there is still a wide spread among models, with some, such as CanESM5 and DWD, only showing a weak-to-moderate El Niño.
Historically, it has been hard to accurately forecast the development of El Niño during early spring, so it will be a few more months before scientists can be confident that a strong or super El Niño will develop.
Exceptional regional warmth
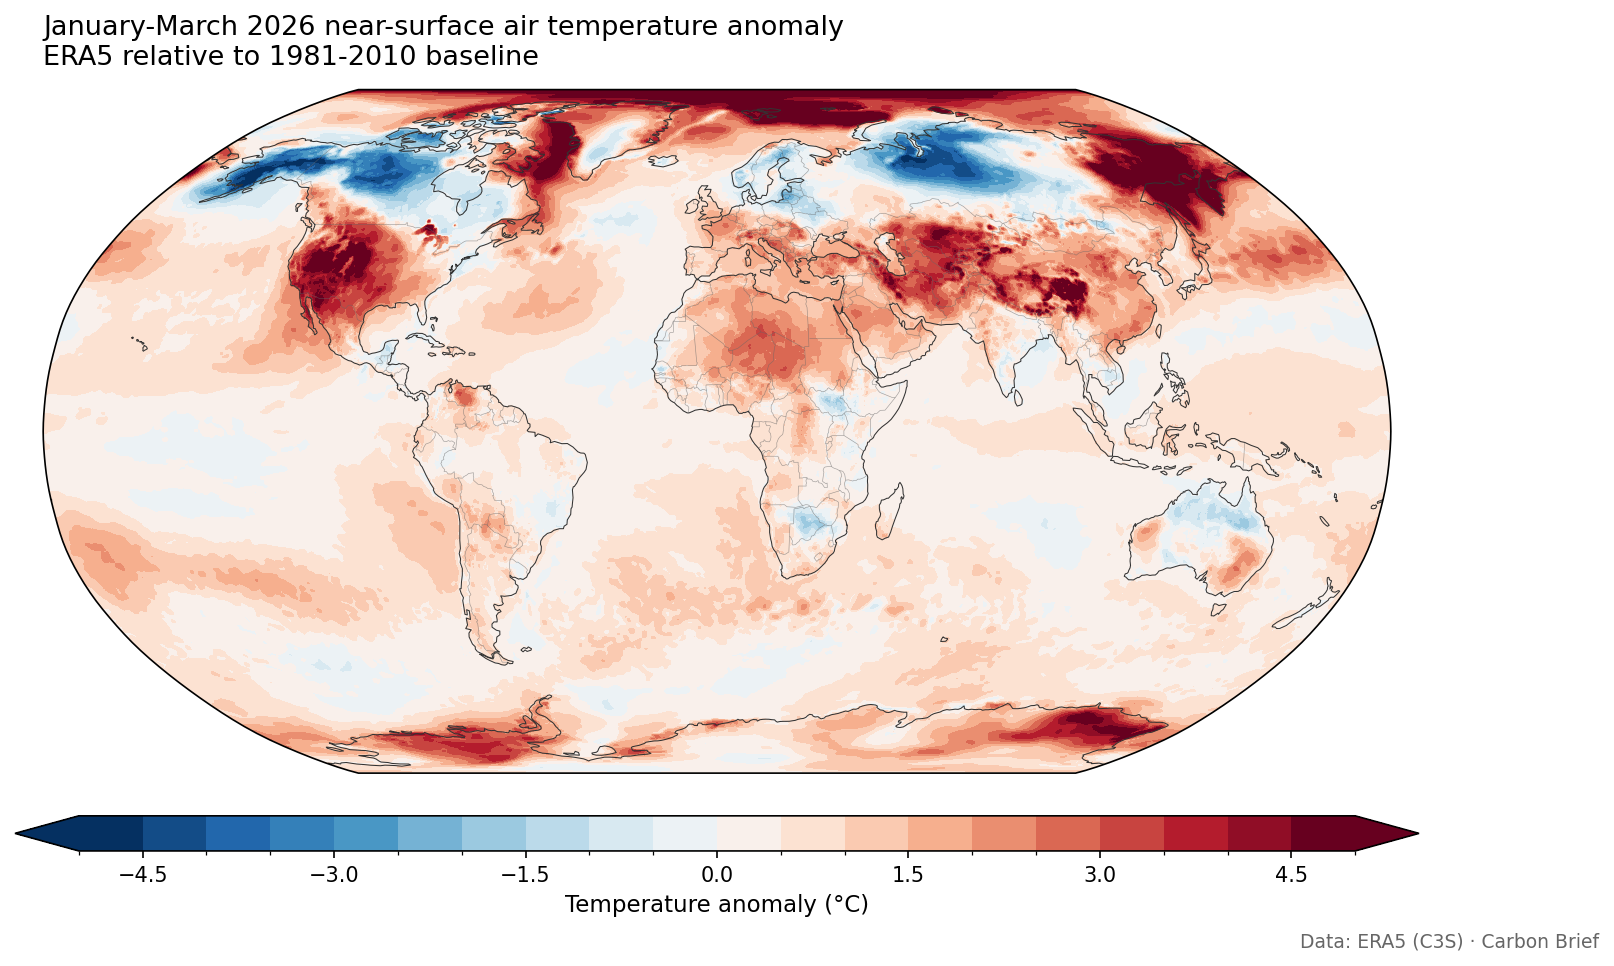
There were many regions of the planet that saw exceptional warmth in the first quarter of 2026. This includes much of the western US, western China and eastern Russia.
The figure below shows the temperature anomaly in the ERA5 dataset, relative to a more recent 1981-2010 baseline period. (ERA5 does not provide gridded data back to the pre-industrial era.)
In addition to temperature anomalies, it is useful to look at where new records have been set. The figure below shows each grid cell that saw one of the top-five warmest first-quarter periods on record, as well as the top-five coolest.
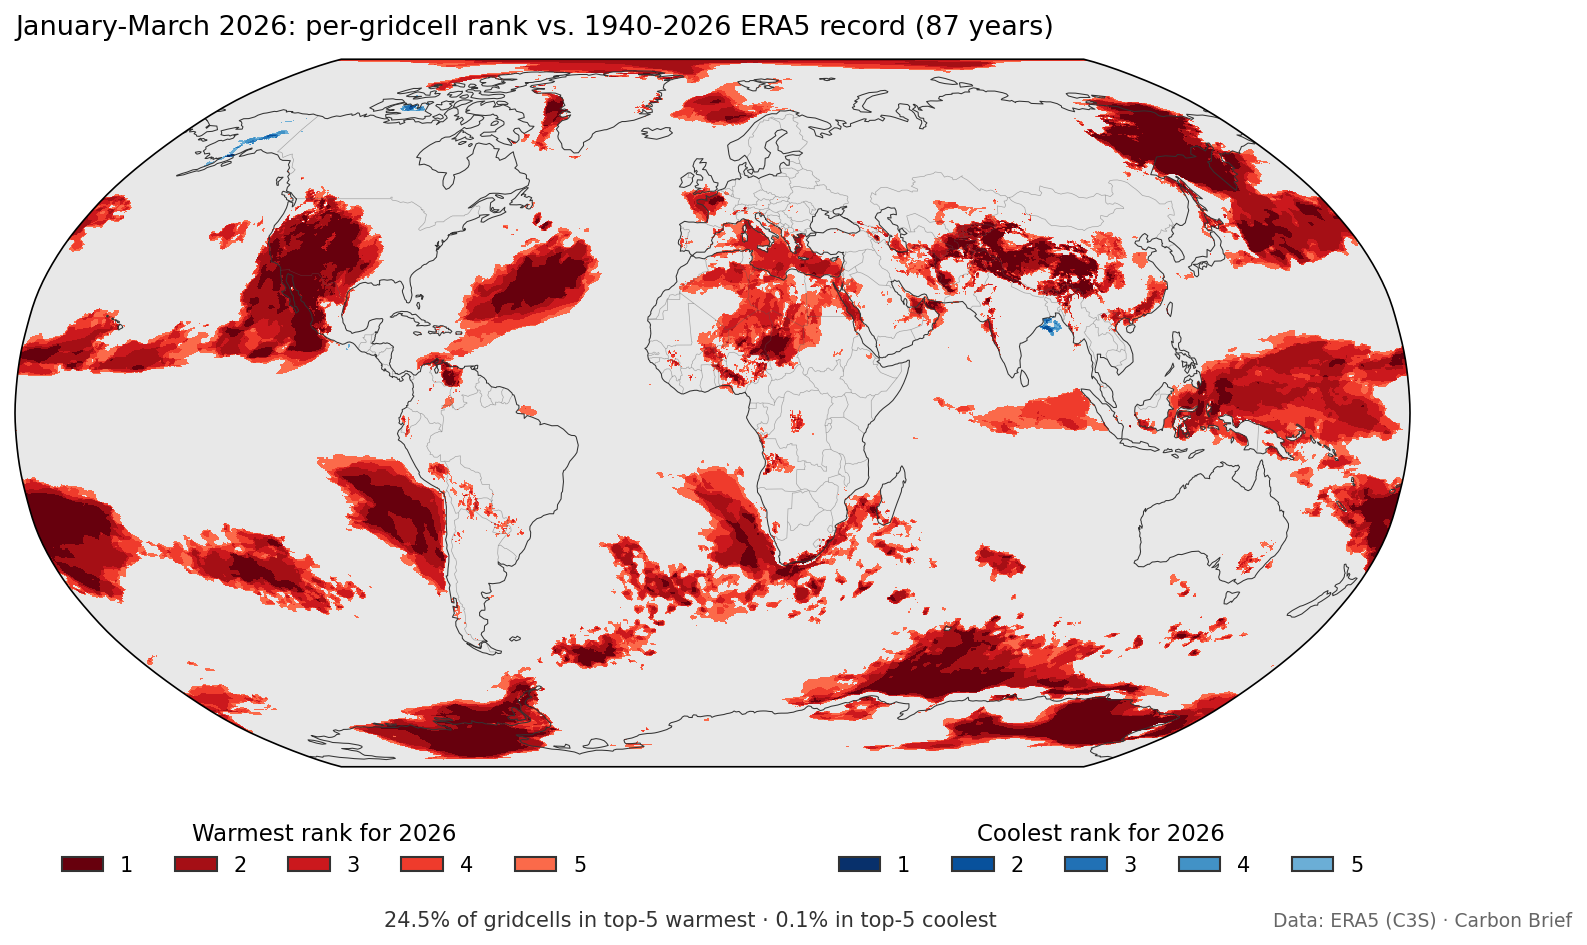
During the first quarter of 2026, 5.2% of the globe saw record warm temperatures, while virtually no place on earth had record cool temperatures. In addition, 24.3% of the globe was in the top-five warmest on record, whereas only 0.1% was in the bottom-five coolest on record.
On track to be second-warmest year on record
Carbon Brief estimates that the global average temperature in 2026 will be between 1.37C and 1.58C, with a best estimate 1.47C. This puts 2026 on track to likely be the second warmest year on record, though it could potentially be as high as the warmest or as low as the fourth warmest.
This is based on the relationship between the first three months and the annual temperatures for every year since 1970. The estimate also accounts for El Niño and La Niña conditions seen in the first three months of 2026, as well as how El Niño conditions are projected to develop across the rest of the year.
The analysis includes a wide range of possible outcomes in 2026, given that temperatures from only the first quarter of the year are available so far.
The chart below shows the expected range of 2026 temperatures using the Carbon Brief average of groups – including a best-estimate (red) and year-to-date value (yellow). Temperatures are shown with respect to the pre-industrial baseline period (1850-1900).
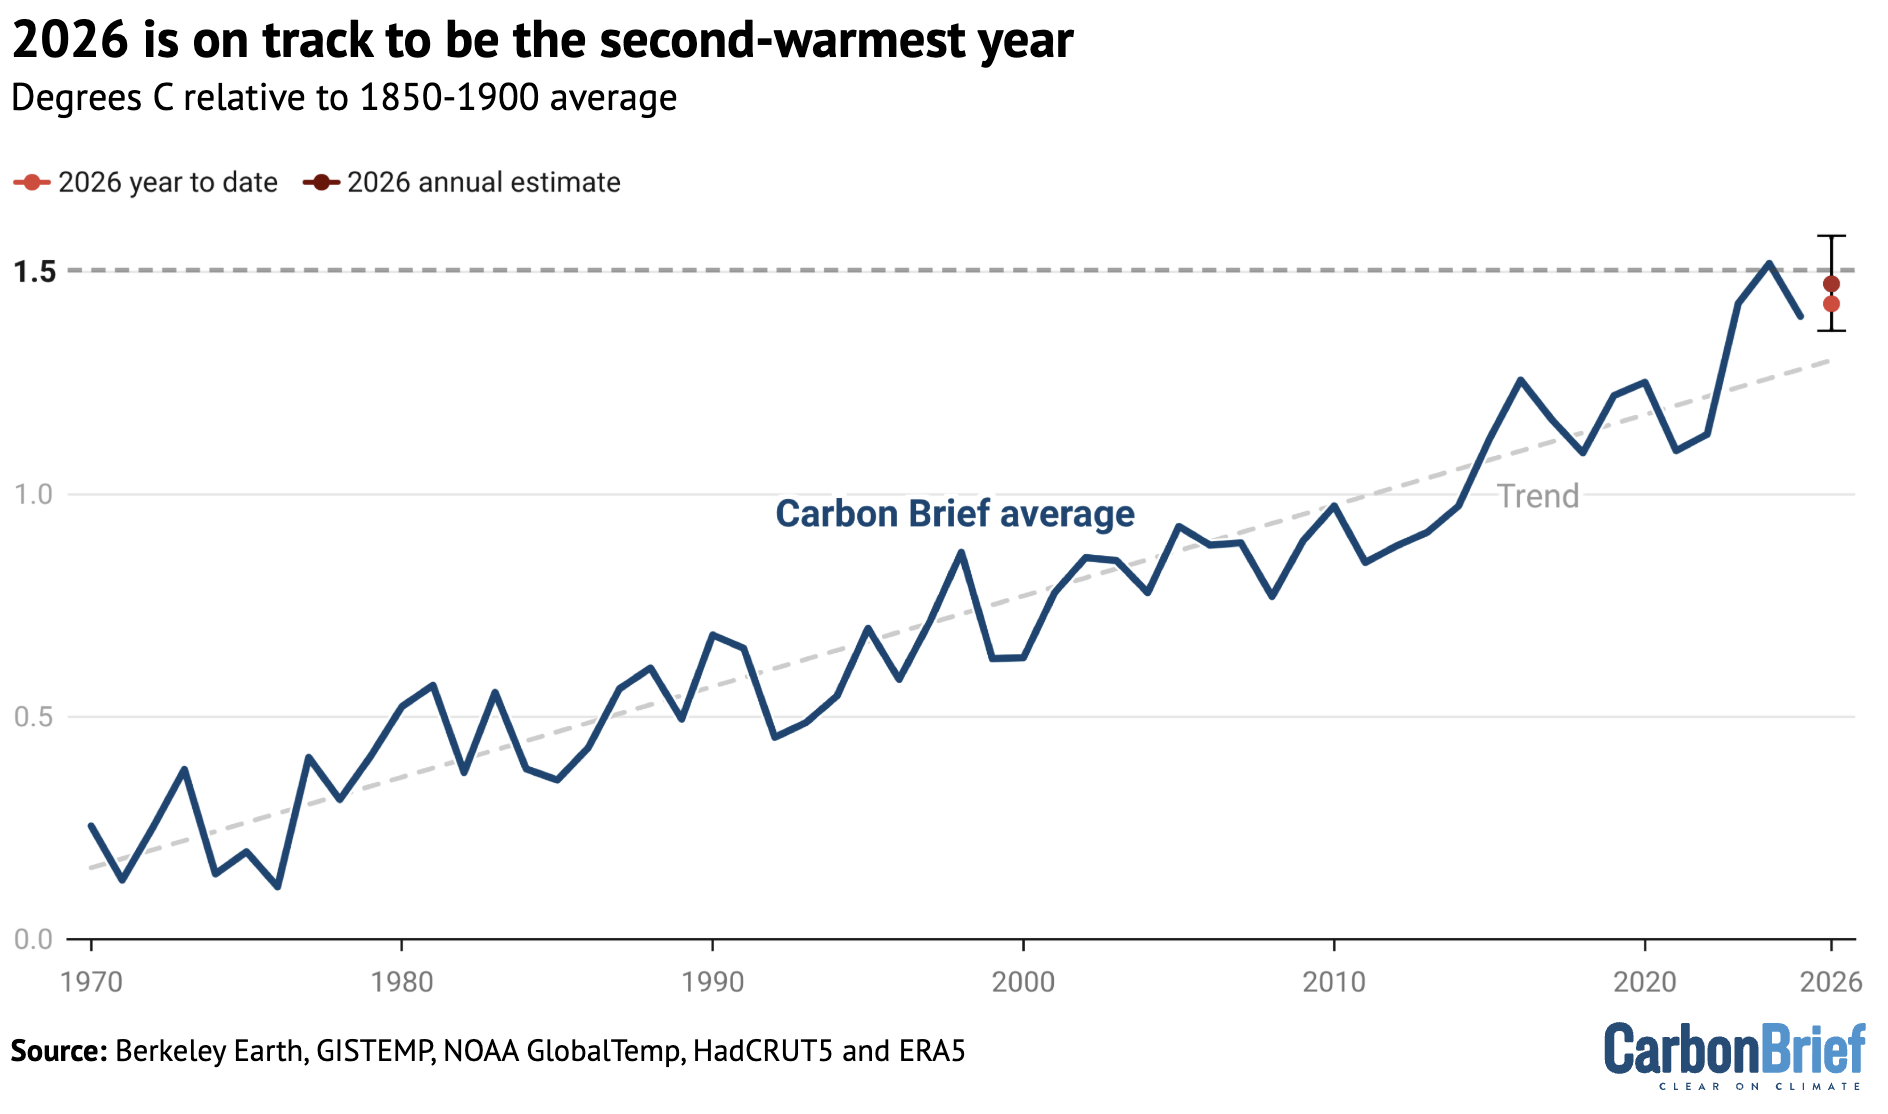
Carbon Brief’s projection suggests that 2026 is virtually certain to be one of the top-four warmest years, with a best-estimate – a 62% chance – that it ends up between 2024 and 2023 as the second-warmest year on record.
However, there remains a 19% chance that 2026 will be the warmest year on record – beating the prior record set in 2024. There is also a 19% chance that it will end up as the third- or fourth-warmest year.
The chances of a record-breaking year depends on the strength of El Niño, as well as how rapidly global temperatures warm up as El Niño develops.
There is also a roughly 30% chance that 2026 will be the second year that exceeds 1.5C above pre-industrial levels.
While the development of a strong or “super” El Niño will give a boost to 2026 temperatures in the latter part of the year, its largest effects will likely be felt in 2027.
Historically, the year where El Niño develops has been warmer than usual, but the year that follows the phenomenon’s winter peak – for example, in 1998, 2016 and 2024 – is record-setting.
This is because there is an approximately three-month lag between the peak of El Niño conditions in the tropical Pacific and the maximum global surface temperature response. If a super El Niño develops this year, it is likely that 2027 will set a new record.
Record-low winter Arctic sea ice
Earlier this year, Arctic sea ice saw the joint-smallest winter peak in a satellite record going back almost half a century.
Sea ice extent peaked for 2026 at 14.29m square kilometres (km2) on 15 March, marking a “statistical tie” with a record low recorded the year before, according to the US National Snow and Ice Data Center (NSIDC).
The figure below shows both Arctic and Antarctic sea ice extent in 2026 (solid red and blue lines), the historical range in the record between 1979 and 2010 (shaded areas) and the record lows (dotted black line).
(Unlike global temperature records, which only report monthly averages, sea ice data is collected and updated on a daily basis, allowing sea ice extent to be viewed up to the present.)
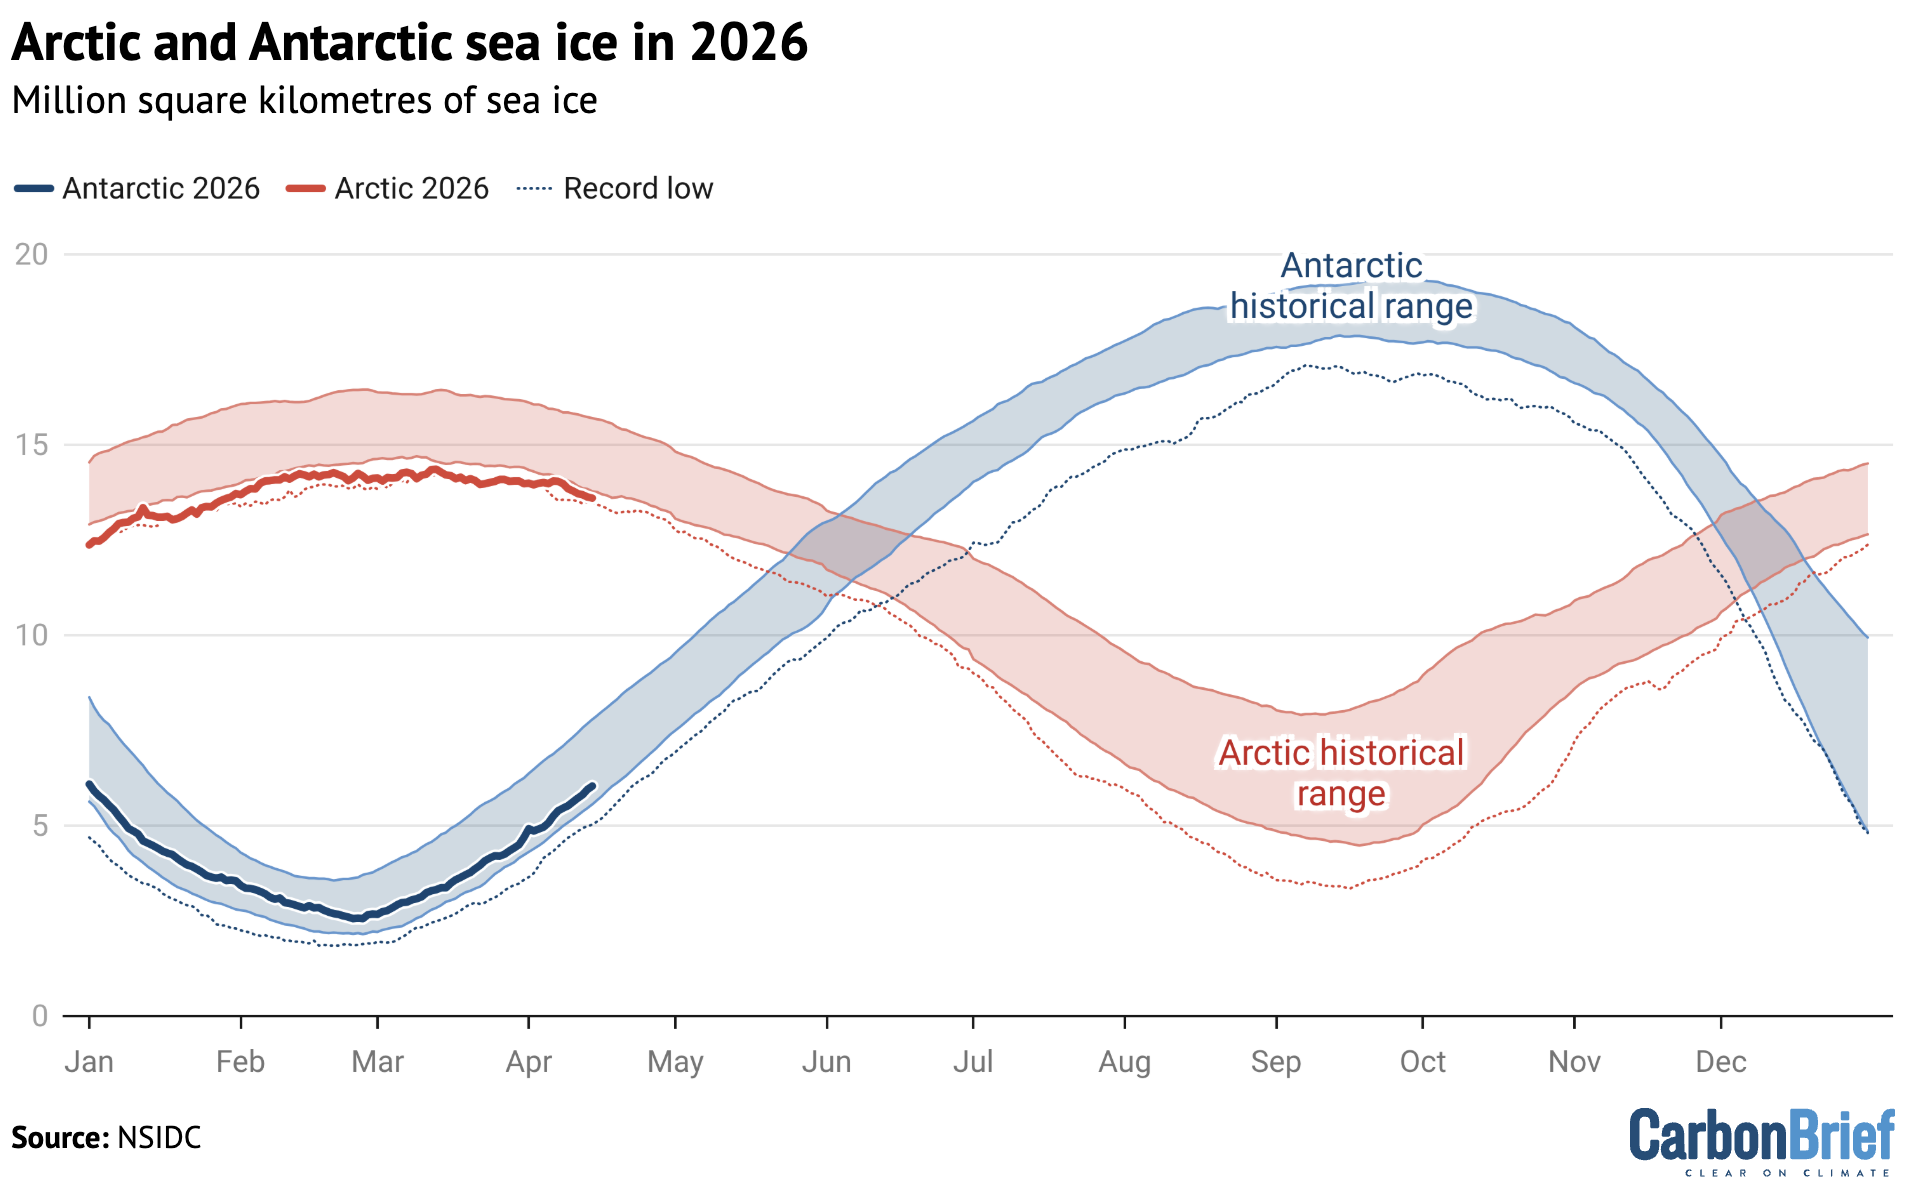
Arctic sea ice set new record daily low values during periods of January, March and early April. Antarctic sea ice did not set any new records so far in 2026, but remains on the low end of the historical (1979-2010) range.
The post State of the climate: Strong El Niño puts 2026 on track for second-warmest year appeared first on Carbon Brief.
State of the climate: Strong El Niño puts 2026 on track for second-warmest year

Global fossil-fuel emissions are set to fall by around 0.5% in 2026 amid the fallout from the Hormuz crisis, according to Carbon Brief analysis.
The US-Iran war has severely disrupted trade through the strait of Hormuz, causing a spike in oil and gas prices that continues to ripple around the global economy.
Each month of disruption – and each new flashpoint, such as in Yemen – is increasing the incentive to switch to alternatives.
Those alternatives include coal, with the latest forecasts pointing to a 1.2% rise in coal demand this year – apparently supporting media claims of a “return to coal” in the wake of the crisis.
Yet Carbon Brief’s analysis shows the rise in emissions associated with this increased coal use, much of which is unrelated to Hormuz, is set to be more than offset by declines for oil and gas.
The estimated overall impact on carbon dioxide (CO2) emissions from fossil fuels in 2026 is shown in the figure below and amounts to a reduction of around 0.5% from 2025 levels.
(Fossil fuels account for two-thirds of global greenhouse gas emissions.)
The emissions estimates for each fossil fuel are based on the latest forecasts from the International Energy Agency (IEA) for coal, oil and gas, in light of the ongoing global energy crisis.
For example, the agency initially estimated that global coal demand would decline this year. In its 2025 coal report, published in mid-December, it said that declining coal demand in China would outweigh the impact of pro-coal policies under US president Donald Trump.
In contrast, the latest update, published in September 2026, said that global coal demand would rise by 1.2% in 2026, instead of the small decline that had been expected.
The report highlighted the boost to coal demand from higher gas prices in the wake of Hormuz. However, there are limits to this, because few countries can switch from gas to coal at large scale.
The IEA’s latest report also noted the role of a strong El Niño, which is pushing up the need for cooling and depressing hydropower output in key markets. Other short-term factors are also affecting coal demand this year, including a rising amount of “wasted” wind and solar in China.
For gas, the IEA did not initially update its previous forecast that global gas demand would rise by 2.0% in 2026, which had been published in January of this year.
Its most recent forecast – published in July – already pointed to a 0.6% drop in demand in 2026. Since then, pressure on gas demand from high prices has only grown stronger.
For oil, there has been an even more dramatic shift in forecasts since the start of the year.
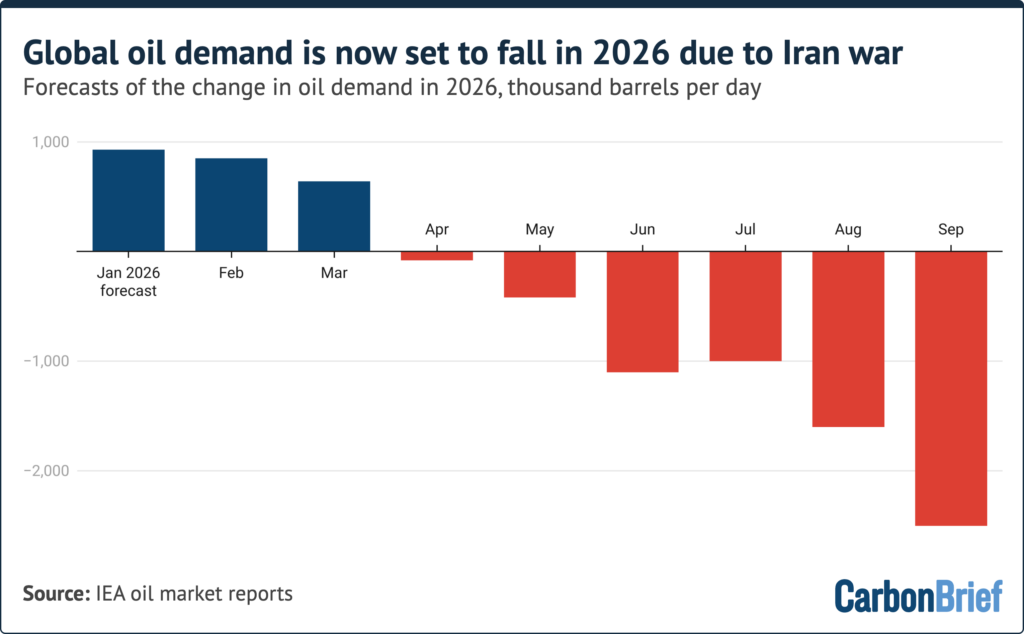
In its January 2026 oil market report, the IEA forecast a rise in demand in 2026 of 930,000 barrels per day (bpd). As shown in the figure below, this has been steadily revised downwards over the course of the year, as the Hormuz crisis was first ignited – and then extended.
By September, the IEA was forecasting a 2,500,000bpd drop in oil demand in 2026, equivalent to a reduction of 2.4% from 2025 levels.
(A 15 September research note from Morgan Stanley, not available online, found a “consensus” forecast of a 2,415,000bpd drop in demand in 2026.)
While there are many short-term factors at play in the shifting forecasts for 2026, it is clear that the latest energy crisis will also affect fossil-fuel demand in the next year and beyond.
For example, whereas the IEA initially forecast that oil demand would rebound in 2027 to well above 2025 levels, it is now expecting use of the fuel to be effectively flat for two years.
This puts a question mark over its previous expectation – published in October last year – that global oil demand would not peak until as late as 2030.
“For every month the conflict lasts, the probability of permanent [oil] demand destruction increases,” wrote Sverre Alvik, vice president at consultancy DNV in a late August analysis.
As fuel prices have surged, electric vehicles (EVs) have captured record shares of major car markets, from Australia and China through to Europe, Indonesia and Thailand.
In July, EV sales nearly doubled year-on-year in “new markets”, noted Alvik, pointing to countries outside China, Europe and North America.
The IEA says the 2027 outlooks for coal and gas are interdependent, with coal demand potentially increasing again if gas prices remain elevated – or dropping back if gas prices ease.
At the same time, governments in countries that had planned to rely on imports of liquefied natural gas (LNG) have been signalling shifts towards favouring domestic clean energy instead – or continuing to use coal for longer.
The current crisis, therefore, has the potential to not only lower fossil-fuel use and emissions in the short term, but also on a more lasting basis.
Related
CCC: Heathrow expansion could push flights to ‘80% of UK emissions by 2050’
Analysis: China’s CO2 emissions fall in Q2 2026 due to plummeting oil use
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
Q&A: What do China’s provincial five-year plans say about climate and energy?
The post Analysis: Global fossil-fuel emissions set to fall in 2026 amid Hormuz crisis appeared first on Carbon Brief.
Analysis: Global fossil-fuel emissions set to fall in 2026 amid Hormuz crisis
Aviation is on track to be responsible for 80% of the UK’s carbon dioxide (CO2) emissions by 2050, according to the Climate Change Committee (CCC).
Emissions from flying have more than doubled since 1990 – driven by rising passenger numbers – even as the climate impact of every other sector in the UK economy has fallen.
The UK does not have “credible” policies in place to reverse this trend of rising emissions, says the CCC in new advice to the government on future aviation policy.
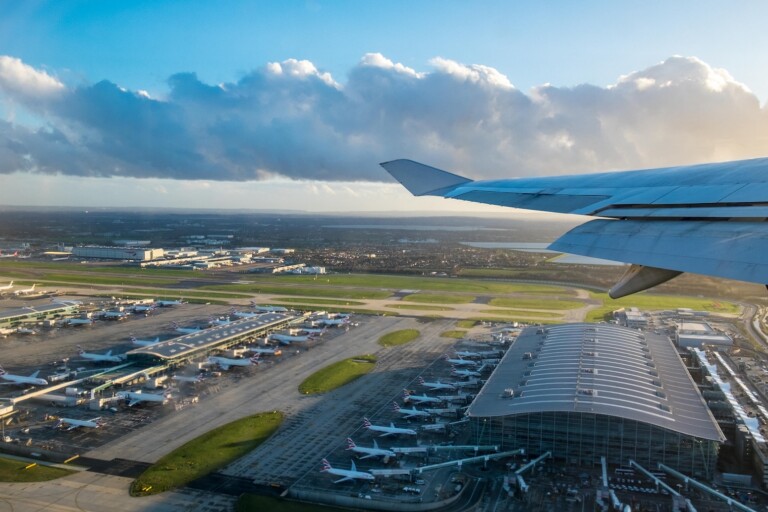
The government has signalled its support for expanding Heathrow, the nation’s largest airport, while relying on “techno-fixes” such as “sustainable aviation fuels” (SAFs) to cut emissions.
Yet, even without Heathrow expansion, the CCC says aviation emissions are on track to be higher in 2050 than they are today – reaching 38m tonnes of CO2 (MtCO2).
As the chart below shows, this would account for most of the remaining CO2 from the UK economy, all of which would need to be removed from the atmosphere in order to meet the legal target of net-zero emissions.
Expanding Heathrow would add another 2.4MtCO2 in 2050, amounting to around 5% of all the UK’s emissions. (This would increase to 4.5MtCO2 when expansion is complete in 2054.)
With a final decision on Heathrow expansion expected by 2029, the government asked the CCC for its advice on whether the plan is compatible with the UK’s climate targets.
The CCC has concluded that the UK simply lacks sufficient policies to reduce aviation emissions and “expanding Heathrow would compound the problem”. In a press briefing, CCC chair Nigel Topping told journalists:
“The UK does not currently have a credible plan to reduce [aviation emissions] in line with net-zero, so that creates a serious challenge for meeting our climate commitments.”
The “jet-zero strategy”, launched by the previous Conservative government in 2022, set out plans to cut aviation emissions. However, the Labour government has since accepted that the strategy’s expectations for SAFs, electric planes and fuel-efficiency improvements were unrealistic.
The CCC says a “credible and robust net-zero policy framework for aviation” should be set out in a revised strategy, which is planned for 2027. Only then could Heathrow expansion be aligned with the net-zero goal, adds the committee.
As part of this new strategy, the CCC says the “aviation sector needs to take responsibility for its emissions”. It says policies should be designed based on the “polluter pays” principle, requiring the aviation industry to fund its own SAFs and CO2 removal.
Specifically, the committee says funding will be needed for “engineered removal” technologies, such as direct air carbon capture and storage (DACCS).
These technologies are currently “not yet available at the scale required”, but are vital for the kind of permanent CO2 removal needed to mop up aviation emissions, says the CCC.
(“Natural solutions” such as tree planting are the other main way CO2 is expected to be removed from the atmosphere. However, the CCC envisages these removals offsetting the remaining methane emissions from livestock agriculture in the UK, whereas it says “engineered removals” would be required to remove and store CO2 from flights.)
The CCC acknowledges that placing decarbonisation costs on airlines would likely lead to higher ticket prices. It estimates that this could mean an increase, in 2024 prices, of around £150 for a return trip to Alicante, Spain, and £400 for a return trip to New York by 2050.
However, it says this is preferable to a public spending approach, which would result in the roughly 50% of the population who do not fly paying for flight-related CO2 removals.
In addition, the committee notes that higher costs would help to manage demand for flights, which would otherwise be expected to increase considerably over the coming decades.
related
The post CCC: Heathrow expansion could push flights to ‘80% of UK emissions by 2050’ appeared first on Carbon Brief.
CCC: Heathrow expansion could push flights to ‘80% of UK emissions by 2050’
A fifth of the world’s greenhouse gas emissions are linked to international trade in goods and services, a new tracker shows, spotlighting a little-studied issue that researchers say should be tackled by the UN climate process.
Currently, as part of the Paris Agreement, every country is responsible for counting and reducing the planet-heating emissions that are produced within its territory. Manufacturing countries, for example, may have high emissions even if what they make is exported for consumption elsewhere.
But new analysis from the European Climate Foundation (ECF) and climate consultancy Matière, based on the tracker’s data, shows that some countries have a high footprint of “imported emissions” from goods and services they ship in. These emissions are often ignored in the places where the products are consumed because they are not formally counted under greenhouse gas inventories.
In the European Union, for example, while domestic emissions have declined since 2015, imported emissions have remained unchanged, the analysis shows. In some countries, like Austria or Sweden, they are as high as the country’s entire annual carbon footprint.
-
Türkiye says it has “final decision” at COP31 despite Australia running negotiations
COP31 President-Designate Murat Kurum told journalists that, while the two countries have been working well together, Türkiye has the final say over the Antalya summit -
As science comes under attack at UN talks, climate movement splits over how to respond
A rift over how IPCC messages are produced and turned into policy is creating tensions in the world’s most influential coalition of climate NGOs

Former EU lead climate negotiator Jacob Werksman said that under the Paris Agreement, these traded emissions are accounted for in the countries where they are originally produced, but importing countries can also take responsibility for their consumption.
“It starts with a wide recognition by many jurisdictions around the world that we need to know the carbon content of these products, and we then need to agree what is a fair, effective, transparent and relatively easy-to-implement way of measuring that carbon in traded products,” he told a launch event for the trade emissions tracker, which contains data for different countries, sectors and gases.
Trade and its role in addressing climate change has become a higher priority at UN climate talks after a push led by emerging economies including China, India and South Africa led to the first trade and climate change dialogue held this year at the mid-year session in Bonn.
At the upcoming COP31 UN summit in Antalya, some voluntary initiatives like the Brazil-led Integrated Forum on Climate Change and Trade are expected to continue, but the issue does not feature in Türkiye’s Action Agenda of climate initiatives and formal negotiations are not scheduled on the topic.
China: the world’s top emissions exporter
As a manufacturing powerhouse, China ranks first in the new tracker as the world’s top-emitting country, but the data shows that a large chunk of the country’s carbon emissions – an amount larger than Brazil’s entire annual carbon footprint – are linked to products that are exported and consumed abroad.
Russia, Brazil, the US and the EU rank as the top destinations for Chinese trade-related emissions, which are mostly linked to components for power generation, basic metals like copper and lead, and non-metallic minerals like graphite and phosphorus.
Yet China is also the world’s top emissions importer, related mostly to agricultural products, fossil fuels and minerals brought from the US, the EU, Japan and India, among others. The US ranks second by a close margin, with both countries importing about 1.6 billion tonnes of CO2 equivalent.
China’s industrial engine starts to break its fossil fuel habit
Richard Baron, ECF’s industrial policy and trade director, said Chinese clean energy products are key for reducing emissions around the world, adding that Europe is “not able to do without those technologies” for its energy transition.
“China has an emissions trading system that counts CO2 differently there. But if China and the EU were to agree on some kind of translation mechanism to say ‘this is how we measure it’, and companies can understand the protocol to navigate both markets, that would set the tone for a lot of other conversations,” he said at the platform’s launch event last week.
The analysis suggests that if the EU and China aligned their climate requirements for products, the resulting standards could influence trade flows representing about 7% of global emissions.
Baron said there’s “a plethora” of multilateral spaces to hold these discussions, including the climate and trade dialogue at the UN climate talks or the Climate Club at the Organisation for Economic Co-operation and Development (OECD), which seeks to cut industrial emissions.
Trade breaks into agenda of UN climate talks – but will it have teeth?
Controversial trade measures
Instruments like the Europe’s Carbon Border Adjustment Mechanism (CBAM) – a recent piece of legislation that penalises emissions-heavy imported products – are one tool that could be used to address trade-related emissions, said Antoine Oger, executive director at the Institute for European Environmental Policy.
He said a significant portion of imported emissions in Europe are already covered by CBAM, as it includes sectors like cement, iron and steel, fertilisers and aluminium. This then allows the EU “to engage in constructive dialogue with our trade partners”, he added.

But across diplomatic summits, including at UN climate talks, emerging economies have pushed back heavily against the CBAM and other trade measures. The most recent BRICS declaration adopted on Saturday by 11 such countries – including China, India and Russia – condemns “protectionism under the guise of environmental objectives”.
The declaration calls for the “elimination of such unlawful measures”, which they argue have “far-reaching negative implications for the human rights, including the rights to development, health and food security” of vulnerable communities.
“The question of responsibility is a political question,” Oger said. “These emissions exist – they are emitted somewhere to make a product that will be consumed elsewhere. So you can debate responsibility but the idea is for the two parts to recognise there’s a problem.”
The aim, he added “is not to point fingers, but to accept this is a reality of our emissions profiles and ask what we can do about it”.
The post International trade linked to 20% of global emissions – but imports ignored appeared first on Climate Home News.
International trade linked to 20% of global emissions – but imports ignored



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits