

The World Bank and International Monetary Fund (IMF) held their spring meetings last week in Washington DC – a key event in a critical year for international climate finance.
As the two so-called Bretton Woods institutions mark their 80-year anniversary, they are under growing pressure to reform and deal with the “polycrisis” enveloping the world.
Many developing nations are struggling with growing food insecurity, income inequality and massive debts that are taking up much of their resources.
All of this is making it harder than ever for them to invest in low-carbon energy or prepare their citizens for the growing threat of climate change. At the same time, some wealthy countries have been scaling back their foreign-aid spending.
While the two financial institutions are undergoing reforms, including changes designed to help them tackle climate change, progress so far has been slow.
Developed countries pledged $11bn at the spring meetings to help boost the World Bank’s lending capacity. However, calls for new funds and debt relief for the world’s poorest countries remained largely unanswered.
In this Q&A, Carbon Brief explains the key outcomes from the spring meetings. The Q&A also looks ahead to the COP29 climate summit in Azerbaijan, where countries are due to agree on a new climate finance target.
- Why are the World Bank and IMF spring meetings important for climate action?
- Are countries giving the World Bank more climate finance?
- What is the World Bank doing to ‘unlock’ more money?
- Did the spring meeting provide any debt relief for climate-vulnerable countries?
- Did leaders decide on ‘innovative’ new sources of climate finance?
- What comes next for global financial system reform?
Why are the World Bank and IMF spring meetings important for climate action?
Developing countries need large sums of money to address the climate and development challenges that they face.
An assessment by the Independent High-Level Expert Group on Climate Finance (IHLEG) in 2022 concluded that developing and emerging countries – excluding China – need to invest $2.4tn every year, by 2030, to meet their climate goals. This amounts to a fourfold increase from current levels.
(In the report, China is considered alongside the “advanced economies” of Europe, North America and East Asia and the Pacific that see the majority of global climate investment.)
The same group stated that insufficient investment, particularly in emerging and developing economies, was the “primary reason” that the world was “badly off track” on the path to its Paris Agreement targets.
Meanwhile, the world’s poorest countries are facing what the World Bank has described as a “great reversal”, with surging debt distress, food insecurity and income inequality increasing since the Covid-19 pandemic. This “polycrisis” makes it harder for them to address climate change.
Multilateral development banks (MDBs) distribute billions of dollars to developing countries every year, largely as loans. These banks are widely viewed as vital for expanding international climate finance and, as the largest MDB, the World Bank is expected to play a key role.
MDBs provided a record $60.9bn of climate finance to developing countries in 2022. However, IHLEG estimates that raising $2.4tn of investment for such nations would require around $250-300bn annually, by 2030, from MDBs and other development finance institutions.
Meanwhile, the IMF – which also lends money, but with a focus on financial stability rather than development – could play a vital role in aiding debt-laden countries that are also facing severe climate hazards.
Over the past year, the World Bank has been undertaking reforms as part of its “evolution roadmap” to increase its spending in developing countries, including more money for climate-related projects.
This came amid a broader push by a group of global-north and global-south nations for reforms to the international financial system – in part to scale up climate finance.
Progress has been slow. One review by the Centre for Global Development concluded that only one-fifth of the required reforms have been implemented by the World Bank so far and, in general, there has been uneven progress across the MDBs.
The spring meetings provided an opportunity for leaders to discuss the status of these activities and push for more progress.
Yet there remains a great deal of mistrust around the role of these institutions in addressing climate change from those who view them as complicit in many of the problems facing developing countries.
“The IMF, as well as the World Bank, contribute greatly to the economic entrapment of the global south,” Dr Fadhel Kaboub, a senior advisor at the thinktank Power Shift Africa, told a press briefing ahead of the spring meetings.
Issues highlighted by campaigners include what they regard as the IMF’s punitive policies for debt-laden countries and the World Bank’s continued financing of fossil-fuel projects.
Finally, the COP29 climate summit in Baku, Azerbaijan, at the end of this year is expected to be the “finance COP”, with nations set to agree on a new climate-finance target to support developing countries.
Writing ahead of the spring meetings, Danny Scull, senior policy advisor for public banks and development at the thinktank E3G, explained that the spring meetings “will set the tone for a key year of transforming the international finance system, which is not limited to these DC-based institutions”.
Are countries giving the World Bank more climate finance?
At the end of this year, wealthy countries are due to “replenish” the International Development Association (IDA) – the arm of the World Bank that provides concessional and grant-based finance to the world’s poorest nations.
Given the challenges ahead, World Bank president Ajay Banga has stated that this replenishment should be the “largest of all time”, calling for $30bn in pledges. Such a commitment would allow IDA to lend more than $100bn.
Much of this money would be climate finance, as the World Bank has pledged to spend 35% of its funds on climate-related projects, rising to 45% by 2025.

Country surveys suggest that IDA funding tends to be well received by developing nations, compared to other sources of funding. However, developed countries such as the US and Germany have reduced their IDA pledges in recent years. Many have cut the foreign aid budgets from which their IDA contributions are drawn.
The last IDA contribution by the UK for example, was less than half its previous one. The government stated in 2022 that it planned to spend more on direct country programmes in order to “control how exactly taxpayers’ money is used to support our priorities”.
Some nations, such as the US, have stressed the need for the World Bank to do more with its existing resources, rather than relying on new investments from donor countries. (See: What is the World Bank doing to ‘unlock’ more money?)
According to the thinktank E3G, an “ambitious” IDA replenishment by wealthy nations would go some way to “re-establish[ing] trust with developing countries” – particularly those in Africa, where more than half of the IDA-eligible states are located.
A report released by the G20 Independent Expert Group last year describes IDA as “the largest source of long-term, cheap financing to low-income countries”, but adds that it is currently “too small to properly address the needs for [climate] adaptation, resilience and mitigation”.
The group therefore recommends a tripling of finance from IDA. This would require a “sharp” increase in contributions from donor countries.
The spring meetings provided a space for discussion of IDA replenishment, which Banga made clear was one of his priorities. A replenishment meeting taking place the week after the event is expected to provide more clarity on how much countries will donate.
What is the World Bank doing to ‘unlock’ more money?
The World Bank is under pressure to change the way it operates and assesses risk in its lending, in order to “unlock” more money from existing funds.
In 2022, an influential report for G20 finance ministers into “capital adequacy frameworks” highlighted measures that it said could unlock “several hundreds of billions of dollars” in extra lending from MDBs.
Crucially, the expert group said this could be done without threatening the financial stability or credit ratings of these banks.
The World Bank has already announced various measures over the past few months to boost lending. However, observers say further steps are needed.
A study by the consultancy Risk Control, which assessed the impact of the G20 report’s proposals, concluded that they could unlock an extra $162bn in lending over a decade from the International Bank for Reconstruction and Development (IBRD) – the arm of the World Bank that focuses on middle-income countries.
It also concluded that the reforms could free up an extra $27bn in lending from the IDA.
Speaking to journalists during the spring meetings, Banga said that the World Bank was working through 27 recommendations from the G20 report that apply to the institution.
Franklin Steves, a senior policy adviser in sustainable finance at E3G, tells Carbon Brief that rapid progress was not expected at the meetings:
“There are lots and lots of political, but also legal and technocratic, issues around how the bank and also the other MDBs can implement those measures. They are going to take a lot of time to work through.”
Nevertheless, the spring meetings did see some progress in the World Bank’s reforms programme. Rich countries pledged a total of $11bn towards new instruments that the World Bank has set up as part of its effort to increase lending capacity.
The US, France, Japan and Belgium committed funds to the portfolio guarantee platform. This money will be available to pay off borrowers’ debts if necessary, allowing the World Bank to lend money more freely.
Separately, a group of countries including Germany, Denmark and the UK contributed to the World Bank’s hybrid capital mechanism. This allows shareholders to raise new funds by investing in special bonds from the bank.
According to the World Bank, in total these additional funds will allow it to lend an extra $70bn over the next 10 years.
Generally, the spring meetings also highlighted the World Bank’s interest in working more with the private sector to mobilise finance for renewable energy and other key investments. In an interview with Agence France-Presse, Banga said:
“The reality is that that gap between tens and hundreds of billions to trillions is not a number that the bank can fill…That’s why you do eventually need the private sector.”
The World Bank president’s language mirrors that of other leaders, such as former US climate envoy John Kerry, who has stated repeatedly that “no government in the world” has enough funds to address climate change on its own.
Banga said the bank was working to address regulatory uncertainties in developing countries, foreign currency risk and protecting private investors from war and other unrest.
At the spring meetings, the bank also launched a new partnership with the African Development Bank and private partners to provide 300 million people in Africa with access to electricity by 2030.
This approach has faced criticism from campaigners, who argue that the private sector has so far failed to mobilise significant climate finance for developing countries.
A report from the Bretton Woods Project launched just before the spring meetings concluded that creating “bankable” low-carbon projects in developing countries is “far from straightforward”. It also noted that ensuring such bankability can clash with the interests of citizens in those countries and jeopardise a “just energy transition”.
Did the spring meeting provide any debt relief for climate-vulnerable countries?
Just ahead of the meetings, Bulgarian economist Kristalina Georgieva was chosen for another five-year term as the IMF managing director. Her reappointment comes at a fraught time for the institution, as the world faces a mounting global debt crisis.
This issue is rising up the global agenda, with newspaper editorials and prominent figures calling for action to help debt-laden developing countries.
Around 60% of low-income nations are trapped in a cycle of paying off debt, which was exacerbated by borrowing during the Covid-19 pandemic and a surge in interest rates.
Developing countries spent $443.5bn on servicing their debts in 2022. Analysis by the ONE campaign concluded that, as of 2024, more money is flowing out of developed countries to service their debts than is flowing into their governments from external sources.

Many countries, particularly in Africa, are spending more on interest payments than on healthcare, education or climate action. This is particularly problematic for debt-laden nations – such as Malawi – which are dealing with climate-driven disasters and need to spend money on recovery and adaptation.
Analysis by the Debt Relief for Green and Inclusive Recovery (DRGR) project found that among 66 of the world’s most economically vulnerable nations, 47 will likely face insolvency in the next five years if they invest the amounts required to meet their climate and development goals.
Many civil society groups blame the IMF for contributing to these issues. Its approach of encouraging austerity policies so that countries can pay off debts has been responsible for “keep[ing] developing countries in a cycle of crisis”, according to a statement released by ActionAid USA country director Niranjali Amerasinghe.
Moreover, according to E3G, the role of the US Federal Reserve in increasing borrowing costs and the failure of wealthy countries to provide debt relief has been “tremendously
corrosive to trust” with developing countries.
Ahead of the spring meetings, civil society groups and academics called for major interventions to address these issues, such as the immediate cancellation of public debt payments for African countries and the “urgent reform” of the G20 “common framework”.
Wealthy creditor nations in the G20 established the common framework in 2020 to help coordinate the restructuring of debts. However, despite the high demand, only four developing countries have used it so far and it has been widely dismissed as inadequate.
Marina Zucker-Marques, a senior academic researcher in global economic governance at the Boston University Global Development Policy Center, tells Carbon Brief:
“What is happening today is that countries are defaulting on their development priorities and climate priorities instead of defaulting on their debt.…[They are] doing this because it’s very difficult to get your debt restructured within the common framework.”
One issue is debt sustainability analysis, which is meant to guide the borrowing decisions of low-income countries. As it stands, this calculation of how much money countries can pay towards their debt obligations does not account for their social, development and climate needs.
At the spring meetings, the IMF and the World Bank started discussions of how to reform this analysis to account for climate action and other issues. “This is a welcome path, but it’s something that is going to take two or three years to have a result,” Zucker-Marques explains.
The meetings also saw the launch of an independent review into the links between sovereign debt, nature and climate change, which will consider potential solutions such as debt for nature or climate swaps.
Did leaders decide on ‘innovative’ new sources of climate finance?
Raising the large sums of money required to tackle climate change is expected to involve tapping new sources of finance. Some of these sources were discussed during the spring meetings.
Representatives from a small group of global-north and global-south countries met on the sidelines of the event in the second ever in-person meeting of the international tax task force.
The goal of this initiative is to analyse and design new forms of taxation that could be used to raise money for climate and development needs. Options being considered include taxes on fossil-fuel producers, shipping fuel, air travel and financial transactions.

The group, co-chaired by France, Barbados and Kenya, was joined by Colombia at the event, bringing its total membership up to eight.
Kenyan climate change envoy Ali Mohamed said in a statement that their goal was to “raise much needed financing to tackle climate change while having minimal impact on ordinary people”.
The task force’s ambition is to present one or more options for taxes at COP30 in 2025, with the goal of gathering a coalition of nations that would be willing to implement them. It will present its initial findings at COP29 in Baku.
Meanwhile, there was growing momentum around the idea of a global tax on billionaires, in part to pay for climate action. A “wealth tax” of 2%, which could raise $250bn each year, was initially proposed by G20 chair Brazil in February, but received support from other leaders at the spring meetings, including IMF head Georgieva.
The concept will be developed further and presented at a G20 meeting of finance ministers and central bankers in July.
Finally, there was a lot of pressure from NGOs at the spring meetings to shift World Bank finance away from fossil fuels and into low-carbon energy sources. Three US senators also issued a public letter to Banga asking him to commit to ending fossil-fuel financing.
Oil Change International analysis shows that the bank was providing roughly $1.2bn a year to fossil fuel projects in developing countries, between 2020 and 2022. This is in spite of the World Bank committing to “align” all of its lending with the Paris Agreement as of July 2023.
Paola Yanguas Parra, a policy advisor at the International Institute for Sustainable Development, tells Carbon Brief that current geopolitics are making calls to end fossil-fuel financing harder. “There is a lot of ‘gas as transition fuel’ and ‘gas as development’ being supported [by the World Bank],” she says.
In the end, there was no commitment from the World Bank to change its policies on fossil-fuel financing.
What comes next for global financial system reform?
This year is set to be a critical milestone for international climate finance.
When nations gather in Baku for COP29 in November, they will decide on a “new collective quantified goal” for providing climate finance to developing countries. This will replace the $100bn annual goal, which developed countries may finally have met in 2022, two years after the 2020 deadline.
The COP29 presidency hosted a “dialogue on enabling global action for climate finance” at the spring meetings, which saw president-designate Mukhtar Babayev sketch out broad priorities for the new climate-finance goal.
Other international events will feed into the climate summit and give a sense of progress towards international financial system reforms. In particular, G20 host Brazil will oversee continued discussions around finance at a meeting in July.
The World Bank and IMF annual meetings will then take place in October, shortly before COP29.


The post Q&A: Climate finance at World Bank and IMF spring meetings 2024 appeared first on Carbon Brief.
Q&A: Climate finance at World Bank and IMF spring meetings 2024

What happens when a love of marine life meets a playful imagination?
Sydney artist, illustrator and children’s author Sha’an d’Anthes, better known as Furry Little Peach, has teamed up with Greenpeace to create Happy Ocean Happy Planet: a joyful celebration of the extraordinary creatures that call our oceans home.
Sha’an felt inspired to create an illustration celebrating the beauty and resilience of marine life. Its hopeful message, A Happy Ocean is a Happy Planet, sparked a special collaboration with Greenpeace and a limited-edition t-shirt designed to help protect the oceans that inspired it.
The exclusive Furry Little Peach tee is available as a gift to new regular Greenpeace donors who give $30 or more and make at least three donations. By becoming a regular giver, you’ll help Greenpeace campaign for ocean protection.

ARTIST INTERVIEW: Sha’an d’Anthes (Furry Little Peach)
Sha’an shares the story behind the artwork, the local marine creatures featured in the design and why hope can be such a powerful force for action.
Hi Sha’an! Can you tell us a little about yourself and what you do?
My name is Sha’an d’Anthes, I also go by the pseudonym Furry Little Peach and I’m an illustrator, artist and children’s author based in Sydney, Australia. I love creating joyful, vibrant and nostalgic art that looks at the world through the lens of childlike wonder.

What do you love about drawing animals and nature?
I love all of the different shapes, colour and narrative you get to explore when drawing animals and nature. I’m also a city-slicker these days, and so I think that my work is a sort of escapism (for myself and hopefully for my audience).
How did the Greenpeace collaboration come about?
I went to the premiere of David Attenborough’s documentary Ocean, and felt compelled to create something to share the message of the film. This t-shirt is actually based off of that illustration including the tagline in I included when I shared it “A Happy Ocean is a Happy Planet”. I’m so grateful Greenpeace approached me for the project – it was a blast.
Where did you start when creating the Happy Ocean Happy Planet design?
The Happy Ocean tee starts the same as all of my work – with a brainstorm/braindump and really loose concept sketches.
How did you choose the animals for the illustration?
I actually asked Greenpeace to help me with the research of local marine life and they were so accommodating. They very quickly delivered me a huge list of local species of fish, mammals and coral and I just went through and looked up each creature and curated a little group of sea life that I thought would look sweet together – a mix of sizes, types, colours, textures and shapes.
What did you use to create the artwork?
So much of my work is traditional, but when it comes to things like t-shirts I always use digital drawing programs because I like to draw each colour in a separate layer which requires me to jump in and out of layers because it allows me to control colour and printing. When working digitally I always sketch in Procreate (an Australian digital art app), and then with this project I created final art in Adobe Fresco because it called for a vector graphic (an image that can be blown up to any size).
Do you have a favourite creature in the design?
I love painting Humpback Whales and always have, but I also have a soft spot for the sweet little Jelly Blubber jellyfish.
What did you want people to feel when they saw the artwork?
I specifically wanted to focus on the outcome that all of us want to see – a happy, thriving ocean where creatures are given the time and space to balance themselves. I feel that even when tackling tough subjects, leaning into hope is my natural inclination. As long as we have hope that things can be better, we will continue to take action.
What was the most fun part of creating it?
I actually documented the entire process of this project in a studio vlog on YouTube – and you can see how much fun I’m having doing final art jumping between layers and building the image. I had just come off completing final art for two books which are multi-year long projects, so being able to do a project that from start to finish in just a few days was really freeing at the time.
What does a “happy ocean” mean to you?
An ocean that given the time and space to repair and balance itself. Something I really took away from David Attenborough’s Ocean is that ocean ecosystems are actually really good at repairing themselves if we just let them do their thing.
How can people get their hands on the t-shirt?
The shirt is a reward for regular givers to Greenpeace – those who commit to at least 3 months of donations will receive the tee as a gift. Read about how at http://act.gp/flp-tee
How is Greenpeace helping to make our oceans happier places?
They have a deep focus on the health and happiness of our oceans through advocating for the set up of marine sanctuaries, holding big ocean polluters to account and calling for a ban on deep sea mining.
What are you working on next?
I will be jumping headfirst into Peachtober – an annual daily art challenge I run each year in October, if there are any artists reading this it’s a great time so please come join! In terms of publications my next picture book The Late Bird will be out in February 2027 (published by Harper Collins US) and then I have an creative activity book for adults coming out next August with Chronicle US and Penguin Australia. Otherwise you can always check out what I’m tinkering away with in my studio on Instagram and YouTube.

Climate Change
AI giant Anthropic’s first Australian data centre deal an “egregious” example of Big Tech double talk
SYDNEY, Thursday 17 September 2026 — Greenpeace Australia Pacific has slammed AI giant Anthropic’s deal for its first Australian site in Queensland’s Western Downs, the heart of coal seam gas country, saying the project will entrench gas and turbocharge climate pollution.
The expected electricity demand from the data centre site, situated in the middle of the Western Downs coal seam gas fields, is comparable to 1.5 million Australian households. Greenpeace’s report Energy Vampires: The AI data centres draining Australia called for a moratorium on frenzied data centre development until appropriate guardrails are in place.
Joe Rafalowicz, Head of Climate and Energy at Greenpeace Australia Pacific, said: “This is an egregious example of Big Tech giants being given carte blanche to drain energy and water, and use polluting gas to fuel their hyperscale data centres.
“AI and Big Tech corporations claim to bring new renewable energy to the grid, while blatantly planning to power their operations with polluting fossil fuels.
“Planning documents show the first stage of this behemoth project could be powered by ‘behind the metre’ gas — the same playbook AI companies have used in the US, leading to a 20% increase in climate pollution from electricity. Now these companies want to bring their cowboy plans to Australia and the Federal Government is allowing it.
“If they plugged into the local grid, the power required would increase Queensland’s electricity grid emissions by around 6.6 million tonnes — an 18% rise. If they build their own gas-fired power plants, this will drive up Queensland’s emissions even more.
“Billions of dollars are now pouring into a massive pipeline of proposed new data centres, of unprecedented size, being built at incredible speed across the country. Australians should be worried about the extreme lack of scrutiny being applied to these projects, and the corporations leading the data centre charge.
“The data centre build-out is happening without the endorsement of the Australian people, yet we are the ones who will pay the price. We can not allow unchecked data centre expansion to derail our renewable energy transition, entrench gas and turbocharge climate pollution — that’s why Greenpeace has called for an urgent moratorium until appropriate guardrails are in place.”
ENDS
Media contact: Kate O’Callaghan on 0406 231 892 or kate.ocallaghan@greenpeace.org
Climate Change
Analysis: India’s power-sector emissions flat for two years due to clean-energy surge
A surge in clean energy has kept carbon dioxide (CO2) emissions in check across India’s power sector, with no growth from the first half of 2024 to the same period in 2026.
This guest post is by:
Lauri Myllyvirta, lead analyst at Centre for Research on Energy and Clean Air (CREA)
Anubha Aggarwal, India analyst at CREA
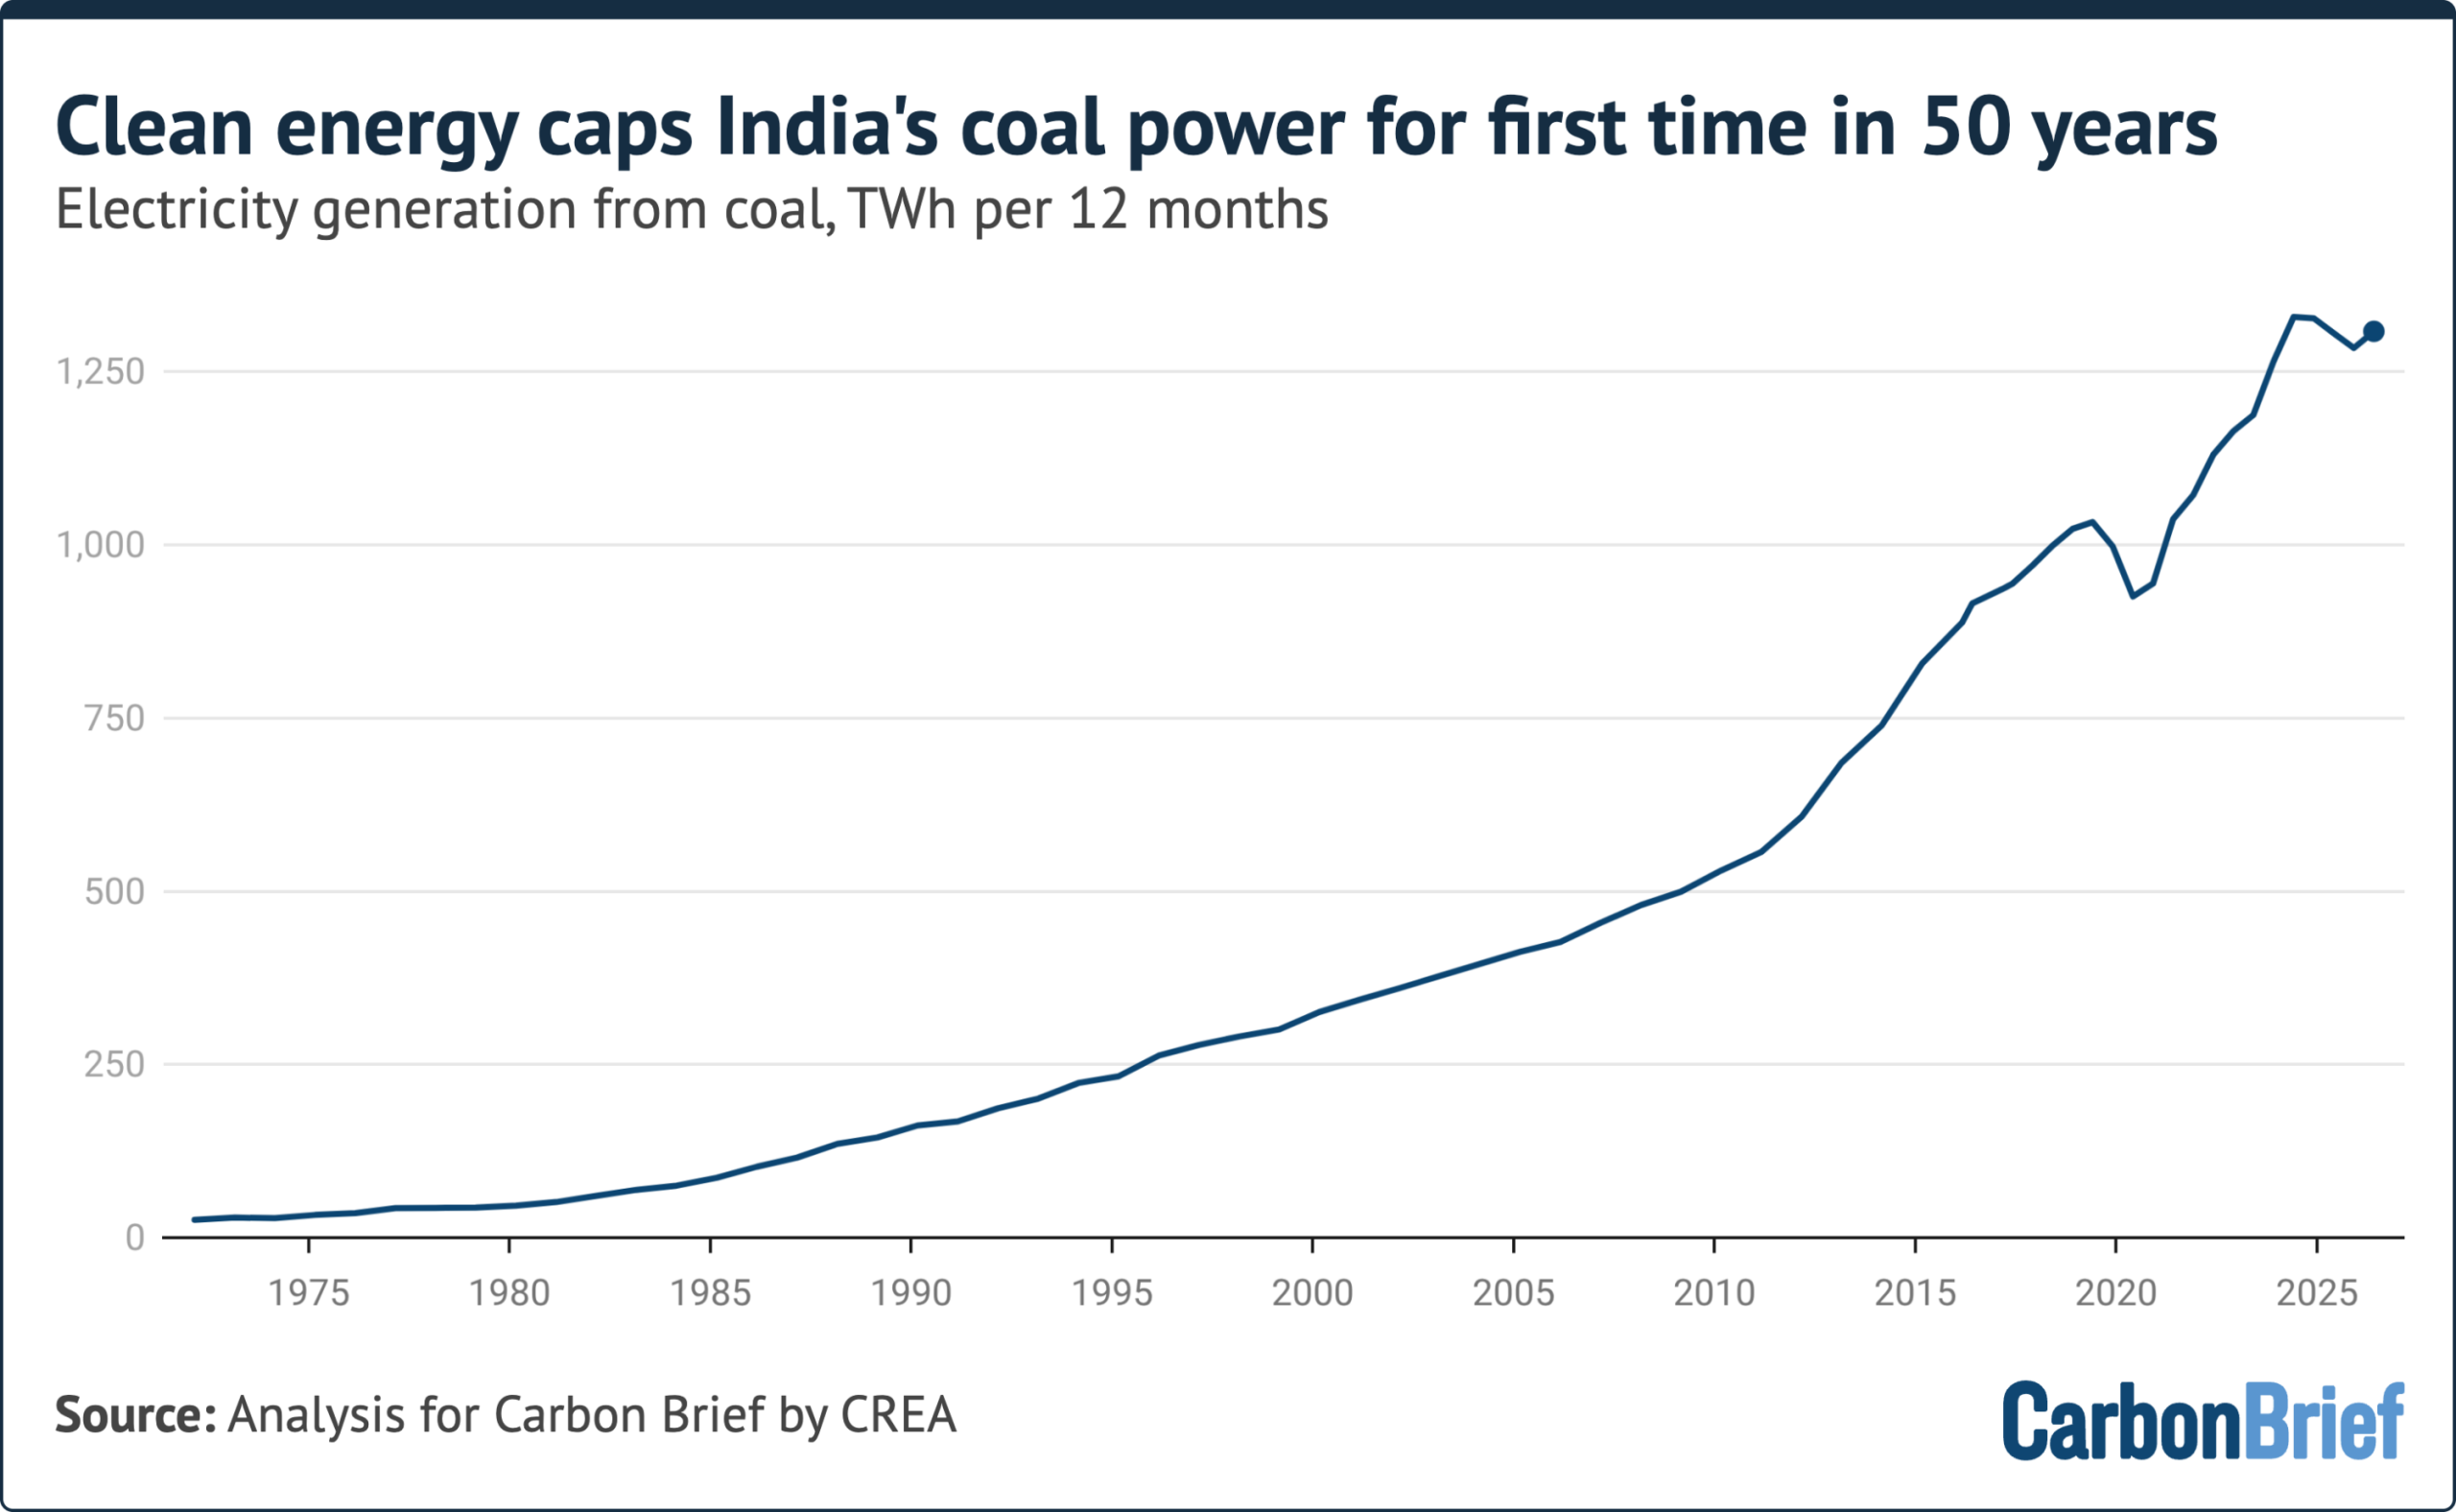
This is the first time in more than 50 years that there has been no growth in India’s coal power over a two-year period, even as electricity demand grew overall.
At the same time, both oil and gas consumption have fallen across the nation for two years in a row, helping alleviate the shock of the Hormuz crisis.
Nevertheless, the new six-monthly analysis for Carbon Brief shows that India’s emissions grew by 3.7% year-on-year in the first half of 2026, due to increases from steel, cement and other sectors.
Other key findings for the first half of 2026 include:
- India’s power-sector emissions flatlined at 2024 levels, after a 2.2% decline in the first half of 2025 and a 2.3% rise in the same period this year.
- Clean energy met all of the 7% rise in India’s electricity demand over the two years, adding 63 terawatt hours (TWh), equivalent to the total demand of Switzerland.
- India has added 77 gigawatts (GW) of solar in this two-year period, helping meet 60% of the rise in electricity demand overall.
- While fossil-fuel generation stagnated, generators added 8.5GW of new coal capacity, leading to fewer running hours and increased costs to electricity consumers.
- CO2 emissions from oil and gas fell by 7% year-on-year, extending a reduction that began in 2025, despite higher demand for road transport fuels.
- Steel and cement emissions grew by 8% year-on-year, reaching a 23% share of India’s total CO2 in the first half of 2026.
If the pace of India’s clean-energy expansion is to continue, it will need to upgrade its electricity grid, rapidly build out energy storage and boost the flexibility of coal power.
While clean-energy expansion is covering most or all of India’s power-demand growth, the fossil-fuel industry continues to pursue major capital investments.
This includes large amounts of new coal-power capacity, ambitious plans for the conversion of coal-to-chemicals and efforts to boost domestic coking coal production for the steel sector.
While CO2 output from the power sector is flat, with oil and gas in decline, India’s emissions still went up due to the contribution from industry.
India lags behind its competitors – including most large emerging economies – when it comes to electrifying its industrial sector.
Faster progress would enable clean electricity to substitute for fossil fuels in industry, as well as for power, offering the potential for India to cut its emissions overall.
Flatlining fossils
Last year, India’s CO2 emissions from fossil fuels and cement grew at their slowest pace in two decades, according to previous analysis for Carbon Brief.
This sharp slowdown was due to rapid clean-energy growth and flat oil demand, combined with rising emissions from steel and cement.
The first half of 2026 marks a continuation of these trends.
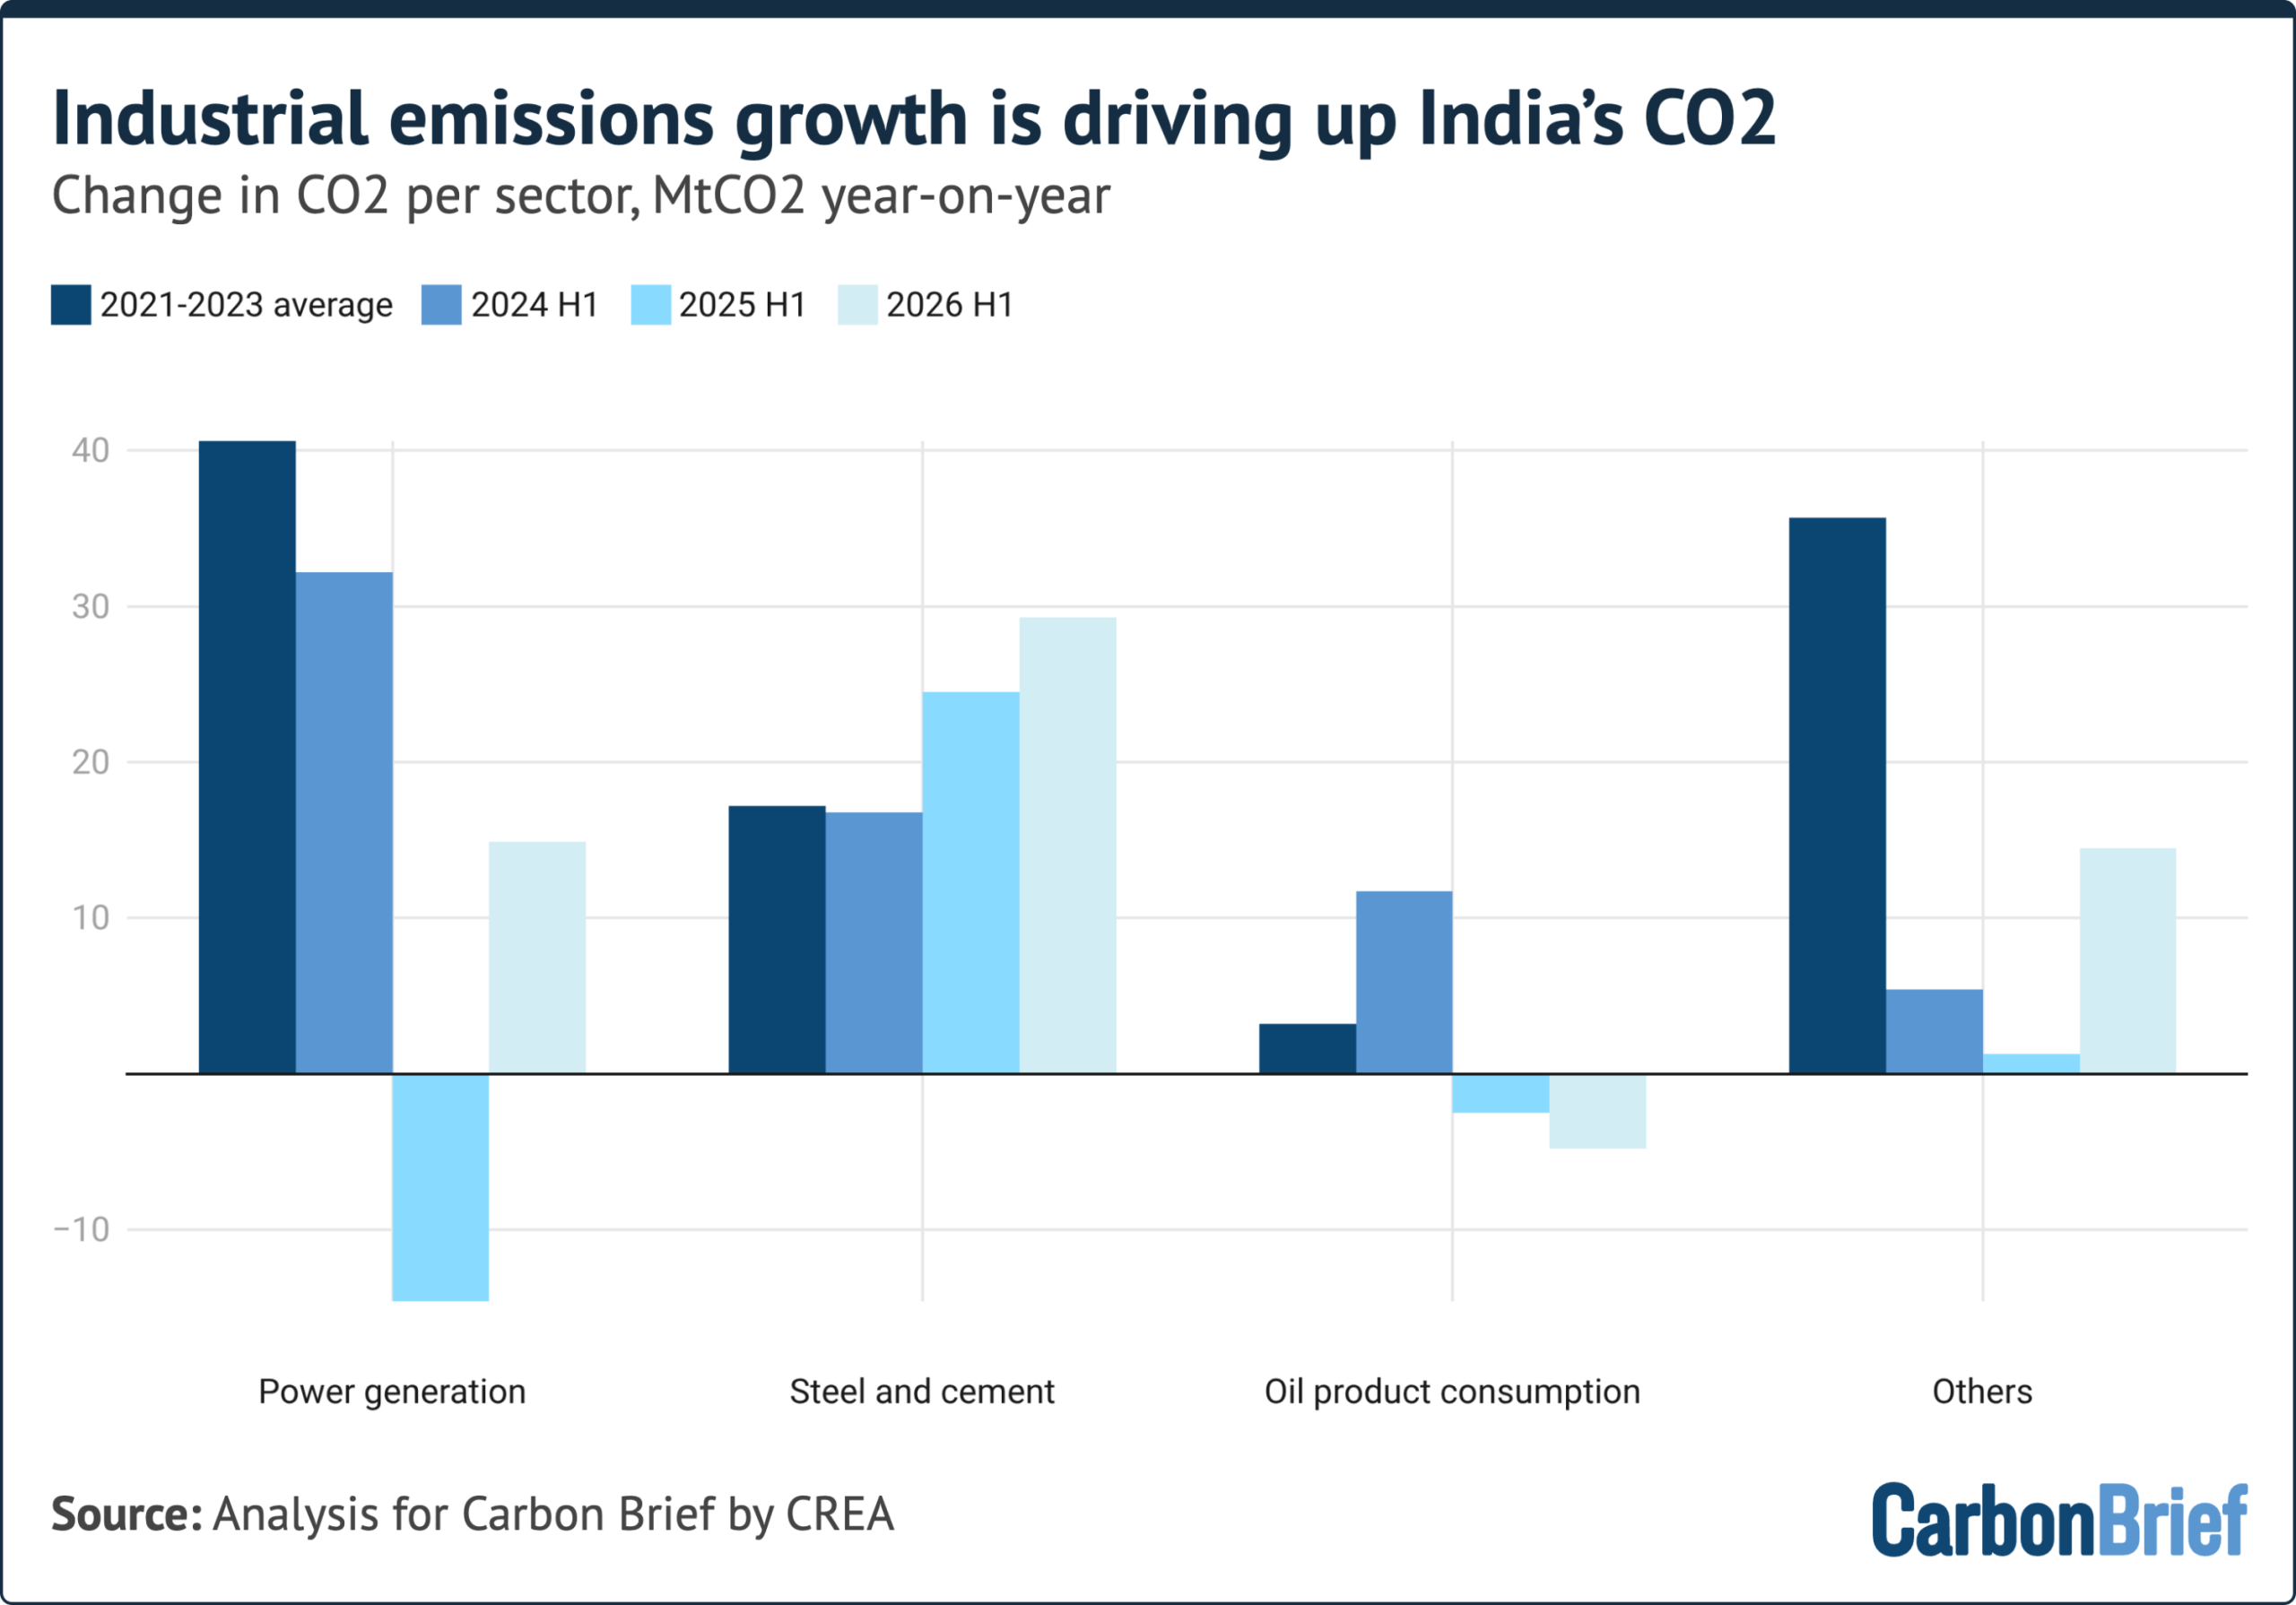
Most strikingly, the ongoing surge in clean-energy generation means that emissions have flatlined in India’s power sector for two years, as shown in the figure below.
Power-sector CO2 was the same in the first half of 2026 as two years earlier, with a small decline in 2025 having been reversed over the same period this year.
Beyond electricity generation, India’s key emitting sectors continued to see divergent trends in the first half of 2026, as some saw ongoing decline while others reached new heights.
This is shown in the figure below, which compares year-on-year changes in emissions during the first half of 2026 with the same periods in 2025, 2024 and the average for 2021-23.
Specifically, emissions grew by 2.3% in the power sector, reversing last year’s decline, while demand for gas and oil products fell for another year.
The biggest increases were for steel and cement, where emissions growth accelerated to 8% year-on-year in the first half of 2026, well above the recent trend.
Clean-energy growth matches power demand
The period from the first half of 2024 to the first half of 2026 saw the largest increase in non-fossil power generation on record in India.
This enabled fossil-fuel consumption and CO2 emissions from the sector to stay flat, even as electricity consumption increased.
Indeed, this is the first time in more than 50 years that there has been no growth in coal power over a two-year period, even as electricity demand grew overall, as shown below.
Over this two-year period, India’s total power generation increased by 7%, some 63TWh, equal to the total consumption of Singapore or Switzerland.
The additional power requirement of 63TWh was met entirely by clean energy. Solar grew by 44TWh, alongside growth from wind (13TWh), nuclear (7TWh) and hydro (8TWh).
Together, clean-energy sources added 70TWh over two years, more than the net increase in demand.
(For comparison, China’s nuclear, wind and solar output increased by 485TWh in 2025.)
The figure below shows that new investments are more than sufficient to maintain this trend, as added power generation from new clean power capacity has stayed above average demand growth for the past 18 months.
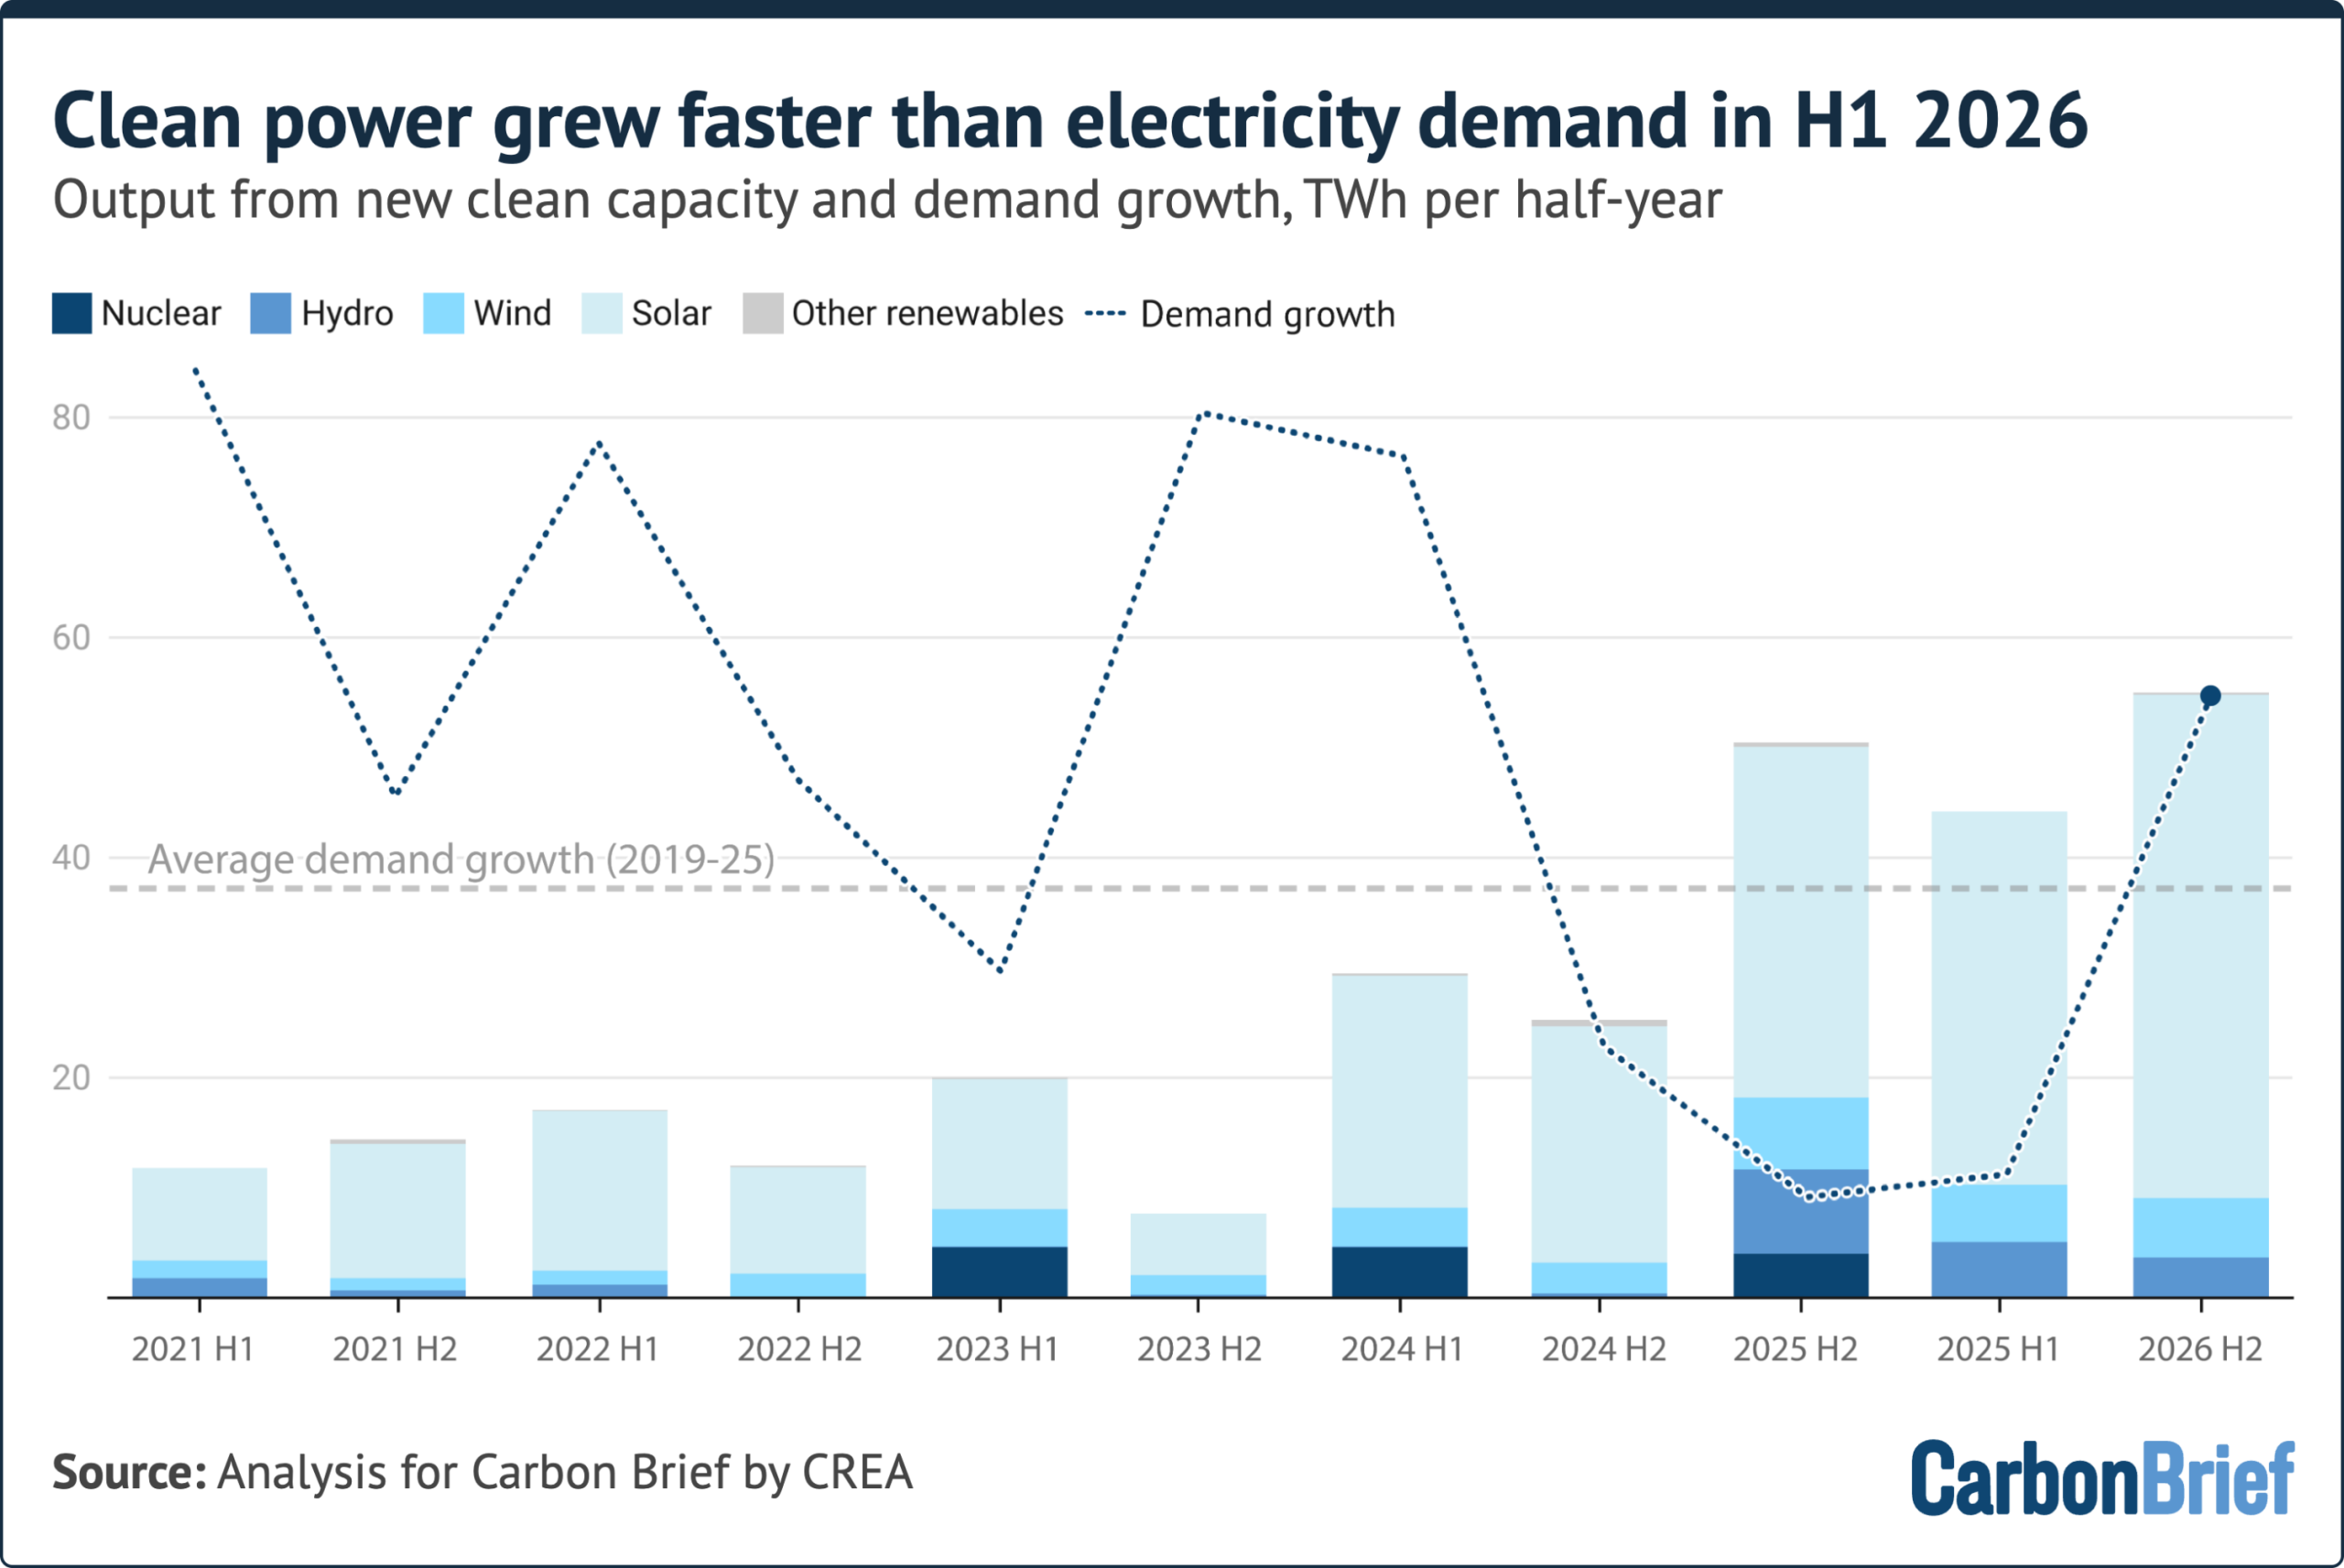
Over the past two years, India added 77GW of new solar capacity, 11GW of wind, 5GW of hydro and 0.6GW of nuclear capacity.
Solar power continues to dominate clean-energy growth, but, collectively, the other non-fossil sources still contributed 40% of the overall increase in generation.
One factor in electricity demand growth in 2026 is the El Niño, which delayed the monsoon and intensified heatwaves, driving up cooling demand.
India is accelerating investment in energy storage, which will support further growth in clean power. The National Electricity Plan projected a requirement of 82 gigawatt-hours (GWh) of energy storage capacity by 2026-27 and 411GWh by 2031-32.
As of May 2026, the government has issued tenders for around 272GWh of energy storage capacity, including 142GWh of pumped hydro and 133GWh of battery storage systems. Current capacity is 7.5GWh of battery storage and around 60GWh of pumped hydro.
Which states led the clean-power shift?
The fall in power generation from fossil fuels from the first half of 2024 to the same period in 2026 was concentrated in a few states.
Gujarat saw both the largest reduction in fossil-fuel generation and the largest expansion in clean power, as shown in the figure below.
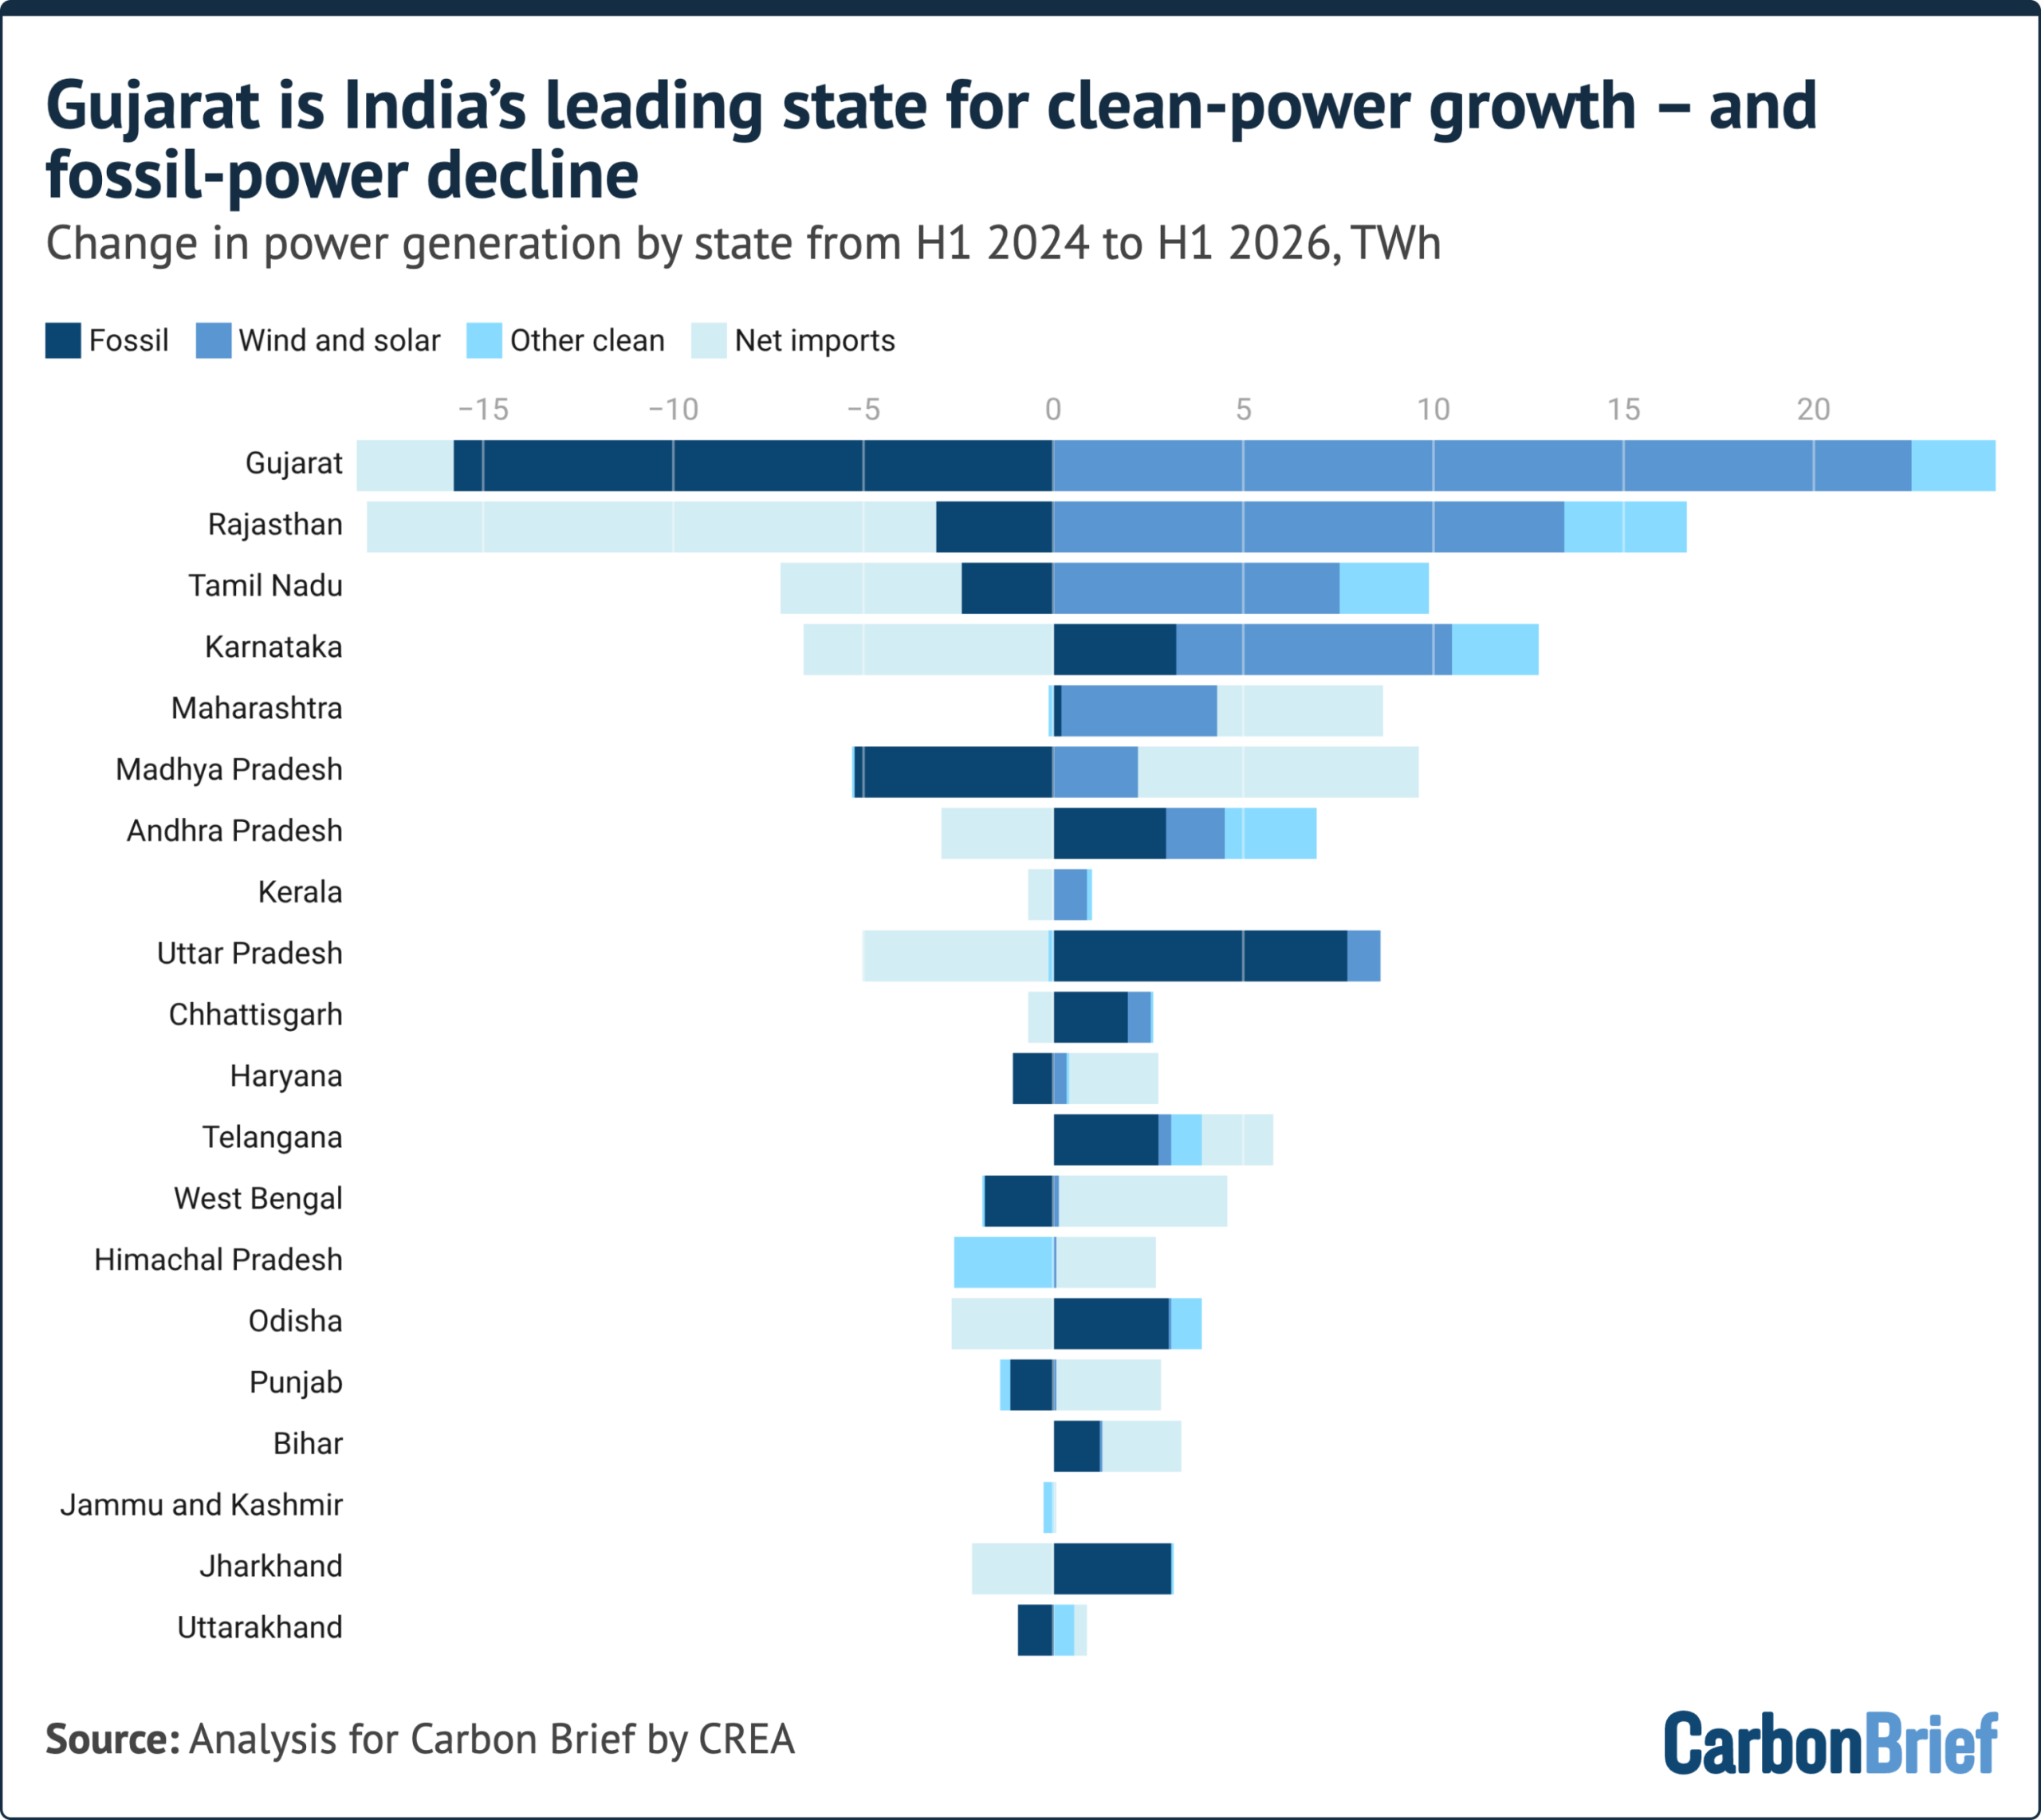
After Gujarat, the largest increases in clean-power generation were seen in Rajasthan and Tamil Nadu, which also saw reductions in power generation from fossil fuels.
Several other states saw declines in fossil-fuel generation due to higher net imports, rather than local clean power. These included Madhya Pradesh, West Bengal and Punjab.
Karnataka and Andhra Pradesh also succeeded in increasing clean-power generation faster than power demand, thereby contributing to keeping fossil fuel-based power generation stable nationwide across the two-year period. However, they exported much of the increase and consequently saw local increases in power generation from fossil fuels.
The two states with the largest increases in power demand, Maharashtra and Telangana, managed to almost match the rise with growth in clean-power generation.
Fall in oil and gas consumption continues
India’s oil consumption continued to fall during the first half of 2026, dropping 1.3% year-on-year, a slight acceleration from the 0.7% reduction in the same period last year.
While diesel and petrol consumption continued to grow, oil consumption was pulled down overall by declines in liquefied petroleum gas (LPG), petcoke (a solid derivative of oil used in the cement industry) and industrial feedstocks. Growth of aviation fuel use eased.
Diesel consumption growth accelerated from 1.8% to 4.1% in the first half of the year, supported by higher freight movement and increased agricultural demand, as the delayed monsoon led to greater use of diesel-powered irrigation.
Petrol consumption returned to growth, increasing 6.9% year-on-year after zero growth in the same period in 2025, reflecting sustained growth in passenger and two-wheeler mobility.
A significant increase in ethanol blending shaved a full percentage point off the growth of petrol consumption. India achieved its 20% ethanol blending target five years ahead of schedule in 2025-26. (Ethanol blending has faced public opposition.)
Electric vehicle (EV) adoption in India is also gaining momentum, with EVs adopted in a widening range of categories.
In Delhi, an EV policy was launched to accelerate electrification of the vehicle fleet, with a particular focus on two-wheelers, three-wheelers (auto rickshaws), commercial vehicles and high-mileage segments, alongside expanded charging infrastructure. Higher EV adoption rates will moderate the growth in emissions from petrol consumption in India.
In contrast, aviation fuel demand growth slowed down from 5% to 2%. The slowdown coincided with the strait of Hormuz and wider crisis, which disrupted international aviation through temporary airspace closures and flight cancellations to several Middle Eastern destinations. Elevated aviation fuel prices also increased airline operating costs, contributing to lower fuel demand.
LPG consumption contracted by 7%, after 5.7% growth in the same period last year, amid disruptions in global LPG markets following the Hormuz crisis.
Petcoke consumption fell 9.9%, more than reversing a 9.3% increase in the same period last year. Rising petcoke prices encouraged cement manufacturers to switch to coal.
Consumption of other petroleum products continued to drop, although the pace of decline moderated from 14% in 2025 to 9% in 2026.
Industrial feedstock use was affected by shortages and price increases.
Naphtha demand contracted as import prices nearly doubled and domestic prices increased by around 60%, prompting petrochemical manufacturers to reduce operating rates and suppress demand for imported naphtha.
Bitumen consumption remained subdued due to slower road construction, driven by persistent land acquisition challenges and higher bitumen costs.
Meanwhile, higher light diesel oil (LDO) prices and shortage of LPG led some industrial consumers to switch back to furnace oil in boilers and heaters, despite the higher air pollutant emissions. Supply of fuel oil to industry increased for the same reason.
Rapid emission growth from heavy industry continues
Steel and cement output in India grew by 8% and 9%, respectively, year-on-year in the first half of 2026, despite rising input prices and weakening profitability.
The growth in steel and cement was supported in part by increased investment in India’s real estate sector, especially in the second quarter. Steel consumption growth outpaced production, implying that inventories built up last year were tapped.
Despite domestic demand growth, profit margins of Indian steel and cement manufacturers remained under pressure for much of the period due to elevated raw material costs – particularly imported coking coal – and higher freight costs stemming from the Hormuz crisis.
The pressure on prices could dampen growth. Cement prices are expected to rise to levels last seen in the 2021-22 financial year, when Russia’s decision to cut back gas exports to Europe drove a sharp increase in fossil-fuel prices.
Outside the steel, cement and power sectors, coal-consumption growth accelerated to 14% in the first half of 2026, up from 3% last year, as the LPG shortage prompted a shift to coal.
Gas shortages resulted in some additional burning of coal for cooking in March and April. The government officially authorised the hospitality industry to use coal, refuse-derived fuel pellets, biomass and kerosene for one month.
The ceramic and tile industry also requested that the government allow the use of coal gasifiers amid the gas shortage. State governments including Delhi NCR, Rajasthan, Tamil Nadu, Gujarat and Maharashtra also allowed industries to temporarily use alternative fuels, including coal.
India’s industrial energy use is dominated by fossil fuels, particularly coal. Indian industry has the second-lowest electrification rate in the G20, as shown in the figure below. The share of electricity in total energy consumption in the sector also lags the world average, in terms of both current levels and the rate of increase.
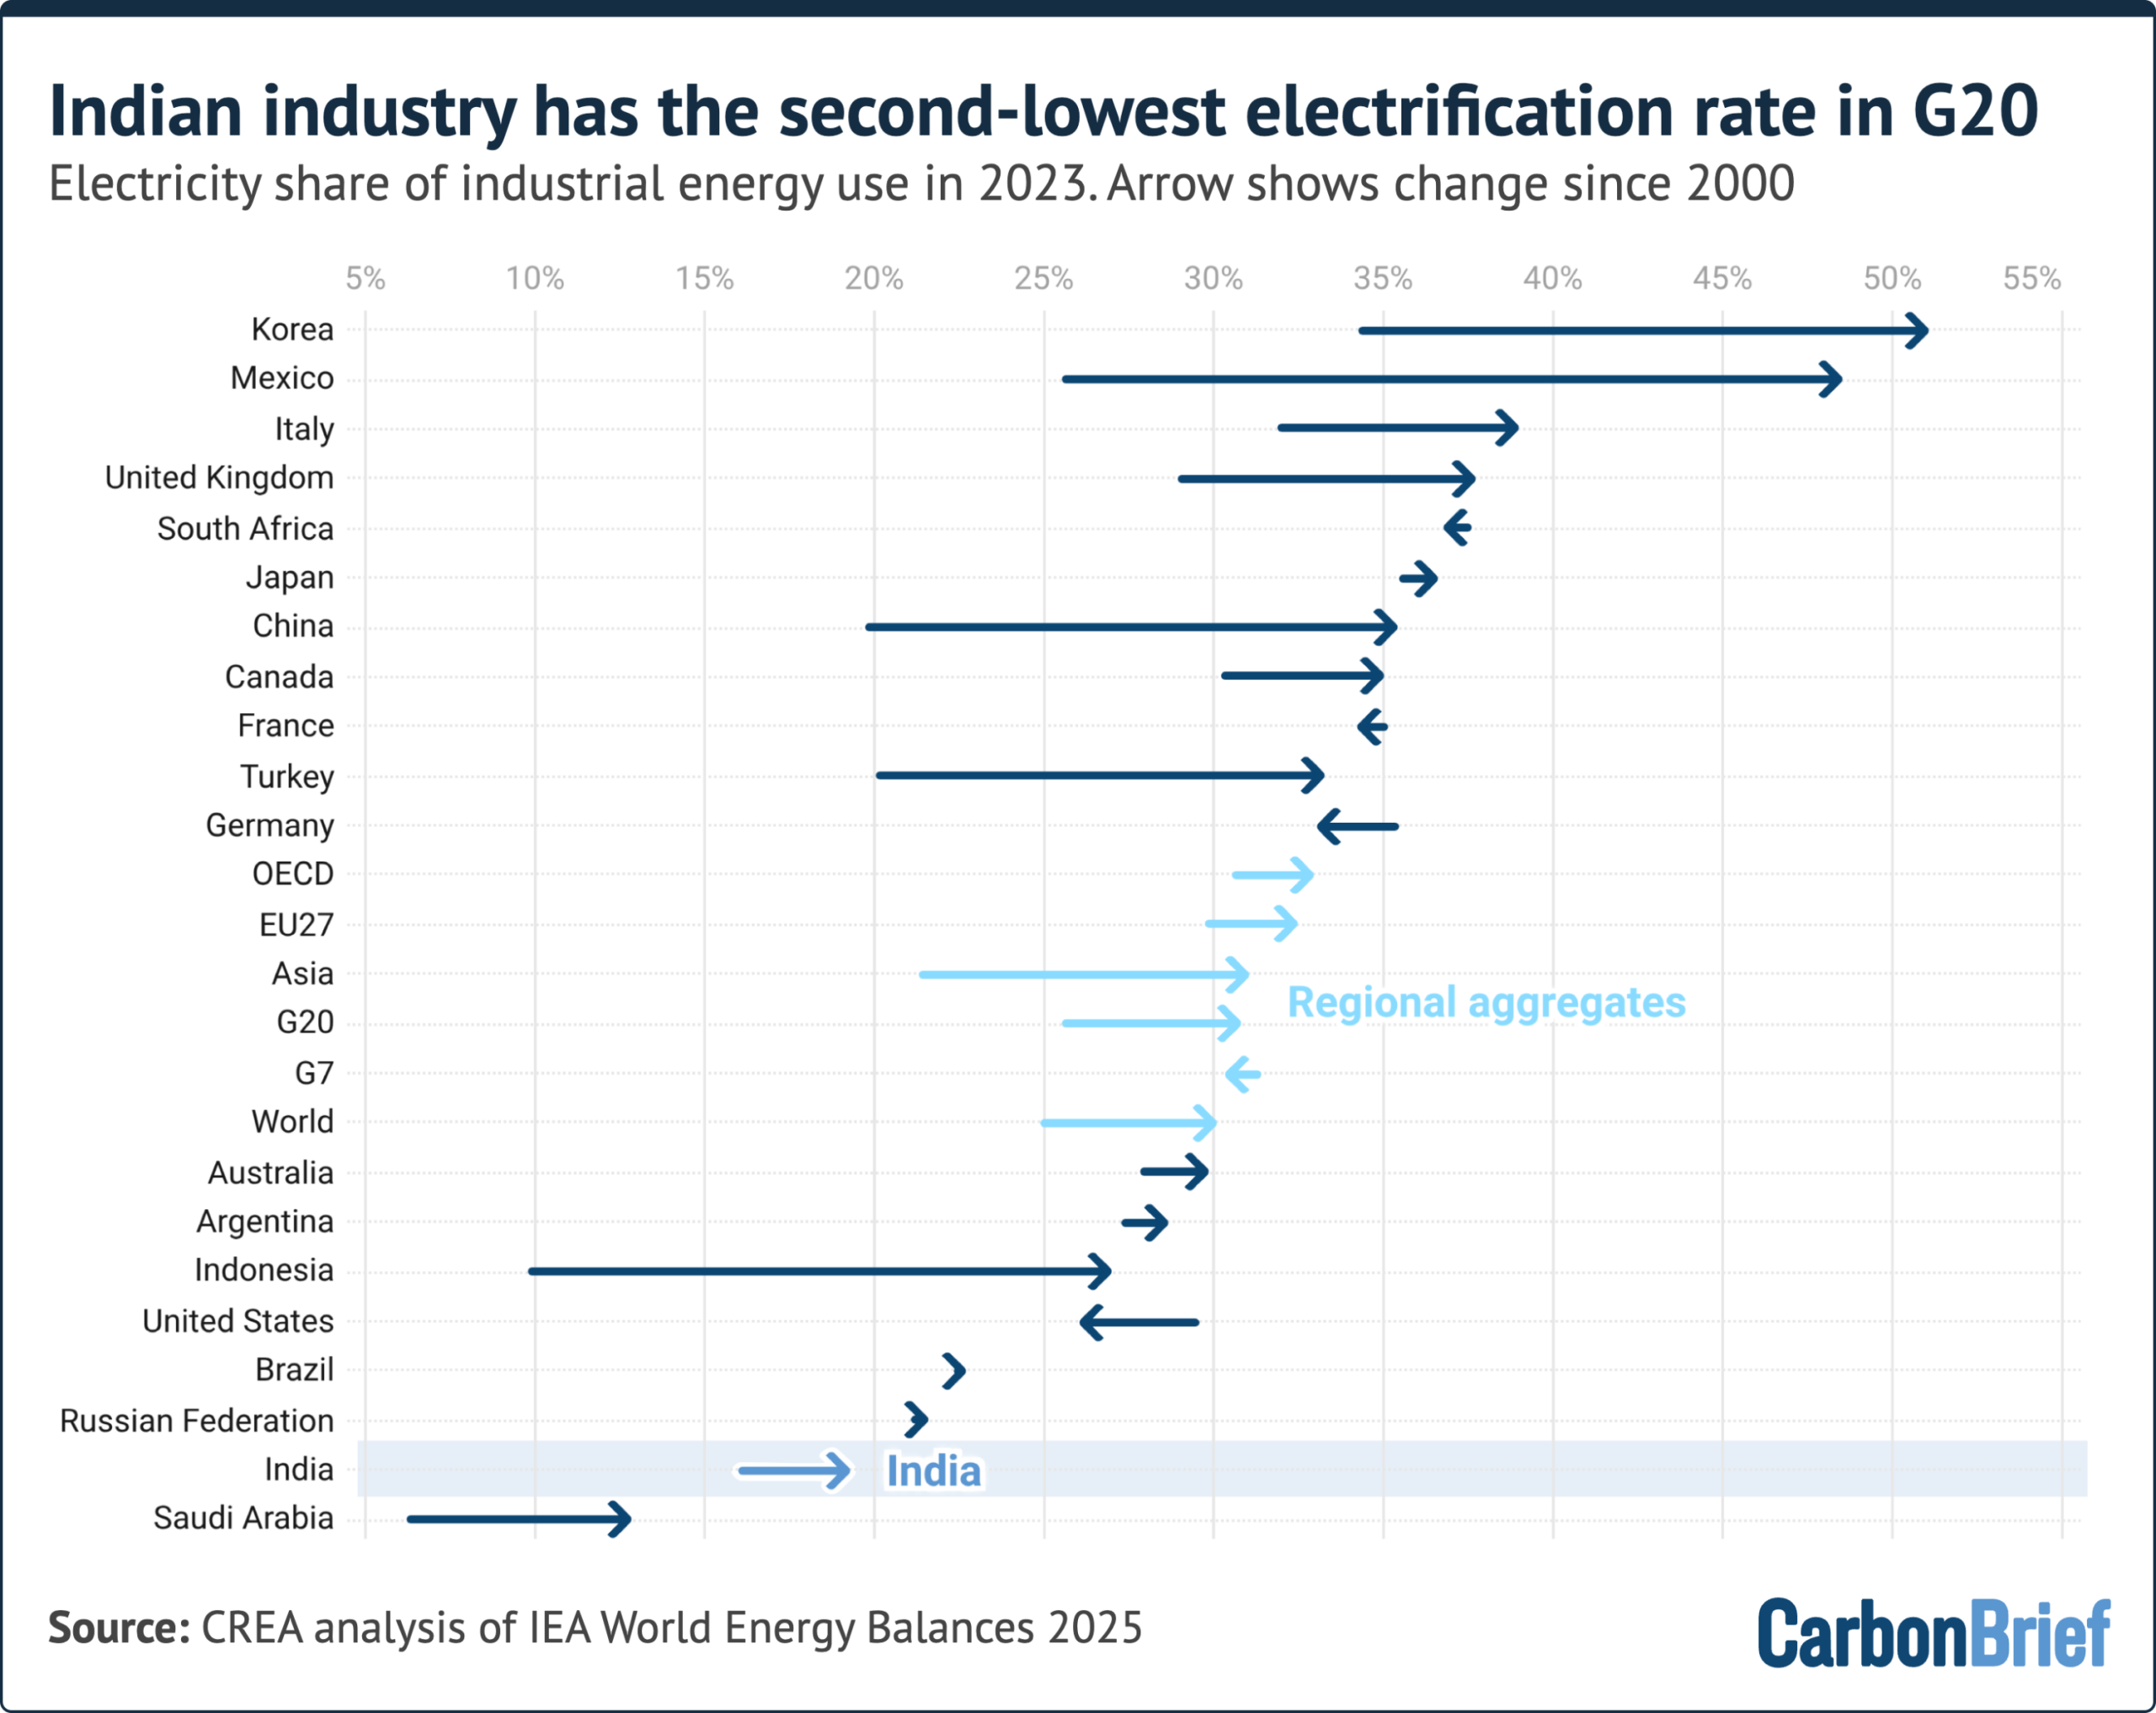
The current low rates of electricity use in Indian industry imply that there is major potential for electrification, using technologies and processes already in place in other countries.
New investments in coal
While the clean-power expansion is starting to meet most or all of India’s electricity demand growth, there are still large investment plans across the coal supply chain.
Some 43GW of coal-power capacity was under construction at the end of June. Additional coal-power capacity is seen as necessary to meet increasing peak loads, even as solar power and energy storage are already playing a role in covering daytime and evening peak demand, respectively. The expansion of energy storage will increase this contribution.
Outside the power sector, India has major ambitions to produce chemical-industry products, such as fertiliser and plastic feedstock, from coal through coal gasification, in pursuit of energy security.
The government is targeting a capacity to process 100m tonnes of coal per year in the next four years, despite the technology for coal gasification still being nascent in India. At present, the only operational use of coal gasification is at Jindal Steel Limited, which is reportedly using syngas in its steel-making process.
Meanwhile, India plans to reduce its average CO2 emissions per tonne of steel by 25% by 2025-26, mainly by reducing the share of coal-based steelmaking.
At the same time, the government is aiming to increase the use of domestic coking coal, which it notified in January this year as a “critical and strategic mineral”. Coal miners and steel companies are reportedly planning to establish additional washeries for coking coal to make it suitable for blending with imported coal for use in steel production.
India is also looking to invest in new coal mines in the near future.
These continued investments in coal gasification, domestic coking coal and new coal mining capacity could lock in coal use across industry for several decades.
Outlook for India’s emissions
Over the two-year period from the first half of 2024 to the same period in 2026, India has achieved its largest clean-energy expansion on record.
As a result, power-demand growth has been met entirely by clean electricity and CO2 emissions in the sector have flatlined.
This expansion of clean energy also allowed a reduction in fossil-fuel imports for power generation, with the use of imported coal falling 38% and the use of gas by 35%, supporting the energy security aims of the government and reducing exposure to the Hormuz shock.
In order to keep the clean-energy growth going, India would need to overcome multiple obstacles, including expansion of the electricity transmission network, improvements in grid flexibility to accommodate variable renewables and the timely completion of new projects.
For example, renewable power projects totalling 5.3GW missed completion deadlines and are having to pay penalties to the grid operator in order to retain network access.
Curtailment has emerged as an issue, particularly for projects relying on interstate power transmission, pointing to the need to upgrade the network. (Curtailment refers to electricity generation that is “wasted” because it cannot be accommodated by the power network.)
Another obstacle to be overcome if clean energy is to keep growing will be making coal-power plants more flexible, so they can ramp down during high renewable output.
A flexibility plan for coal-power plants has been delayed by more than a year due to persistent regulatory bottlenecks, contributing to the curtailment of renewable energy.
Expanding energy storage has the potential to ease grid and flexibility constraints, while reducing or eliminating the need for adding thermal-power capacity to meet peak loads.
The Central Electricity Authority has proposed that, after June 2027, all new government-owned solar and wind projects would have “mandatory” two-hour battery storage. (This mirrors a policy that was in place in China until early 2025 and was subsequently scrapped, in favour of more market-based approaches.)
For oil and gas, India’s consumption has been flatlining for the past two years, after half a century of continuous growth that was only briefly interrupted by Covid-19.
This has reduced the impacts of the Hormuz crisis on the country’s trade balance, helping close the gap between supply and consumption. But it has entailed disruptive shifts in many oil-dependent sectors.
For example, high prices and fuel shortages due to the Hormuz crisis led state governments to reverse their orders banning the use of dirtier fuels such as fuel oil, kerosene and coal in industries and commercial establishments.
Meanwhile, EV adoption has also begun to influence oil consumption.
Despite the progress in the power sector and reductions in oil consumption, India’s total emissions went up over the past two years due to a major increase in industrial emissions.
Low levels of electricity use in industry mean that growing industrial output results in increasing direct fossil-fuel use and emissions.
Unless the rate of industrial electrification picks up, increases in heavy industry output will continue to translate into increases in fossil-fuel consumption and CO2 emissions.
About the data
This analysis is based on official monthly data for fuel consumption, industrial production and power generation from different ministries and government institutes.
Coal-power emissions are estimated by combining plant-level coal consumption from the Central Electricity Authority’s (CEA) monthly coal reports with data on the calorific value and emission factors of coal used at different power plants from the CEA’s CO2 baseline database.
For each station and month, total coal consumption is split into domestic and imported coal using the imported share of coal receipts over a trailing two-month window, found to best reproduce the actual split in data available for 2023.
Consumption is converted to CO2 using each plant’s station-specific gross calorific value from the CEA database and IPCC emission factors for domestic coal, imported coal and lignite. The national-average calorific value is used for recently added plants, for which data is not available in the baseline database.
Coal use at steel and cement plants, as well as process emissions from cement production, are estimated using production indices from the index of eight core industries released monthly by the Office of Economic Adviser, assuming that changes in total fossil-fuel use follow production volumes. These production indices were used to scale fuel use by the sectors in 2022.
To form a basis for using the indices, monthly coal-consumption data for 2022 was constructed for the sectors by combining the annual total coal and petcoke consumption reported in IEA World Energy Balances with monthly production data. This work was set out in a paper by Robbie Andrew, a researcher at Norwegian research institute CICERO, on monthly CO2 emission accounting for India. Monthly petcoke consumption was available from the Petroleum Planning and Analysis Cell, while coal consumption by the cement industry was calculated by subtracting petcoke use from total fossil-fuel use.
Annual cement-process emissions up to 2025 were also taken from Andrew’s work and scaled using the production indices. This approach better approximated changes in energy use and emissions reported in the IEA World Energy Balances, than did the amounts of coal reported to have been dispatched to the sectors, showing that production volumes are the dominant driver of short-term changes in emissions.
For other sectors – including aluminium, auto, chemical and petrochemical, paper and plywood, pharmaceutical, graphite electrode, sugar, textile, mining, traders and others – coal consumption is estimated based on data on despatch of domestic and imported coal to end users from statistical reports and monthly reports by the Ministry of Coal, as consumption data is not available.
Coal consumption by “captive” coal-power plants – those supplying power to industrial sites, not to the public electricity network – was calculated based on capacity changes from Global Energy Monitor, assuming constant utilisation, as utilisation has been very stable year-to-year, as calculated from Central Electricity Authority data.
The difference between coal consumption and dispatch is stock changes, which are estimated by assuming that the changes in the amount of coal stored at end-user facilities mirror those at coal mines, with end-user inventories excluding power, steel and cement assumed to be 70% of those at coal mines, based on comparisons between our data and the IEA World Energy Balances.
Stock changes at mines are estimated as the difference between production at and dispatch from coal mines, as reported by the Ministry of Coal.
Coal consumption is estimated in two ways for sectors beyond power, steel and cement. Consumption of domestic coal in these other sectors is taken from the monthly reports by the Ministry of Coal. Their consumption of imported coal is estimated from the total imports of thermal coal reported by consultancy Kpler, by subtracting demand for imports at coal-power plants. The basis for this assumption is that steel and cement industries use little imported thermal coal, according to Ministry of Coal data.
Product-by-product consumption data for petroleum products, as well as gas use by sector, is from the Petroleum Planning and Analysis Cell of the Ministry of Petroleum and Natural Gas.
As the fuel dispatch and consumption data is reported as physical volumes – such as tonnes or litres – calorific values are taken from IEA’s World Energy Balance and CO2 emission factors from 2006 IPCC Guidelines for National Greenhouse Gas Inventories.
The emissions factor for motor oil or petrol was updated, based on the blending percentage of ethanol each year. The ethanol-blending percentage is as reported by the Ministry of Petroleum and Natural Gas.
Calorific values are assigned separately to different fuel types, including domestic and imported coal, anthracite and coke, as well as to petrol, diesel and several other oil products.
related
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
UNEP: New country climate plans ‘barely move needle’ on expected warming
Analysis: India’s power-sector CO2 falls for only second time in half a century
World’s electricity supply close to ‘peak emissions’ due to growth of wind and solar
The post Analysis: India’s power-sector emissions flat for two years due to clean-energy surge appeared first on Carbon Brief.
Analysis: India’s power-sector emissions flat for two years due to clean-energy surge



-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits