

Expanding and decarbonising the world’s electricity supplies is key to meeting global climate goals – and this has been reflected in a series of recent pledges.
These include the COP28 deal to triple global renewable capacity by 2030 and agreement among the G7 group of major economies to end the use of unabated coal power by 2035.
These targets contribute towards the transition away from fossil fuels and aligning energy systems with the 1.5C limit, priorities that were also agreed at COP28.
However, the proliferation of power-sector targets creates a pressing need for timely data in order to keep tabs on progress.
The new Global Energy Monitor (GEM) global integrated power tracker (GIPT) makes it easy to track progress, bringing together the latest data on power-plant developments around the world.
This article introduces the GIPT and illustrates the sorts of insights it can generate, using the example of the G7’s pledges – and progress towards meeting them.
About the tracker
The GIPT is the culmination of a decade of work since GEM created its global coal plant tracker in 2014. It currently consists of a database of 116,095 power units and is free to use.
The GIPT is a Creative Commons database based on GEM trackers for coal, gas, oil, hydropower, utility-scale solar, wind, nuclear, bioenergy and geothermal, as well as on energy ownership.
GEM’s international team manually researches each power facility in the database using governmental, corporate and media reports, as well as satellite imagery. They work in Arabic, Chinese, English, Hindi, Portuguese, Russian and Spanish.
The data is updated twice per year and is also mapped to allow geospatial analysis, with each of the underlying trackers providing various summaries and dashboard information.
Coal phaseout
The G7 pledge to phase out unabated coal power by 2035 is seen as particularly significant for the US and Japan, who host the largest coal fleets in the group.
Data in the GIPT shows that coal power capacity in G7 countries peaked at 497 gigawatts (GW) in 2010 and has since fallen 37%, to 310GW of operational capacity at the end of 2023.
A continuation in the rapid decline in operating coal capacity in the UK, France, Italy and Canada will see these countries hitting their targeted coal phaseout dates before 2030.
The parties that make up Germany’s government wrote into their coalition agreement in 2021 that the 2035-2038 deadline for coal exit should “ideally” be brought forward to 2030. However, the coalition’s commitment to this ambition is far from assured.
Japan and the US, meanwhile, still have no explicit coal phaseout target. New rules from the US Environmental Protection Agency, requiring coal plants to capture 90% of their carbon dioxide (CO2) emissions by 2032, are expected to expedite plant closures.
If firm national targets for coal-exit years are followed – and assuming a 45-year average lifetime for coal plants in Japan and the US that lack a planned retirement year – then the G7 coal fleet would not be completely phased out until the middle of this century, as shown in the figure below.


Under this current outlook for retirements there would be a 77% reduction in G7 coal plant capacity by 2035 compared to today, leaving 72GW remaining.
Yet numerous assessments suggest that developed countries – such as those in the G7 – should completely phase out unabated coal by 2030, if the world is to limit warming to 1.5C.
This goal of an end by 2030 to unabated coal power could be achieved under an accelerated phaseout of G7 coal plants, whereby the average plant lifetime drops by 10 years, as shown in the figure.
Hiding within this average, however, is a considerable number of early retirements, mostly impacting coal-reliant G7 countries, particularly the US and Japan.
GIPT data show that, under this accelerated coal retirement case, some 28% of currently operating coal capacity in Japan – 15GW – would retire before reaching 20 years of operation.
Gas proliferation
Turning to G7 gas power, the GIPT shows that capacity grew by 55% over the past two decades. Gas is now the G7’s largest source of electricity and its leading source of power sector CO2.
This is despite the lower emissions intensity – the CO2 emissions per unit of electricity – of gas compared to coal, as well as the growing contributions from renewables, notably wind and solar.
Moreover, recent analysis suggests that electricity generation in developed countries such as the G7 should be completely decarbonised by 2035 to align with the 1.5C limit. This would mean phasing out unabated gas power by 2035, after shutting down coal by 2030.
Yet an additional 73GW of new gas-fired projects are currently in development across the G7, the majority of which are in the US, as shown in the figure below.
(The GIPT classifies “in development” projects as those that have been announced or are in the pre-construction and construction phases.)

The GIPT also includes information on the ownership structure of combustion power facilities.
An analysis of common parent entities underscores the way that many of these incumbent firms have made an apparent pivot from coal to gas, rather than leaving fossil fuels behind.
For instance, the top 100 companies for coal retirements in the G7 have brought 232GW of coal plants offline since 2000. Of these, 61 companies are also active in the gas power sector and have brought some 266GW of new capacity online since that date.
This near one-to-one switching appears to weaken when considering planned coal retirements and gas additions out to 2035. Yet of the 100 companies planning the most coal retirements by 2035, every 3GW of coal coming offline is still paired with 1GW of new gas capacity in development.
Tripling renewables
In terms of renewables, the G7 declaration “welcomes” the COP28 goal of tripling capacity globally by 2030, but does not adopt a specific target for the bloc or its member countries.
Nevertheless, it is clear that the countries of the world are collectively falling short of the tripling target, with the International Energy Agency (IEA) warning in June that they are on track to be 30% short of the goal in 2030.
While the global tripling target has not been broken down into regional or national goals, the International Renewable Energy Agency (IRENA) and the International Energy Agency (IEA) have calculated regional deployment ranges that would be consistent with getting on track.
Along with monitoring government targets for renewables expansion, tracking on-the-ground project developments can provide a sense of deployment progress.
The GIPT offers this capability by cataloguing project-by-project development statuses for existing and planned power facilities.
Across the G7 and EU, GEM data shows 181GW of utility-scale solar photovoltaic (PV) and 101GW of onshore wind projects with a planned start year before 2030. Most announced start dates for these projects fall within the next two years and are comparable to the record levels of installations in 2023.
If these projects start operating on schedule, then capacity additions for 2024 and 2025 would hit the bottom of the range of the annual levels of deployment within the G7 and EU. That would be consistent with tripling by 2030 globally, as shown in the figure below.


Beyond 2025, however, the GIPT suggests deployment rates for utility solar PV and onshore wind could drop below the range consistent with a tripling of capacity. This reflects the large number of “announced” and “pre-construction” projects that are yet to issue anticipated start dates, some 228GW for utility solar and 111GW for onshore wind.
For the G7 and EU to remain on track with the “tripling-consistent” deployment pathways beyond 2025, these as-yet undated projects would need to progress through various stages of conception, permitting and tendering to “shovels in the ground”.
In the case of offshore wind, a greater proportion of projects have anticipated start dates. Should these offshore projects reach commercial operation on time, then the deployment rates averaging 16GW per year sit within the range of deployment consistent with tripling.
On the other hand, the wind industry has faced numerous project delays and cancellations as a result of rising interest rates and increased commodity costs.
Indeed, 15% of offshore wind projects in the G7 were either cancelled or shelved between mid-2023 and mid-2024, with a further 22GW seeing slippage in anticipated commercial operation date.
Despite these challenges, a vast 303GW pipeline of G7 offshore wind projects sits in “announced” and “pre-development” stages, albeit without a target commercial operation date.
Converting around 3% of this project pipeline into operational wind farms per year would achieve a “tripling-consistent” capacity increase by 2030. Such a conversion rate was already seen between 2022 and 2023 across European countries.


The post Guest post: Tracking G7 climate progress with data from 116,095 power plants appeared first on Carbon Brief.
Guest post: Tracking G7 climate progress with data from 116,095 power plants

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
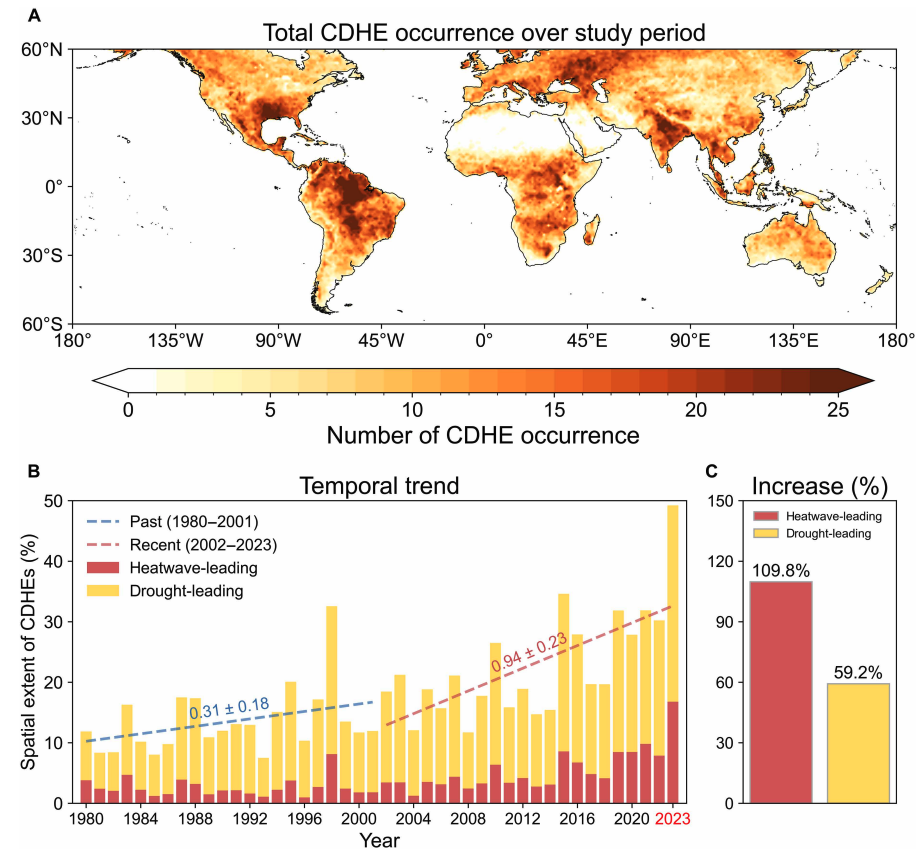
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: Bloomberg reported on increases in diesel prices in Europe and the US, speculating that rising fuel costs could be “a risk for president Donald Trump”. US gas producers are “poised to benefit from the big disruption in global supply”, according to CNBC. Indian government sources told the Economic Times that Russia is prepared to “fulfil India’s energy demands”. China Daily quoted experts who said “China’s energy security remains fundamentally unshaken”, thanks to “emergency stockpiles and a wide array of import channels”.
‘ESSENTIAL’ RENEWABLES: Energy analysts said governments should cut their fossil-fuel reliance by investing in renewables, “rather than just seeking non-Gulf oil and gas suppliers”, reported Climate Home News. This message was echoed by UK business secretary Peter Kyle, who said “doubling down on renewables” was “essential” amid “regional instability”, according to the Daily Telegraph.
China’s climate plan
PEAK COAL?: China has set out its next “five-year plan” at the annual “two sessions” meeting of the National People’s Congress, including its climate strategy out to 2030, according to the Hong Kong-based South China Morning Post. The plan called for China to cut its carbon emissions per unit of gross domestic product (GDP) by 17% from 2026 to 2030, which “