


As the global energy landscape evolves, one material has emerged as a cornerstone for both renewable energy and defense sectors: antimony. This versatile mineral is pivotal in solar technology, battery advancements, and military applications.
However, recent geopolitical tensions have highlighted vulnerabilities in its supply chain, emphasizing the need for nations to secure sustainable sources. Companies like Military Metals Corp are stepping up to bridge the gap, ensuring antimony’s availability in an increasingly resource-scarce world.
Renewable Energy’s Secret Weapon
The transition to renewable energy relies heavily on advanced materials, and antimony is no exception. In solar panels, this mineral enhances the efficiency of perovskite solar cells by improving light absorption and charge transport. This results in higher energy conversion rates, making solar panels more effective at capturing sunlight.
Additionally, antimony compounds increase thermal stability, allowing panels to endure extreme conditions without frequent replacements.
Energy storage is another area where antimony shines. Liquid-metal batteries, a promising solution for storing solar energy, depend on antimony’s unique properties. These batteries enable efficient capture and distribution of excess solar power, addressing the intermittency challenges of renewable energy sources.
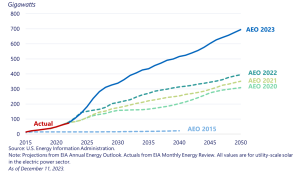
With solar installations projected to grow exponentially, antimony’s role in making this energy transition feasible cannot be overstated. The EIA projects solar capacity to reach over 300 GW by 2030 and around 700 GW by 2050.
The Silent Shield: Antimony’s Role in Defense Systems
Beyond renewable energy, antimony is indispensable to national security. The Department of Defense (DoD) uses this critical mineral in 200+ types of munitions, including percussion primers, stab detonators, and armor-piercing rounds.
Moreover, antimony alloys enhance the durability and reliability of lead-acid batteries used in military vehicles and equipment.
Antimony’s role in flame retardants further underscores its importance in defense. Military uniforms, equipment, and vehicles rely on antimony-based compounds for fire resistance, ensuring the safety of personnel in combat scenarios. Furthermore, antimony-containing semiconductors are critical for infrared sensors and night-vision devices, key technologies for modern warfare.
Breaking China’s Grip: Global Efforts to Secure Antimony Supplies
China controls nearly 50% of global antimony mining and 80% of processing, creating a bottleneck in the supply chain. Recent export restrictions by China, citing dual-use applications of the mineral for both civilian and military purposes, have exacerbated this dependence.
These restrictions pose significant challenges for countries like the United States, which relies on imports for over 80% of its antimony consumption.
China’s export controls also affect antimony’s availability for renewable energy technologies. The U.S. solar industry, a critical player in the clean energy transition, faces potential disruptions due to limited access to the material for solar panel production.
As trade tensions escalate, securing alternative sources becomes a strategic imperative. Antimony is one of the critical minerals that China restricted export more recently in October this year.
Diversifying Antimony: The Key to Supply Chain Resilience
Countries worldwide are taking steps to reduce reliance on Chinese antimony.
Over two years, global antimony drilling activity totaled 625 holes, with 88 yielding significant intervals. Australia dominated with 444 holes, including 65 significant finds, reflecting its active exploration sector. The USA followed with 44 holes and 10 significant intervals.
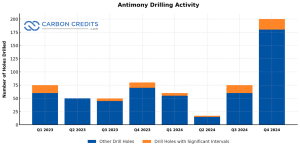
Other contributions came from Canada, New Zealand, and Namibia. Emerging interest in regions like Bosnia, Indonesia, and Slovakia highlights a global push to secure antimony resources, driven by rising demand in energy and defense sectors.
This data underscores strategic exploration efforts amid tight global supply chains and geopolitical tensions impacting mineral accessibility.
- In the U.S., the Department of Defense awarded $15.5 million to Perpetua Resources to explore antimony production from the Stibnite Gold Project in Idaho.
Similarly, Spearmint Resources in Canada has doubled its acreage at the George Lake South Antimony Project, recognizing the mineral’s strategic value.
Moreover, international collaboration is gaining momentum. Nations like Australia, Belgium, and India are investing in antimony processing facilities. Meanwhile, African countries such as Mozambique and Tanzania are emerging as alternative mining hubs. These efforts aim to create resilient supply chains that can withstand geopolitical shocks.
Antimony’s dual role in solar technology and defense highlights its unique importance. This underscores the need for a balanced approach to resource allocation, ensuring that both renewable energy goals and national security needs are met.
The escalating U.S.-China trade war further complicates this balance. Tariffs, export restrictions, and retaliatory measures threaten to disrupt global markets, making it imperative for industries to innovate and adapt.
Surging Prices and Market Outlook
The global antimony market is under intense pressure due to surging demand and constrained supply. In December 2024, antimony trioxide prices soared by almost 232% compared to last year, reaching $38,000 per metric ton. This is largely driven by China’s export restrictions and heightened geopolitical tensions.
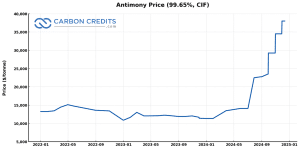
The mineral’s critical role in defense, solar panels, and battery technologies has made it a highly sought-after resource.
Global demand for antimony is expected to rise sharply in the coming years, particularly as renewable energy and defense sectors expand. Analysts predict that its market value could grow significantly, driven by advancements in solar technology, energy storage, and defense applications.
Demand for this critical mineral is forecasted to reach $3.5 billion by 2030. However, the market remains vulnerable to supply chain disruptions, with China’s dominance continuing to exert influence on global prices.
Efforts to address these challenges include investments in alternative sources and recycling initiatives. Countries like the U.S. and Canada are accelerating domestic production, while companies like Military Metals Corp are spearheading exploration projects to tap into previously untapped reserves.
Military Metals Corp: Leading the Antimony Revolution
Military Metals Corp is an emerging key player in ensuring a stable antimony supply. The company’s strategic assets in Slovakia and Canada aim to reduce dependency on Chinese imports by revitalizing historical mining sites with untapped potential.
Trojarova, Slovakia: Military Metals has identified significant antimony-gold mineralization at this site, with historical estimates indicating high-grade deposits. By extending underground adits and exploring deeper veins, the company plans to unlock valuable resources for both defense and renewable energy applications.
West Gore, Nova Scotia: Once Canada’s largest antimony producer, this site holds immense potential for modern exploration. Historical data suggests significant quantities of this mineral and gold in waste dumps and tailings, providing a cost-effective avenue for resource extraction.
Military Metals’ commitment to sustainable practices and strategic exploration ensures a reliable supply of antimony, bolstering both energy independence and defense readiness.
What Comes Next for Antimony?
To meet antimony’s growing demand, a multi-faceted approach is essential:
- Investment in Domestic Mining: Expanding mining operations in countries like the U.S. and Canada can reduce reliance on imports and strengthen supply chain resilience.
- Technological Innovation: Developing alternative materials and recycling methods can alleviate pressure on antimony resources.
- International Cooperation: Collaborative efforts among nations can diversify supply chains and ensure equitable access to critical minerals.
Antimony is more than just a mineral; it is a linchpin for renewable energy and national security. As the world navigates the complexities of the clean energy transition and geopolitical tensions, ensuring a stable supply of this critical resource is paramount. The time to act is now, and antimony’s story is one of resilience, innovation, and opportunity.
- READ MORE: Trump’s Tactic to Make America Great Again: Expanding Domestic Oil, Gas, and Critical Minerals
The post Antimony: The Unsung Hero of Solar Energy and National Defense appeared first on Carbon Credits.

Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits