

China’s carbon dioxide (CO2) emissions fell by 1% in the final quarter of 2025, likely securing a decline of 0.3% for the full year as a whole.
This extends a “flat or falling” trend in China’s CO2 emissions that began in March 2024 and has now lasted for nearly two years.
The new analysis for Carbon Brief shows that, in 2025, emissions from fossil fuels increased by an estimated 0.1%, but this was more than offset by a 7% decline in CO2 from cement.
Other key findings include:
- CO2 emissions fell year-on-year in almost all major sectors in 2025, including transport (3%), power (1.5%) and building materials (7%).
- The key exception was the chemicals industry, where emissions grew 12%.
- Solar power output increased by 43% year-on-year, wind by 14% and nuclear 8%, helping push down coal generation by 1.9%.
- Energy storage capacity grew by a record 75 gigawatts (GW), well ahead of the rise in peak demand of 55GW.
- This means that growth in energy storage capacity and clean-power output topped the increases in peak and total electricity demand, respectively.
The CO2 numbers imply that China’s carbon intensity – its fossil-fuel emissions per unit of GDP – fell by 4.7% in 2025 and by 12% during 2020-25.
This is well short of the 18% target set for that period by the 14th five-year plan.
Moreover, China would now need to cut its carbon intensity by around 23% over the next five years in order to meet one of its key climate commitments under the Paris Agreement.
Whether Chinese policymakers remain committed to this target is a key open question ahead of the publication of the 15th five-year plan in March.
This will help determine if China’s emissions have already passed their peak, or if they will rise once again and only peak much closer to the officially targeted date of “before 2030”.
‘Flat or falling’
The latest analysis shows China’s CO2 emissions have now been flat or falling for 21 months, starting in March 2024. This trend continued in the final quarter of 2025, when emissions fell by 1% year-on-year.
The picture continues to be finely balanced, with emissions falling in all major sectors – including transport, power, cement and metals – but rising in the chemicals industry.
This combination of factors means that emissions continue to plateau at levels slightly below the peak reached in early 2024, as shown in the figure below.
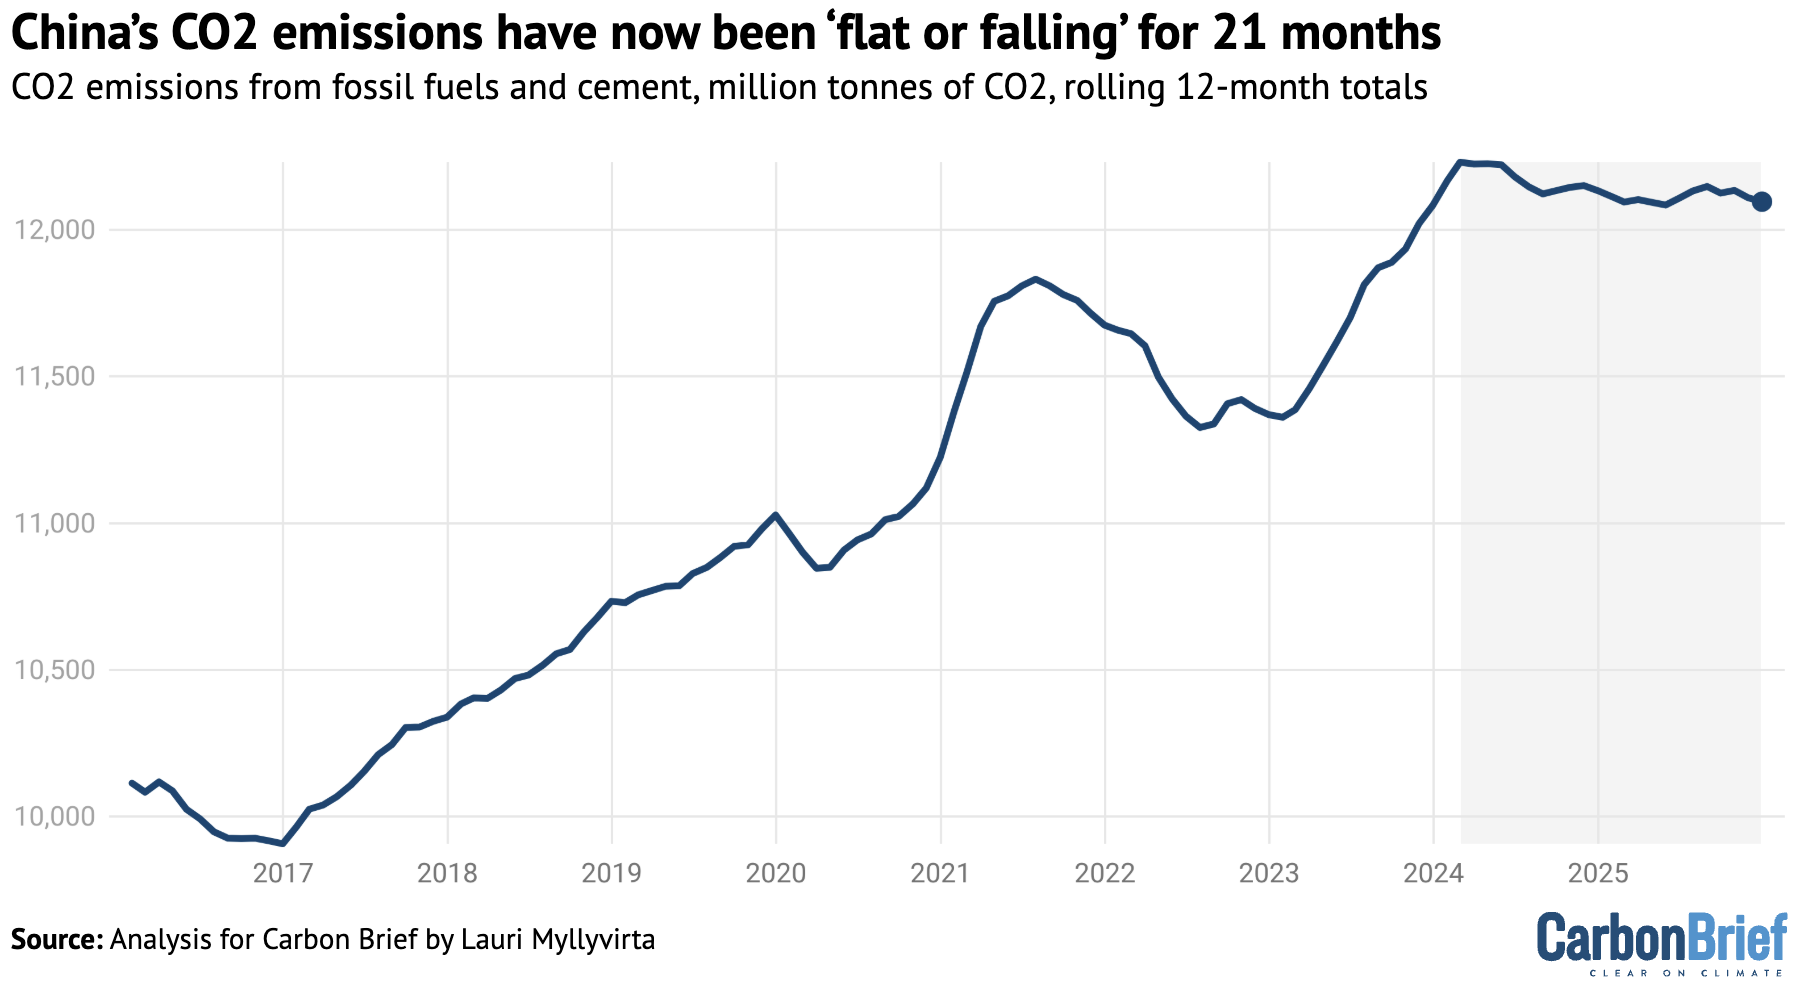
Power sector emissions fell by 1.5% year-on-year in 2025, with coal use falling 1.7% and gas use increasing 6%. Emissions from transportation fell 3% and from the production of cement and other building materials by 7%, while emissions from the metal industry fell 3%.
These declines are shown in the figure below. They were partially offset by rising coal and oil use in the chemical industry, up 15% and 10% respectively, which pushed up the sector’s CO2 emissions by 12% overall.

In other sectors – largely other industrial areas and building heat – gas use increased by 2%, more than offsetting the reduction in emissions from a 3% drop in their coal consumption.
Clean power covers electricity demand growth
In the power sector, which is China’s largest emitter by far, electricity demand grew by 520 terawatt hours (TWh) in 2025.
At the same time, power generation from solar increased by 43% and wind power generation by 14%, delivering 360TWh and 130TWh of additional clean electricity. Nuclear power generation grew 8%, supplying another 40TWh. The increased generation from these three sources – some 530TWh – therefore met all of the growth in demand.
Hydropower generation also increased by 3% and bioenergy by 3%, helping push power generation from fossil fuels down by 1%. Gas-fired power generation increased by 6% and, as a result, power generation from coal fell by 1.9%.
Furthermore, the surge in additions of new wind and solar capacity at the end of 2025 will only show up as increased clean-power generation in 2026.
On the other hand, the growth in solar and wind power generation has fallen short of the growth in capacity, implying a fall in capacity utilisation – a measure of actual output relative to the maximum possible. This is highly likely due to increased, unreported curtailment, where wind and solar sites are switched off because the electricity grid is congested.
If these grid issues are resolved over the next few years, then generation from existing wind and solar capacity will increase over time.
Developments in 2025 extended the trend of clean-power generation growing faster than power demand overall, as shown in the top figure below. This trend started in 2023 and is the key reason why China’s emissions have been stable or falling since early 2024.
In addition, 2025 saw another potential inflection point, shown in the bottom figure below. It was the first year ever that energy storage capacity – mainly batteries – grew faster than peak electricity demand in 2025 and faster than the average growth in the past decade.
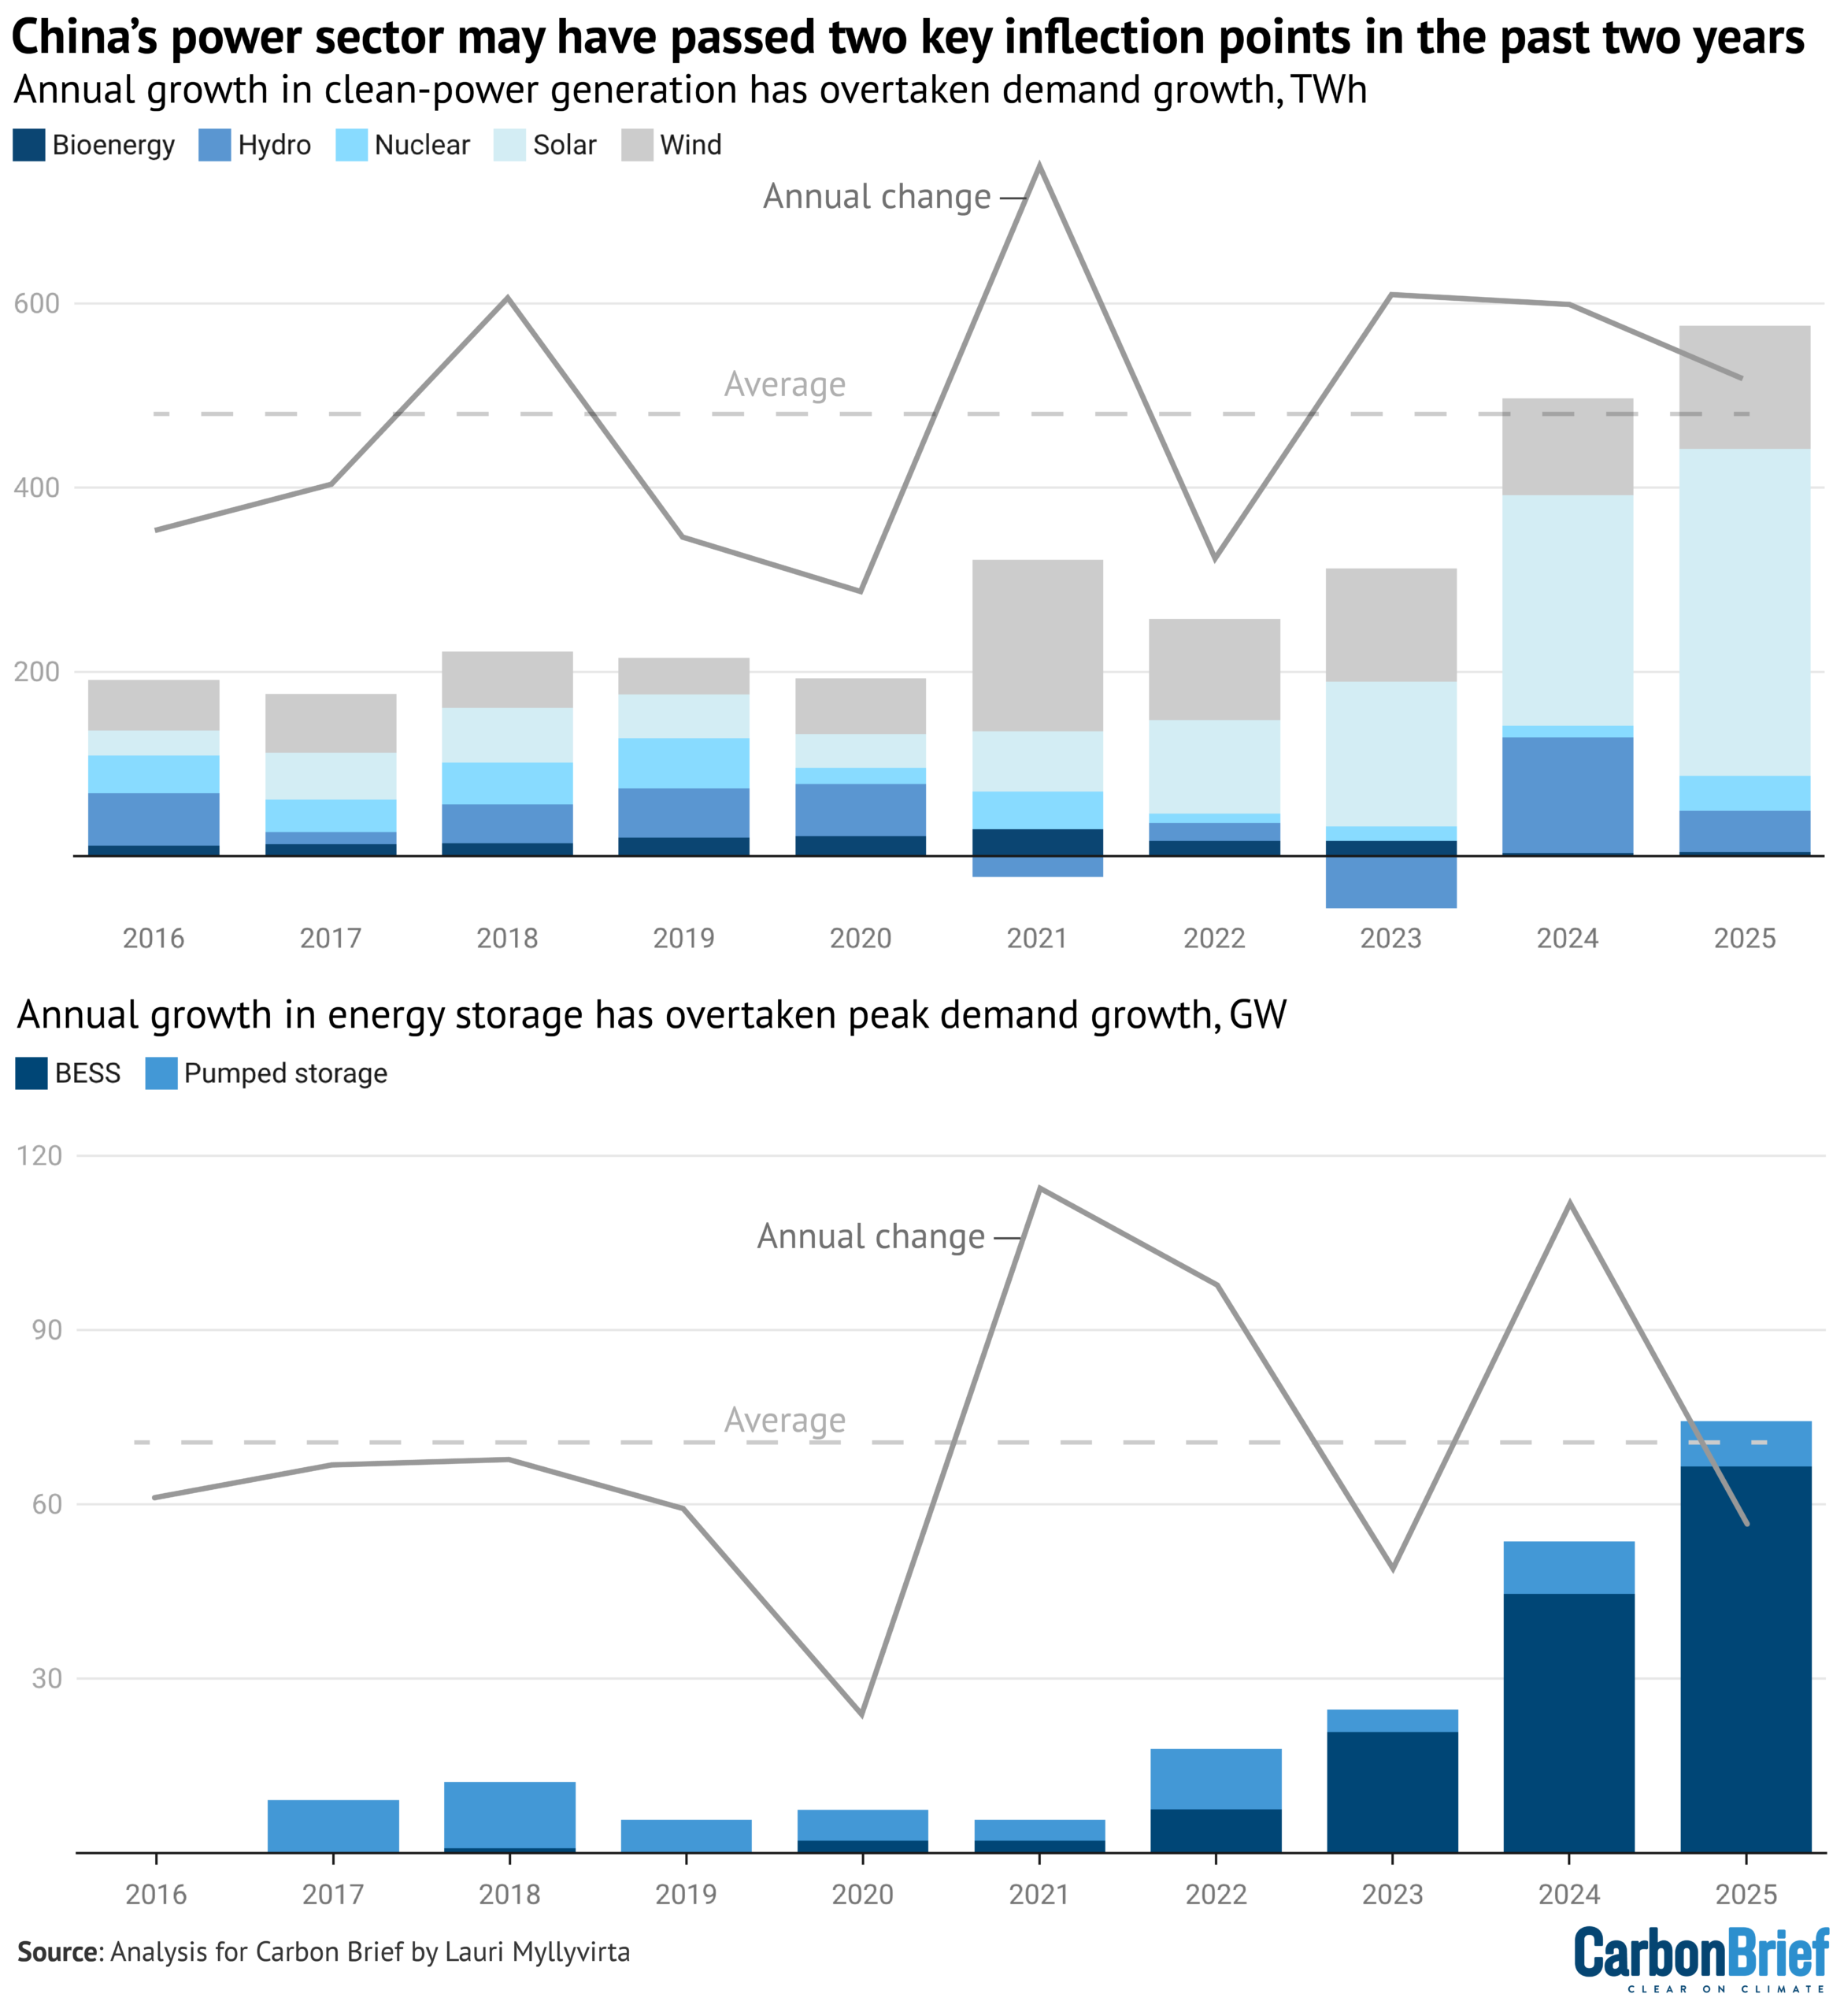
China’s energy storage capacity increased by 75GW year-on-year in 2025, while peak demand only increased by 55GW. The rise in storage capacity in 2025 is also larger than the three-year average increase in peak loads, some 72GW per year.
Peak demand growth matters, because power systems have to be designed to reliably provide enough electricity supply at the moment of highest demand.
Moreover, the increase in peak loads is a key driver of continued additions of coal and gas-fired power plants, which reached the highest level in a decade in 2025.
The growth in energy storage could provide China with an alternative way to meet peak loads without relying on increased fossil fuel-based capacity.
The growth in storage capacity is set to continue after a new policy issued by China’s top economic planner the National Development and Reform Commission (NDRC) in January.
This policy means energy storage sites will be supported by so-called “capacity payments”, which to date have only been available to coal- and gas-fired power plants and pumped hydro storage.
Concerns about having sufficient “firm” power capacity in the grid – that which can be turned on at will – led the government to promote new coal and gas-fired power projects in recent years, leading to the largest fossil-fuel based capacity additions in a decade in 2025, with another 290GW of coal-fired capacity still under construction.
Reforming the power system and increasing storage capacity would enable the grid to accommodate much higher shares of solar and wind, while reducing the need for new coal or gas capacity to meet rising peaks in demand.
This would both unlock more clean-power generation from existing capacity and improve the economics and risk profiles of new projects, stimulating more growth in capacity.
Peaking power CO2 requires more clean-energy growth
China’s key climate commitments for the next five-year period until 2030 are to peak CO2 emissions and to reduce carbon intensity by more than 65% from 2005 levels. The latter target requires limiting CO2 emissions at or below their 2025 level in 2030.
The record clean-energy additions in 2023-25 have barely sufficed to stabilise power-sector emissions, showing that if rapid growth in power demand continues, meeting the 2030 targets requires keeping clean-energy additions close to 2025 levels over the next five years.
China’s central government continues to telegraph a much lower level of ambition, with the NDRC setting a target of “around” 30% of power generation in 2030 coming from solar and wind, up from around 22% in 2025.
If electricity demand grows in line with the State Grid forecast of 5.6% per year, then limiting the share of wind and solar to 30% would leave space for fossil-fuel generation to grow at 3% per year from 2025 to 2030, even after increases from nuclear and hydropower.
Such an increase would mean missing China’s Paris commitments for 2030.
Alternatively, in order to meet the forecast increase in electricity demand without increasing generation from fossil fuels would require wind and solar’s share to reach 37% in 2030.
Similarly, China’s target of a non-fossil energy share of 25% in 2030 will not be sufficient to meet its carbon-intensity reduction commitment for 2030, unless energy demand growth slows down sharply.
This target is unlikely to be upgraded, since it is already enshrined in China’s Paris Agreement pledge, so in practice the target would need to be substantially overachieved if the country is to meet its other commitments.
If energy demand growth continues at the 2025 rate and the share of non-fossil energy only rises from 22% in 2025 to 25% in 2030, then the consumption of fossil fuels would increase by 3% per year, with a similar rise in CO2 emissions.
Still, another recent sign that clean-energy growth could keep exceeding government targets came in early February when the China Electricity Council projected solar and wind capacity additions of more than 300GW in 2026 – well beyond the government goal of “over 200GW”.
Chemical industry
The only significant source of growth in CO2 emissions in 2025 was the chemical industry, with sharp increases in the consumption of both coal and oil.
This is shown in the figure below, which illustrates how CO2 emissions appear to have peaked from cement production, transport, the power sector and others, whereas the chemicals industry is posting strong increases.
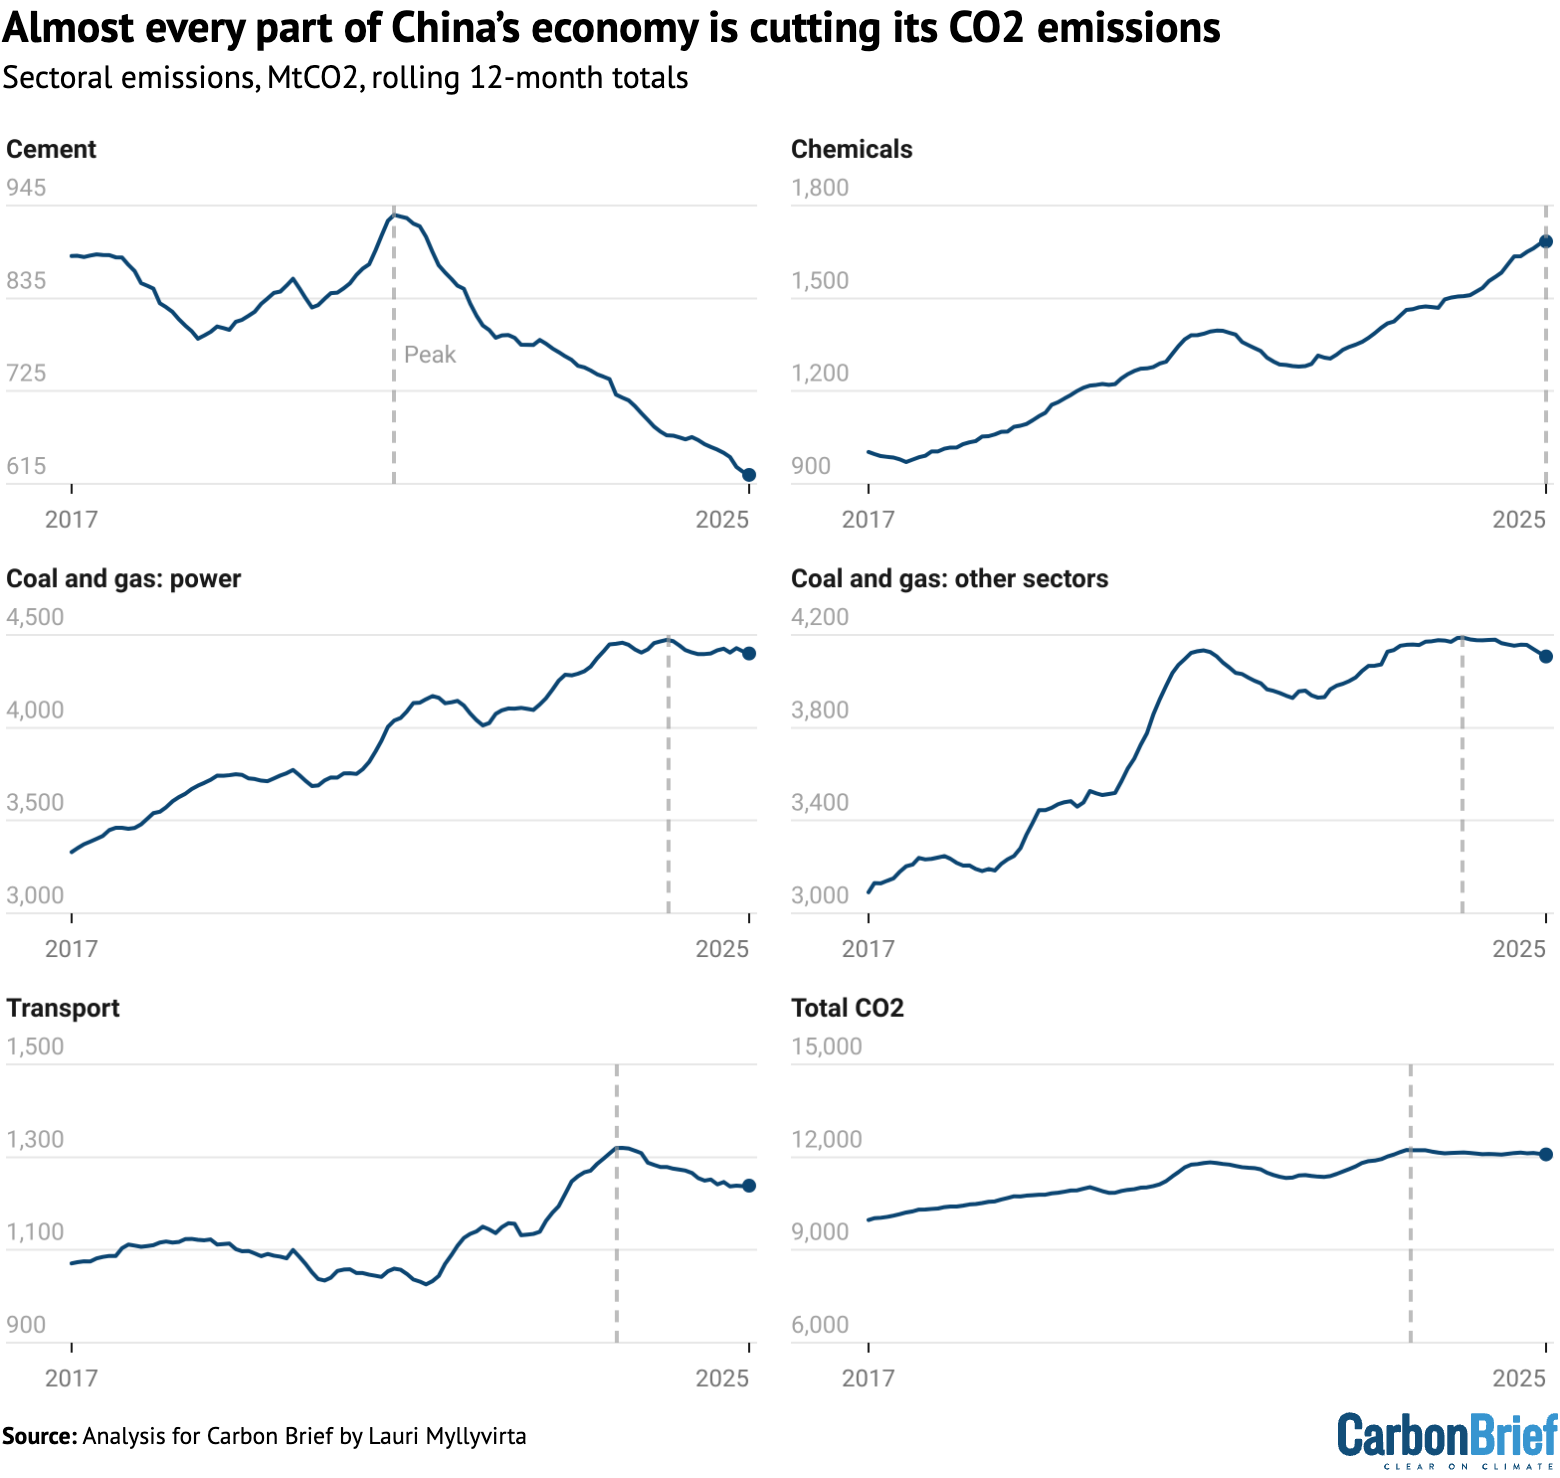
Even though chemical-industry emissions are small relative to other sectors – at roughly 13% of China’s total – the pace of expansion is creating an outsize impact.
Without the increase from the chemicals sector, China’s total CO2 emissions would have fallen by an estimated 2%, instead of the 0.3% reported here.
Without changes to policy, emission growth is set to continue, as the coal-to-chemicals industry is planning major increases in capacity.
Whether these expansion plans receive backing in the upcoming five-year plan for 2026-30 will have a major impact on China’s emission trends.
Another key factor is the development of oil and gas prices. Production in the coal-based chemical industry is only profitable when coal is significantly cheaper than crude oil.
The current coal-to-chemicals capacity in China is dominated by plants producing higher-value – and therefore less price-sensitive – chemicals such as olefins and aromatics, as feedstocks for the production of plastics.
In contrast, the planned expansion of the sector is expected to be largely driven by plants producing oil products and synthetic gas to be used for energy. For these products, electrification and clean-electricity generation provide a direct alternative, meaning they are even more sensitive to low oil and gas prices than chemicals production.
Outlook for China’s emissions
This is the latest analysis for Carbon Brief to show that China’s CO2 emissions have now been stable or falling for seven quarters or 21 months, marking the first such streak on record that has not been associated with a slowdown in energy demand growth.
Notably, while emissions have stabilised or begun a slow decline, there has not yet been a substantial reduction from the level reached in early 2024. This means that a small jump in emissions could see them exceed the previous peak level.
China’s official plans only call for peaking emissions shortly before 2030, which would allow for a rebound from the current plateau before the ultimate emissions peak.
If China is to meet its 2030 carbon intensity commitment – a 65% reduction on 2005 levels – then emissions would have to fall from the peak back to current levels by 2030.
Whether China’s policymakers are still committed to meeting this carbon intensity pledge, after the setbacks during the previous five-year period, is a key open question. The 2030 energy targets set to date have fallen short of what would be required.
The most important signal will be whether the top-level five-year plan for 2026-30, due in March, sets a carbon intensity target aligned with the 2030 Paris commitment.
Officially, China is sticking to the timeline of peaking CO2 emissions “before 2030”, which was announced by president Xi Jinping in 2020.
According to an authoritative explainer on the recommendations of the Central Committee of the Communist Party for the upcoming five-year plan, published by state-backed news agency Xinhua, coal consumption should “reach its peak and enter a plateau” from 2027.
It says that continued increases in demand for coal from electricity generators and the chemicals industry would be offset by reductions elsewhere. This is despite the fact that China’s coal consumption overall has already been falling for close to two years.
The reference to a “plateau” in coal consumption indicates that in official plans, meaningful absolute reductions in emissions would have to wait until after 2030. Any increase in coal consumption from 2025 to 2027, before the targeted plateau, would need to be offset by reductions in oil consumption, to meet the carbon intensity target.
Moreover, allowing coal consumption in the power sector to grow beyond the peak of overall coal use and emissions implies slowing down China’s clean-energy boom. So far, the boom has continued to exceed official targets by a wide margin.
In addition, the explainer’s expectation of further growth in coal use by the chemicals industry indicates a green light for at least a part of its sizable expansion plans.
The Xinhua article recognises that oil product consumption has already peaked, but says that oil use in the chemicals industry has kept growing. It adds that overall oil consumption should peak in 2026.
Elsewhere, the article speaks of “vigorously” developing non-fossil energy and “actively” developing “distributed” solar, which has slowed down due to recent pricing policies.
Yet it also calls for “high-quality development” of fossil fuels and increased efforts in domestic oil and gas production, suggesting that China continues to take an “all of the above” approach to energy policy.
The outcome of all this depends on how things turn out in reality. The past few years show it is possible that clean energy will continue to overperform its targets, preventing growth in energy consumption from fossil fuels despite this policy support.
The key role of the clean-energy boom in driving GDP growth and investments is one key motivator for policymakers to keep the boom going, even when central targets would allow for a slowdown. It is also possible that the five-year plans of provinces and state-owned enterprises could play a key role in raising ambition, as they did in 2022.
About the data
Data for the analysis was compiled from the National Bureau of Statistics of China, National Energy Administration of China, China Electricity Council and China Customs official data releases, as well as from industry data provider WIND Information and from Sinopec, China’s largest oil refiner.
Electricity generation from wind and solar, along with thermal power breakdown by fuel, was calculated by multiplying power generating capacity at the end of each month by monthly utilisation, using data reported by China Electricity Council through Wind Financial Terminal.
Total generation from thermal power and generation from hydropower and nuclear power were taken from National Bureau of Statistics monthly releases.
Monthly utilisation data was not available for biomass, so the annual average of 52% for 2023 was applied. Power-sector coal consumption was estimated based on power generation from coal and the average heat rate of coal-fired power plants during each month, to avoid the issue with official coal consumption numbers affecting recent data.
CO2 emissions estimates are based on National Bureau of Statistics default calorific values of fuels and emissions factors from China’s latest national greenhouse gas emissions inventory, for the year 2021. The CO2 emissions factor for cement is based on annual estimates up to 2024.
For oil, apparent consumption of transport fuels – diesel, petrol and jet fuel – is taken from Sinopec quarterly results, with monthly disaggregation based on production minus net exports. The consumption of these three fuels is labeled as oil product consumption in transportation, as it is the dominant sector for their use.
Apparent consumption of other oil products is calculated from refinery throughput, with the production of the transport fuels and the net exports of other oil products subtracted. Fossil-fuel consumption includes non-energy use such as plastics, as most products are short-lived and incineration is the dominant disposal method.
The post Analysis: China’s CO2 emissions have now been ‘flat or falling’ for 21 months appeared first on Carbon Brief.
Analysis: China’s CO2 emissions have now been ‘flat or falling’ for 21 months

Climate Change
FLIP OFF WOODSIDE TO SAVE SCOTT REEF: Greenpeace, Michael Caton, Thinkerbell mobilise Australia to challenge gas project at Scott Reef

6 November 2026
Greenpeace Australia Pacific has joined forces with Thinkerbell and iconic Australian actor Michael Caton on a major public movement and behaviour change initiative to save Scott Reef, calling on Australians to “flip off” gas corporation Woodside. The company plans to drill for gas at Australia’s largest oceanic reef, home to vulnerable green sea turtles, endangered pygmy blue whales, and thousands of marine species, off the coast of Western Australia.
WATCH THE FULL VIDEO HERE
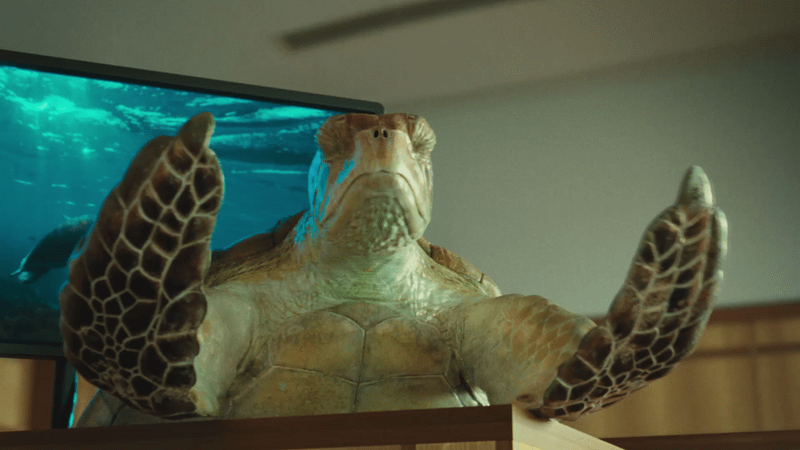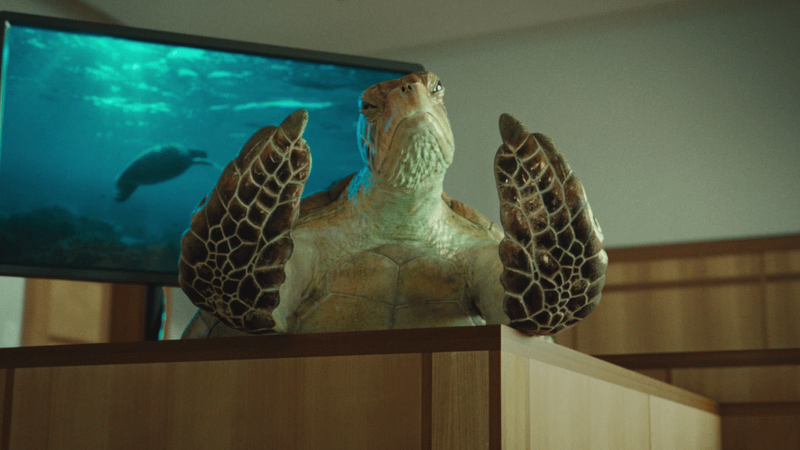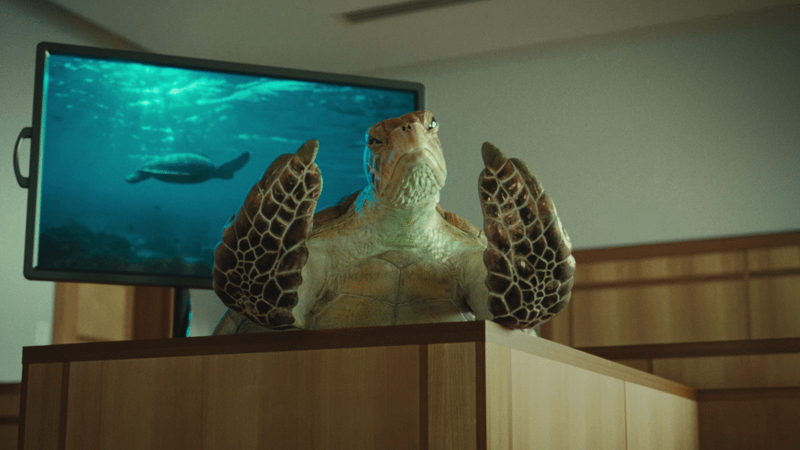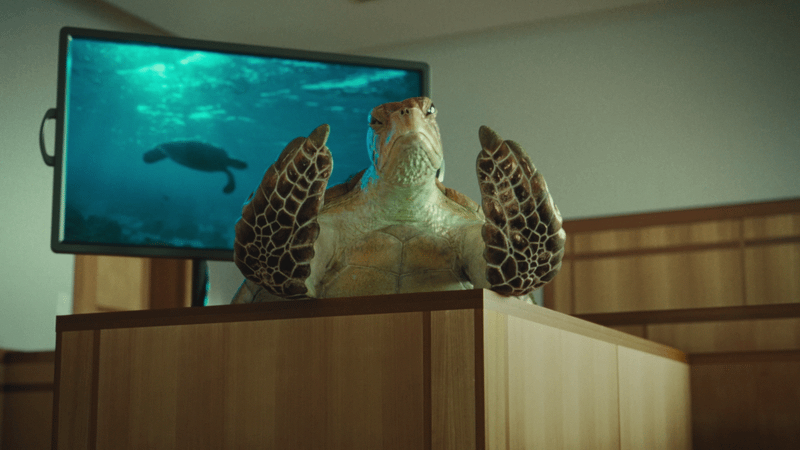
At the heart of the collaboration is somebody who knows a thing or two about fighting off corporations to protect a home: Michael Caton. Set in a courtroom, Caton gives his voice to a voiceless inhabitant, a green sea turtle, and together they invite the public to show their support to save Scott Reef.
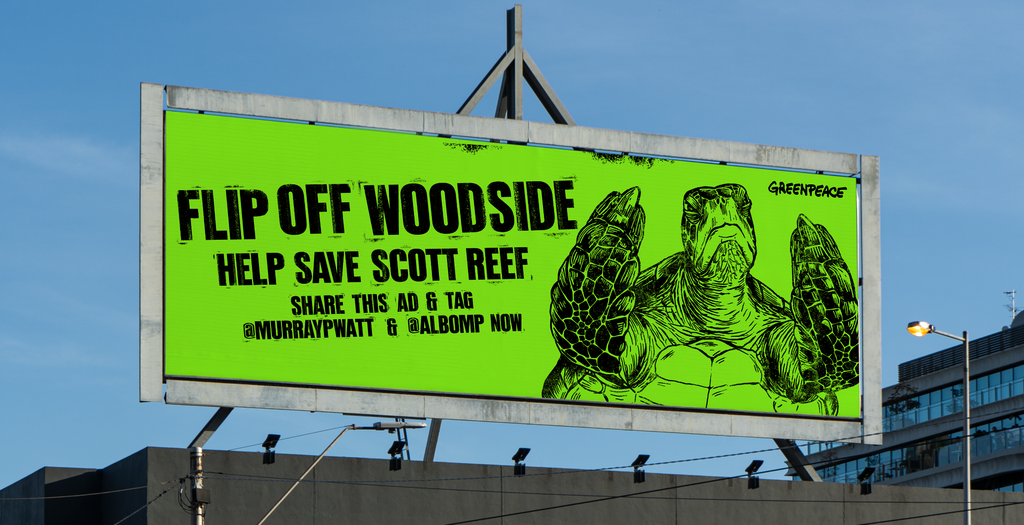
Designed to shift public behaviour and drive national debate, the movement asks the public to tag their MPs – applying direct political pressure on Environment Minister Murray Watt and Prime Minister Albanese Albanese to “flip off” Woodside’s dirty gas project, which would see up to 57 toxic wells drilled around Scott Reef off the coast of Western Australia.
Voiced by Michael Caton and set to a soundtrack provided by Radiohead, the narrative centres on our hero turtle defending her home from corporate overreach in a courtroom showdown. As the turtle defiantly flips her flippers at Woodside, Michael Caton calls on everyday Australians to take a stand and help save her home.
Michael Caton said: “I’m proud to lend my voice to Greenpeace to help save Scott Reef. The marine life out there can’t speak up, so we need to. Some things are too precious to risk.”
Glenn Walker, Head of Nature at Greenpeace Australia Pacific, added: “Woodside’s dirty gas project at Scott Reef, Australia’s largest oceanic reef, is an environmental disaster waiting to happen, threatening thousands of species, including the extremely vulnerable green sea turtles that nest there. By literally flipping off Woodside and Big Gas, Aussies are cutting through corporate spin and sending an unignorable message to Environment Minister Murray Watt and the Albanese government: save Scott Reef.”
Adam Ferrier, co-founder of Thinkerbell, said: “You can fight a corporation in the courtroom forever, but the real power to deliver lasting protection rests in parliament. Right now, our MPs hold an extraordinary opportunity to safeguard Scott Reef for generations to come. I’m proudly from WA, and I know how much the natural environment means to the people and economy of Western Australia. I’m also sure Woodside wants to do the right thing, and with enough public support and government action we’ll together save Scott Reef.
Paul Swann, Chief Creative Tinker at Thinkerbell notes: “When the stakes are this high, polite ads don’t work. You need an unignorable provocation that galvanises people and puts the pressure squarely where it belongs, on our leaders in Canberra. This isn’t just about protecting a reef; it’s about holding power to account.”
Greenpeace has been campaigning to stop Woodside’s dirty gas plans for years, increasing pressure on the Australian government to save Scott Reef from becoming an industrialised gas zone. From actions aboard Woodside’s gas platform to cinemas across Australia, Greenpeace isn’t backing off in their advocacy to save Scott Reef.
Rolling out across OOH, digital, social and cinema with an interactive landing page, this project will be amplified by high-profile figures urging Australians to take action, tag their MPs, and defend Scott Reef. The movement combines cinematic storytelling with organic social mobilsation and earned media, planned via Thinkerbell’s Alchemy model to drive real behaviour change and impact.
Marking their first Australian tour in 15 years, English rock band Radiohead will play 16 arena shows across Perth, Melbourne and Sydney in May and June 2027. A $2 donation is included in every ticket price with proceeds going to Greenpeace Australia Pacific and the Australian Marine Conservation Society. Radiohead will match the final amount raised.
ENDS
WATCH NOW:
FOR ASSETS OR MORE INFORMATION, PLEASE CONTACT:
Adam Ferrier | 0413 633 344 | adamferrier@thinkerbell.com
Kimberley Bernard | 0407 581 404 | kbernard@greenpeace.org
ABOUT THINKERBELL
Thinkerbell is a 9-year-old independent creative company. We practise Measured Magic – the coming together of marketing science and hardcore creativity – to help our clients build their brands and change behaviour.
ABOUT GREENPEACE
Greenpeace Australia Pacific is a global independent campaigning organisation that uses peaceful protest and creative confrontation to expose environmental problems and promote solutions that are essential to a green and peaceful future.
Climate Change
Jimmy Barnes, King Gizz lead Aussie music supergroup on new release to save Scott Reef
SYDNEY, Monday 9 November 2026 — Australian music icons Jimmy Barnes AO, King Gizzard & the Lizard Wizard, Fred Leone, Gordi & Montaigne are among the more than 20 Australian artists who have joined forces to release a new song with an urgent message: save Scott Reef.
Released today, “If Not Now” is a reimagining of King Gizzard & the Lizard Wizard’s Environmental Music Prize-winning song “If Not Now, Then When?”, and is a collaboration between Greenpeace Australia Pacific, Green Music Australia, and p(doom) Records.
Scott Reef is a 15-million-year-old ancient coral reef located 270 kilometres off the Kimberley coast of Western Australia. It is Australia’s largest oceanic reef and is home to thousands of marine animals and endangered species, but fossil fuel corporation Woodside plans to drill up to 57 toxic wells under and around the reef, threatening to turn it into an industrial gas zone.
“If Not Now” is the reef’s first and only release, out on all digital platforms and on limited edition 7” vinyl. The song is accompanied by cover art and visualiser from acclaimed Australian artist and ARIA-winning music video director Jonathan Zawada (Flume, The Avalanches).