

China’s central and local governments, as well as state-owned enterprises, are busy preparing for the next five-year planning period, spanning 2026-30.
The top-level 15th five-year plan, due to be published in March 2026, will shape greenhouse gas emissions in China – and globally – for the rest of this decade and beyond.
The targets set under the plan will determine whether China is able to get back on track for its 2030 climate commitments, which were made personally by President Xi Jinping in 2021.
This would require energy sector carbon dioxide (CO2) emissions to fall by 2-6% by 2030, much more than implied by the 2035 target of a 7-10% cut from “peak levels”.
The next five-year plan will set the timing and the level of this emissions peak, as well as whether emissions will be allowed to rebound in the short term.
The plan will also affect the pace of clean-energy growth, which has repeatedly beaten previous targets and has become a key driver of the nation’s economy.
Some 250-350 gigawatts (GW) of new wind and solar would be needed each year to meet China’s 2030 commitments, far above the 200GW being targeted.
Finally, the plans will shape China’s transition away from fossil fuels, with key sectors now openly discussing peak years for coal and oil demand, but with 330GW of new coal capacity in the works and more than 500 new chemical industry projects due in the next five years.
These issues come together in five key questions for climate and energy that Chinese policymakers will need to answer in the final five-year plan documents next year.
Five-year plans and their role in China
1. Will the plan put China back on track for its 2030 Paris pledge?
2. Will the plan upgrade clean-energy targets or pave the way to exceed them?
3. Will the plan set an absolute cap on coal consumption?
4. Will ‘dual control’ of carbon prevent an emission rebound?
5. Will it limit coal-power and chemical-industry growth?
Five-year plans and their role in China
Five-year plans are an essential part of China’s policymaking, guiding decision-making at government bodies, enterprises and banks. The upcoming 15th five-year plan will cover the years 2026-30, set targets for 2030 and use 2025 as its base year.
The top-level five-year plan will be published in March 2026 and is known as the five-year plan on economic and social development. This overarching document will be followed by dozens of sectoral plans, as well as province- and company-level plans.
The sectoral plans are usually published in the second year of the five-year period, meaning they would be expected in 2027.
There will be five-year plans for the energy sector, the electricity sector, for renewable energy, nuclear, coal and many other sub-sectors, as well as plans for major industrial sectors such as steel, construction materials and chemicals.
It is likely that there will also be a plan for carbon emissions or carbon peaking and a five-year plan for the environment.
During the previous five-year period, the plans of provinces and state-owned enterprises for very large-scale solar and wind projects were particularly important, far exceeding the central government’s targets.
The five-year plans create incentives for provincial governments and ministries by setting quantified targets that they are responsible for meeting. These targets influence the performance evaluations of governors, CEOs and party secretaries.
The plans also designate favoured sectors and projects, directing bank lending, easing permitting and providing an implicit government guarantee for the project developers.
Each plan lists numerous things that should be “promoted”, banned or controlled, leaving the precise implementation to different state organs and state-owned enterprises.
Five-year plans can introduce and coordinate national mega-projects, such as the gigantic clean-energy “bases” and associated electricity transmission infrastructure, which were outlined in the previous five-year plan in 2021.
The plans also function as a policy roadmap, assigning the tasks to develop new policies and providing stakeholders with visibility to expected policy developments.
1. Will the plan put China back on track for its 2030 Paris pledge?
Reducing carbon intensity – the energy-sector carbon dioxide (CO2) emissions per unit of GDP – has been the cornerstone of China’s climate commitments since the 2020 target announced at the 2009 Copenhagen climate conference.
Consequently, the last three five-year plans have included a carbon-intensity target. The next 15th one is highly likely to set a carbon-intensity target too, given that this is the centerpiece of China’s 2030 climate targets.
Moreover, it was president Xi himself who pledged in 2021 that China would reduce its carbon intensity to 65% below 2005 levels by 2030. This was later formalised in China’s 2030 “nationally determined contribution” (NDC) under the Paris Agreement.
Xi also pledged that China would gradually reduce coal consumption during the five-year period up to 2030. However, China is significantly off track to these targets.
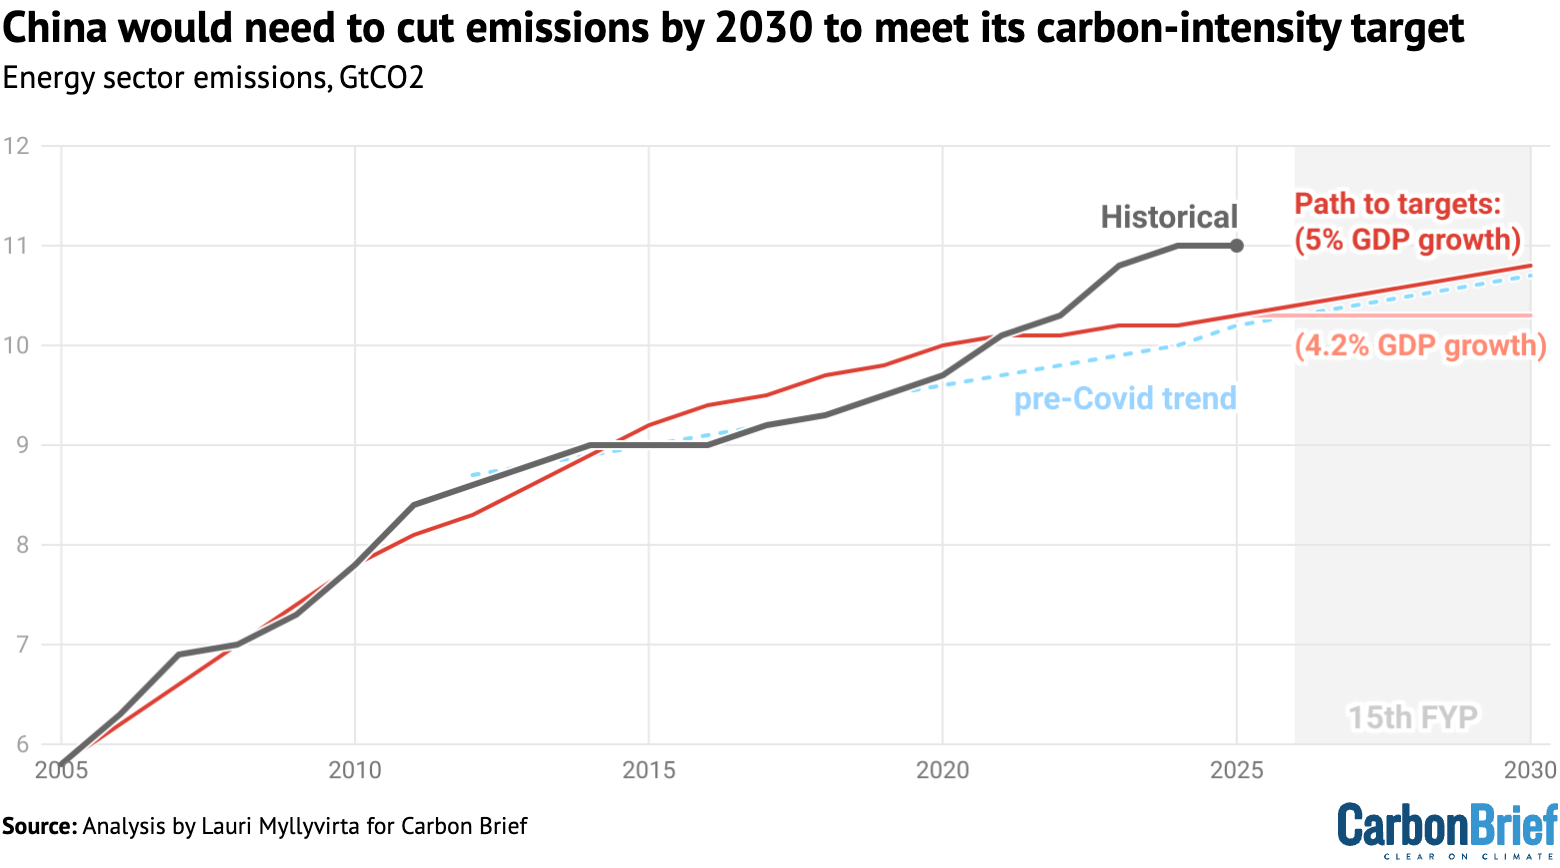
China’s CO2 emissions grew more quickly in the early 2020s than they had been before the Coronavirus pandemic, as shown in the figure below. This stems from a surge in energy consumption during and after the “zero-Covid” period, together with a rapid expansion of coal-fired power and the fossil-fuel based chemical industry. as shown in the figure below.
As a result, meeting the 2030 intensity target would require a reduction in CO2 emissions from current levels, with the level of the drop depending on the rate of economic growth.
Xi’s personal imprimatur would make missing these 2030 targets awkward for China, particularly given the country’s carefully cultivated reputation for delivery. On the other hand, meeting them would require much stronger action than initially anticipated.
Recent policy documents and statements, in particular the recommendations of the Central Committee of the Communist Party for the next five-year plan, and the government’s work report for 2025, have put the emphasis on China’s target to peak emissions before 2030 and the new 2035 emission target, which would still allow emissions to increase over the next five-year period. The earlier 2030 commitments risk being buried as inconvenient.
Still, the State Council’s plan for controlling carbon emissions, published in 2024, says that carbon intensity will be a “binding indicator” for the next five-year period, meaning that a target will be included in the top-level plan published in March 2026.
China is only set to achieve a reduction of about 12% in carbon intensity from 2020 to 2025 – a marked slowdown relative to previous periods, as shown in the figure below.
(This is based on reductions reported annually by the National Bureau of Statistics until 2024 and a projected small increase in energy-sector CO2 emissions in 2025. Total CO2 emissions could still fall this year, when the fall in process emissions from cement production is factored in.)
A 12% fall would be far less than the 18% reduction targeted under the 14th five-year plan, as well as falling short of what would be needed to stay on track to the 2030 target.
To make up the shortfall and meet the 2030 intensity target, China would need to set a goal of around 23% in the next five-year plan. As such, this target will be a key test of China’s determination to honour its climate commitments.
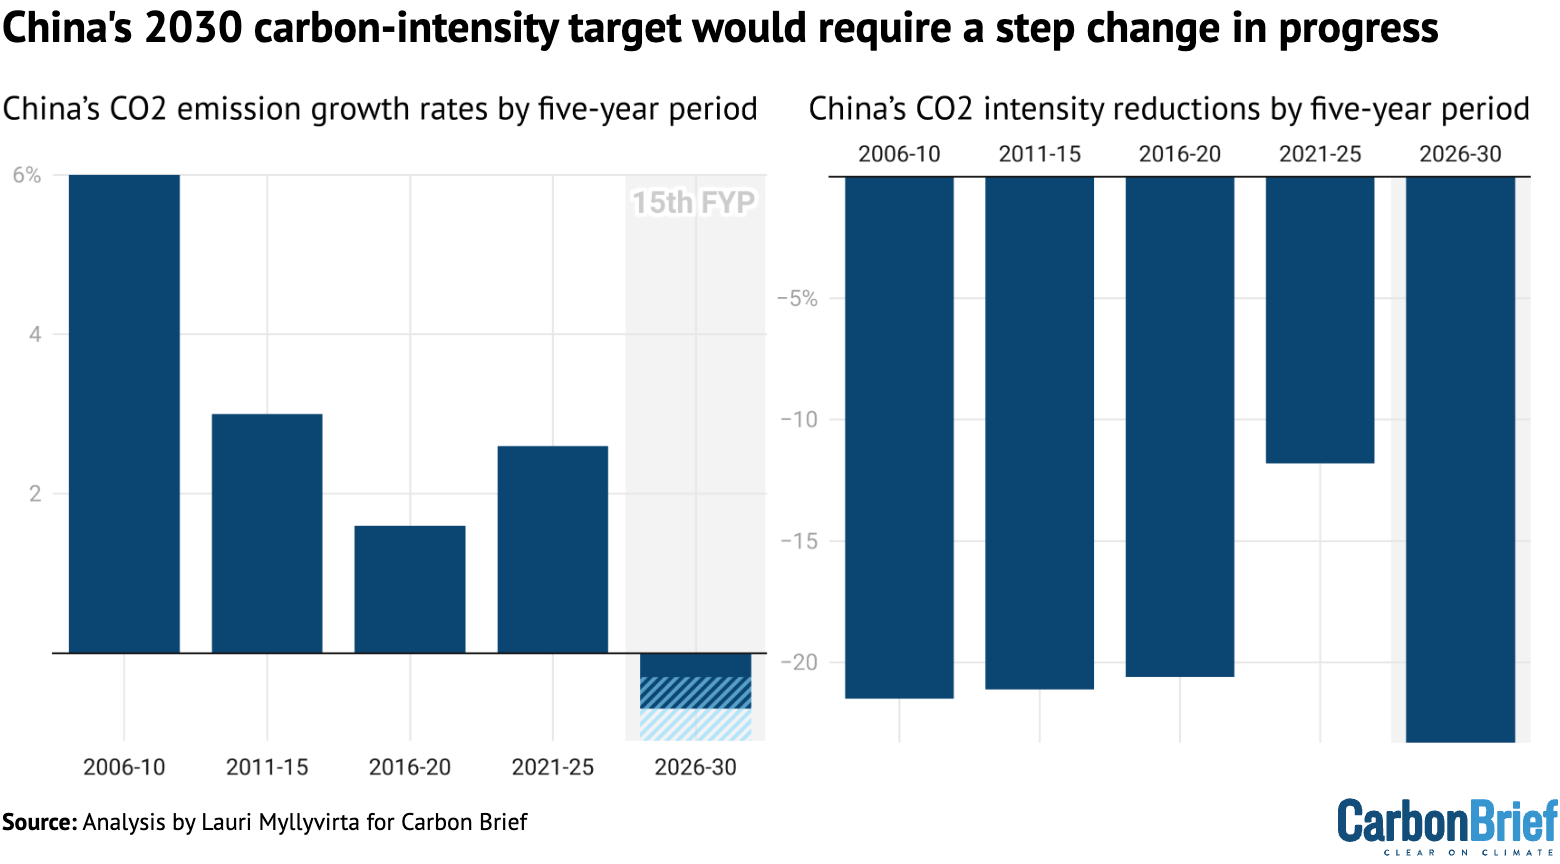
A carbon-intensity target of 23% is likely to receive pushback from some policymakers, as it is much higher than achieved in previous periods. No government or thinktank documents have yet been published with estimates of what the 2030 intensity target would need to be.
In practice, meeting the 2030 carbon intensity target would require reducing CO2 emissions by 2-6% in absolute terms from 2025, assuming a GDP growth rate of 4.2-5.0%.
China needs 4.2% GDP growth over the next decade to achieve Xi’s target of doubling the country’s GDP per capita from 2020 to 2035, a key part of his vision of achieving “socialist modernisation” by 2035, with the target for the next five years likely to be set higher.
Recent high-level policy documents have avoided even mentioning the 2030 intensity target. It is omitted in recommendations of the Central Committee of the Communist Party for the next five-year plan, the foundation on which the plan will be formulated.
Instead, the recommendations emphasised “achieving the carbon peak as scheduled” and “promoting the peaking of coal and oil consumption”, which are less demanding.
The environment ministry, in contrast, continues to pledge efforts to meet the carbon intensity target. However, they are not the ones writing the top-level five-year plan.
The failure to meet the 2025 intensity target has been scarcely mentioned in top-level policy discussions. There was no discernible effort to close the gap to the target, even after the midway review of the five-year plan recognised the shortfall.
The State Council published an action plan to get back on track, including a target for reducing carbon intensity in 2024 – albeit one not sufficient to close the shortfall. Yet this plan, in turn, was not followed up with an annual target for 2025.
The government could also devise ways to narrow the gap to the target on paper, through statistical revisions or tweaks to the definition of carbon intensity, as the term has not been defined in China’s NDCs.
Notably, unlike China’s previous NDC, its latest pledge did not include a progress update for carbon intensity. The latest official update sent to the UN only covers the years to 2020.
This leaves some more leeway for revisions, even though China’s domestic “statistical communiques”, published every year, have included official numbers up to 2024.
Coal consumption growth around 2022 was likely over-reported, so statistical revisions could reduce reported emissions and narrow the gap to the target. Including process emissions from cement, which have been falling rapidly in recent years, and changing how emissions from fossil fuels used as raw materials in the chemicals industry are accounted for, so-called non-energy use, which has been growing rapidly, could make the target easier to meet.
2. Will the plan upgrade clean-energy targets or pave the way to exceed them?
The need to accelerate carbon-intensity reductions also has implications for clean-energy targets.
The current goal is for non-fossil fuels to make up 25% of energy supplies in 2030, up from the 21% expected to be reached this year.
This expansion would be sufficient to achieve the reduction in carbon intensity needed in the next five years, but only if energy consumption growth slows down very sharply. Growth would need to slow to around 1% per year, from 4.1% in the past five years 2019-2024 and from 3.7% in the first three quarters of 2025.
The emphasis on manufacturing in the Central Committee’s recommendations for the next five-year plan is hard to reconcile with such a sharp slowdown, even if electrification will help reduce primary energy demand. During the current five-year period, China abolished the system of controlling total energy consumption and energy intensity, removing the incentive for local governments to curtail energy-intensive projects and industries.
Even if the ratio of total energy demand growth to GDP growth returned to pre-Covid levels, implying total energy demand growth of 2.5% per year, then the share of non-fossil energy would need to reach 31% by 2030 to deliver the required reduction in carbon intensity.
However, China recently set the target for non-fossil energy in 2035 at just 30%. This risks cementing a level of ambition that is likely too low to enable the 2030 carbon-intensity target to be met, whereas meeting it would require non-fossil energy to reach 30% by 2030.
There is ample scope for China to beat its targets for non-fossil energy.
However, given that the construction of new nuclear and hydropower plants generally takes five years or more in China, only those that are already underway have the chance to be completed by 2030. This leaves wind and solar as the quick-to-deploy power generation options that can deliver more non-fossil energy during this five-year period.
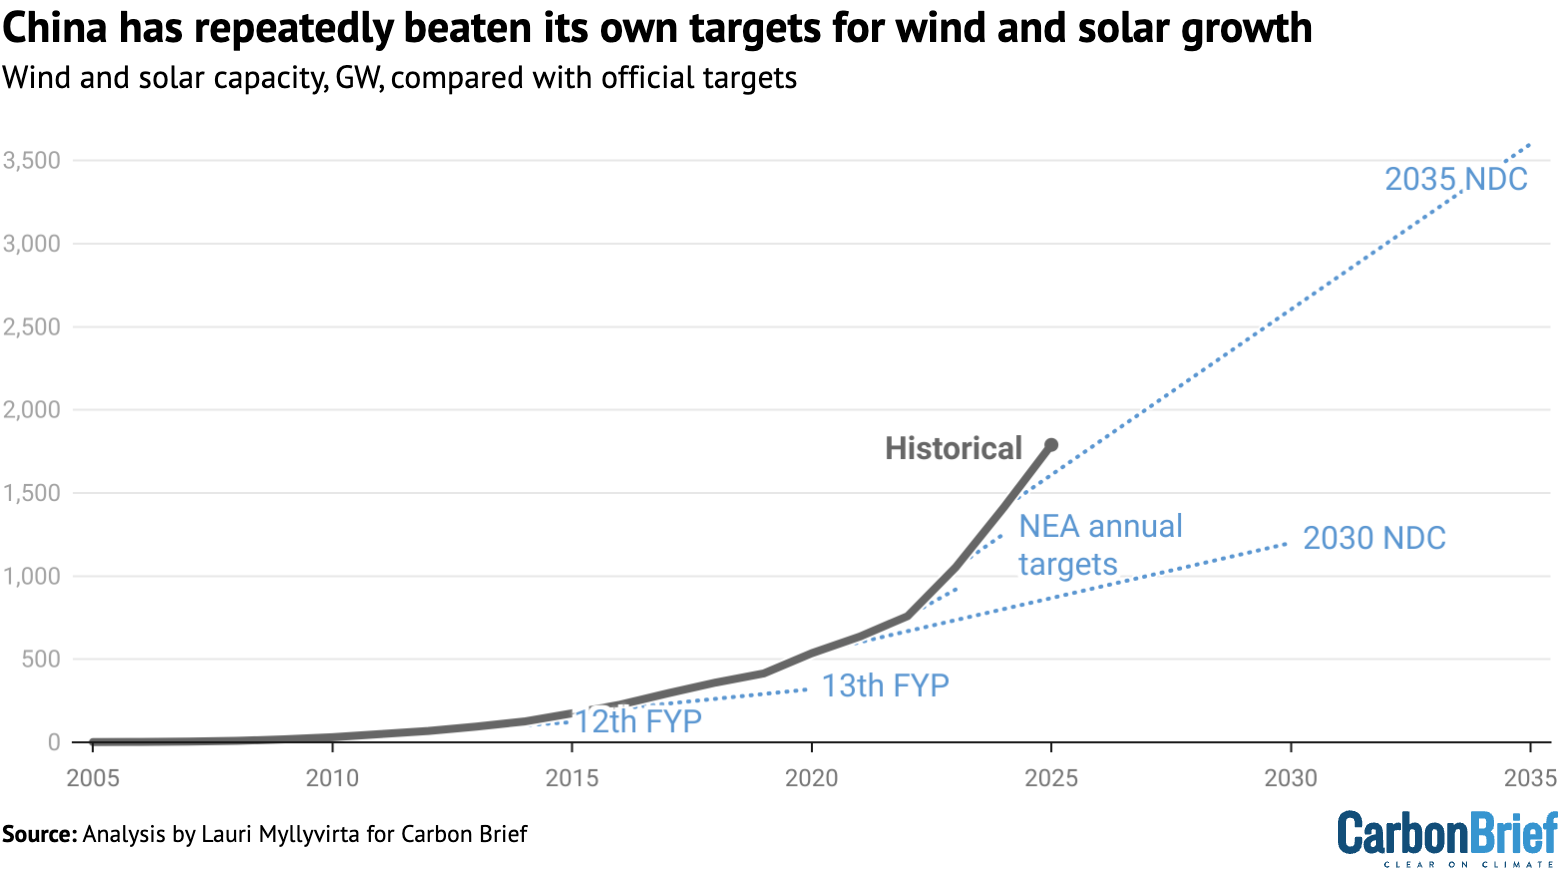
Reaching a much higher share of non-fossil energy in 2030, in turn, would therefore require much faster growth in solar and wind than currently targeted. Both the NDRC power-sector plan for 2025-27 and China’s new NDC aim for the addition of about 200 gigawatts (GW) per year of solar and wind capacity, much lower than the 360GW achieved in 2024.
If China continued to add capacity at similar rates, going beyond the government’s targets and instead installing 250-350GW of new solar and wind in each of the next five years, then this would be sufficient to meet the 2030 intensity target, assuming energy demand rising by 2.5-3.0% per year.
All previous wind and solar targets have been exceeded by a wide margin, as shown in the figure below, so there is a good chance that the current one will be, too.
While the new pricing policy for wind and solar has created a much more uncertain and less supportive policy environment for the development of clean energy, provinces have substantial power to create a more supportive environment.
For example, they can include clean-energy projects and downstream projects using clean electricity and green hydrogen in their five-year plans, as well as developing their local electricity markets in a direction that enables new solar and wind projects.
3. Will the plan set an absolute cap on coal consumption?
In 2020, Xi pledged that China would “gradually reduce coal consumption” during the 2026-30 period. The commitment is somewhat ambiguous.
It could be interpreted as requiring a reduction starting in 2026, or a reduction below 2025 levels by 2030, which in practice would mean coal consumption peaking around the midway point of the five-year period, in other words 2027-28.
In either case, if Xi’s pledge were to be cemented in the 15th five-year plan then it would need to include an absolute reduction in coal consumption during 2026-30. An illustration of what this might look like is shown in the figure below.
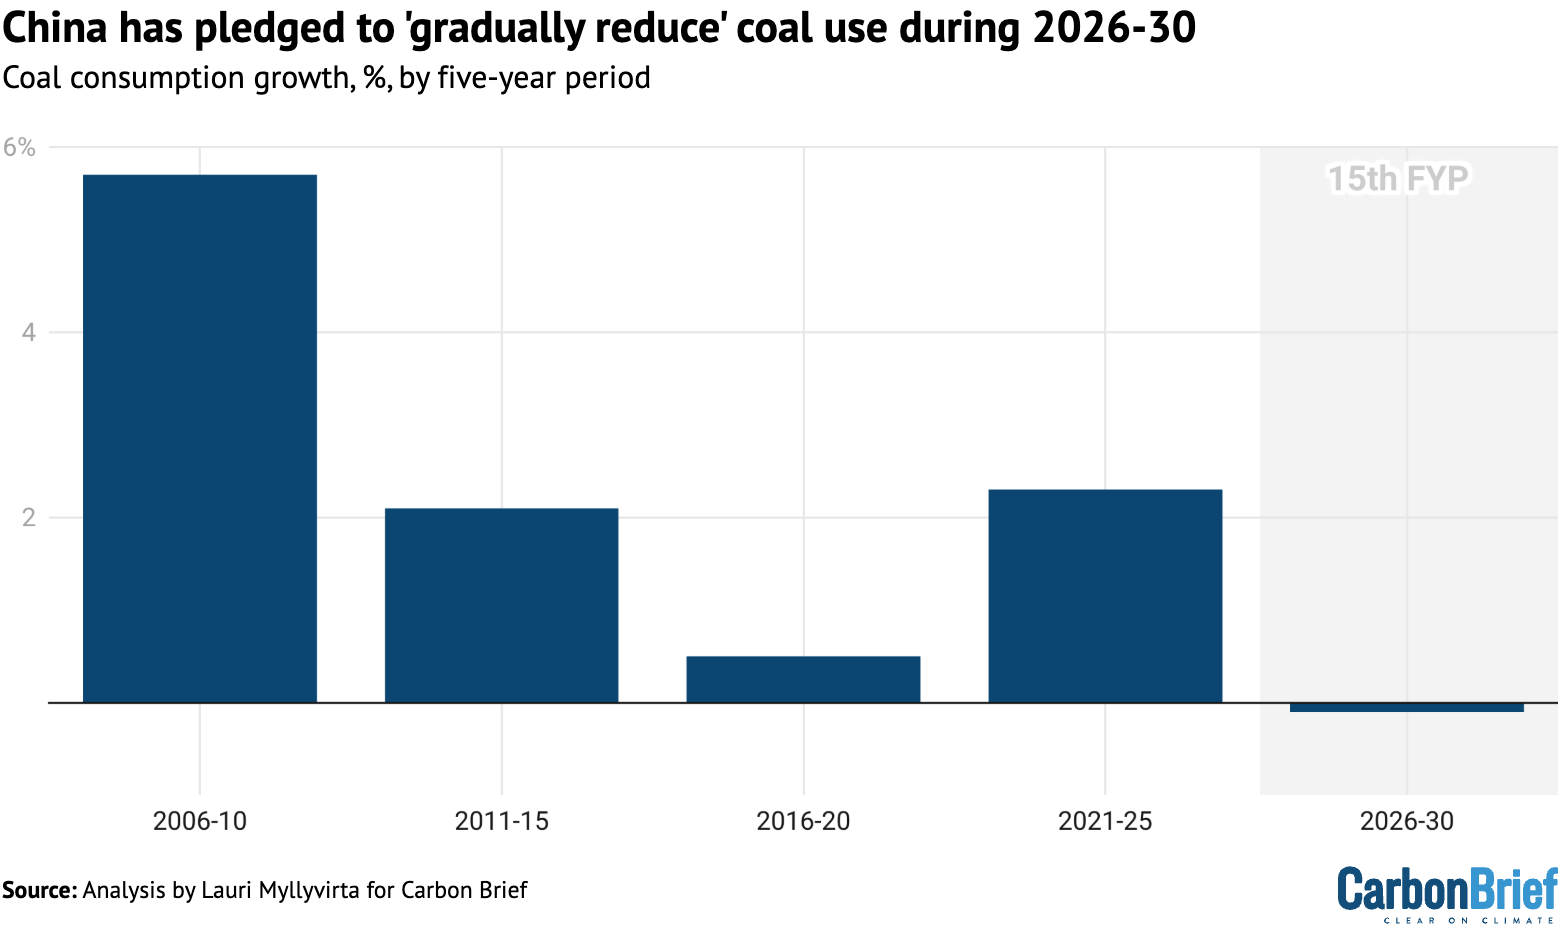
However, the commitment to reduce coal consumption was missing from China’s new NDC for 2035 and from the Central Committee’s recommendations for the next five-year plan.
The Central Committee called for “promoting a peak in coal and oil consumption”, which is a looser goal as it could still allow an increase in consumption during the period, if the growth in the first years towards 2030 exceeds the reduction after the peak.
The difference between “peaking” and “reducing” is even larger because China has not defined what “peaking” means, even though peaking carbon emissions is the central goal of China’s climate policy for this decade.
Peaking could be defined as achieving a certain reduction from peak before the deadline, or having policies in place that constrain emissions or coal use. It could be seen as reaching a plateau or as an absolute reduction.
While the commitment to “gradually reduce” coal consumption has seemed to fade from discussion, there have been several publications discussing the peak years for different fossil fuels, which could pave the way for more specific peaking targets.
State news agency Xinhua published an article – only in English – saying that coal consumption would peak around 2027 and oil consumption around 2026, while also mentioning the pledge to reduce coal consumption.
The energy research arm of the National Development and Reform Council had said earlier that coal and oil consumption would peak halfway through the next five-year period, in other words 2027-28, while the China Coal Association advocated a slightly later target of 2028.
Setting a targeted peak year for coal consumption before the half-way point of the five-year period could be a way to implement the coal reduction commitment.
With the fall in oil use in transportation driven by EVs, railways and other low-carbon transportation, oil consumption is expected to peak soon or to have peaked already.
State-owned oil firm CNPC projects that China’s oil consumption will peak in 2025 at 770m tonnes, while Sinopec thinks that continued demand for petrochemical feedstocks will keep oil consumption growing until 2027 and it will then peak at 790-800m tonnes.
4. Will ‘dual control’ of carbon prevent an emission rebound?
With the focus on realising a peak in emissions before 2030, there could be a strong incentive for provincial governments and industries to increase emissions in the early years of the five-year period to lock in a higher level of baseline emissions.
This approach is known as “storming the peak” (碳冲锋) in Chinese and there have been warnings about it ever since Xi announced the current CO2 peaking target in 2020.
Yet, the emphasis on peaking has only increased, with the recent announcement on promoting peaks in coal consumption and oil consumption, as well as the 2035 emission-reduction target being based on “peak levels”.
The policy answer to this is creating a system to control carbon intensity and total CO2 emissions – known as “dual control of carbon” – building on the earlier system for the “dual control of energy” consumption.
Both the State Council and the Central Committee have set the aim of operationalising the “dual control of carbon” system in the 15th five-year plan period.
However, policy documents speak of building the carbon dual-control system during the five-year period rather than it becoming operational at the start of the period.
For example, an authoritative analysis of the Central Committee’s recommendations by China Daily says that “solid progress” is needed in five areas to actually establish the system, including assessment of carbon targets for local governments as well as carbon management for industries and enterprises.
The government set an annual target for reducing carbon intensity for the first time in 2024, but did not set one for 2025, also signaling that there was no preparedness to begin controlling carbon intensity, let alone total carbon emissions, yet.
If the system is not in place at the start of the five-year period, with firm targets, there could be an opportunity for local governments to push for early increases in emissions – and potentially even an incentive for such emission increases, if they expect strict control later.
Another question is how the “dual” element of controlling both carbon intensity and absolute CO2 emissions is realised. While carbon intensity is meant to be the main focus during the next five years, with the priority shifting to reducing absolute emissions after the peak, having the “dual control” in place requires some kind of absolute cap on CO2 emissions.
The State Council has said that China will begin introducing “absolute emissions caps in some industries for the first time” from 2027 under its national carbon market. It is possible that the control of absolute carbon emissions will only apply to these sectors.
The State Council also said that the market would cover all “major emitting sectors” by 2027, but absolute caps would only apply to sectors where emissions have “stabilised”.
5. Will it limit coal-power and chemical-industry growth?
During the current five-year period, China’s leadership went from pledging to “strictly control” new coal-fired power projects to actively promoting them.
If clean-energy growth continues at the rates achieved in recent years, there will be no more space for coal- and gas-fired power generation to expand, even if new capacity is built. Stable or falling demand for power generation from fossil fuels would mean a sharp decline in the number of hours each plant is able to run, eroding its economic viability.
Showing the scale of the planned expansion, researchers from China Energy Investment Corporation, the second-largest coal-power plant operator in China, project that China’s coal-fired power capacity could expand by 300GW from the end of 2024 to 2030 and then plateau at that level for a decade. The projection relies on continued growth of power generation from coal until 2030 and a very slow decline thereafter.
The completion of the 325GW projects already under construction and permitted at the end of 2024, as well as an additional 42GW permitted in the first three quarters of 2025, could in fact lead to a significantly larger increase, if the retirement of existing capacity remains slow.
In effect, China’s policymakers face a choice between slowing down the clean-energy boom, which has been a major driver of economic growth in recent years, upsetting coal project developers, who expect to operate their coal-fired power plants at a high utilisation, or retiring older coal-power plants en masse.
Their response to these choices may not become clear for some time. The top-level five-year plan that will be published in March 2026 will likely provide general guidelines, but the details of capacity development will be relegated to the sectoral plans for energy.
The other sector where fossil fuel-based capacity is rapidly increasing is the chemical industry, both oil and coal-based. In this sector, capacity growth has led directly to increases in output, making the sector the only major driver of emissions increases after early 2024.
The expansion is bound to continue. There are more than 500 petrochemical projects planned by 2030 in China, of which three quarters are already under construction, according to data provider GlobalData.
As such, the emissions growth in the chemical sector is poised to continue in the next few years, whereas meeting China’s 2030 targets and commitments would require either reining it in and bringing emissions back down before 2030, or achieving emission reductions in other sectors that offset the increases.
The expansion of the coal-to-chemicals industry is largely driven by projects producing gas and liquid fuels from coal, which make up 70% of the capacity under construction and in planning, according to a mapping by Anychem Coalchem.
These projects are a way of reducing reliance on imported oil and gas. In these areas, electrification and clean energy offer another solution that can replace imports.
Conclusions
The five-year plans being prepared now will largely determine the peak year and level of China’s emissions, with a major impact on China’s subsequent emission trajectory and on the global climate effort.
The targets in the plan will also be a key test of the determination of China’s leadership to respect previous commitments, despite setbacks.
The country has cultivated a reputation for reliably implementing its commitments. For example, senior officials have said that China’s policy targets represent a “bottom line”, which the policymakers are “definitely certain” about meeting, while contrasting this with other countries’ loftier approach to target-setting.
Depending on how the key questions outlined in this article are answered in the plans for the next five years, however, there is the possibility of a rebound in emissions.
There are several factors contributing to such a possibility: solar- and wind-power deployment could slow down under the new pricing policy, weak targets and a deluge of new coal- and gas-power capacity coming onto the market.
In addition, unfettered expansion of the chemical industry could drive up emissions. And climate targets that limit emissions only after a peak is reached could create an incentive to increase emissions in the short term, unless counteracted by effective policies.
On the other hand, there is also the possibility of the clean-energy boom continuing so that the sector beats the targets it has been set. Policymakers could also prioritise carbon-intensity reductions early in the period to meet China’s 2030 commitments.
Given the major role that clean-energy industries have played in driving China’s economic growth and meeting GDP targets, local governments have a strong incentive to keep the expansion going, even if the central government plans for a slowdown.
During the current five-year period, provinces and state-owned enterprises have been more ambitious than the central government. Provinces can and already have found ways to support clean-energy development beyond central government targets.
Such an outcome would continue a well-established pattern, given all previous wind and solar targets have been exceeded by a wide margin.
The difference now is that a significant exceedance of clean-energy targets would make a much bigger difference, due to the much larger absolute size of the industry.
To date, China’s approach to peaking emissions and pursuing carbon neutrality has focused on expanding the supply and driving down the cost of clean technology, emphasising economic expansion rather than restrictions on fossil-fuel use and emissions, with curbing overcapacity an afterthought.
This suggests that if China’s 2030 targets are to be met, it is more likely to be through the over-delivery of clean energy than as a result of determined regulatory effort.
The post Q&A: Five key climate questions for China’s next ‘five-year plan’ appeared first on Carbon Brief.
Q&A: Five key climate questions for China’s next ‘five-year plan’

Climate Change
Q&A: What can – and cannot – be said about global warming’s role in the 2026 Himalayan floods
On the morning of 26 August, flash floods surged through a Himalayan border region of Nepal and the Chinese region of Tibet, killing more than 1,300 people, with thousands still missing.
In the days since the floods, scientists have examined satellite imagery, drone footage and seismic data in order to understand and explain the forces behind the event.
While initial theories pinned the flood on a glacial collapse, scientists now understand the event as a “multi-hazard cascade”, which began with a bedrock collapse.
Some climate sceptics have tried to use this to falsely claim that human-caused climate change had no impact on the event.
Yet, scientists have noted that, while no formal attribution study has been carried out thus far, warming is making such ice-rock avalanches in the region more likely.
Researchers have highlighted how rapid warming is dramatically reshaping Asia’s high-mountain region – and identified rising temperatures, glacier retreat and permafrost thaw as factors that may have all contributed to the disaster.
Balendra Shah, Nepal’s prime minister, has called the floods a “serious signal that…the risks we must bear in the Himalayan region are increasing” due to climate change.
Here, Carbon Brief unpacks what scientists currently know about the causes of the catastrophic event and what they can – and cannot – say about the role of climate change.
What happened?
A report published on 28 August by the HiRisk scientific consortium of high mountain experts detailed the events that led to the flash floods.
It said that events were set in motion on 26 August when a mass of bedrock, as well as the glacier ice on top of it, broke off a slope of Langtang-Lirung mountain in the Nepalese Himalaya, plunging from approximately 5,200 metres above sea level to the valley floor at 3,000 metres.
The landslide shook the ground hard enough that, at 8:37am Nepal local time, the US Geological Survey (USGS) initially reported a magnitude 4.4 earthquake. Later that day, it clarified the shaking was caused by glacier collapse and debris flow, equivalent to a magnitude 5.2 earthquake.
On the valley floor, the melting ice, water and debris slammed into the Lhende Khola river, a high-altitude river that runs along Nepal’s border with China.
Known downstream as the Bhote Koshi river in Nepal and the Poiqu or Poqu in China, the Lhende Khole feeds a network of rivers across Nepal and the Chinese region of Tibet, including the Trishuli river. (In China, the Lhende Khola is known as the Donglin Tsangpo.)
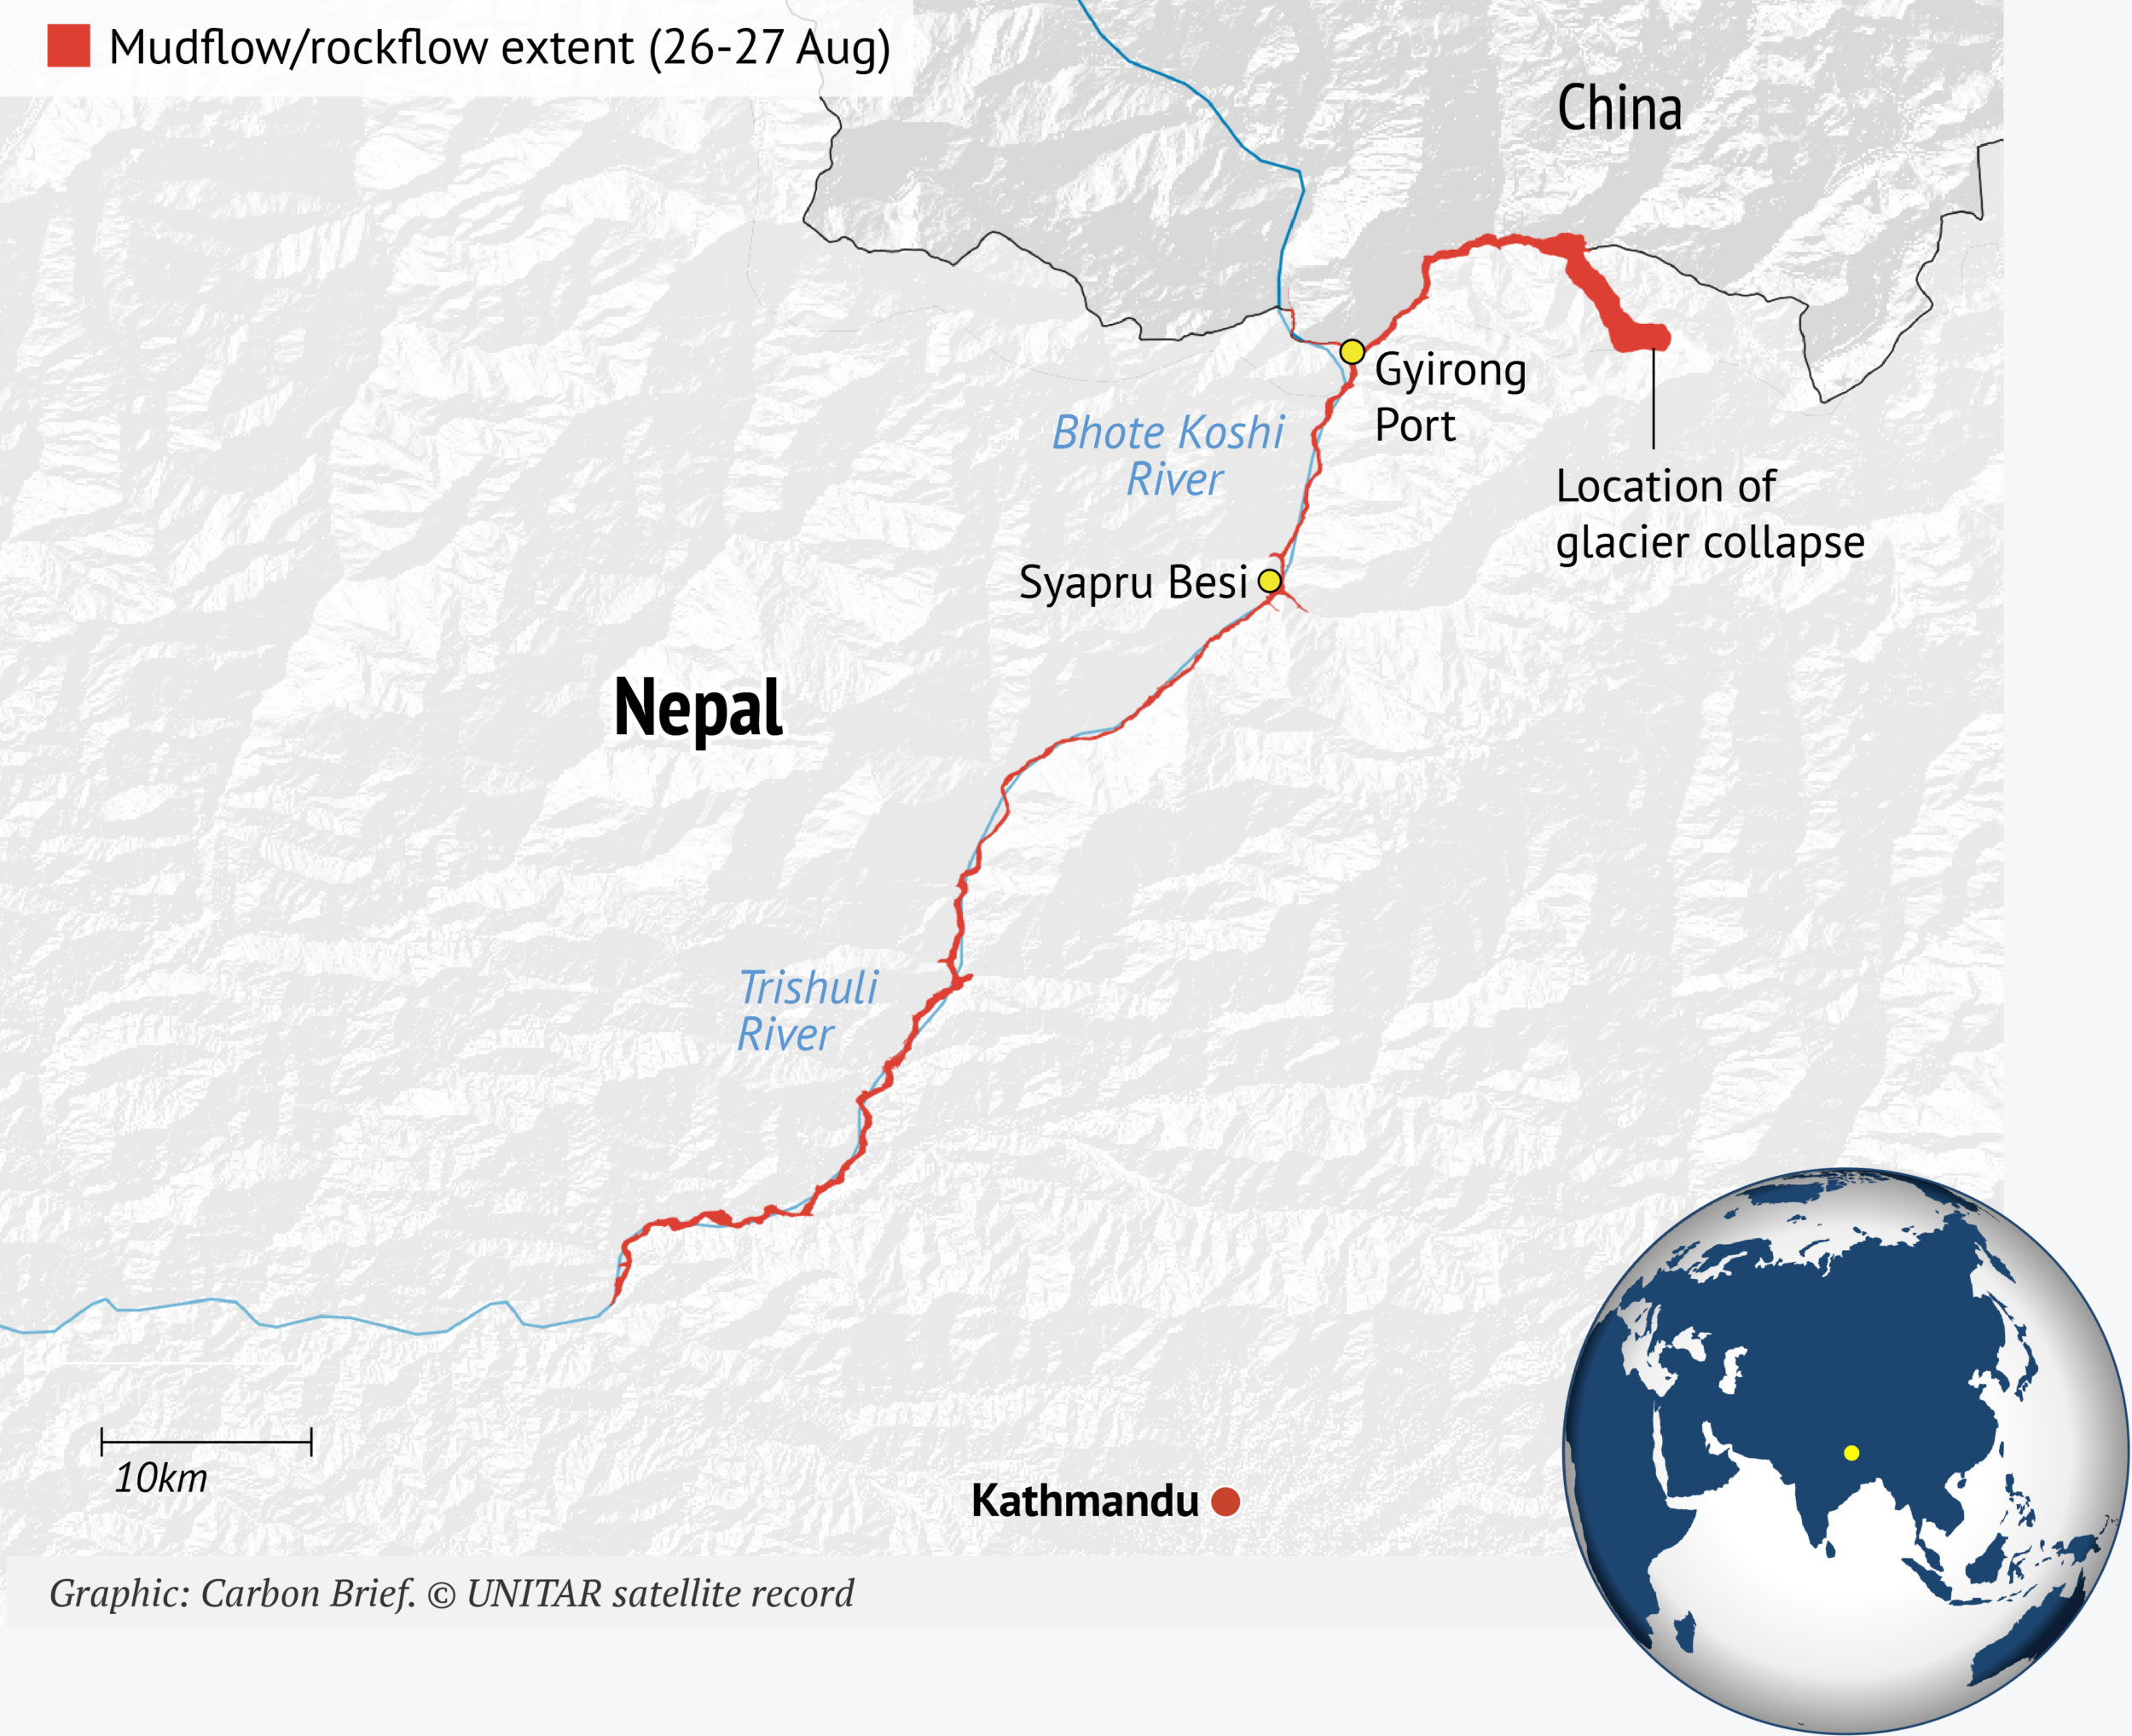
A large “debris” lake was briefly formed on the valley floor. When this lake burst, a wall of water and rock travelled downstream, killing more than a thousand people and destroying settlements, roads, bridges, hydropower plants and border posts across Nepal and Tibet.
HiRisk said that the floodwave travelled down rivers as fast as 30km an hour (around 19 miles per hour) and reached Mugling – a Nepalese town more than 130km downstream – at around 1pm local time.
A separate report from the Center for Land Surface Hazards in the US noted that the flood moved “exceptionally fast, was sediment-laden and extreme in scale”. For example, in the Nepalese municipality of Galchhi, the Trishuli river rose by nine metres in 30 minutes, it said.
Writing in the Conversation, Dr Umesh Haritashya, a glaciologist at the University of Dayton in Ohio, explained that the disaster “wasn’t finished when the first wall of water passed [on 26 August]”.
He continued that a new “barrier lake” – estimated to hold a few million cubic metres of water – had developed in a location where two rivers meet in Tibet before crossing into Nepal. This lake burst on 28 August and the river rose again, he said.
On 4 September, the chief of Nepal’s National Disaster Risk Reduction and Management Authority, told Reuters that property and infrastructure worth “at least” $2.5bn (£1.9bn) had been lost. Dharma Raj Upreti estimated the cost to build roads and temporary shelters, provide drinking water and restore power would be around $53m (£39m).
How did bedrock collapse trigger the flash floods?
In the immediate aftermath of the floods, initial reports suggested that the trigger was a collapsing glacier or earthquake in the high mountains of Nepal.
After confirming that a seismic tremor was as a result of falling rock and ice, the USGS said the trigger was likely a “glacial collapse and debris flow”. This was widely picked up by the media.
Subsequently, satellite imagery revealed that an “enormous chunk of the mountainous bedrock” beneath the glacier had also given way, reported the New York Times.
Dr Kristen Cook, a geomorphologist at the Université Grenoble Alpes in France, told the newspaper:
“The rock that the glacier was sitting on collapsed…It was a much larger collapse than we were initially able to see in the satellite imagery.”
The result was a “deluge of rock and ice, which pulverized into mud and water as it surged down the mountainside”, the newspaper said.
Dr Jakob Steiner a geoscientist at the University of Graz in Austria, tells Carbon Brief:
“It was not a glacier that collapsed. It was the mountain below the glacier that collapsed and the glacier had no other chance but to go with it because it was sitting on top of it.
“The trigger for that is something that we are not 100% certain about, but, in the end, it very much looks like simply a mechanical failure of the rock material because of stressors that have built up over a long period of time.”
Failures of “bedrock” – the hard, solid rock that sits below looser rocks and soil – are an “increasingly common occurrence”, says Prof Bethan Davies, a professor of glaciology at Newcastle University. She tells Carbon Brief:
“These massive landslides occur in mountain regions, commonly following rapid deglacierisation [the melting away of a glacier]. Similar events happened in the Chamoli event in 2021 [in the Indian Himalaya] and in the Blatten landslide last year in Switzerland. They’ve also occurred recently in Alaska.”
With a shift in focus from the failure of a glacier to the bedrock underneath, some climate sceptics seized on the development to falsely claim that climate change had not played any role in the disaster.
These include Dr Matthew Wielicki, recently appointed by the Trump administration to lead the US Global Change Research Program, on Twitter, as well as former Conservative peer and climate-sceptic commentator Matt Ridley in the Spectator.
However, scientists have highlighted the likely contribution of rapid warming in the region. These factors include the thawing of permafrost and glacier retreat. (For more, see sections below).
Fundamentally, “this would have been a much less significant tragedy if it had been just a rock-slope failure”, notes Davies.
The initial landslide took a mixture of rock and ice into a valley that “contains buried ice” as well, she says, providing the water that “resulted in the hyperconcentrated flow, which took so many lives”.
How have temperatures risen in the affected region?
Global temperatures have risen by roughly 1.4C since the pre-industrial period. However, this increase is not uniform across the planet, with some regions warming faster than others.
A study published in Global and Planetary Change in June 2026 investigated changes in the Langtang catchment – a river basin in central Nepal, in which the Langtang-Lirung mountain is located, which eventually drains into the Ganges. Around one-quarter of the area is made up of glaciers.
The paper found that glacial areas of the catchment – found at 4,000 metres above sea level – warmed at 0.31C per decade over 1960-2023. This was “more than three times” the rate observed at a lower elevation weather station, the authors said.
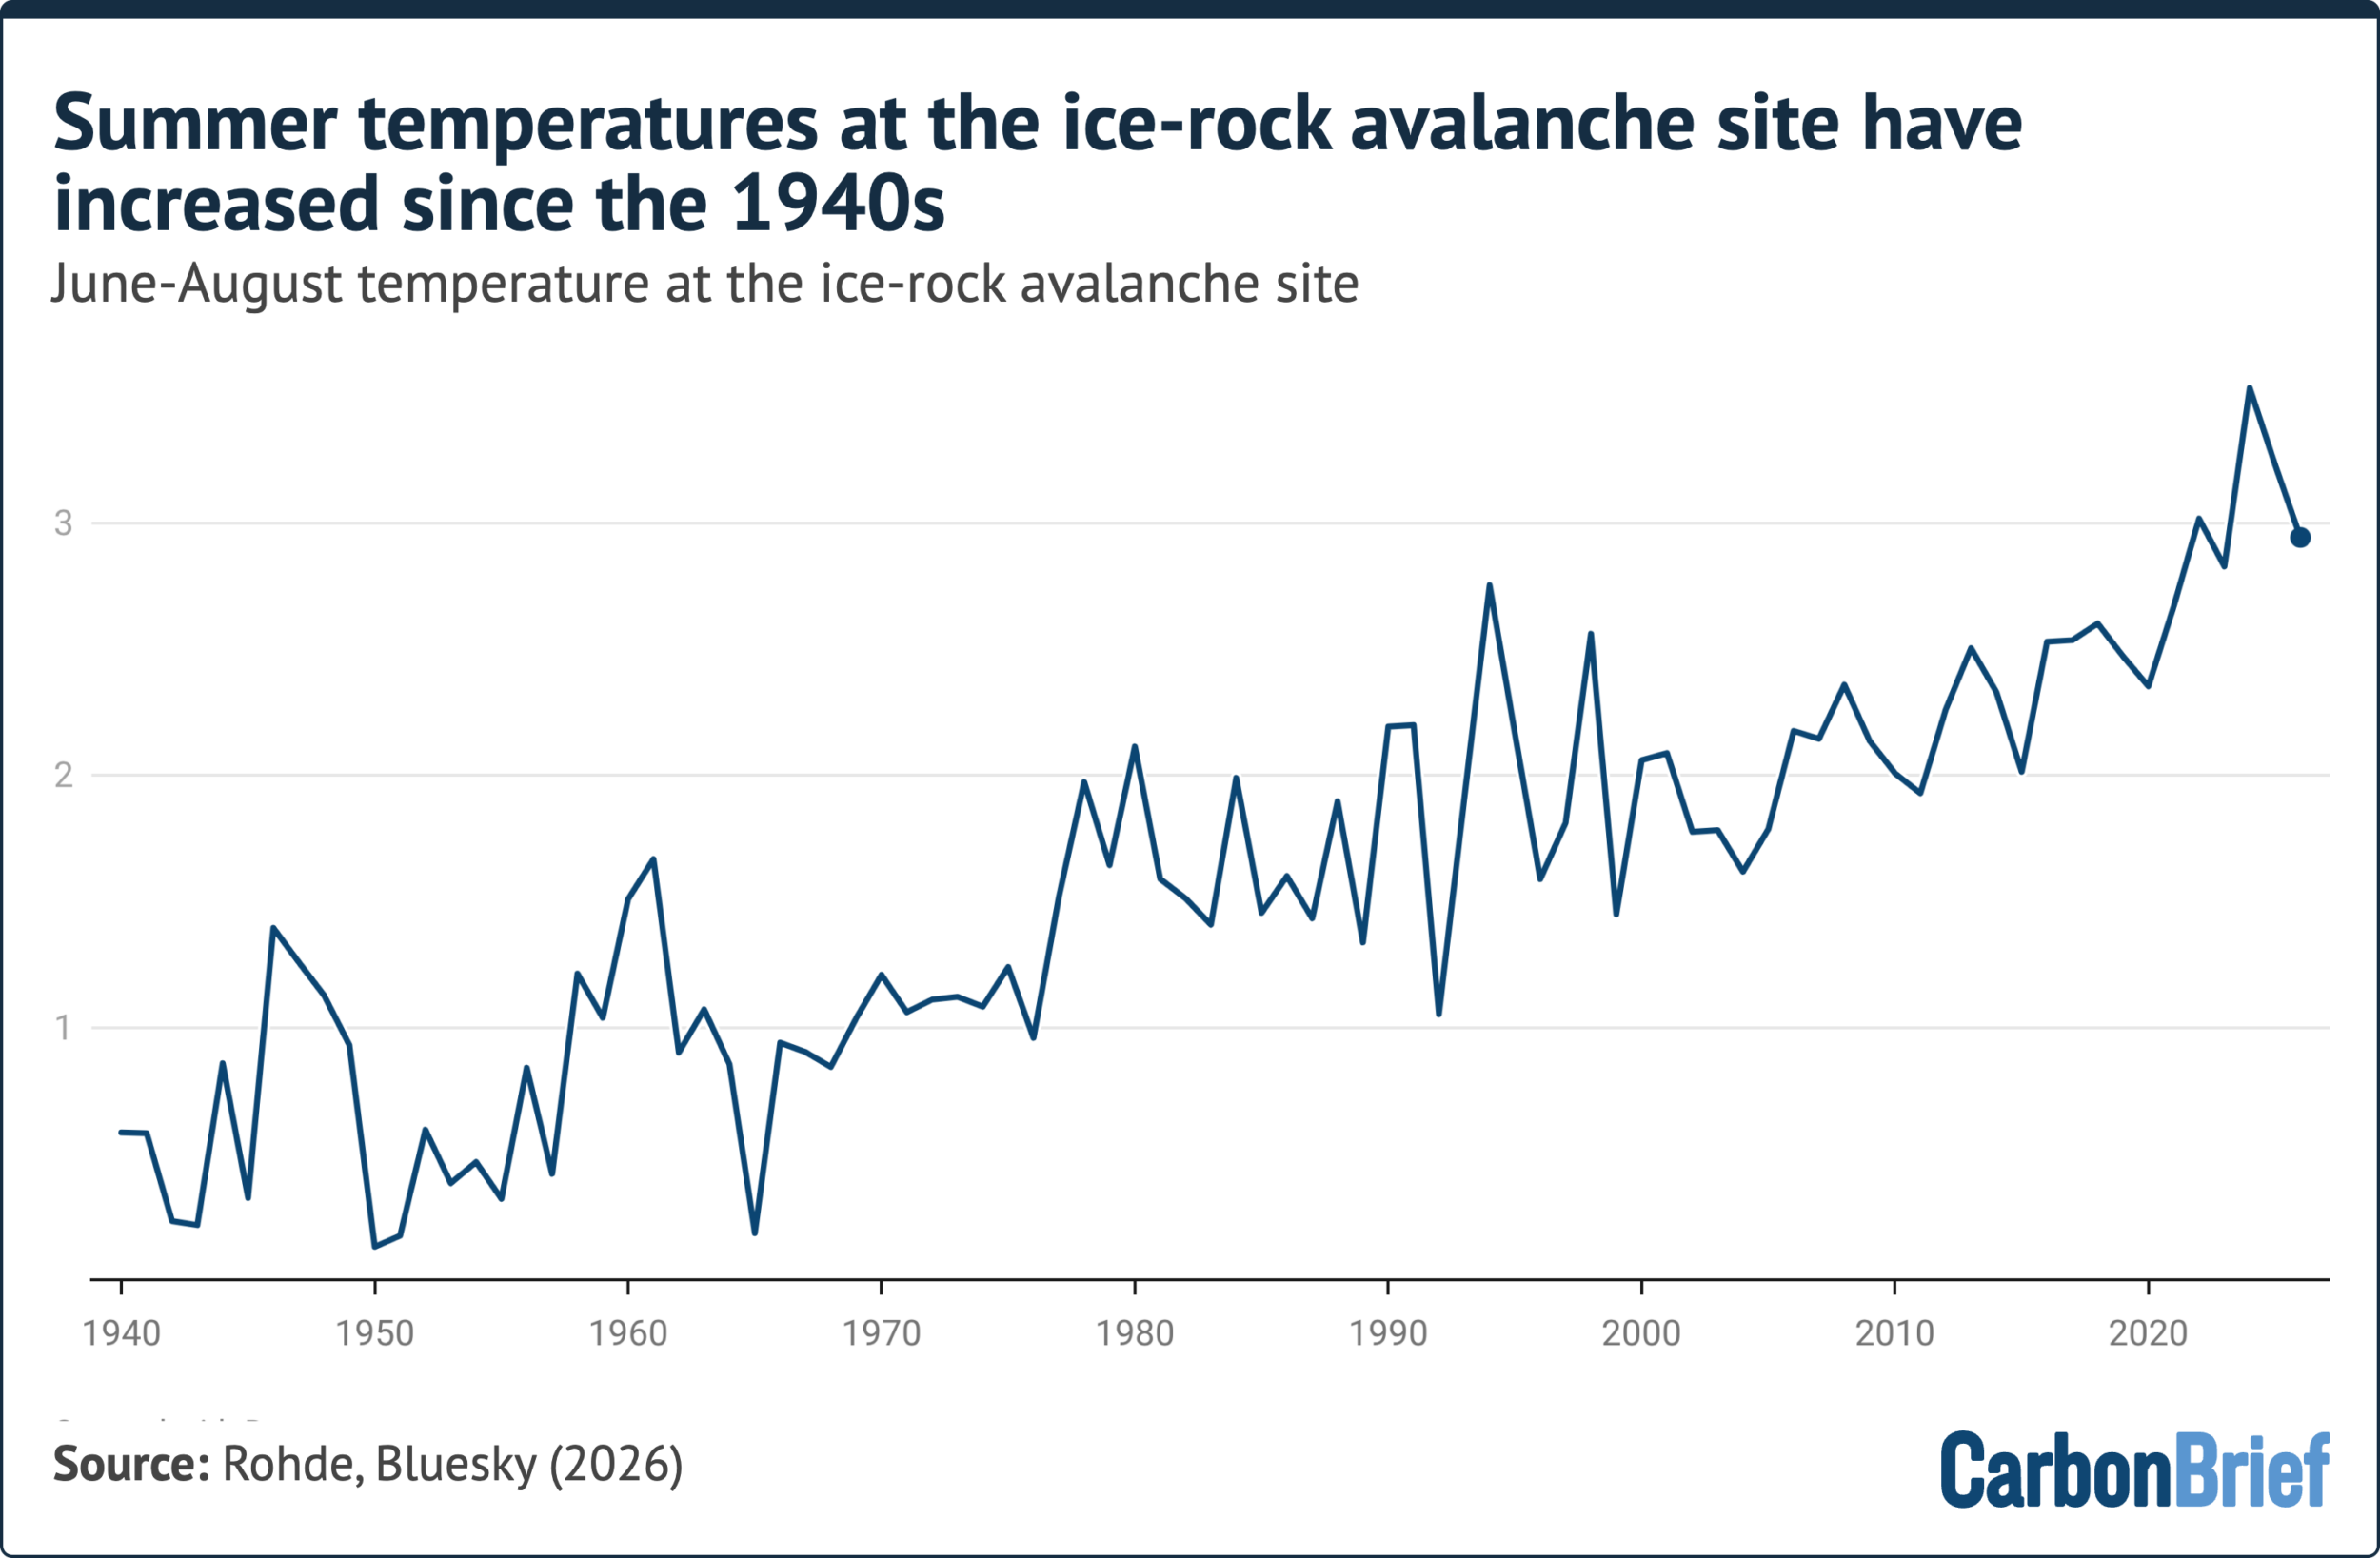
Looking in more detail at the site of the glacial collapse, Dr Robert Rohde, chief scientist for Berkeley Earth, used ERA5 reanalysis data to show how temperature has changed at the 5,200-metre elevation site where the mass of ice and rock broke loose.
Rohde’s analysis found that June-to-August temperatures have been rising at the site of the glacier collapse since the year 1940, with 2026’s summer the fourth warmest on record, behind 2024, 2025 and 2022. This is shown in the graph below.
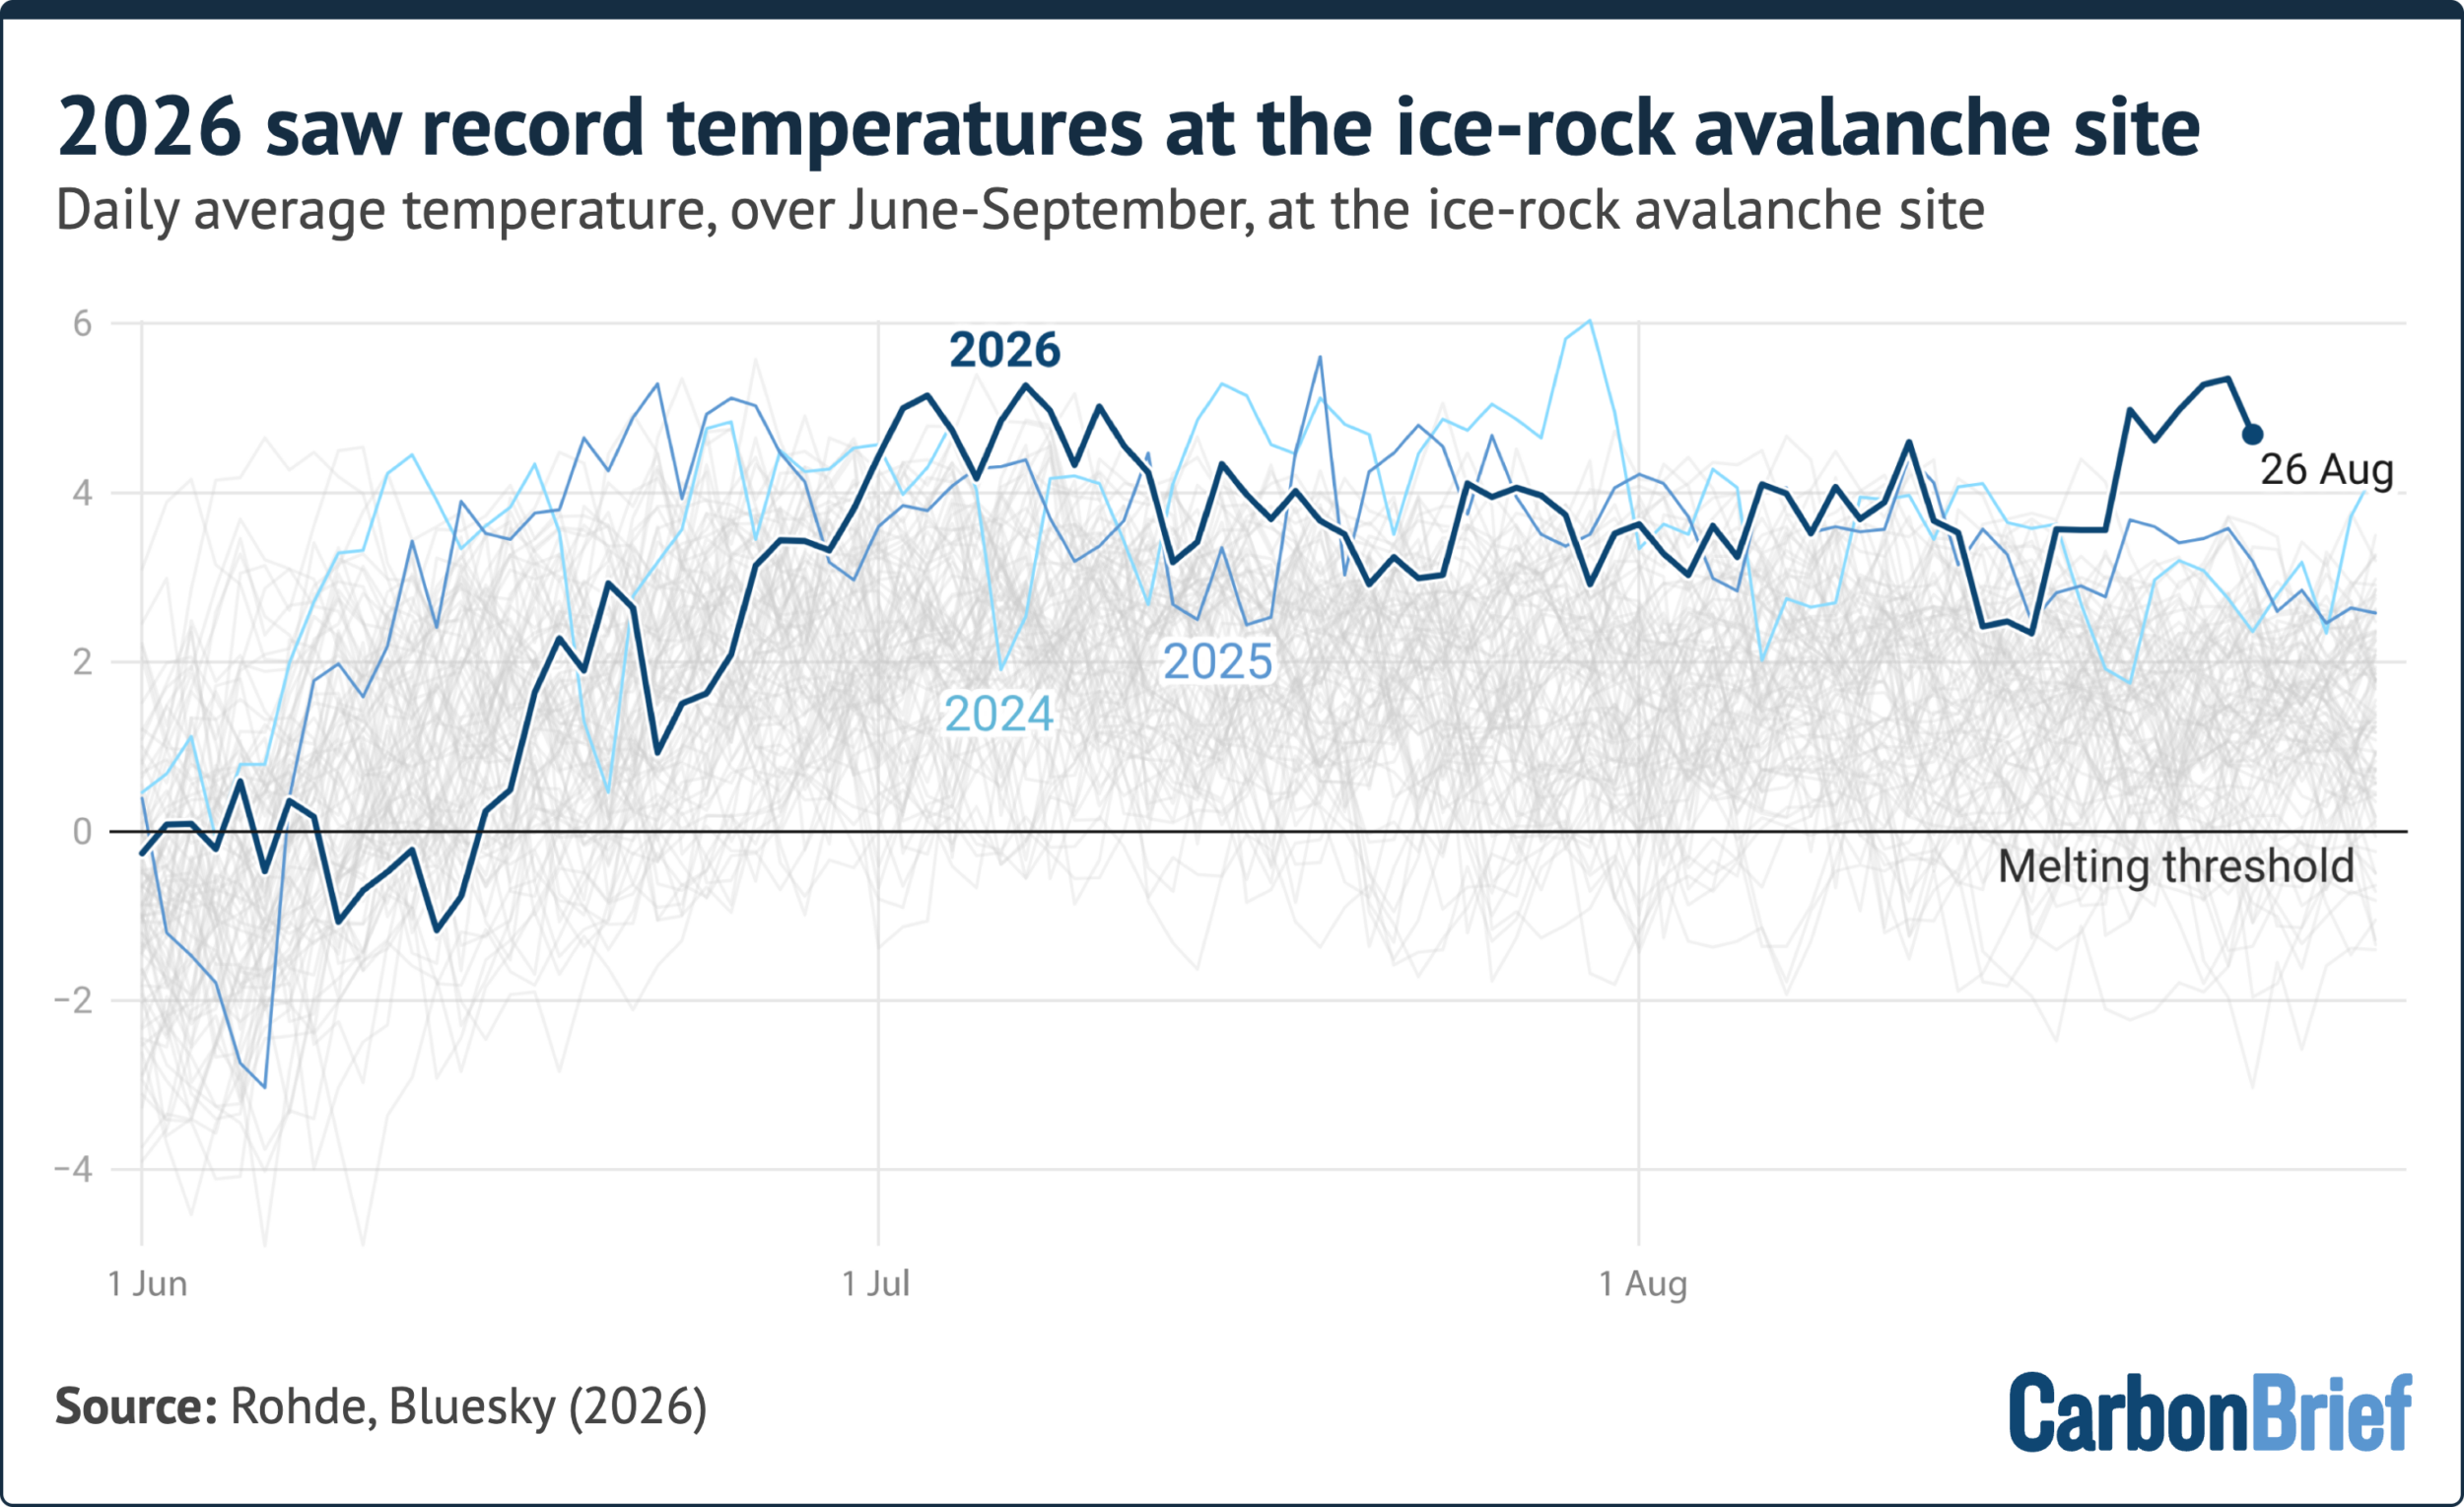
Rohde also found that the days leading up to the disaster recorded the hottest August temperatures ever experienced at the site. This is shown in the graph below.
On social media, Rohde stated:
“Given the warming trend, this Nepali glacier had probably been thinning and weakening for years, or even decades. But it ultimately failed during the warmest week in one of its warmest years on record. It would be a hell of a coincidence if global warming wasn’t at least partially to blame.”
How have rising temperatures affected mountain stability?
Many experts have linked warming temperatures in the region to thawing permafrost – ground that has been frozen for at least two consecutive years, whose thickness ranges from less than one metre to more than a kilometre.
Steiner is part of a research team that has been using sensors to monitor permafrost in the region since 2014. He tells Carbon Brief that it is “pretty clear” the permafrost has been thawing “very actively” at elevations as high as 5,200 metres above sea level “for many years”. He adds:
“This means that the ground has, over the last decades, moved from being in a solid state into – at least, periodically during the warm season – patchy ground where some is frozen and some isn’t…
“If you have frozen ground next to non-frozen ground, you have dynamics happening between that because there are different densities and there’s movement happening, which is conducive to interventional failure – and that we know from many other cases.”
Davies also points to the “degradation” of perennially frozen ground as a factor in the disaster:
“This permafrost acts as a glue to hold together the rocks and, as it melts, the rock can become weakened.”
Permafrost thaw can also result in saturated ground, says Davies, which adds “pressure in the joints” of rock and can “facilitate” failure. She continues:
“Sources of the water include melting permafrost and meltwater from the overlying glacier. We know that this event happened during a period of warmth, but in the absence of heavy precipitation, pointing to ice melt as the source of water.”
A 2025 study of rock and ice avalanches in High Mountain Asia found that more than two-thirds started in areas “where permafrost is probable”.
How have glaciers retreated in the affected region?
Glaciers – frozen rivers of ice holding three-quarters of the global freshwater supply – are extremely vulnerable to climate change.
In the Himalaya, the rate of glacier retreat has doubled since the late 20th century, according to a 2019 study in Science Advances.
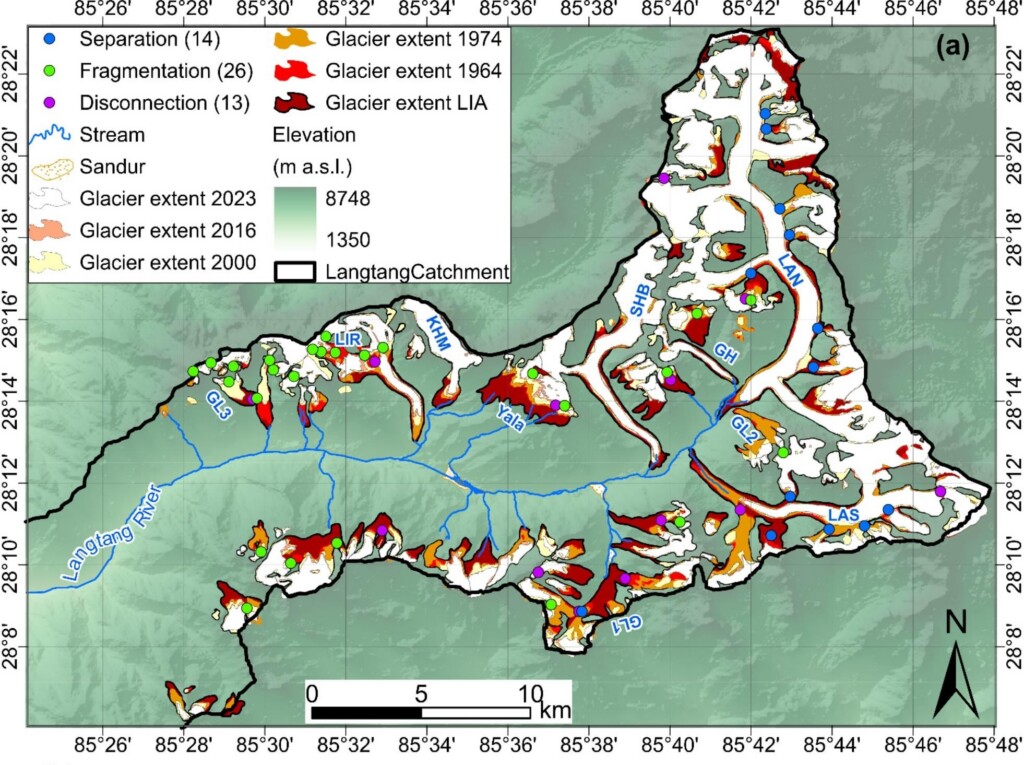
The Global and Planetary Change study found that glacier area loss rates in the Langtang catchment increased more than fourfold from 1964 to 2023 – with melting accelerating after 2000.
It added that glaciers in the region also experienced “fragmentation” and “widespread thinning” over this period.
The study noted that this loss “coincided with elevation dependent warming”.
The figure below provides an overview of glacier loss in the Langtang catchment over 1964-2023, with orange, red and dark red indicating areas of retreat.
In addition, green dots note points of glacier fragmentation, while blue dots show separation and pink show disconnection.
In comments released by the University of Reading, Prof Maria Shahgedanova, a climate scientist researching climate impacts on mountain glaciers, said that the glacier involved in the floods had “retreated by approximately 450 metres between 1990 and 2020”.
She adds that this “potentially reduce[d] the mechanical support provided by the glacier to the underlying rock slope”.
Speaking to Carbon Brief, Davies reiterates that the retreat of the glacier is “potentially a contributing factor” to the bedrock collapse and subsequent disaster.
This is because the removal of the glacier from the lower slopes leaves the “upper rock slopes less stable”, she says.
The most recent assessment by the International Centre for Integrated Mountain Development said that glaciers in the Hindu Kush Himalaya region are “rapidly shrinking” as a result of climate change. (This region extends 3,500km over Afghanistan, Bangladesh, Bhutan, China, India, Myanmar, Nepal and Pakistan.)
It said this loss is threatening the safety of the nearly two billion people, including by increasing the risk of “glacial lake outburst floods” (GLOFs). A GLOF is a sudden and catastrophic release of meltwater from a glacial lake.
Although this disaster was not caused by a GLOF, it is known that climate change is making such events more likely.
Can the event be attributed to climate change?
In the wake of the flash floods, climate campaigners, media outlets and Nepalese politicians have linked them to human-caused climate change.
However, many climate scientists have cautioned that it is too early to say precisely how climate change impacted the disaster.
Davies tells Carbon Brief:
“These events happen so quickly that the exact causes and drivers can take a little time to uncover, especially if the event was a surprise and there had been no monitoring system in place.”
When trying to determine the role human-caused climate change played in the intensity or likelihood of extreme weather, scientists turn to the field of “attribution science”.
To date, no formal rapid attribution study has been produced that attempts to quantify whether – and how – climate change contributed to the event.
Scientists have noted that climate attribution of ice-rock avalanches – which are typically driven by a variety of factors – remains limited, in part because of the lack of a long-term observational record of previous collapses in high mountain areas.
Meanwhile, the studies that do exist stop short of directly linking such disasters to climate change. For example, the authors of a 2021 study into the Chamoli ice-rock avalanche concluded that “we cannot attribute this individual disaster specifically to climate change”.
However, they added, the “possibly increasing frequency of high-mountain slope instabilities can likely be related to observed atmospheric warming and corresponding long-term changes in cryospheric conditions (glaciers and permafrost)”.
In the aftermath of the disaster, many researchers have similarly highlighted that climate change could not be singled out as the cause of the disaster, even if warming likely increased the probability of its occurrence.
On the Climate Brink substack, Carbon Brief’s climate science contributor Dr Zeke Hausfather noted that a “definitive single-event attribution” of the more recent disaster “may never be possible” due to the “messy causality of rock-ice avalanches”.
However, he added that both the existing scientific literature and “essentially every scientist working on these hazards point in the same direction” – namely, that warming is making such events more likely in the Himalaya.
Steiner tells Carbon Brief it might be possible to attribute different factors that played a role in the disasters to climate change – for instance, the recession of the glacier – but it would be more difficult to do so for the event as a whole.
Part of the reason for this, he says, is that rock failures in this region of the Himalaya have occurred for millennia, well before humans started altering the climate.
However, he continues:
“The physics of it is not something that has been made possible by climate change. This could have happened without it. But the chance of it happening – and the likelihood of it happening five years after a previous, similar event [in Chamoli] – we, as the scientific community, can be pretty confident about that [being increased because of a changing climate].
“This is because so many of the changes that we know are related to climate change can potentially drive the build-up to eventual failure.”
Ultimately, says Davies, a “careful attribution study is needed, but it is hard to argue that the rapidly warming climate is not having an effect in these regions”. She adds:
“A single event may have multiple drivers, but we are seeing an increase in these events and are likely to see more as the permafrost and glacier melt continues.”
Related
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
Climate change exposes 580 million children to 20 extra ‘heat-stress days’ every year
Explainer: How the ‘super El Niño’ will reshape the world’s weather
Analysis: The two largest reservoirs in the US have hit record-low levels
The post Q&A: What can – and cannot – be said about global warming’s role in the 2026 Himalayan floods appeared first on Carbon Brief.
Q&A: What can – and cannot – be said about global warming’s role in the 2026 Himalayan floods
Chinese industry is beginning to shift from fossil fuels to clean electricity, with wind, solar and batteries progressively displacing coal, oil and gas across the industrial sectors that made the country the world’s factory and largest carbon emitter, a new analysis shows.
Clean electricity met all of China’s demand growth in 2025 and coal generation fell for the first time in a decade, even as electricity demand rose by 5%, the report found.
Despite a rebound in coal power generation in the first half of 2026, the analysis by global energy think-tank Ember found the growth in clean electricity illustrates a longer-term shift: a massive build-out of wind, solar energy and battery storage and deepening electrification of the economy are starting to make a dent in the fossil-fuel energy system supporting China’s industrial base.
China keeps Indonesia’s battery dream afloat but future less certain
The research identifies early signs that a structural transformation of China’s industrial economy from coal, oil and gas to clean electricity is underway, even if changes on the ground are not yet reflected in national data.
“The energy foundation of the Chinese industrial economy is shifting,” Muyi Yang, a senior energy analyst at Ember and the report’s lead author, told Climate Home News.
“Fossil fuels are progressively being replaced in the many functions they have historically assumed. Because of that, fossil fuel peaking is increasingly coming into view,” he said.
Electrifying industry
Coal generation has stopped growing in 17 of the 26 provinces and regions analysed by Ember between 2021 and 2025. This includes industrial centres such as Hunan in southern China and Shandong – home to energy-intensive industries like cement production. Together, these regions are home to more than half of China’s thermal power capacity.
A greater share of the Chinese economy is now running on electricity than in other major economies, accounting for 29% of final energy consumption in 2024, compared with about 23% in Europe and 21% in the US. Less than half of China’s electricity was generated from coal in the first half of the year.
-
China’s coal power rebounds as record clean energy goes to waste
Long-term contracts guarantee coal plants buyers regardless of demand, crowding out renewables, report finds -
China’s coal-chemicals boom risks repeating the mistakes of the past
By reviving the problematic industry in the name of energy security, China runs the risk of higher emissions, stranded assets and setting back its ambitions as a clean energy leader -
China’s carbon emissions rise again as more clean power is wasted
The economic powerhouse burned more coal and gas in the first quarter of 2026, despite record wind and solar build-out


Meanwhile, fossil fuel use has fallen in eight of 11 tracked industrial sectors, declining between 26% and 71% from peak consumption levels across fossil fuel extraction, manufacturing industries such as textiles, machinery and food and beverages, transport equipment and chemical materials.
Earlier this year, German company BASF, the world’s largest chemical producer, opened a new facility in southern China, which is fully supplied by renewable energy. The company said emissions from the site could be 50% lower than conventional petrochemical facilities.

In easier-to-electrify sectors such as machinery, electronics and textiles, electricity now supplies about three-quarters of final energy consumption, Ember found.
Fossil fuel use is also showing signs of flattening in the metals smelting and processing sector – one of the most fossil-intensive parts of the economy – offering “encouraging signs” that the transformation is starting to take hold in harder-to-abate sectors, said Yang.
“If that is happening in more and more provinces, and more and more economic sectors that means that fossil fuels are progressively being squeezed out of the energy system,” he said.
“Growing by greening”
China’s vast cleantech manufacturing power has become an engine for growth in its own right, spurring investment, creating jobs and generating export revenues.
Yang described this “growing-by-greening” dynamic as “turning each step of the transition into a source of strength for the next”.
China and Brazil join pledge to triple global nuclear energy capacity
For Li Shuo, director of China Climate Hub at the Asia Society Policy Institute, this is part of what makes China’s lead in manufacturing clean energy equipment “irreversible”, comparing its growth with that of a rainforest, where different parts of the ecosystem thrive by reinforcing one another.
The early success of deploying wind and solar helped drive down electricity costs, which created favourable conditions for the rapid adoption of electric vehicles (EVs) and in turn boosted demand for batteries that are now critical to balance the grid.

An oversupply of renewable energy incentivised industrial players to benefit from cheap and readily available clean power generation, encouraging innovative solutions to electrify other parts of the economy. In the transport sector, for example, electrification is moving from passenger vehicles to harder-to-electrify trucks.
This abundance of cheap green energy is also making China competitive in what has long been seen as the anchor of Western competitiveness, Li said.
Stalling fossil fuel use
At the same time, China’s huge legacy fossil fuel generation capacity is still expanding, even as coal power plants are being used less intensively.
China brought 30 GW of new coal power capacity into operation in the first six months of the year and coal-fired generation rose 3% over the same period after local governments fast-tracked coal projects to prevent a repeat of severe power shortages in 2021.
Solar surge kept fossil electricity flat in 2025 as China and India made ‘historic’ shift
A further 274 GW of coal capacity is either under construction or has permits to be built while vast amounts of solar and wind power that could not be absorbed by the grid have gone to waste in the first half of the year.
“This doesn’t mean that the transition is losing steam,” said Yang, arguing that China is now grappling with some of the more complex aspects of the transition.
A recent analysis by the Centre for Research on Energy and Clean Air (CREA) for Carbon Brief found that China’s CO2 emissions from fossil fuels and cement have plateaued for more than two years following a peak in March 2024. Ember found that on a 12-month moving average, coal generation has been stalling since then, following years of continuous expansion.
-
EU, UK lead push for electrification as “powerful weapon” against fossil fuels
A group of dozens of countries seeks to build momentum for a COP31 pledge to electrify 35% of global energy use by 2035 as an alternative to fossil fuels -
COP31 leaders unveil global targets, with spotlight on electrification
Co-hosts Türkiye and Australia want countries to sign on to global targets in three of their priority areas for this year’s COP climate negotiations -
Africa can lead the Age of Electrification
The electrification agenda presents both an extraordinary opportunity for Africa and an immense challenge for the continent


In the second quarter of the year, CO2 emissions fell by 1% after China’s oil consumption plummeted 9% as the US-Iran war prevented the transport of oil cargoes from the Gulf through the Strait of Hormuz.
The electrification of the transport sector, particularly electric trucks, was the biggest driver in displacing oil demand as the conflict in the Middle East accelerated the transition.
A lesson in sequencing
China’s bumpy transition offers a useful lesson for other countries at an earlier stage of their transition, said Xunpeng Shi, president of the Sydney-based International Society of Energy Transition Studies (ISETS), a global network of professionals that shares research and fosters collaborations.
“Build quickly enough so that clean electricity can start taking over and prepare for the pressure on the fossil system before it arrives, because that is the part nobody has done easily,” he said.
For countries that are heavily reliant on revenue from fossil fuel exports, a peak in Chinese fossil fuel use weakens the assumption of rising demand on which investments have long been made.
“For them, the time to plan for that is now, while the revenues are still there,” he said.
The post China’s industrial engine starts to break its fossil fuel habit appeared first on Climate Home News.
China’s industrial engine starts to break its fossil fuel habit
Carbon credit developers, corporate buyers and some leading conservation NGOs are challenging new proposed rules to stop UN carbon credits being wiped out by fire, drought or logging, in what critics have called a “coordinated lobbying campaign” to weaken the nascent market’s push for greater integrity.
According to documents seen by Climate Home News – including a briefing given to government officials – companies, NGOs and the UN Environment Programme (UNEP) have contested the scientific basis for the move, arguing that stronger protection for carbon reductions could hike project costs and restrict the supply of credits to the market.
The climate benefit of credits that claim to reduce or avoid greenhouse gas emissions by storing carbon is undone if that carbon is released back into the atmosphere – something known as reversal risk. To protect against such losses and preserve the credibility of the credits’ carbon-offsetting claims, projects are generally required to set aside a reserve of credits that cannot be sold, as a form of insurance.
How these “buffer pools” are calculated has long been a source of contention, especially in forest conservation projects, which many experts say have historically underestimated the risk of carbon losses.
In July, the technical UN panel tasked with drafting rules for the Article 6.4 mechanism, which underpins the credits that countries and companies can use to meet their climate goals, proposed a new system. It would require project developers to size these insurance pools of credits based on local risk values derived from new research published by a group of independent scientists.
UK’s budget juggling trick with rainforest loan for bus-fare cap needs transparency
Its supporters have hailed it as a more rigorous approach than current practice in the voluntary carbon market, which largely relies on expert guesswork and, in some cases, gives significant leeway for project developers to come up with their own data.
“The decision on the reversal risk assessment tool will be crucial,” said Federica Dossi, an expert at Brussels-based advocacy group Carbon Market Watch. “It would bring a new paradigm for calculating the number of units forwarded to the buffer pool based on empirical data.”
The technical panel is due to discuss the reversal risk tool and its application to a specific set of projects at a five-day meeting in Bonn this week. It is then expected to forward new recommendations to the mechanism’s regulator, the Supervisory Body, for a decision on whether to approve them at a meeting in early October.
The rules are set to be applied initially only to clean cookstove projects, one of the market’s most popular and heavily criticised credit types. They could then be extended to other activities, including programmes to protect forests.
Copy and paste?
More than 30 organisations aired their views in lengthy public submissions to the Article 6.4 mechanism, responding to a call from the UN secretariat for external feedback.
A Climate Home News review of those submissions found that there was significant overlap in their messages and, in several cases, sections of the text, or even entire submissions, were copied and pasted by different organisations. This points to a coordinated effort to flag concerns regarding the new rules.
In one instance, tech giant Apple, a large buyer of nature-based carbon credits, warned against relying on one scientific model and called for rules that let project developers use a variety of risk mitigation tools, rather than surrendering buffer credits, to cover the risk of carbon losses.
Apple’s submission is a lightly-edited version of a separate input presented by the Beyond Alliance, a coalition of corporate buyers and NGOs that promote market-based climate investments. In an apparent oversight in one paragraph, the Beyond Alliance’s name appears in Apple’s submission instead of the tech giant’s.
-
Most “zombie credits” locked out of new UN carbon market after China and India snub
Fears of a flood of environmentally-dubious carbon credits have faded, with most old projects not able to transition to new UN market -
UN’s first Paris Agreement carbon credits face human rights and climate concerns
Civil society groups allege the cookstove project in Myanmar exaggerated its climate impact while maintaining ties with military junta


The Beyond Alliance told Climate Home News that, after receiving input from its members, it shared its final submission, leaving them to decide if and how they wanted to use it. The coalition rejected any characterisation that its submission advocates for a weaker tool and only reflects business concerns.
The Beyond Alliance added that its members received briefings by UNEP, which Climate Home News understands has played an important role in wider efforts to influence the development of the rules underpinning the UN carbon market.
Three experts and a European Union diplomat told Climate Home News that the interventions of the UN agency overwhelmingly supported the views of those with a financial interest in carbon markets.
UNEP’s head of mitigation Gabriel Labbate rejected this accusation. He told Climate Home News that the UN agency contributes technical inputs from a “politically-neutral, science-based perspective” and its positions are grounded in an assessment of environmental integrity and are not shaped by, or aligned with, the financial interests of any market participant.
UNEP, NGOs criticise scientific basis
In mid-July, representatives from UNEP, Conservation International and The Nature Conservancy (TNC) briefed government officials from Canada, the UK, Germany, Costa Rica, Belgium, Nigeria and Peru, according to a webinar readout seen by Climate Home News.
The online event was organised by the Forest & Climate Leaders Partnership (FCLP), an initiative that brings together 41 countries plus the EU.
The speakers voiced strong criticism of the new proposed rules. A technical advisor to Conservation International, a US-based NGO that runs several large-scale carbon offsetting programmes, told participants the Article 6 panel’s approach was “based on bad science”. This, he said, is because it relies on a single model that he claimed is not appropriate to determine buffer pool contributions, according to a presentation seen by Climate Home News.
During a high-level discussion led by UNEP’s Labbate, speakers said the application of measures to manage reversal risk on cookstove projects could “impose disproportionate costs and undermine the financial viability of these activities”, according to the readout.

Cookstove programmes issue credits by calculating the greenhouse gas emissions prevented by burning less fuel – usually wood or charcoal – through the use of more efficient stoves. With the new reversal risk tool, these activities would be expected to guard against future carbon losses for the first time under the UN carbon market.
But UNEP, as well as leading NGOs and carbon credit firms, have pushed back against the requirement, arguing this type of credit represents a “flow” of avoided emissions rather than a “stock” of stored carbon that can be released. Scientists reject that distinction, noting that the wood left unburned is still standing in a forest exposed to the same risks as any other.
At the online briefing, speakers also raised concerns that the tighter approach would be replicated for nature-based carbon projects with a direct impact on the future of large-scale forest conservation credits. The Conservation International advisor called it a “bad precedent”.
Both Conservation International and TNC run carbon credit programmes that aim to protect trees from being cut down. Labbate leads the UN-REDD programme, which supports countries developing forest protection initiatives including through carbon credits, and is co-chair of the expert panel advising the Integrity Council for the Voluntary Carbon Market (ICVCM).
After the webinar, the organisers shared by email a series of “key messages” and draft submissions produced by the three organisations, which participants were invited to consider and adapt in their own inputs to the Article 6.4 consultation process.
Getting the rules ‘right’
In a statement to Climate Home News, Ghana, Paraguay and the UK – which are FCLP co-leads for its work on forest carbon credits – said members of the coalition welcomed expert views from a range of partners to help them understand the potential impact of Article 6.4 rules on the eligibility of forest carbon credits in international markets.
They added that the FCLP does not have a common position on the rules and its members are free to choose whether to attend webinars and use any of the materials circulated.
In a statement to Climate Home News, Conservation International said “getting these rules right is important to the environmental integrity of the carbon market, while ensuring all sectors have a place in it”. It added that the NGO does not dispute the validity of the scientific research underlying the proposed buffer pool, but recommends a broader approach including multiple models and datasets.
A spokesperson for TNC said the organisation had helped clarify complex materials and their potential implications, while decisions on how to respond remained entirely with participating countries.
‘Inconvenient science’
The scientific basis for the disputed reversal risk tool rests on two pieces of research. A peer-reviewed study, published in Nature in May and led by scientists at several US universities, modelled forest carbon-loss risk across the United States and found existing buffer pools there are undersized by an average factor of six.
To extend that approach worldwide, the Article 6.4 panel also drew on a second, global analysis by the same research team, which has not yet completed peer review. That study used satellite images, weather records and computer modelling to estimate a 31-42% chance of forests worldwide losing stored carbon within 100 years, depending on the scenario.
The panel picked one of these scenarios and turned its estimates into fixed risk percentages for individual countries, and in some cases provinces, which projects in those locations would need to apply.
Palestine: Israel’s bombing has left Gaza vulnerable to climate change
Critics say the peer-reviewed portion of the research was calibrated on North American forests, and that applying the same approach to other regions relies on a global study that is still going through academic checks.
But, for William Anderegg, professor of biological sciences at the University of Utah and one of the authors of that research, it is the best science currently available. He described it as “light-years better” than assumptions underlying the voluntary carbon market, where risk numbers are not generally based on independent evidence and tend to be incredibly low.
Scientific research, including by Anderegg, has found that buffer pools in forestry projects in the voluntary carbon market are substantially smaller than they should be to adequately protect against future releases of carbon.
“There really seems to be a fairly coordinated campaign to try to weaken the strength of these [Article 6.4] tools and their scientific underpinning,” he told Climate Home News. “It’s a little dispiriting to see folks attack science that’s inconvenient.”
Regulators under pressure?
An EU diplomat told Climate Home News that experts and negotiators working on the Article 6.4 mechanism have faced intense pressure from big carbon credit developers and large parts of the nature-based solutions community.
“It is very clear that they are lobbying against strong rules, and they want to align the Paris Agreement mechanism with the standards of the voluntary carbon market,” the diplomat said. “They have influence, time and money, even more than some governments, so they can be very effective in their efforts.”
Last year, the Article 6.4 Supervisory Body, the new market’s regulator, approved rules on the permanence of credits aiming to remove carbon from the atmosphere which critics said were watered down compared to the technical panel’s recommendations. This followed feedback from carbon market firms and conservation NGOs, which submitted dozens of critical views.
EU carbon credits could supercharge world’s clean cooking push, France says
Carbon Market Watch’s Dossi said decisions that strengthen environmental integrity are targeted in particular as they tend to reduce the number of credits that can be issued.
Then, as now, those who opposed tighter rules argued that overly strict safeguards would make some projects too expensive to carry out, with a negative impact on local communities and the climate.
But proponents argue that higher-integrity programmes will drive up market prices, ultimately benefiting everyone.
“If rules ensuring better-quality credits make them somewhat more expensive than they are today, that’s an acceptable consequence, not a reason to weaken the rules, especially since these credits will be used to offset continued emissions,” said Dossi.
Efforts to pull the rule-makers in different directions are expected to intensify in the coming weeks as a decision on the new credit protection system nears.
“I really don’t know how this will turn out in the end,” one veteran carbon market expert said. “What I am sure about is that it will be quite a battle.”
The post Industry and NGOs lobby to weaken UN carbon credit rules in “coordinated” push appeared first on Climate Home News.
Industry and NGOs lobby to weaken UN carbon credit rules in “coordinated” push



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits