

Electric vehicles (EVs) now account for more than one-in-four car sales around the world, but the next phase is likely to depend on government action – not just technological change.
That is the conclusion of a new report from the Centre for Net Zero, the Rocky Mountain Institute and the University of Oxford’s Environmental Change Institute.
Our report shows that falling battery costs, expanding supply chains and targeted policy will continue to play important roles in shifting EVs into the mass market.
However, these are incremental changes and EV adoption could stall without efforts to ensure they are affordable to buy, to boost charging infrastructure and to integrate them into power grids.
Moreover, emerging tax and regulatory changes could actively discourage the shift to EVs, despite their benefits for carbon dioxide (CO2) emissions, air quality and running costs.
This article sets out the key findings of the new report, including a proposed policy framework that could keep the EV transition on track.
A global tipping point
Technology transformations are rarely linear, as small changes in cost, infrastructure or policy can lead to outsized progress – or equally large reversals.
The adoption of new technologies tends to follow a similar pathway, often described by an “S-curve”. This is divided into distinct phases, from early uptake, with rapid growth from very low levels, through to mass adoption and, ultimately, market saturation.
However, technologies that depend on infrastructure display powerful “path-dependency”, meaning decisions and processes made early within the rollout can lock in rapid growth, but equally, stagnation can also become entrenched, too.
EVs are now moving beyond the early-adopter phase and beginning to enter mass diffusion. There are nearly 60m on the road today, according to the International Energy Agency, up from just 1.2m a decade ago.
Technological shifts of this scale can unfold faster than expected. Early in the last century in the US, for example, millions of horses and mules virtually disappeared from roads in under three decades, as shown in the chart below left.
Yet the pace of these shifts is not fixed and depends on the underlying technology, economics, societal norms and the extent of government support for change. Faster or slower pathways for EV adoption are illustrated in the chart below right.
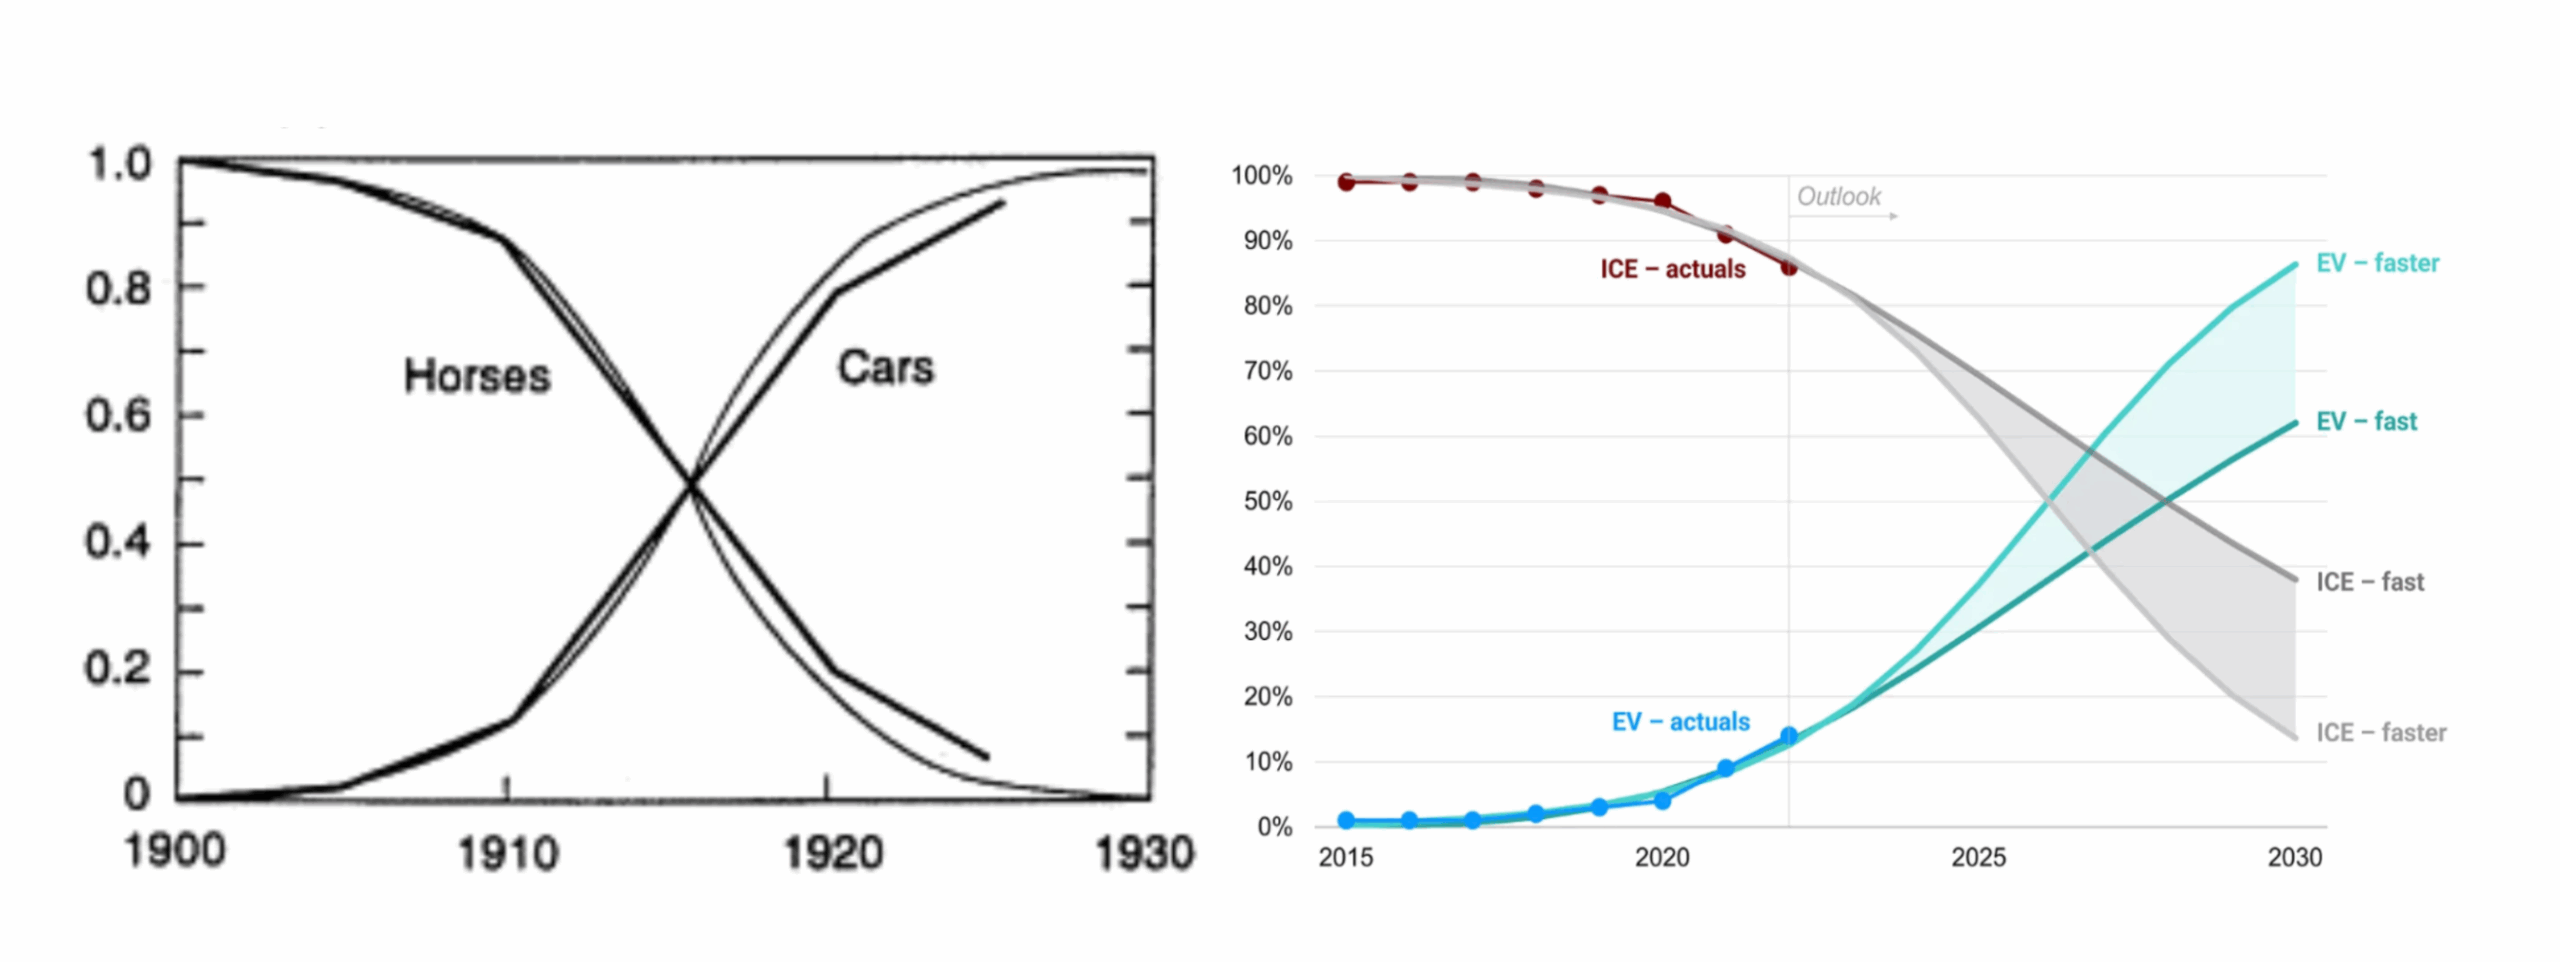
Internal combustion engine (ICE) vehicles did not prevail in becoming the dominant mode of transport through technical superiority alone. They were backed by massive public investment in roads, city planning, zoning and highway expansion funded by fuel taxes.
Meanwhile, they faced few penalties for pollution and externalities, benefitting from implicit subsidies over cleaner alternatives. Standardisation, industrial policy and wartime procurement further entrenched the ICE.
EVs are well-positioned to follow a faster trajectory, as they directly substitute ICE vehicles while being cleaner, cheaper and quieter to run.
Past transitions show that like-for-like replacements – such as black-and-white to colour TVs – tend to diffuse faster than entirely novel products.
Late adopters also benefit from cost reductions and established norms. For example, car ownership took 60 years to diffuse across the US, but just 20 years in parts of Latin America and Japan.
In today’s globalised economy, knowledge, capital and supply chains travel faster still. Our research suggests that the global EV shift could be achieved within decades, not half a century.
Yet without decisive policy, investment and coordination, feedback loops could slow, locking in fossil-fuel dependence.
Our research suggests that further supporting the widespread deployment of EVs hangs on three interlinked actions: supporting adoption; integrating with clean electricity systems; and ensuring sustainability across supply chains and new mobility systems.
Closing the cost gap
EVs have long offered lower running costs than ICE vehicles, but upfront costs – while now cost-competitive in China, parts of Europe and in growing second-hand markets – remain a major barrier to adoption in most regions.
While battery costs have fallen sharply – lithium-ion battery packs fell by 20% in 2024 alone – this has not fully translated into lower retail vehicle prices for consumers.
In China, a 30% fall in battery prices in 2024 translated into a 10% decline in electric SUV prices. However, in Germany, EV retail prices rose slightly in 2024 despite a 20% drop in battery costs.
These discrepancies reflect market structures rather than cost fundamentals. Our report suggests that a competitive EV market, supported by transparent pricing and a strong second-hand sector, can help unlock cost parity in more markets.
Beyond the sale of EVs, government policy around running costs, such as fuel duty, has the potential to disincentivse EV adoption.
For example, New Zealand’s introduction of road-pricing for EVs contributed to a collapse in registrations from nearly 19% of sales in December 2023 to around 4% in January 2024.
EV-specific fees have also been introduced in a number of US states. Last month, the UK also announced a per-mile charge for EVs – but not ICEs – from 2028.
Addressing the loss of fuel-duty revenue as EVs replace ICE vehicles is a headache for any government seeking to electrify mobility.
However, to avoid slowing diffusion, new revenues could be used to build out new charging infrastructure, just as road-building was funded as the ICE vehicle was scaling up.
While subsidies to support upfront costs can help enable EV adoption, the best approach to encouraging uptake is likely to shift once the sector moves into a phase of mass diffusion.
Targeted support, alongside innovative financing models to broaden access, from blended finance to pay-as-you-drive schemes, could play a greater role in ensuring lower-income drivers and second-hand buyers are not left behind.
Mandates as engines of scale
Zero-emission vehicle (ZEV) mandates and ICE phase-out deadlines can reduce costs more effectively than alternatives by guaranteeing market scale, our research finds, reducing uncertainty for automakers and pushing learning rates forward through faster production.
California’s ZEV mandate was one of the first in the 1990s, a policy that has since been adopted by ten other US states and the UK.
China’s NEV quota system has produced the world’s fastest-growing EV market, while, in Norway, clear targets and consistent incentives mean EVs now account for nearly all of new car sales. These “technology-forcing” policies have proved highly effective.
Analyses consistently show that the long-run societal benefits of sales mandates for EVs far outweigh their compliance costs.
For example, the UK’s ZEV mandate has an estimated social net present value of £39bn, according to the government, driven largely by emissions reductions and lower running costs for consumers.
Benefits can also extend beyond national borders. For example, California’s “advanced clean cars II” regulations – adopted by a number of US states and an influence on other countries – have been instrumental in compelling US automakers to develop and commercialise EVs, which can, in turn, trigger innovation and scale to reduce costs worldwide.
Research suggests that, where possible, combining mandates and incentives creates further synergies: mandates alleviate supply-side constraints, making subsidies more effective on the demand side.
Public charging: a critical bottleneck
Public charging is one of the most significant impediments to EV adoption today.
Whereas EVs charged at home are substantially cheaper to run than ICE vehicles, higher public charging costs can erase this benefit – in the UK, this can be up to times the home equivalent.
While most homes in the UK, for example, do have access to off-street parking, there are large swathes of low-income and urban households without access to private driveways. For these households, a lack of cheap public charging has been described as a de facto “pavement tax”, which is disincentivising EV adoption and resulting in an inequitable transition.
Our research shows that a dual-track charging strategy could help resolve the situation. Expanding access to private charging – through cross-pavement cabling, “right-to-charge” legislation for renters and planning mandates for new developments could be combined with strategic investment in public charging, to overcome the “chicken-and-egg” problem for investors uncertain about future EV demand.
Meanwhile, “smart charging” in public settings – where EV demand is matched with cheaper electricity supply – can also help close the affordability gap, by delivering cheap off-peak charging that is already available to those charging at home.
The Centre for Net Zero’s research shows that drivers respond to dynamic pricing outside of the convenience of their homes, which reduces EV running costs below those of petrol cars.
The figure below shows that, while the level of discount being offered had the strongest impact, lower-income areas showed the largest behavioural response, indicating that they may stand to gain the most from a rollout of such incentives.
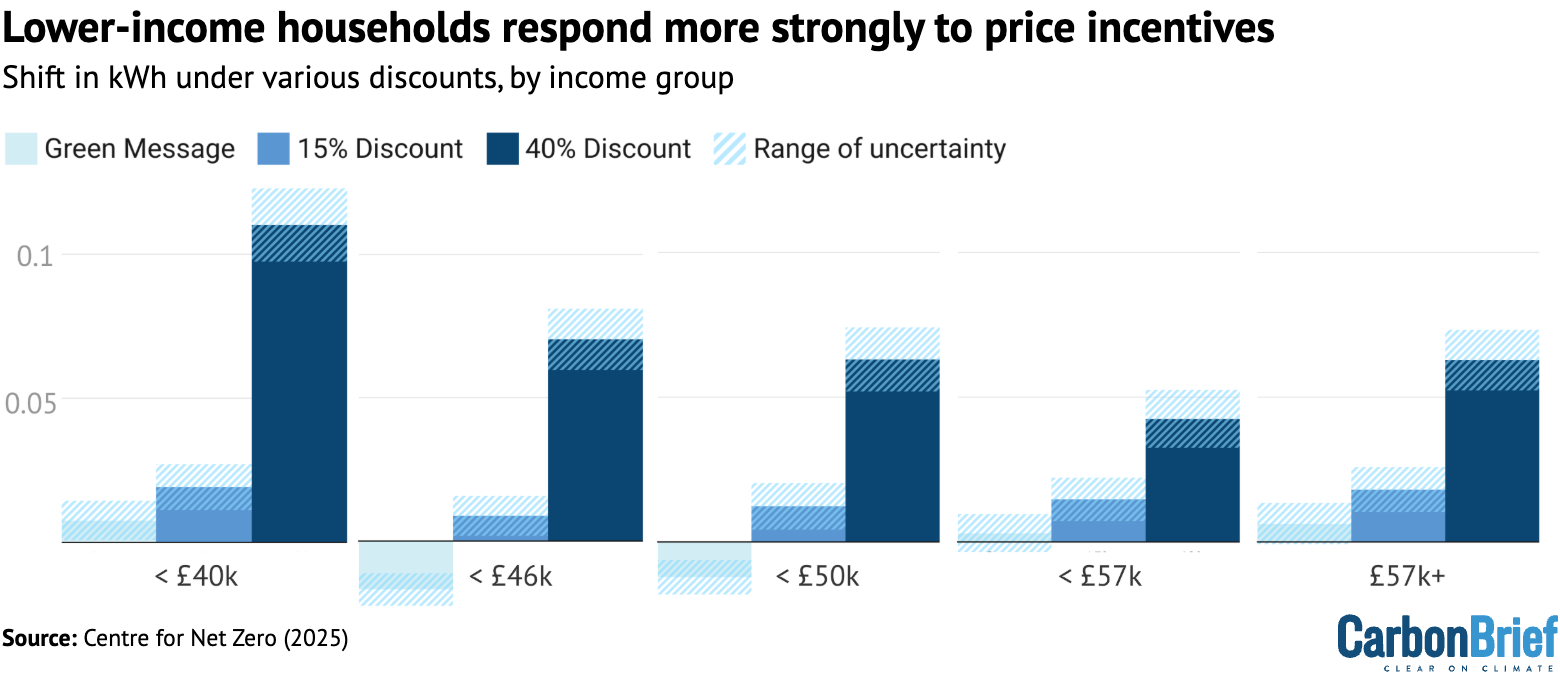
Our research suggests that policymakers could encourage this type of commercial offering by creating electricity markets with strong price signals and mandating that these prices are transparent to consumers.
Integrating with clean electricity grids
Electrification is central to decarbonising the world’s economies, meaning that sufficient capacity on electricity networks is becoming a key focus.
For the rollout of EVs, pressure will be felt most on low-voltage “distribution” networks, where charging is dispersed and tends to follow existing peaks and troughs in domestic demand.
Rather than responding to this challenge by just building out the grid – with the corresponding economic and political implications – making smart charging the norm could help mitigate pressure on the network.
Evidence from the Centre for Net Zero’s trials shows that AI-managed charging can shift EV demand off-peak, reducing residential peak load by 42%, as shown in the chart below.
Additionally, the amount of time when EVs are plugged in but not moving is often substantial, giving networks hours each day in which they can shift charging, targeting periods of low demand or high renewable output.
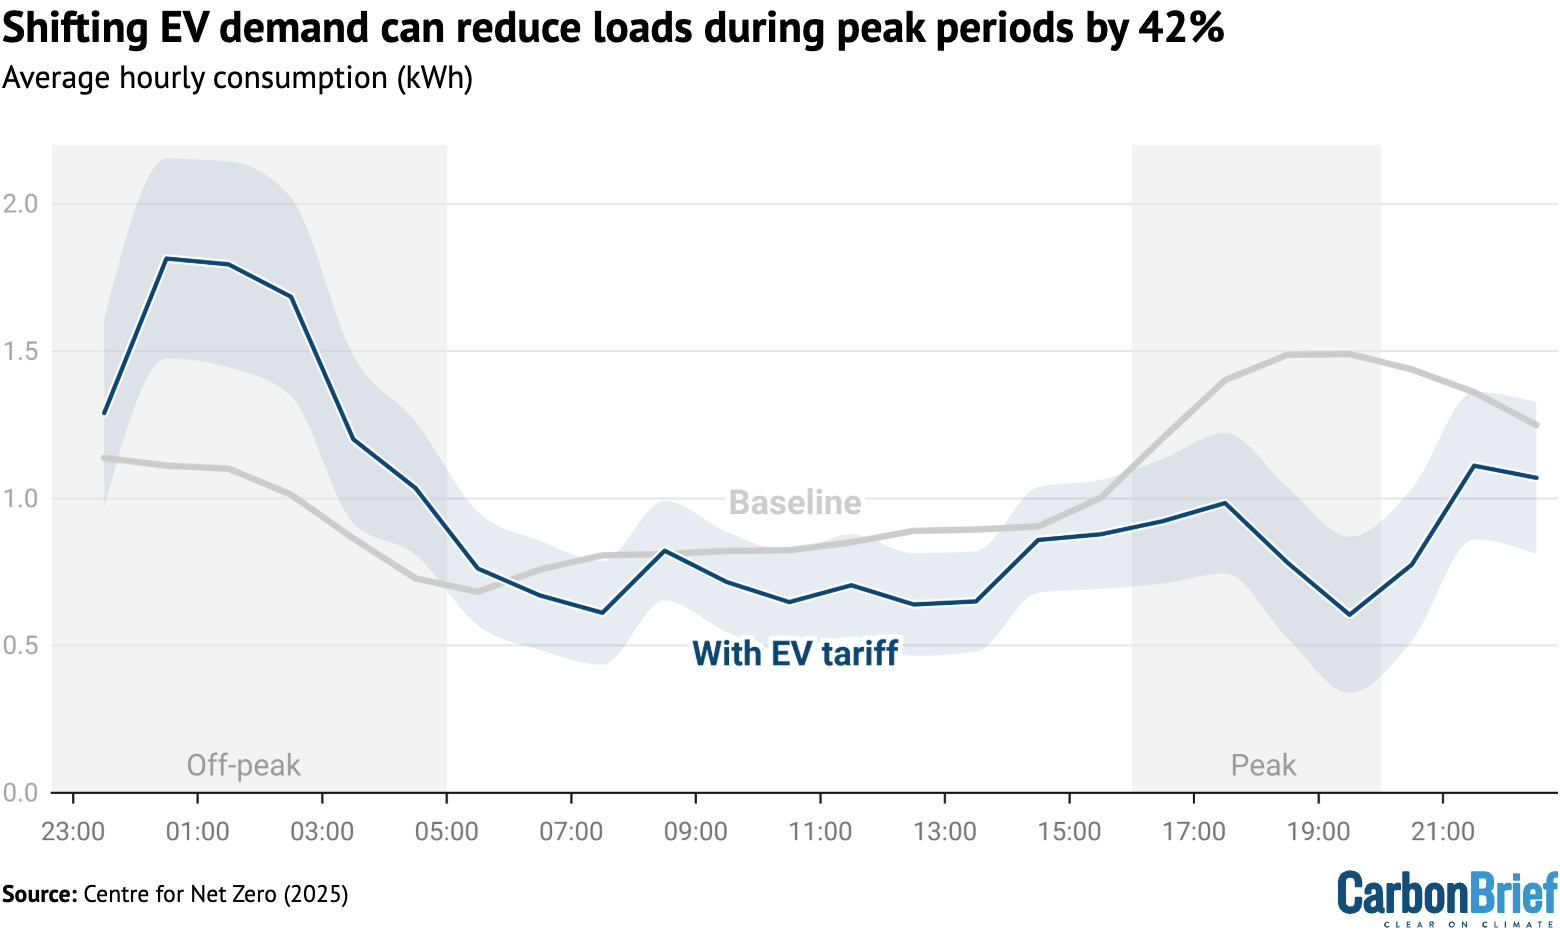
The system value of this flexible charging is significant. In the UK, managed charging could absorb 15 terrawatt hours (TWh) of renewable electricity that would otherwise be curtailed by 2030 – equivalent to Slovenia’s entire annual consumption.
For these benefits to be realised, our research suggests that global policymakers may need to mandate interoperability across vehicles, chargers and platforms, introduce dynamic network charges that reflect local grid stress and support AI-enabled automation.
Bi-directional charging – which allows EVs to export electricity to the grid, becoming decentralised, mobile storage units – remains underexploited. This could allow EVs to contribute to the capacity of the grid, helping with frequency and providing voltage support at both local and system levels.
The nascency of such vehicle-to-grid (V2G) technology means that penetration is currently limited, but there are some markets that are further ahead.
For example, Utrecht is an early leader in real-world V2G deployment in a context of significant grid congestion, while Japan is exploring the use of V2G for system resilience, providing backup power during outages. China is also exploring V2G systems.
Our research shows that if just 25% of vehicles across six major European nations had V2G functionality, then the theoretical total capacity of the connected vehicles would exceed each of those country’s fossil-fuel power fleet.
Mandating V2G readiness at new chargepoints, aligning the value of exports with the value to the system and allowing aggregators to pool capacity from multiple EVs, could all help take V2G from theory to reality.
A sustainable EV system
It is important to note that electrification alone does not guarantee sustainability.
According to Rocky Mountain Institute (RMI) analysis, the total weight of ore needed to electrify the world’s road transport system is around 1,410mtonnes (Mt). This is 40% less than the 2,150Mt of oil extracted every year to fuel a combustion-based system. EVs concentrate resource use upfront, rather than locking in fossil-fuel extraction.
Moreover, several strategies can reduce reliance on virgin minerals, including recycling, new chemistries and improved efficiency.
Recycling, in particular, is progressing rapidly. Some 90% of lithium-ion batteries could now be recycled in some regions, according to RMI research. Under an accelerated scenario, nearly all demand could be met through recycling before 2050.
Finally, while our report focuses largely on EVs, it is important to highlight that they are not a “silver bullet” for decarbonising mobility.
Cities such as Seoul and New York have demonstrated that micromobility, public transport and street redesign can cut congestion, improve health and reduce the number of overall vehicles required.
Better system design reduces mineral demand, lowers network strain and broadens access.
The ‘decision decade’ ahead
Policy decisions made today will determine whether EVs accelerate into exponential growth or stall.
Our research suggests that governments intent on capturing the economic and environmental dividends of electrified mobility are likely to need coherent, cross-cutting policy frameworks that push the market up the steep climb of the EV S-curve.

The post Guest post: How to steer EVs towards the road of ‘mass adoption’ appeared first on Carbon Brief.
Guest post: How to steer EVs towards the road of ‘mass adoption’

When oil and gas shipments stopped flowing through the Strait of Hormuz at the start of the Iran war, Southeast Asian nations were left reeling as the supply crunch laid bare their acute reliance on fossil fuel imports.
As prices soared, governments in the region scrambled to introduce emergency energy-saving measures – from a four-day working week to curbs on air conditioning. Thailand revived decommissioned coal plants while the Philippines, which imports nearly all of its oil, declared a “national energy emergency”.
But the crisis has also prompted renewed resolve to find a long-term solution to their vulnerability at a time when electricity demand is booming to power the region’s growing industry, cooling needs and the mushrooming of energy-hungry data centres.
At the heart of Southeast Asian nations’ response is a longstanding infrastructure project to connect the region’s power grids by 2045 and enable cross-border trading of clean electricity through a network of underground and subsea interconnectors.
-
Southeast Asia’s fragile grids threaten billions in clean energy investment
Renewables developers need reliable electricity infrastructure and stable policies to help the region meet climate goals and surging demand for power -
UN backs push to upgrade grids slowing clean power uptake in Africa and SE Asia
The Global Grids Accelerator will help turn national and regional plans to expand electricity infrastructure into viable projects on the ground -
China keeps Indonesia’s battery dream afloat but future less certain
Chinese capital and technology turned Indonesia into the world’s top nickel supplier, but its dependence on China and the rise of nickel-free batteries could upset its battery ecosystem plans
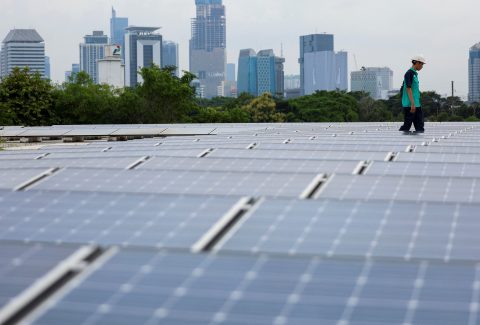
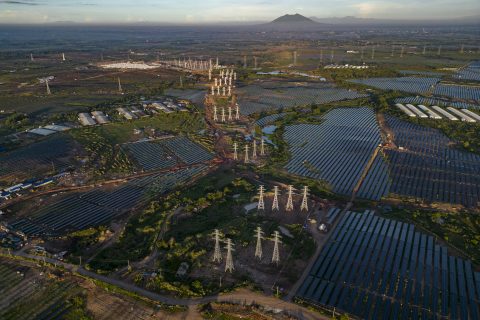
The plans will allow nations with high renewable energy generation potential to trade surplus power to their neighbours and major demand centres like Singapore, helping to integrate more renewables into the power mix and reduce reliance on fossil fuel imports.
“[It] will give us more energy security,” the Philippines’ energy secretary, Sharon Garin, told a press conference after a meeting of the Association of Southeast Asian Nations’ (ASEAN) energy ministers last week, when they discussed accelerating the delivery of the regional grid as part of measures to respond to the energy crisis.
“The Philippines is rich in solar power, Malaysia is rich in hydropower and Indonesia has geothermal: different countries have different resources. [The ASEAN Power Grid] will optimise the utilisation of renewables to the benefits of each member state,” said Garin.
But turning this decade-old political vision into a reality has been slow, held up by painstaking work to harmonise a patchwork of regulatory and legal frameworks and mobilise the private capital needed to build cross-border infrastructure.
More than $300 billion is needed to expand and modernise the region’s fragile grids to support the projected energy demand increase by 2050. This includes $27 billion required to deliver the cross-border interconnections by 2040, according to the International Energy Agency (IEA).
Every year of delay could cost the region billions of dollars in additional fuel costs and lock in new gas infrastructure for decades to come, according to analysis by global energy think-tank Ember.
The building block for energy security
With electrification high on the agenda of the COP31 climate talks in Türkiye next month, there is growing attention on the need to modernise and expand grid infrastructure to cope with growing electricity use and more renewables in the power mix.
Clean electrification and energy efficiency could deliver about a third of cumulative carbon emission reductions between 2026 and 2050, according to the International Renewable Energy Agency’s World Energy Outlook. But delivering that would require doubling annual global grid investment to $1 trillion between now and 2035.
Last month, the UN launched an initiative to accelerate investment into expanding and modernising grids in Southeast Asia and Africa.
First conceptualised in 1997, the ASEAN Power Grid has gained fresh impetus in recent years as countries turn to renewables to cut their emissions and move away from volatile fossil fuel markets.
Energy supply disruption caused by wars in Ukraine and the Middle East has strengthened the case for regional grid connections. Before this year’s conflict began, the Middle East accounted for 60% of Southeast Asia’s crude oil imports. Competition for fewer, more expensive oil and gas shipments has left Southeast Asia facing a $160 billion energy import bill this year. Based on current policies, this could rise to $400 billion by mid-century.
In the Philippines last week, energy ministers agreed on an enhanced planning framework to deliver the ASEAN Power Grid and made progress on regulatory guidelines.
Garin said ministers were considering accelerating the project’s delivery. “The first study was to connect [by] 2045 – that’s too far,” she said.
A strong business case
The economic benefits of the plan have “captured the political imagination” of leaders in the region, Robert Cooke, grids advocacy lead at the Global Renewables Alliance, told Climate Home News. “The business case is stronger than ever,” he said.
“If countries were to go about building their own separate grids, of course that would be an expensive endeavour. But the discussion around the ASEAN Power Grid includes what costs could we share in building out this grid,” added Tiza Mafira, director of the Indonesia office for the Climate Policy Initiative.
Stronger grids would help the region meet collective targets to increase the share of renewable energy in total primary energy supply from 14% to 30% and in installed power capacity from 34% to 45% by 2030.
Connecting and pooling dispersed renewable resources would also help smooth local power shortages caused by daily and seasonal variations, reducing the need for backup gas plants and battery storage.
The IEA found the ASEAN Power Grid could help unlock some of the 20 terawatts of untapped solar and wind potential across Southeast Asia – an amount around 55 times the region’s current total power capacity.
From lines on a map to shovels in the ground
Rather than building a single unified network, the ASEAN Power Grid is developing cross-border links between neighbouring countries and smaller groups of nations.
As of 2025, nine of 18 priority interconnection projects are operational – accounting for around 10 GW of capacity with an additional 13.7 GW planned by 2040.
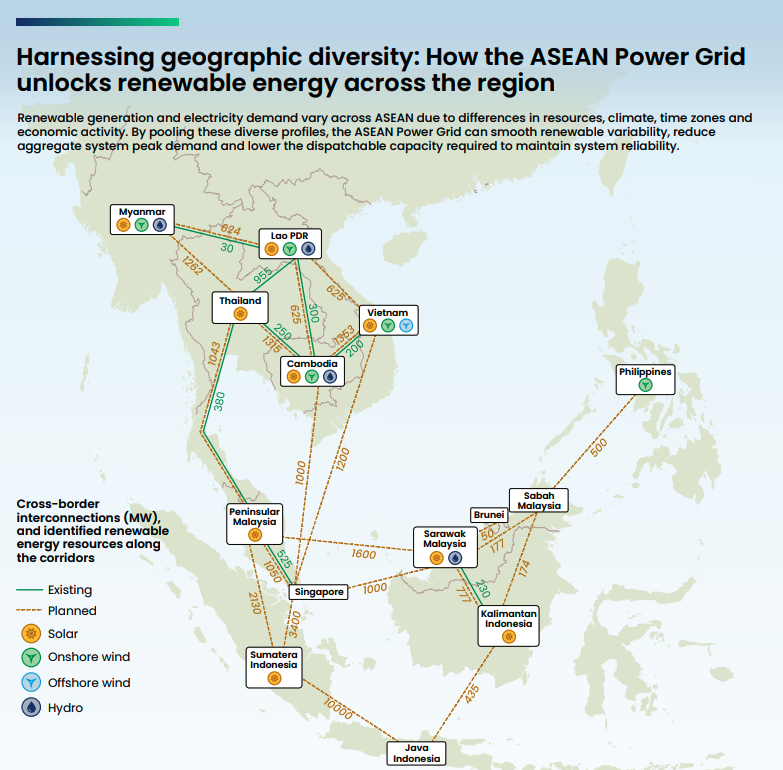
Source: Ember
A power line channelling up to 200 MW of clean electricity generated from hydropower in Laos to Singapore via Thailand and Malaysia has emerged as a key building block for grid-to-grid trading.
Progress on technical discussions will also help provide the clarity the private sector needs to invest in bankable projects, said Cooke.
In 2025, the Asian Development Bank and the World Bank announced a dedicated funding initiative to support the project.
“The enabling pieces are emerging,” said Monalisa Dimalanta, former chair of the Philippine Energy Regulatory Commission and the National Renewable Energy Board. “But the timelines remain unclear and a 2045 vision cannot answer today’s emergency,” she said.
“A power grid… that exists only on paper will not keep the lights on.”
Singapore: the delivery test
The implications of failing to deliver the ASEAN Power Grid are most acute in Singapore.
Constrained by space, with few renewable energy resources and dependent on gas for more than 90% of its electricity mix, Singapore has emerged as a leading proponent of a regional power grid as it seeks to achieve net-zero emissions by 2050.
To meet its power needs, the city-state aims to import 6 GW of low-carbon electricity by 2035, around one-third of its energy demand – a target which it is