

China and India accounted for 87% of the new coal-power capacity put into operation in the first half of 2025, whereas other regions continued to move away from coal.
These developments, highlighting a growing global divide between many countries phasing out coal power and a handful continuing to expand new capacity, are revealed in Global Energy Monitor’s latest Global Coal Plant Tracker results and reported here for the first time.
The results include Ireland becoming the fifth EU country to phase out coal power and Latin America becoming a region with zero active proposals for new coal capacity.
Meanwhile, the results show the US is on track to retire more coal capacity in 2025 than it did under the Biden administration last year, despite the efforts of the Trump White House.
Moreover, rather than follow the US in turning away from clean-energy leadership, other countries have continued their efforts to phase down coal power, with “just energy transition partnerships” (JETPs) advancing in Vietnam, Indonesia and South Africa during 2025 to date.
EU and Latin America pave the way for coal phaseout
The EU and Latin America are emerging as the global leaders in phasing out coal power, according to GEM’s analysis.
On the heels of the UK coal phaseout in 2024, Ireland stopped the use of coal power in June 2025, with nine EU countries expected to follow suit through 2029, including Spain, France and the Netherlands.
In total, all but three EU countries are planning to phase out coal by 2033, as shown in the chart below.
According to the International Energy Agency (IEA), coal power should be virtually phased out in advanced economies by 2030 and the rest of the world by 2040 to keep warming below 1.5C, as the Paris Agreement targets.
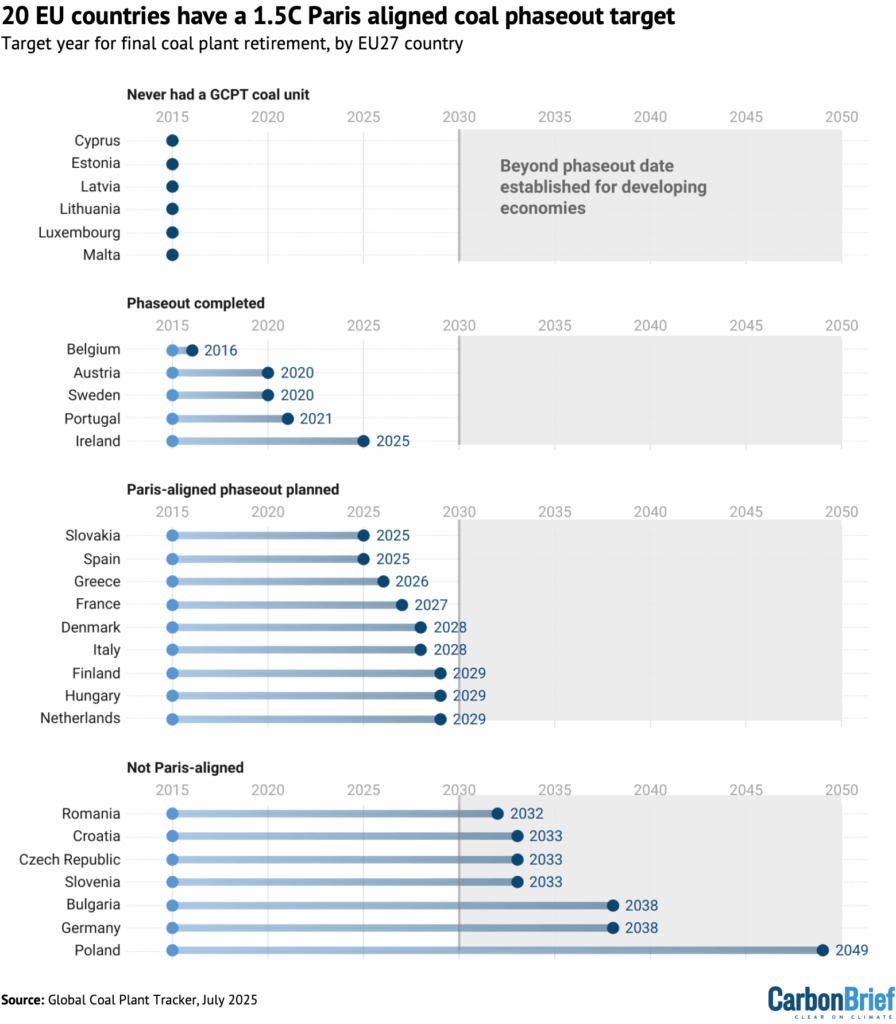
Development has also ceased in the region. No new coal plants have been proposed in the EU since 2018 and no coal plants have entered construction since 2019.
The coal phaseout in the EU and UK has been driven by a combination of country commitments and supporting policies and regulations, including air and carbon pollution limits on power plants, carbon pricing and policy support for clean-energy deployment.
Coal-power capacity retirements in the EU stalled for two years, following gas shortage concerns in the wake of Russia’s invasion of Ukraine, but they have since accelerated.
Coal capacity retired in the first half of 2025 (2.5GW) has already nearly exceeded all of 2023 (2.7GW) – with another 11GW planned for retirement in the EU by the end of the year.
GEM data shows that, in Latin America, the shelving of two coal-plant proposals in Honduras and Brazil in 2025 has left the region with no new coal plants actively proposed, as shown in the chart below – a collapse of the 18 plants totalling 7.3GW of capacity proposed in 2015.
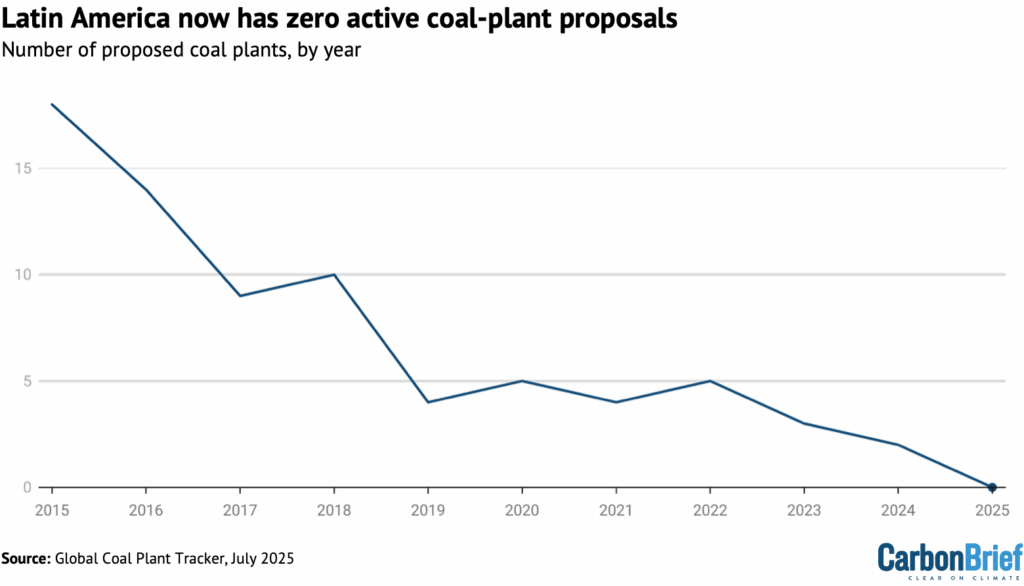
This followed the entry of Honduras into the Powering Past Coal Alliance (PPCA) in May and the lack of new coal plants proposed in Brazil’s 2025 national energy auctions, with a decrease in coal-power generation projected through 2034 in Brazil’s most recent 10-year energy plan.
Latin America is also nearly on track for a coal-power pathway that would be aligned with the 1.5C target of the Paris Agreement. More than 60% (10GW) of its 16.3GW of operating coal-power capacity is scheduled to come offline by 2040.
China and India continue to dominate
China and India dominated coal development in the first half of 2025, as the two countries had more new proposals, construction starts and coal plants commissioned than the rest of the world combined, GEM’s tracker shows.
As the chart below shows, there were 74.7GW and 12.8GW of newly proposed coal projects in China and India, respectively, in the first half of 2025, compared to just 11GW in the rest of the world.
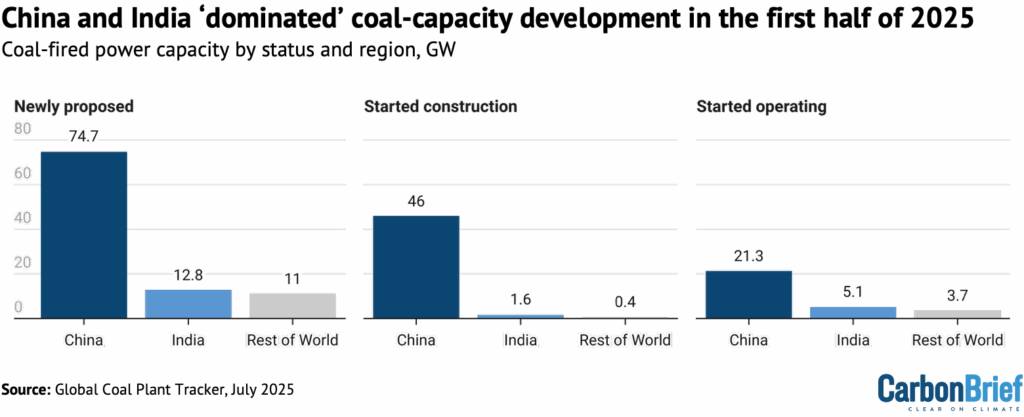
Construction starts and restarts in China also reached 46GW, putting the country on track to match the record levels of 2024, when more than 97GW of coal-power plants began construction.
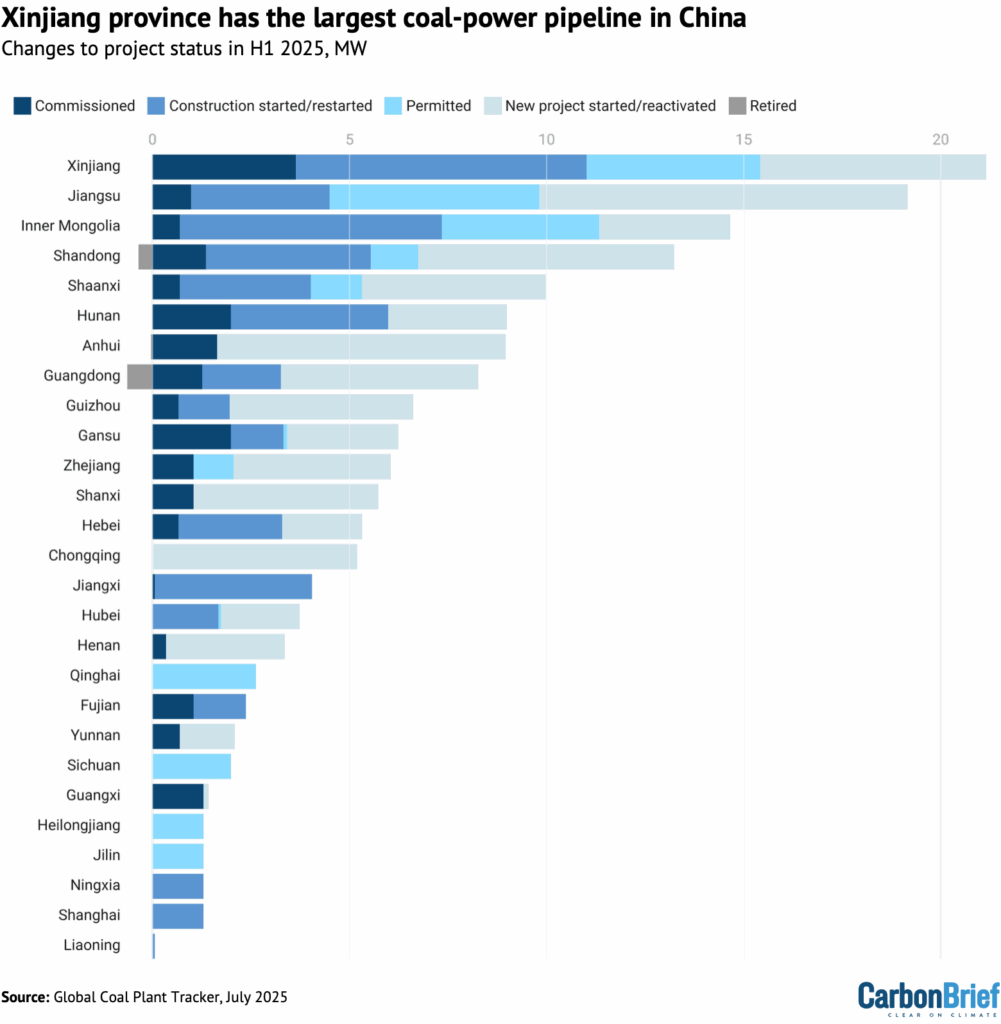
As discussed in GEM’s recent joint report with the Centre for Research on Energy and Clean Air (CREA), major coal-producing provinces, including Xinjiang, Inner Mongolia, Shandong and Shaanxi, are among the provinces commissioning and building the most new coal power, as shown in the chart below.
This expansion is backed by established permitting pathways, strong local power companies and a reliable flow of investment.
Yet, China has also been installing record amounts of clean energy, with more than 500GW of solar and wind power expected to come online in 2025. The increased generation from solar and wind power exceeded the increase in power demand in the first half of 2025, helping drive down China’s CO2 emissions by 1% compared to last year.
As clean energy has gained growing significance in China’s energy mix, more attention is being placed on renewables’ role in energy security and on coal power’s future as a flexible, supporting resource rather than as a primary generator.
Despite this narrative shift, coal remains deeply embedded in China’s power system, with little public discussion of its phasedown or eventual exit.
Coal-plant development is also on the rise in India, GEM’s tracker shows.
Commissioning of new coal plants in the country in H1 2025 (5.1GW) has already exceeded all of last year (4.2GW), as shown in the chart below.
Proposed coal-power capacity in India has also been on the rise, led by a record 38.4GW of coal-plant proposals in 2024 – driving up proposed coal capacity to over 92GW as of July 2025.
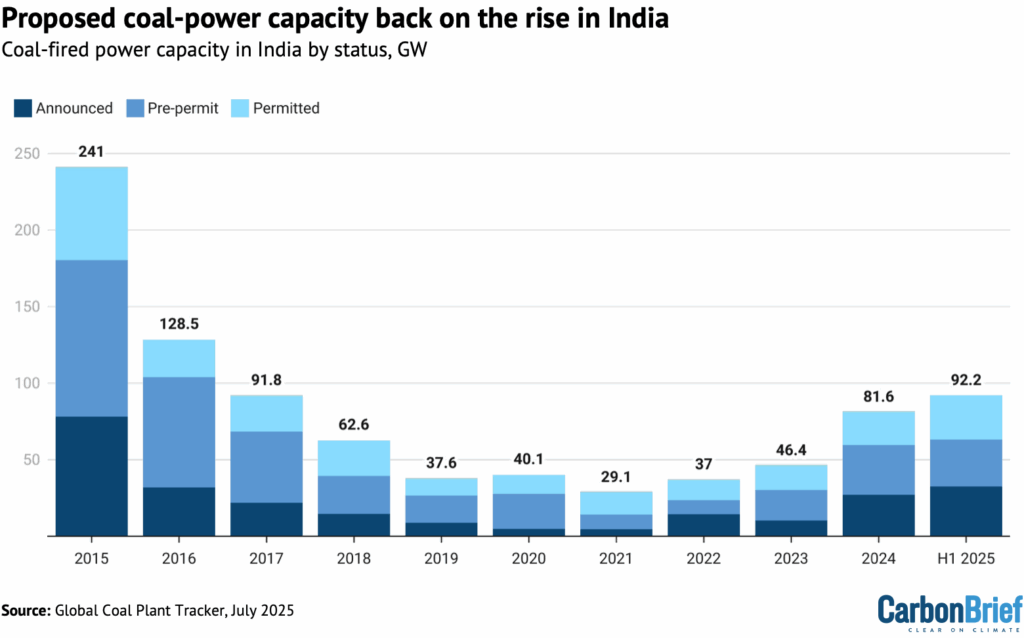
Retirements also remained sluggish in India, with 0.8GW retired in H1 2025 and just 0.2GW retired in 2024 and 2023, according to GEM’s tracker.
The decline follows 2023 guidance by India’s Central Electricity Authority (CEA) advising power utilities not to retire any thermal power capacity until 2030. In 2025, the country’s environment ministry again delayed long-pending sulfur dioxide regulations on coal plants.
Yet India also added more than 28GW of wind and solar power in 2025, a nearly 50% increase over the previous year. Despite the growth, the Indian government has stated that it is planning a coal expansion, with coal use not projected to peak until 2040, according to India’s Ministry of Coal.
In both China and India, coal retains its policy support, with clean energy framed, not as a replacement, but as a supplement – reinforcing a dual-track energy strategy that postpones difficult decisions on coal phaseout.
The US goes big on ageing coal plants
Like China and India, the US under President Donald Trump is also supporting coal power. Unlike China and India, however, the US has reversed course on clean energy in the first half of 2025.
During his tenure, former US president Joe Biden reached an agreement with other G7 nations to phase out coal power by 2035, offered incentives for clean energy under the Inflation Reduction Act (IRA) and moved to finalise pending power plant regulations – effectively helping replace the nation’s ageing coal plants with lower-cost solar and wind power while boosting domestic cleantech manufacturing.
The Trump administration has moved to derail Biden’s agenda by phasing out the clean energy tax credits, repealing coal plant regulations and slowing or halting solar and wind power permitting and financing.
It has also been using “emergency powers” to keep coal plants online, racking up $29m in costs to extend the life of Michigan’s Campbell plant through the summer – costs the utility is seeking to pass on to ratepayers for power the grid operator said was not needed.
Despite the political support for coal, the US remains on track to retire more coal power in 2025 than in 2024, with 3.7GW retired as of July.
Whether this trend continues in an increasingly uncertain environment for clean energy remains to be seen, as plant closures are often part of long-term plans and economic considerations, usually extensively negotiated with state regulators and based on broader considerations than just current federal policy.
In all, US utilities are slated to close nearly 100GW of coal capacity by 2035, as shown in the chart below. By then, the average age of a US coal plant will be 55 years.
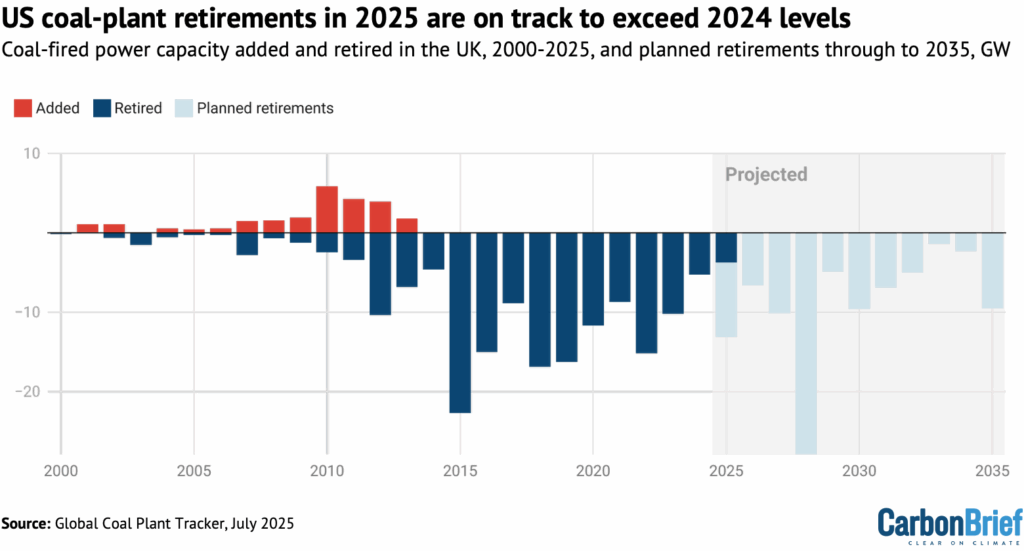
The US also saw a new coal plant proposal in H1 2025, bringing the total to three proposals according to GEM’s tracker, the most of any OECD country. All three plan to incorporate carbon capture and storage, although none have the necessary permits for construction.
Just energy transition partnerships advance despite hurdles
Despite delayed documentation, ongoing negotiations and the withdrawal of the US from International Partner Group participation, JETP agreements in Vietnam, Indonesia and South Africa are all continuing to progress.
In Vietnam, three clean-energy investment projects have officially penned financing agreements as of July 2025, getting the country one step closer to mobilising JETP capital.
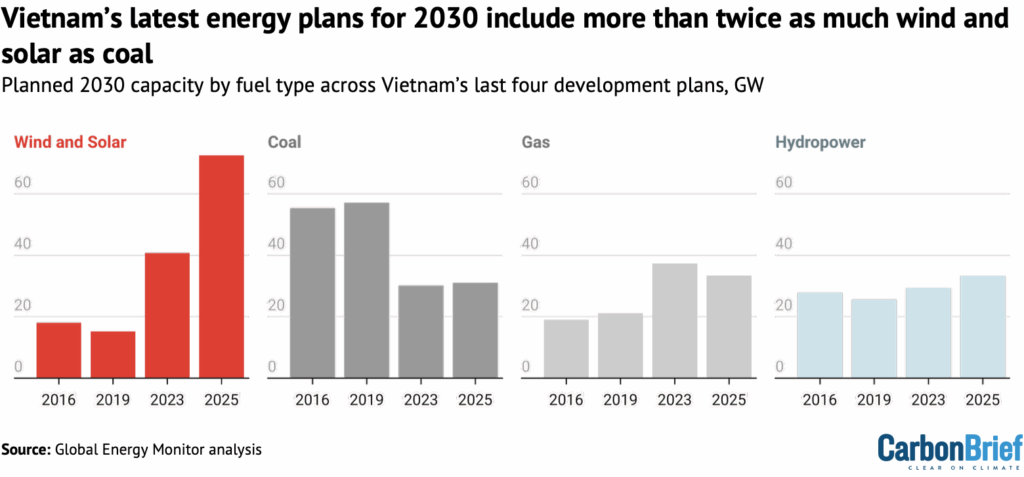
Just a few months prior, Vietnam released an adjustment to its latest power development plan, which featured substantial increases in projected wind and solar capacity and a modest increase in projected hydropower capacity.
However, the plan also includes a 1GW increase in projected coal power by 2030, as shown in the chart below.
The new figure for peak coal, 31.1GW, coincides with the interest from state-owned utility EVN to revive a coal plant previously considered to be cancelled.
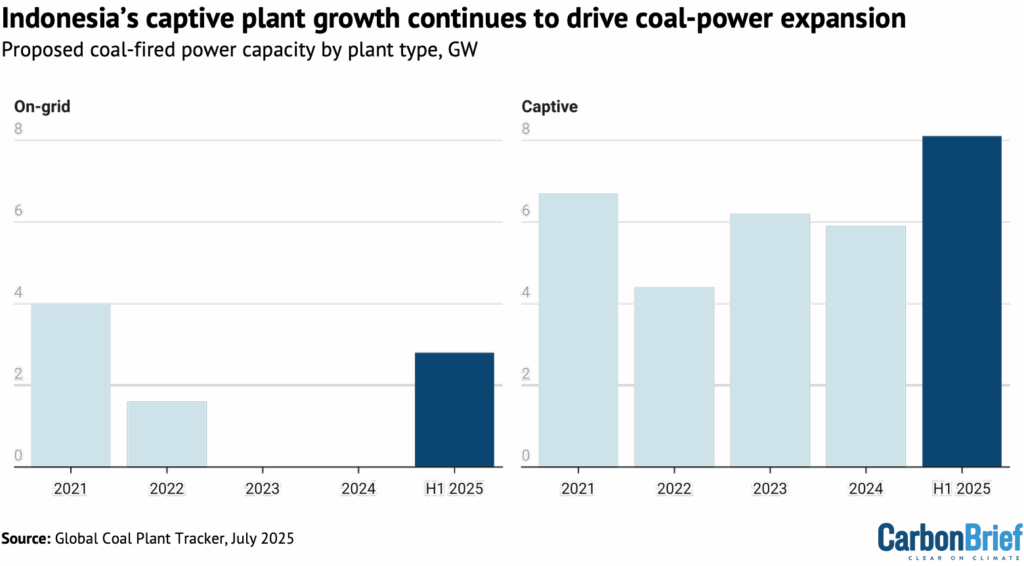
In Indonesia, the release of the latest electricity supply business plan (RUPTL 2025–2034) in May 2025 resulted in a spike in new and revived proposals for on-grid coal capacity. This was alongside the continued growth of off-grid, captive-coal plant proposals to power industrial areas, as GEM’s tracker shows.
Accounting for these captive-coal plants in Indonesia’s JETP documentation has presented a challenge, but Indonesia’s JETP secretariat has reiterated that updates to the country’s JETP comprehensive investment and policy plan are ongoing through the first six months of 2025 to address emissions from captive plants and incorporate efficiency targets.
Disparity remains between the government’s stated renewable energy ambitions and the reality of present advancements at the project level. Presidential regulation 112/2022 targets a 2050 national coal phaseout date in Indonesia and President Prabowo Subianto has more recently made overtures to an even faster 2040 coal phaseout.
Meanwhile, Indonesia’s proposed coal-power capacity grew by 5.1GW in H1 2025, to 17.1GW overall, as shown in the chart below.
In South Africa, the government has also reiterated its commitment to its JETP agreement. While Vietnam and Indonesia have substantial numbers of recently built coal plants and plants in continued development, South Africa operates a fleet of old, unreliable coal plants.
World Bank-linked funding for South Africa’s energy transition was approved in June 2025. While solidifying a climate investment fund, the plan also included the delayed closure of three coal plants that already average more than 50 years of age (Camden, Hendrina and Grootvlei).
All three countries are continuing down the dual paths of simultaneously extending coal’s lifetime and maintaining just energy transition commitments, banking on “all of the above” approaches and, ultimately, causing misalignment with JETP principles.
Yet, the continued progress of their just energy transition programs, despite global political and economic volatility, is a strong indicator that policy and planning priorities could soon align towards the phaseout of coal.


The post Guest post: China and India account for 87% of new coal-power capacity so far in 2025 appeared first on Carbon Brief.
Guest post: China and India account for 87% of new coal-power capacity so far in 2025

Cristina Rumbaitis del Rio is a senior advisor on adaptation and resilience with the United Nations Foundation and Mattias Söderberg is global climate lead at Danish NGO DanChurchAid.
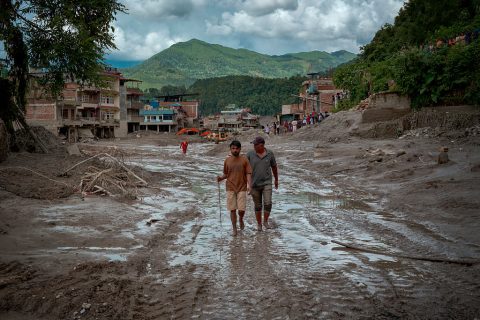
Recent extreme events – from wildfires and heatwaves in Europe to flash flooding following a glacier collapse in Nepal – have shocked and devastated communities, bringing years of warnings about such climate impacts to the doorstep of communities around the world.
One thing is certain: the new climate reality is here – and the adaptation strategies designed for yesterday’s world are no longer sufficient.
Attribution science has since shown that the hotter and more frequent heatwaves we’re experiencing around the world would have been virtually impossible without today’s high concentrations of greenhouse gases in the atmosphere. Climate shocks are now so severe that they reverberate through supply chains, food and water systems, financial markets and the movement of people.
-
Foreign minister: Nepal needs “meaningful” international support to face climate threats
Following its recent Himalayan flooding disaster, the South Asian nation is seeking urgent help from a new UN climate fund, appealing for “stronger global solidarity” -
Palestine: Israel’s bombing has left Gaza vulnerable to climate change
With homes, hospitals and water storage destroyed, Palestine’s government says that Gazans have little protection from climate impacts and sets conditional emissions targets

They must be a catalyst for a new way of thinking about adaptation and resilience, and how we finance solutions that work. A failure to invest in adaptation in one region can create costs far beyond it, which is why the concept of shared resilience is critical for leaders to grasp.
Investment not charity
At the UN General Assembly (UNGA 81) this month, leaders have an opportunity to translate today’s urgency into concrete commitments on adaptation and loss and damage finance ahead of COP31.
Those commitments are needed to underpin global stability, shared prosperity and human security. Governments should use this moment to show what a new response looks like: finance that reaches communities faster, supports locally grounded solutions, strengthens national systems, and helps countries prepare before the next shock arrives.
If we want sustained economic growth, food and water security, and resilient and prosperous societies across every region, adaptation must be at the heart of today’s development and security agenda. It cannot be just a future planning consideration or a narrow issue for climate ministries. Adaptation is now everyone’s business – and it must be financed fast and fair.
UN Secretary-General António Guterres has repeatedly framed climate finance as an investment rather than charity, warning that “a world in climate chaos cannot be a world at peace” and describing human security as freedom from the chronic and sudden disruptions that climate change multiplies.
What’s more, adaptation delivers a real return-on-investment, with researchers estimating that every dollar invested produces $10 in benefits, saving lives, protecting livelihoods, and reducing the costs of future disasters.
Hitting adaptation limits
The urgency to scale adaptation systematically is growing. The newly released “Limiting Overshoot” report from the UN Environment Programme (UNEP) confirms what scientists have long warned: exceeding global warming of 1.5C is now unavoidable under current policies. Yet, how high temperatures rise – and how long the world remains above the 1.5C threshold – will determine whether communities, economies and entire ecosystems can keep pace.
There are limits to adaptation. When we breach those limits, lives and livelihoods are lost, and people and ecosystems suffer greatly. We cannot simply build yesterday’s infrastructure a little stronger and assume it will be enough.
Nepal flood destruction shows “limits to adaptation”, scientists say
We need to fundamentally change the systems that determine how societies anticipate, absorb and recover from both immediate and evolving non-linear climate shocks. This includes transforming physical systems, such as infrastructure, and the governance systems that affect where and how we live to how we maintain our health and wellbeing.
Finance today is nowhere near the scale of the challenge.
The UNEP “Adaptation Gap Report 2025” estimates the shortfall in adaptation finance in developing countries at $284 billion–$339 billion a year – roughly 12 to 14 times current international public flows of around $26 billion. That gap is a development, economic and human security problem, especially for the most vulnerable populations who have contributed the least to causing the climate crisis.
Building resilience into financial systems
There are already signs of what a more systemic adaptation response could look like. Communities around the world are delivering practical solutions at local level, even as adaptation finance remains notoriously, and appallingly, difficult to access. Cyclone-resistant homes, local forecasting capacities, drought-resistant crops, heat insurance for pregnant informal workers and mangrove restoration are rooted in local knowledge and lived experience, while delivering benefits far beyond the communities where they originate from.
But local innovation alone is not enough; the systems around it need to be resilient too.
Jamaica offers one example. The country has built a multi-layered disaster-risk financing framework, including a catastrophe bond and contingency funds, through sustained fiscal discipline and proactive investment. Its debt-to-GDP ratio fell from around 147% in 2012 to around 62% in 202-25. That groundwork matters when disaster strikes.
Hurricane Melissa’s destruction shows need for climate resilience push
Following Hurricane Melissa, Jamaica was able to secure billions of dollars in reconstruction financing from multilateral banks – finance that might otherwise have been much harder to access. The lesson is clear: resilience can be built into the financial architecture of a country before a crisis arrives. That is the shift we now need to make at scale.
The foundations already exist – in Kingston’s fiscal reforms, in early-warning systems from the Sahel to the Pacific, and in every community that adapted before disaster struck. What is still missing is the political will, and the finance, to take what works and put it to work everywhere, at the speed our world’s new climate reality demands.
To hear more on this issue from high-level officials and experts, sign up for this event during Climate Week NYC, at 8am EDT on September 24 (in person or online), moderated by Climate Home News Editor Megan Rowling: Adapting to the New Climate Reality: Why Accelerating Impacts Demand New Responses.
The post Human security relies on adapting to the world’s new climate reality appeared first on Climate Home News.
Human security relies on adapting to the world’s new climate reality
Climate Change
Framing the climate science debate as a binary battle isn’t just wrong – it’s dangerous
Lidy Nacpil is the coordinator of Asian Peoples’ Movement on Debt and Development (APMDD).
Recent reporting on international climate negotiations has highlighted a sharpening divide within civil society and multilateral diplomacy. A troubling, simplistic narrative has taken root: that the UN climate process is witnessing a binary struggle between defenders of science and those attacking it.
This framing is not only inaccurate; it is dangerous. Characterising a substantive methodological and political debate in these terms misdiagnoses the stakes and stirs conflict instead of clarity.
No one disputes that climate action must rest on science. Science tells us what has led us to the climate crisis – the accumulation of historical emissions – and how much carbon budget remains if we are to keep temperature rise below 1.5C. It tells us how much global emissions must drop, and how fast. Science is also essential in assessing each country’s historical contribution to the accumulation of greenhouse gases in the atmosphere.
Responsibility, however, must also be based on capacity. For those who generated the largest share of historical emissions, that capacity includes the enormous wealth and economic power accumulated through the same fossil-fuel-intensive development that generated those emissions.
As science comes under attack at UN talks, climate movement splits over how to respond
While principles that should guide human action aren’t scientific questions – they are matters of values – applying them to real-world problems requires scientific grounding. Equity recognises the scientifically established reality of differentiated responsibilities among countries and within societies. Putting equity into practice demands scientific rigour.
Scrutiny of IPCC models
Today, critics are scrutinising the assumptions and frameworks behind the Intergovernmental Panel on Climate Change’s Integrated Assessment Models (IAMs), used to project future scenarios and map global mitigation pathways. These concerns centre squarely on equity and justice.
The economic, technological and policy assumptions used in IAM scenarios are normative choices rather than scientifically prescribed or neutral facts. These include choices about discount rates, economic growth, energy demand, technology costs, carbon prices, land availability and the regional location of mitigation. Many IAM scenarios reproduce existing global inequalities rather than transform them. Questions about transparency, representativeness and diversity in the scientific process are deeply urgent.
Most IAM scenarios are built primarily around global cost-effectiveness – directing emissions reductions to places where mitigation is modelled as cheapest rather than allocating effort according to historical responsibility, capacity and development needs.
The resulting pathways allow developed countries to retain disproportionately high levels of energy and fossil-fuel consumption while requiring developing countries to undertake substantial mitigation and carbon removal, including land-based measures that threaten food security and local development.
Northern models often assume uniform access to cheap financing. In reality, Global South economies face far higher capital costs, driving up the price tag of rapid infrastructure shifts.
Constraints on development space
Scenario constraints also limit the development space poorer nations need without guaranteeing adequate climate finance. When models treat profoundly unequal starting points as uniform baselines, policy pathways lock in global inequality under the banner of scientific objectivity.
Pointing out these structural flaws isn’t rejecting science. It is essential scientific scrutiny aimed at producing stronger, fairer, and more actionable results.
Science ‘under attack’ from fossil fuel interests at UN climate talks
The fight is not about whether we want to keep temperature rise below 1.5C, but about how we get there. A pathway can be technically compatible with 1.5C or 2C while still being deeply unequal in who gets to consume energy, who must reduce emissions, and whose development is constrained. Temperature compatibility alone does not make a pathway fair.
Critiquing IAM scenarios from an equity perspective is neither an attack on the Intergovernmental Panel on Climate Change (IPCC) nor an attack on science. Rigorously examining IPCC reports – their substance, assumptions, and processes – is an acknowledgement of the IPCC’s importance and entirely consistent with scientific method.
Tensions over AR7 timing
There is a separate but related tension over the cycle and timeline of the IPCC’s Seventh Assessment Report (AR7). Some governments and civil society voices advocate completing its Working Group reports in time to feed directly into the UN’s Second Global Stocktake in 2028.
The motivation makes sense: policymakers need timely science. But several developing-country negotiators and researchers have warned that meeting that deadline could severely disadvantage the Global South.
Funding gap threatens next round of IPCC climate science reports, chair warns
Global North authors and institutions remain disproportionately represented in the research underlying IAM assessments. Developing-country researchers often work with fewer institutional resources, smaller research budgets, and less administrative support. Accelerated publishing and assessment schedules can further limit their ability to generate, submit, and peer-review research in time for inclusion.
The AR7 timeline concerns boil down to inclusivity, representation, and equity. Requiring the IPCC to meet tight political calendars without ensuring meaningful support and participation for developing-country researchers risks reproducing the very inequalities being challenged.
Cooperation requires equity
Political interests are indeed at work in UNFCCC negotiations and must be surfaced. Bad-faith actors seek to evade fossil-fuel phase-outs or shirk climate-finance obligations. Many developed country parties are guilty of both, including those who style themselves as “Friends of Science.”
We must not lump legitimate scientific critiques raised by several Global South researchers and many civil society organisations concerning representation, economic assumptions and fair-share accounting together with obstructionism. Doing so risks misrepresenting and delegitimising critical scientific work and Global South equity and justice perspectives.
The climate movement is strongest when it aligns rigorous science with global equity and justice. Achieving the Paris Agreement’s goals requires robust science that fully integrates the experiences, economic realities and academic contributions of the Global South. Effective climate action also requires international cooperation, and without equity, such cooperation cannot be sustained. We do not have to choose between science and equity. We need both.
The post Framing the climate science debate as a binary battle isn’t just wrong – it’s dangerous appeared first on Climate Home News.
Framing the climate science debate as a binary battle isn’t just wrong – it’s dangerous
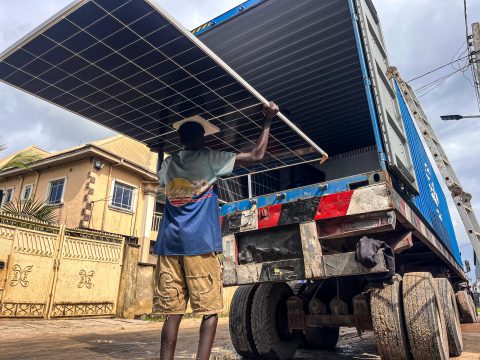
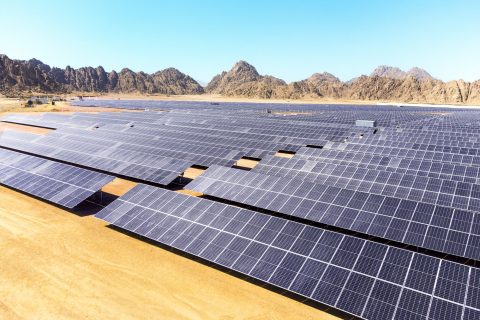
More than 300,000 solar panels and 120 battery containers are helping to power Africa’s largest copper mine with continuous clean energy in the Democratic Republic of the Congo, as miners turn to solar as an alternative to expensive diesel and energy imports.
The project at the Kamoa Copper mine in the south of the DRC, which became operational last month, is one of the largest solar and battery facilities generating baseload power on the continent.
The clean electricity is displacing millions of litres of polluting diesel and costs less than a fifth of the price of generator power per kilowatt hour, the mining company said.
The project is part of a massive solar deployment across the continent. Recent data from global energy think-tank Ember found record solar capacity of 17 GW will be installed in Africa this year – a 45% rise from 2025.
Installed by CrossBoundary Energy, a developer of distributed renewable energy systems, the solar-battery facility at the DRC mine is “proof of concept” that solar and battery systems can provide the reliable power at scale needed by remote industrial operations, Annebel Oosthuizen, managing director at Kamoa Copper, told Climate Home News in an interview.
“There’s always been this perception in the DRC that solar isn’t ideal because it is raining half of the year. But it’s perfectly ideal. We are seeing a lot of interest from other mines that are still depending on generators and power imports,” she said.
Mining drives solar and battery surge
Like Kamoa Copper, a growing number of miners in the DRC are looking to solar power to compensate for the country’s chronic energy deficit at a lower cost as global diesel prices hit record highs amid ongoing attacks on oil infrastructure in the Middle East.
As a result, the mining sector has become a key driver of the country’s growing clean energy demand and one of the biggest importers of large-scale solar equipment.
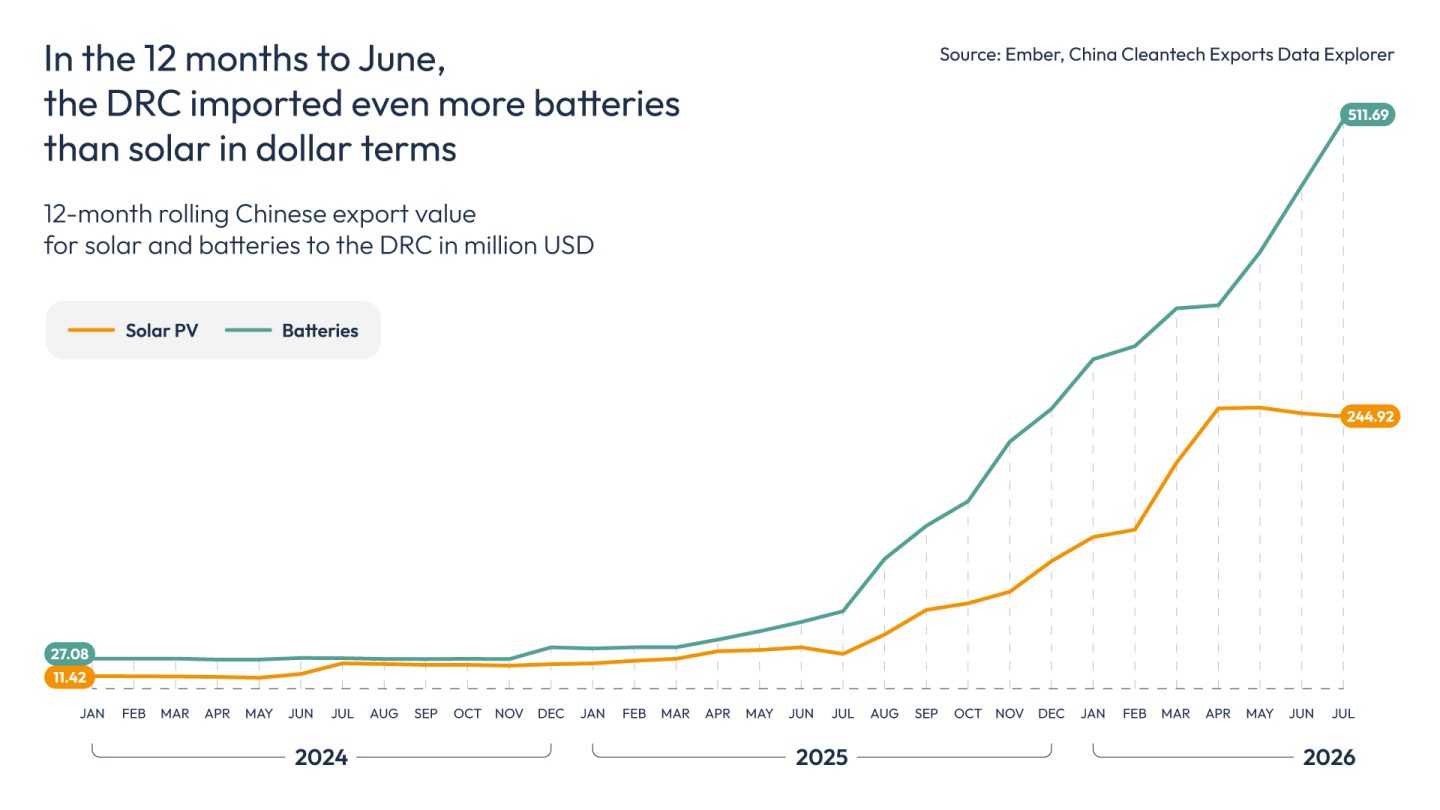
Ember found the DRC is set to install a record 1.7 gigawatts (GW) of solar panels this year – a 544% increase compared to 2025 and the equivalent of adding more than 60% of the country’s entire 2023 grid capacity.
The deployment of combined solar and battery storage solutions to deliver stable energy supplies to mines has also caused battery imports to surge. In dollar terms, the DRC’s imports of batteries from China far exceeded that of solar in the year to June 2026, according to Ember.
A crippling power deficit
The DRC holds significant energy resources and some of the world’s largest reserves of the minerals required to manufacture clean energy technologies. It is the world’s largest producer of cobalt, which is needed to make batteries, and Africa’s top producer of copper – a metal sought after for its electrical conductivity which is pivotal to the world’s electrification efforts.
Yet just 22.5% of the DRC’s population had access to electricity in 2024 – one of the lowest rates in the world, according to the World Bank. And as mining expands and more of the minerals extracted are being processed in the country, unreliable power supply has become a major constraint for the sector, which contributed to more than a quarter of the country’s GDP in 2024, excluding oil and gas.
The country has enormous hydropower potential, with the hydroelectric potential of the Congo River estimated at around 100 GW. But only a fraction is being harnessed.
-
Made in Nigeria: The race to build an African solar industry from scratch
A solar power revolution is gathering pace in Africa and Nigeria wants a slice of the fast-growing industry, but competing with Chinese imports won’t be easy -
Can giant batteries unlock Africa’s green industrial future?
Battery energy storage systems (BESS) could drive clean tech manufacturing in Africa but shortfalls in finance and data are still limiting deployment at scale -
Egypt seeks to unlock renewable potential to power regional clean energy hub
Europe is investing in Egypt’s bid to position itself as a clean electricity exporter to reduce its emissions and generate a new source of income

Still, virtually all of the DRC’s grid-connected electricity is generated by hydropower by the state-owned utility, Société Nationale d’Électricité (SNEL).
The electricity then has to be transported more than 1,500 kilometres to reach the mining belt in the south – a challenge made more difficult by ageing grid infrastructure and limited transmission capability. SNEL did not respond to a request for comment.
“It is estimated that there’s around a 1 GW energy deficit for the DRC mining sector,” said Matt Tilleard, CEO of CrossBoundary Energy, which owns the solar and battery equipment at the Kamoa Copper mine and provides the power as a service.
“The interest in solar from the mining industry is not theoretical – it is already translating into large-scale solar and battery procurement for mining operations in the region,” he added.
Solar displaces gas, saves energy costs
The facility installed by CrossBoundary is part of a plan by Kamoa Copper to supply more of the electricity it needs with solar energy and batteries as its operations expand, a faster solution than relying on harder-to-build hydropower projects.
“Our processing capacity has increased drastically over the last couple of years. We’ve constructed the largest copper smelter in Africa and that is so power-intensive,” said managing director Oosthuizen.
A joint venture between Canadian firm Ivanhoe Mines, Chinese company Zijin Mining Group and the DRC government, the mine needs 235 megawatts (MW) of power, which is expected to nearly double to 450 MW in the next five years.
Kamoa Copper currently receives 100 MW from state utility SNEL – “and the rest we have to find a solution for”, said Oosthuizen.
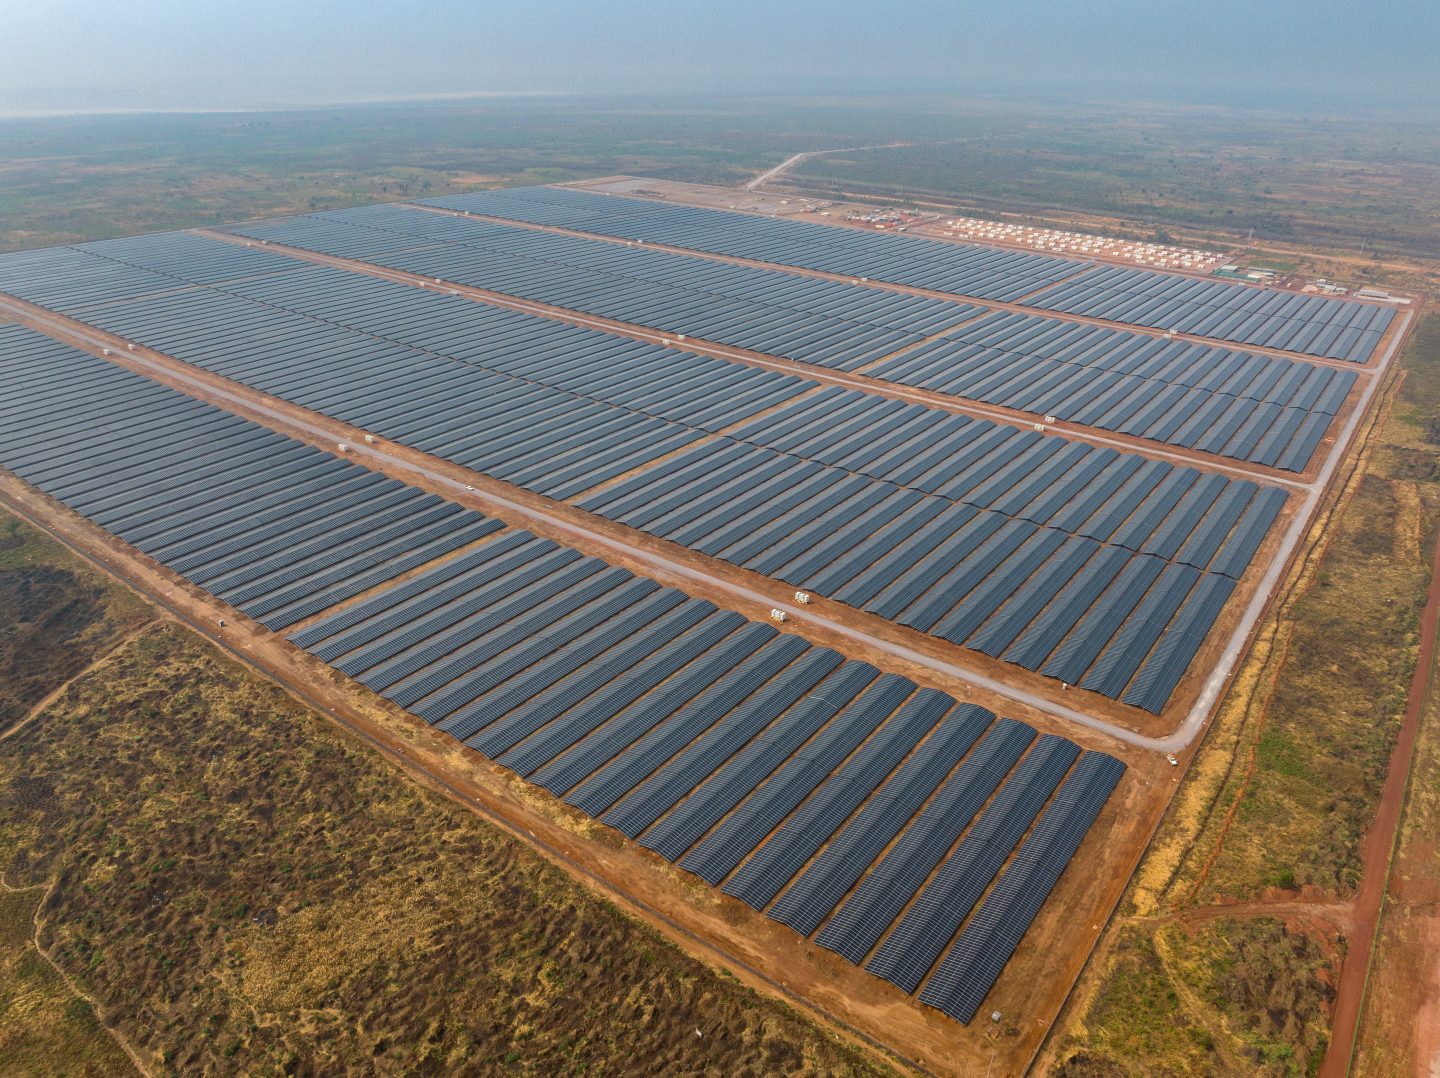
Another 30 MW solar and battery baseload facility is expected to come into operation this month, enabling around 25% of the mine’s power needs to be generated by solar energy. An additional 60 MW of continuous solar power will be added by the end of 2027, and the company is exploring options for more solar capacity and two hydropower projects.
The operational 30 MW of clean electricity provided by CrossBoundary Energy will power pumps that prevent 400 million litres of water from flooding the underground mine every day.
In August alone, the facility has reduced the mine’s diesel consumption by around four million litres, generating an estimated $11 million dollars in savings at current diesel prices, Oosthuizen said.
The mine still relies on generators to meet a 20-40 MW deficit and to power the trucks used in the mine, which Oosthuizen said would be difficult to electrify in the next five years because the technology isn’t yet ready to operate in the mine’s tough and wet conditions.
Avoiding a two-speed transition
To prevent a major imbalance between industrial players’ access to clean, reliable energy and the millions of Congolese who remain without power, the government requires private electricity producers to reserve at least 10% of their generated power for local communities living near rural production sites.
Delivering this, combined with rural electrification, mini-grid development and national grid expansion, is critical to prevent a two-speed energy transition that leaves people behind, said Catherine Mukobo, head of ACERD, the Congolese Association for Renewable and Decentralised Energies.
“Without implementing these policies, the DRC could get in a situation where mines have access to abundant modern energy while a large part of the population remains without electricity,” she said.
The post DR Congo’s power-hungry mining sector drives record solar surge appeared first on Climate Home News.
DR Congo’s power-hungry mining sector drives record solar surge



-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits