

China’s carbon dioxide (CO2) emissions fell by 3% in March 2024, ending a 14-month surge that began when the economy reopened after the nation’s “zero-Covid” controls were lifted in December 2022.
The new analysis for Carbon Brief, based on official figures and commercial data, reinforces the view that China’s emissions could have peaked in 2023.
The drivers of the CO2 drop in March 2024 were expanding solar and wind generation, which covered 90% of the growth in electricity demand, as well as declining construction activity.
Oil demand growth also ground to a halt, indicating that the post-Covid rebound may have run its course.
A 2023 peak in China’s CO2 emissions is possible if the buildout of clean energy sources is kept at the record levels seen last year.
However, there are divergent views across the industry and government on the outlook for clean energy growth. How this gap gets resolved is the key determinant of when China’s emissions will peak – if they have not done so already.
Other key findings from the analysis include:
- Wind and solar growth pushed fossil fuels’ share of electricity generation in China down to 63.6% in March 2024, from 67.4% a year earlier, despite strong growth in demand.
- The ongoing contraction of real-estate construction activity in China saw steel production fall by 8% and cement output by 22% in March 2024.
- Electric vehicles (EVs) now make up around one-in-10 vehicles on China’s roads, knocking around 3.5 percentage points off the growth in petrol demand.
- Some 45% of last year’s record solar additions were smaller-scale “distributed” systems, creating an illusory “missing data problem”.
Why did emissions fall in March?
Looking at the first quarter of 2024 as a whole, China’s CO2 emissions increased significantly, based on preliminary data on energy consumption from the National Bureau of Statistics.
January and February of this year still saw large increases from the low base of 2023, when the economy was still subdued by the recent ending of zero-Covid restrictions.
As a result, CO2 emissions during the quarter increased by 3.8% year-on-year, with coal consumption growing 3%, oil 4% and gas 11% compared with the same period in 2023.
The turnaround happened in March, when CO2 emissions fell by 2%, due to a 1% fall in coal use, flat oil demand and a 22% drop in cement production. The reduction in CO2 emissions came despite a 14% rise in gas consumption, as the fuel is a minor part of China’s mix.
As seen in the figure below, China’s CO2 emissions had started increasing in February 2023, after Covid-19 controls were lifted in December 2022.
The year-on-year comparison to January-February 2023 is, therefore, still affected by the low base caused by the last year of zero-Covid, making March the first month to give a clear indication of the emissions trends after the rebound.

The main driver of China’s emissions growth in recent years has been the power sector (see below).
Conversely, the main reason the emissions trend turned into a reduction in March was that power-sector emissions growth slowed down sharply. Emissions from the sector only increased by 1% year-on-year, due to strong growth in solar and wind power generation.
While power-sector emissions stabilised, the largest source of reductions in emissions in March was the continued decline in demand for steel and cement from the construction sector, as illustrated in the figure below.
Steel production fell by 8% and, as a result, there was also a fall in production of the main fuel used by steel mills – coking coal. Cement production fell dramatically, by 22% year-on-year.
These trends seem set to continue, as real-estate investment continued to contract – for the third year – as a result of a government clampdown on excess leverage and financial risk in the sector, and sizable supply resulting from booming construction in the past.

The contraction in construction volumes has not resulted in as large a drop in China’s demand for steel and other energy-intensive metals as might be expected.
The reason is rapid growth and investment in manufacturing, which uses metals for the construction of facilities and the production of industrial machinery.
It is unlikely that this manufacturing growth can continue, as global markets for different goods and commodities become saturated. The government’s economic policy now emphasises “new productive forces”, in the latest attempt to shift economic growth away from traditional heavy industry. The term refers to high-end manufacturing and R&D, which are, for the most part, less energy intensive than China’s traditional industrial sectors.
Looking at other sectors in March 2024, oil demand for transport was unchanged on a year earlier – following months of strong increases – suggesting that the post-Covid rebound could be petering out.
The production of jet fuel (+35%) and petrol (+7%) still increased, indicating growth in demand from passenger transport, but diesel production stagnated (+1%) and total crude oil refining volumes also only increased 1%.
The rise in the share of electric vehicles (EVs) is making a meaningful dent in oil demand, with the share of electric vehicles out of all vehicles on the road increasing to 10.5%, from 7.0% a year ago, as estimated on the basis of cumulative sales over the past 10 years. This indicates that EV adoption lowered petrol demand growth by 3.5 percentage points.
Gas demand rebounded sharply, increasing 14% year-on-year, after a drop caused by high gas prices. Growth in gas consumption came predominantly from industry and households.
Power-sector gas consumption increased 8%, as the utilisation of gas-fired power plants recovered, but this only contributed a small fraction of the overall growth.
The share of gas in China’s energy mix fell from 2021 to 2023, after more than two decades of continuous increases, and has only now started to resume growth.
One recent driver of emissions increases continued: coal consumption in the chemical industry increased 14%, extending the double-digit growth seen in 2022 and 2023.
While there is not yet enough data to estimate CO2 emissions in April, industrial data for the month indicates that the trends seen in March continued.
Thermal power output – mostly from coal – grew at a slow rate of 1.3%, with most demand growth being covered by solar. Steel, cement and coke output fell by 8%, 9% and 7%, respectively, reflecting continued decline in construction volumes. Oil refining volumes fell 3%.
Domestic coal mining output fell 3% while imports increased 11%, meaning total supply fell 5%.
Gas demand saw further strong growth, with imports increasing 15% and domestic production 3%. Among energy-intensive industries, the chemical and non-ferrous metal industries continued rapid output growth.
Solar and wind covering demand growth
The stabilising emissions in the power sector are notable because electricity demand growth continued at a high rate of 7.4% – and hydropower utilisation stayed below the long-term average, affected by a prolonged drought.
Electricity demand growth has been exceptionally fast during the past few years, driven predominantly by industrial power use. In March, industrial demand growth slowed down, but a rebound in the service sector sustained overall growth.
Half of demand growth came from industry, with non-ferrous metals, chemicals, machinery and electronics the largest growth areas. One third came from services, with wholesale and retail trading the largest growth driver, and one sixth from households.
Household power demand has also seen a surge in the past couple of years, driven by a wave of air conditioning unit purchases triggered by the historic heatwave in 2022, especially in lower-income households that lacked air conditioning before.
Despite rapid growth in electricity demand, the rate of growth for large-scale power generation slowed to 3%, due to rising distributed solar power generation.
(Distributed solar refers to smaller-scale installations, often on the rooftops of homes and businesses, in contrast to the large, centralised solar farms.)
Overall, the record addition of solar and wind capacity in 2023 enabled these sources to deliver 22% of power generation and almost 90% of year-on-year growth in March, as shown in the figure below. The share of non-fossil power generation rose to 36.2%, from 32.6% last year.

The growing contribution of distributed solar power to generation has been somewhat hidden by the way that China’s monthly electricity data is reported. The National Bureau of Statistics only reports monthly power generation from very large-scale solar and windfarms. It has also made systematic upward revisions of previous year’s data, suggesting it had not captured output from new firms entering the market in real time.
As 45% of last year’s record solar additions were distributed generation, the exclusion of small solar installations is affecting these numbers a lot more than it used to.
This has caused a lot of confusion in China and overseas, especially as the reported electricity consumption became much larger than generation – an apparent impossibility. Bloomberg even called this a “missing data problem”.
The widening gap between electricity consumption and large-scale power generation makes it clear, however, that distributed solar is increasingly contributing to meeting electricity demand.
Unlike the monthly figures, there is no “missing” data in China’s annual reporting, as the yearly statistics include all power plants regardless of size. In 2023, for example, the annual statistics reported twice as much solar and 10% more wind power generation than the monthly statistics.
Indeed, calculating generation from reported installed capacity and utilisation hours of the capacity on a monthly basis reproduces the annual numbers closely. This makes it clear that the expansion of small-scale solar is contributing substantially to meeting electricity demand, even if the statistics bureau’s monthly data does not cover the power generation.
Clean energy boom continues
The fall in emissions in March was enabled by last year’s massive solar and wind power additions, with almost 300 gigawatts (GW) of new capacity connected to the grid. This boom accelerated in the first three months of 2024, with a 40% increase compared with the year before.
Solar power installations stood at 46GW, up 36% on year, and wind power installations at 16GW, increasing 50% year-on-year.
The first months of the year tend to be slower in terms of installations – and there are also gaps in reporting that mean that quite a bit of new capacity is only reported at the end of the year.
The strong year-on-year growth indicates that concerns about grid access for new projects have not affected the pace of capacity additions yet. Even if growth rates are tempered for the rest of the year, the numbers to date indicate that last year’s record pace could be maintained in 2024.
Solar panel production grew another 20% in January-March from last year’s already significant numbers, signalling strong demand from China and overseas.
EV production grew 29% while total vehicle production resumed its fall, so the share of EVs continued its rapid climb, reaching 31% in the first quarter compared with 26% the year before.
As the economics of solar and wind projects are strong, the main constraint on capacity additions will be grid access. Numerous provincial grid operators already began to limit additions of new wind and solar last year, as they were concerned that they would not be able to fully integrate the additional generation.
This highlights the shortcomings in China’s grid operation, because such challenges are arising when the share of wind and solar power in China’s power generation is still modest, at 15%, compared with 27% in the EU and 40% in Germany, Spain and Greece.
Action is being taken. The NDRC has begun to relax requirements for the grid access of solar and wind generators. This will increase the uncertainty for investors in wind and solar projects, but makes it easier for grid operators to integrate more capacity and will, therefore, support growth in capacity and generation.
The NDRC also issued a policy on developing electricity storage, pledging that, by 2027, the power system would be able to integrate new solar and wind capacity while keeping the share of their output that is wasted due to grid issues to a low level.
While solar and wind are beginning to cover most or all of power demand growth, investment in coal power is continuing. Additions of thermal power capacity slowed down slightly year-on-year in the first quarter, but provinces’ “key project lists” for 2024 include over 200GW of thermal power projects, which are mainly coal-fired.
Future ambition a major question mark
The fall in China’s emissions in March could mark the turnaround after blistering growth since 2020. As explained in analysis for Carbon Brief published last autumn, the current growth rate of clean energy has the potential to peak the country’s emissions.
Whether the clean energy growth will continue is, therefore, the key question for the future path of China’s emissions. However, views about the pace of future wind and solar developments diverge widely.
The China Photovoltaic Industry Association (CPIA) forecasts average annual capacity additions of 225GW from 2024 to 2030 in its “conservative” scenario, a slight increase from the 217GW installed in 2023. Its “optimistic” scenario would see this accelerate to 280GW per year. Under the CPIA’s projections, China’s total installed solar capacity reaches 2200-2600GW in 2030, up from 660GW today.
According to the wind power industry, China needs to install more than 50GW of new wind power capacity annually from 2021-2025 and more than 60GW annually from 2026 onwards, in order to reach the 2060 carbon neutrality target. This is a fairly modest trajectory, since capacity additions in 2023 were already 76GW.
On the other hand, the head of the National Energy Administration (NEA) Zhang Jianhua wrote in a recent article that clean-energy capacity additions should be kept above 100GW per year, less than half of the level achieved in 2023, implying that he views the recent acceleration as an anomaly and not something to be maintained.
Similarly, the NEA’s 2024 workplan targets 170GW of non-fossil power capacity added, as implied by the targets for total generating capacity and the share of non-fossil energy capacity. (Despite the 160GW target in the 2023 workplan, additions reached nearly 300GW.)
These alternative visions of wind and solar expansion are shown in the figure below. The dark blue line shows Zhang’s expectation that annual capacity additions would return to levels seen during 2020-2022, while the light blue and red lines show the renewable industry forecasts of growth broadly being maintained at 2023 levels – or steadily increasing.

The difference between the CPIA and NEA levels of ambition amounts to 1,400-1,800GW of solar and wind power capacity by 2030. If the resulting clean power generation were to replace coal in 2030, the difference in CO2 emissions would amount to 10-15% of China’s current emissions. By 2035, with a continuing trend in wind and solar growth, the CO2 saving would reach 20-25% of current emissions.
In his article, Zhang points to a number of challenges that could justify the lower level of clean-energy capacity additions that he is proposing, including the lack of a robust pricing mechanism for electricity storage, the need for better coordination of policies on the energy transition, as well as managing the land and marine area requirements for large new energy projects.
Still, dialling back the additions of solar and wind, as well as the associated battery storage, would be a cold shower to China’s economy, as these clean energy sectors have become a key source of economic growth.
Moreover, massive recent investments in manufacturing capacity in these sectors will only be utilised and pay off with continued growth in the demand for clean energy equipment.
The lower level of ambition of the government is also reflected in official targets for this year. The environmental ministry recently set a target to reduce carbon intensity – the level of emissions per unit of GDP – by 3.9% in 2024.
This target, if met, is an increase over the past three years when carbon intensity improved by only 1.5% per year on average. Yet, given that the target for GDP growth is “around 5%”, the carbon intensity target allows emissions to increase by more than 1%.
After rapid emission increases in 2021 to 2023, China is already severely off track for its 2025 and 2030 carbon intensity targets – and the annual targets for 2024 fail to close this gap.
Instead, it is exactly the required annual average that would have been needed every year to meet the 14th five-year plan target of 18%. As such, it avoids the existing shortfall from getting wider, but does nothing to make up for slow progress to date. The NDRC set a less ambitious target of reducing “fossil energy intensity” by 2.5% in 2024, which allows emissions to increase by more than 2%.
Zhang Jianhua also argued that clean energy should cover 70% of energy consumption growth in 2026-30, a target that is consistent with a slowdown in clean energy additions.
This would mean that 30% of energy consumption growth would still be covered by increasing the use of fossil fuels – and, therefore, CO2 emissions would also continue to increase.
Continued emissions growth would imply a major risk of missing China’s 2030 carbon intensity commitment – which is part of its international climate pledge under the Paris Agreement – as there is no space for energy-sector CO2 emissions to increase from 2023 to 2030 under the commitment, assuming average GDP growth of 5% or less.
China’s pledge, therefore, depends on clean energy growth continuing to significantly exceed the central government’s targets – or those targets being ratcheted up.
About the data
Data for the analysis was compiled from the National Bureau of Statistics of China, National Energy Administration of China, China Electricity Council and China Customs official data releases, and from WIND Information, an industry data provider.
Power sector coal consumption was estimated based on power generation from coal and the average heat rate of coal-fired power plants during each month, to avoid the issue with official coal consumption numbers affecting recent data. Power generation from coal was calculated from total thermal power generation and the reported capacity and utilisation hours of power plants firing coal, gas and biomass, to obtain the fuel mix of thermal power generation.
When data was available from multiple sources, different sources were cross-referenced and official sources used when possible, adjusting total consumption to match the consumption growth and changes in the energy mix reported by the National Bureau of Statistics.
The data for the first quarter of 2024 was scaled to match the reported year-on-year growth rates for the whole quarter in preliminary official data from the National Bureau of Statistics. The conclusion that emissions fell in March holds both with and without this adjustment.
CO2 emissions estimates are based on National Bureau of Statistics default calorific values of fuels and emissions factors from China’s latest national greenhouse gas emissions inventory, for the year 2018. Cement CO2 emissions factor is based on annual estimates up to 2023.
For oil consumption, apparent consumption is calculated from refinery throughput, with net exports of oil products subtracted.


The post Analysis: Monthly drop hints that China’s CO2 emissions may have peaked in 2023 appeared first on Carbon Brief.
Analysis: Monthly drop hints that China’s CO2 emissions may have peaked in 2023

An exceptional El Niño is building. The World Meteorological Organization (WMO) says it has intensified to very strong levels and is likely to last at least through February 2027. If its current trajectory holds, it could become stronger than anything seen since WMO monitoring began four decades ago.
That is bad news for agriculture. El Niño – a naturally occurring weather phenomenon – can scramble rainfall patterns across the world, bringing drought to some regions and floods to others. And this time it is unfolding against the backdrop of a significantly hotter climate, with farmers already contending with unreliable growing seasons, extreme heat and less predictable rainfall because of global warming.
El Niño expected to bring next record-hot year as soon as 2027
We are seeing the consequences already. In Sri Lanka, drought linked to El Niño has dried wells and reservoirs and cut into crops and farmer incomes. Indonesia is experiencing its worst wildfire season in 11 years, with prolonged drought and extreme heat exacerbated by El Niño. And in Peru, authorities are preparing for the opposite extreme: intense rains, flooding and landslides which the national civil-defence agency says could affect around 1.2 million people.
These impacts will multiply as El Niño intensifies.
And yet, just as the risks to food production are rising, the money available to help farmers withstand them is shrinking.
10% funding decline in 2024
A forthcoming analysis from the Food and Agriculture Organization (FAO) shows that climate-related development finance for agrifood systems is moving in the wrong direction. In 2024, the latest year for which data is available, it fell by 10 percent compared with a 2 percent overall decline. The sectors that put food on our tables — crops, livestock, forestry and fisheries — received just 5 percent.
Yet this is precisely the moment when climate investment in agriculture needs to grow, not shrink. It can help communities adapt, build resilience and protect food security, while unlocking larger flows of public and private finance. Agriculture feeds us, supports the livelihoods of well over a billion people, and is often the first sector hit by drought, floods and extreme heat. Cutting that investment now is a false economy.
One failed harvest can plant the seed for the next crisis, forcing farmers to eat the seed they have saved for planting, sell livestock or tools, or take on debt. It can also deepen food insecurity, disrupt supply chains and drive up prices, showing up months later in supermarket aisles far away.
The Central American Dry Corridor, stretching through much of the region, shows both how exposed farmers are, and what investment can do. Based on an analysis of 41 years of satellite observations, FAO finds that some crop and pasture areas there face more than a 50 percent chance of agricultural drought over the coming months.
About half of Central America’s 1.9 million producers of maize, beans and other basic grains live in the Dry Corridor. Many grow food both for sale and for their own families. When a harvest fails, they lose both income and dinner.
El Salvador project conserves water and soil
In El Salvador, which lies within the Dry Corridor, more than 50,000 farmers have adopted practices to better withstand drought and increasingly unreliable rainfall through RECLIMA, a project financed by the Green Climate Fund and implemented by FAO in partnership with the government of El Salvador. It has substantial national co-financing, including from the country’s Environmental Investment Fund.
El Niño can intensify El Salvador’s annual mid-season dry spell, known as the canícula, turning it into a longer, harsher drought just as maize needs water most.
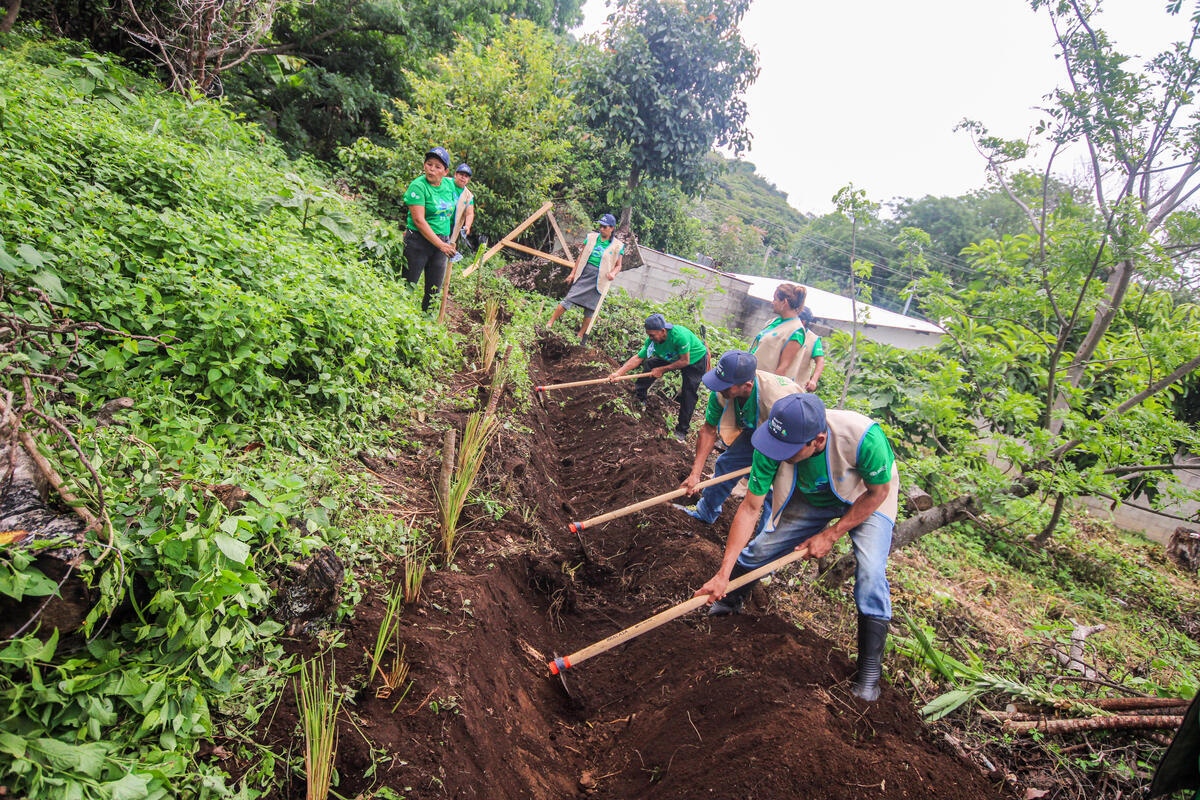
For María Cristina Corvera de López, a second-generation farmer in rural Nahualapa, adapting means changing how every drop of rain is captured and used. She plants trees alongside her crops to provide shade and minimise evaporation and uses simple irrigation channels and a homemade drip system to conserve water. Instead of burning stalks, leaves and husks after harvest, as generations before her did, she turns them into mulch to hold moisture in the soil.
“The effects of climate change are a constant challenge,” she says. But the new techniques have made her farm more resilient to El Niño as well. Where she once harvested about 50 bags of maize per acre, she now gets around 80, even during droughts. It’s enough to feed her family and sell the surplus.
Managing risk now cuts future costs
Together, these adaptations can mean the difference between losing a crop and getting through a dry season with enough food, seed and income to plant again. They are also the result of climate finance invested before disaster strikes.
RECLIMA shows what that kind of adaptation investment can buy. Adaptation accounted for 45 percent of climate-related development finance to agrifood systems in 2024, and multilateral development banks are directing more agricultural finance towards resilience. That shift reflects a growing recognition that adaptation is a form of risk management, not just a development cost.
We need much more of it. The same investments that help farmers withstand El Niño also enable them to adapt to a hotter, more unpredictable future. Cutting investment in the people who produce our food just as climate risks intensify does not save money. It simply pushes a much larger bill into the next harvest, the next food crisis, and the next El Niño.
The post As El Niño intensifies, we should be investing more in the world’s farmers appeared first on Climate Home News.
As El Niño intensifies, we should be investing more in the world’s farmers
An area of Amazon forest roughly the size of the US state of New Jersey has remained standing due to Luiz Inácio Lula da Silva’s leadership of Brazil, according to Carbon Brief analysis.
Lula beat Jair Bolsonaro in the 2022 election to become president of the nation that is home to nearly 60% of the Amazon rainforest.
Forest loss surged during Bolsonaro’s far-right presidency and dropped sharply under the left-wing Lula, with Amazon deforestation likely to hit its lowest level on record this year.
Now, as another presidential election approaches, Lula is facing off against Bolsonaro’s son, Flávio Bolsonaro, whose “anti-environmental” policies are similar to his father’s.
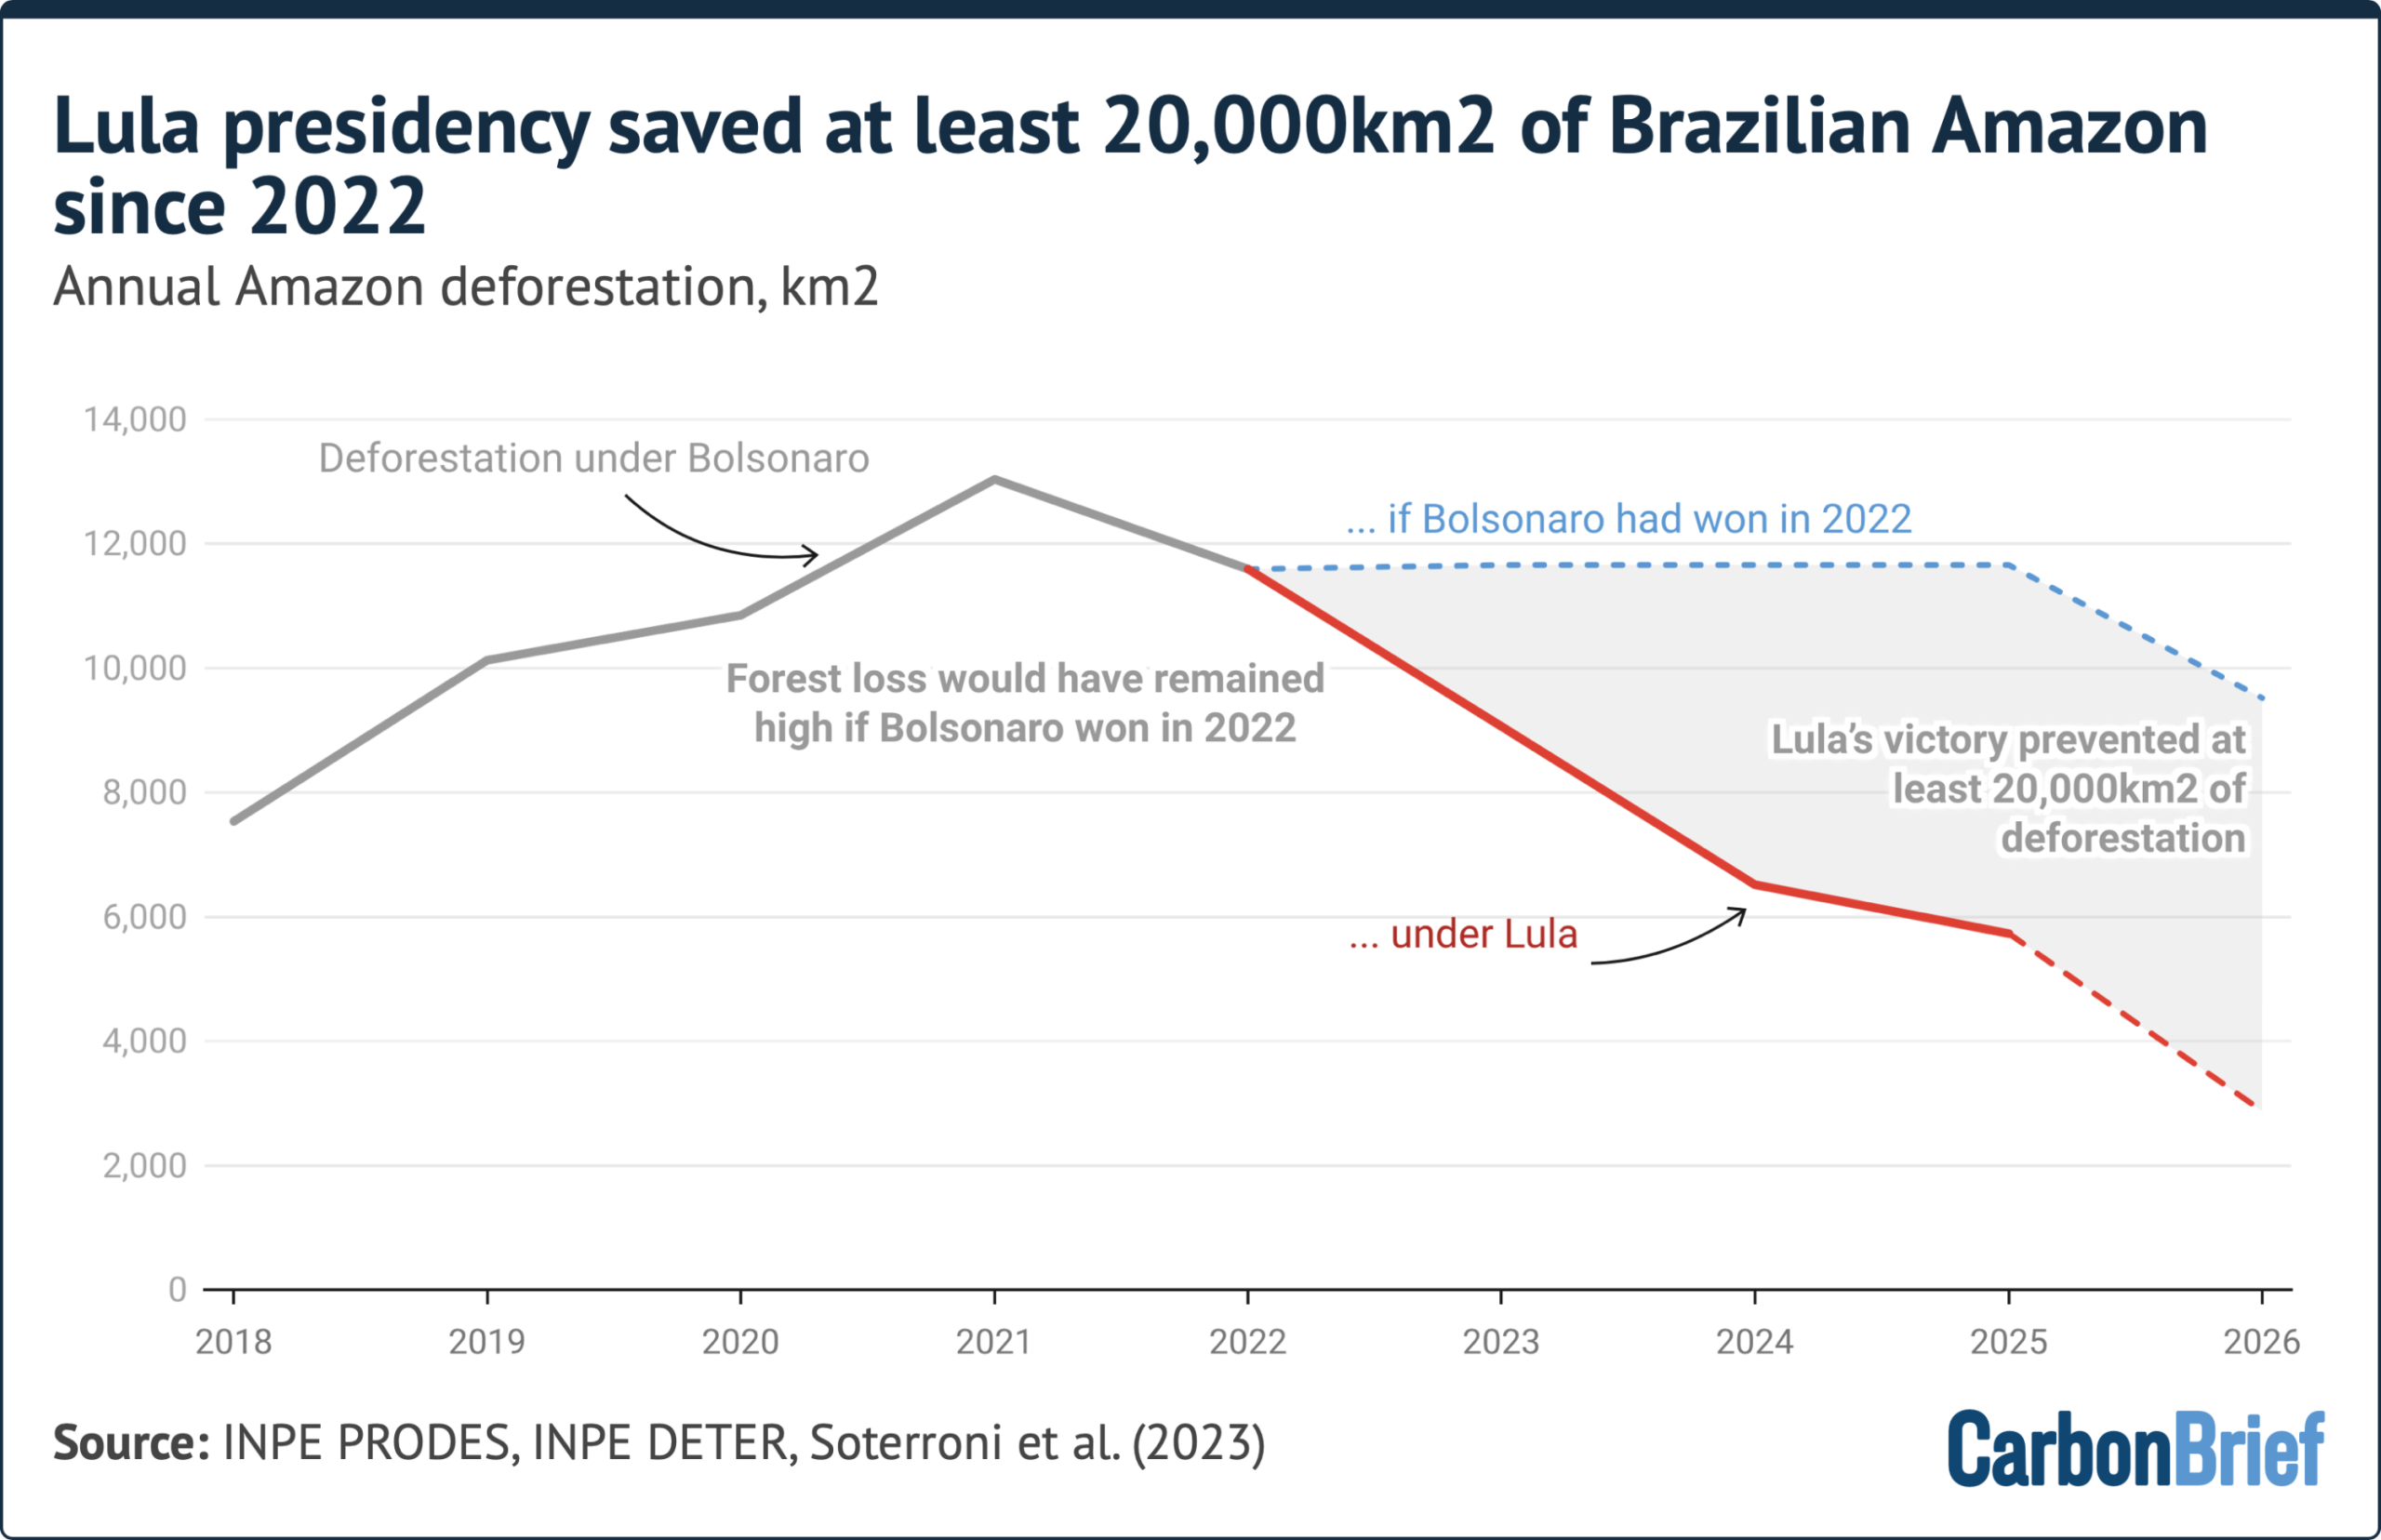
Carbon Brief’s analysis suggests that at least 20,000 square kilometres (km2) of deforestation has been avoided since Lula took office and prioritised Amazon protection.
The analysis is based on modelling by an international research team of an alternative scenario in which Brazil’s flagship forest code legislation was not enforced – a proxy for Jair Bolsonaro’s leadership.
Experts tell Carbon Brief that this estimate is likely “conservative” and that actual deforestation under Bolsonaro could have been “much higher”.
With Lula and Flávio Bolsonaro tied in the polls, the upcoming election is expected to significantly shape the level of environmental action in the world’s fourth-largest emitter, whose emissions are largely driven by deforestation.
‘Brazil is back’
When Jair Bolsonaro was president of Brazil between 2019 and 2022, he championed the nation’s powerful agribusiness sector and oversaw an unprecedented increase in Amazon deforestation.
Bolsonaro weakened regulations, slashed federal agency budgets and empowered illegal activities in the Amazon, while attacking Indigenous and environmental groups.
This meant that the forest code – Brazil’s flagship legislation that requires landowners to preserve and restore forest on their property – was not properly enforced.
After Lula’s presidential victory in 2022, he promised to target “zero deforestation” by 2030, telling the COP27 UN climate summit that “Brazil is back”.
Lula rolled back Bolsonaro’s wave of deregulation and reinstated a deforestation “action plan”. Led by celebrated environmentalist Marina Silva, the environment ministry scaled up enforcement and policing activities in the Amazon.
As a result, annual deforestation in the Amazon has more than halved from 11,594km2 per year in 2022 to 5,731km2 in 2025.
Data from August 2025 to July 2026 – the timespan used in government records – is yet to be released, but preliminary satellite alerts put the deforestation figure at 2,874km2.
While the final figure is likely to be higher, experts still think Amazon deforestation in 2026 could hit its lowest level since records began in 1988.
New Jersey-sized forest
Compared to a scenario in which Bolsonaro won in 2022, Carbon Brief analysis suggests that at least 20,000km2 of Amazon forest remains standing today due to Lula’s leadership.
This area – roughly the size of Wales, Belize, Slovenia or the US state of New Jersey – is indicated by the grey area in the chart below.
This analysis is based on a 2023 study on the role of nature-based solutions in Brazil’s pathway to net-zero emissions. This was a refined update of a 2018 study that used the same GLOBIOM-Brazil model, from researchers at the University of Oxford, the International Institute for Applied Systems Analysis and Brazil’s National Institute for Space Research (INPE).
It is based on a comparison of forest code implementation with a “baseline” scenario in which the code is not enforced, reflecting the kind of weak governance seen under the Bolsonaro administration. (See Carbon Brief’s 2022 article for more details of this modelling.)
Dr Aline Soterroni, a University of Oxford researcher who led the 2023 analysis, tells Carbon Brief that the reversal seen under Lula “shows how quickly deforestation can respond to political will”.
However, she stresses that the modelling of the “no forest code” scenario is “relatively conservative”, with deforestation remaining high but not rising.
Deforestation in this scenario – used here as a proxy for a Bolsonaro election win – is tempered by slower demand growth for Brazilian beef and soy, says Soterroni. She notes that the scenario also does not capture the potential for illegal forest clearing in response to weak governance.
Indeed, some experts anticipated in 2022 that a Bolsonaro victory would send deforestation rates rising to near-record levels.
Claudio Angelo, international policy coordinator at Brazil’s Climate Observatory, tells Carbon Brief that if Bolsonaro had won in 2022, “we have reason to believe [this would have resulted] in much higher rates than during his first term”.
Angelo says the “political signal” would likely have driven an “explosion of wildcat mining” and illegal deforestation in the Amazon. He also points to efforts – including by Flávio Bolsonaro – to formally dismantle the forest code in the Brazilian congress, during Jair Bolsonaro’s first term.
Soterroni notes that deforestation rates did not immediately drop following Lula’s election, as suggested by modelling of a full “forest code compliance” scenario. She says this reflects the “gradual and imperfect process” of restoring and enforcing the law.
Nevertheless, she tells Carbon Brief:
“The key message from our modelling is the contrast between these trajectories: weak environmental governance keeps deforestation substantially higher than full implementation of the forest code. That message remains relevant today.”
Election significance
With Jair Bolsonaro in prison for plotting a coup after losing the 2022 election, his son Flávio Bolsonaro, a senator for Rio de Janeiro, is standing against Lula in the upcoming contest for president.
There are 13 candidates, but Flávio Bolsonaro and Lula are by far the frontrunners and are currently neck-and-neck in opinion polls.
If Lula wins, experts say he is likely to continue with the “zero deforestation by 2030” agenda that has already had a pronounced impact on forest loss.
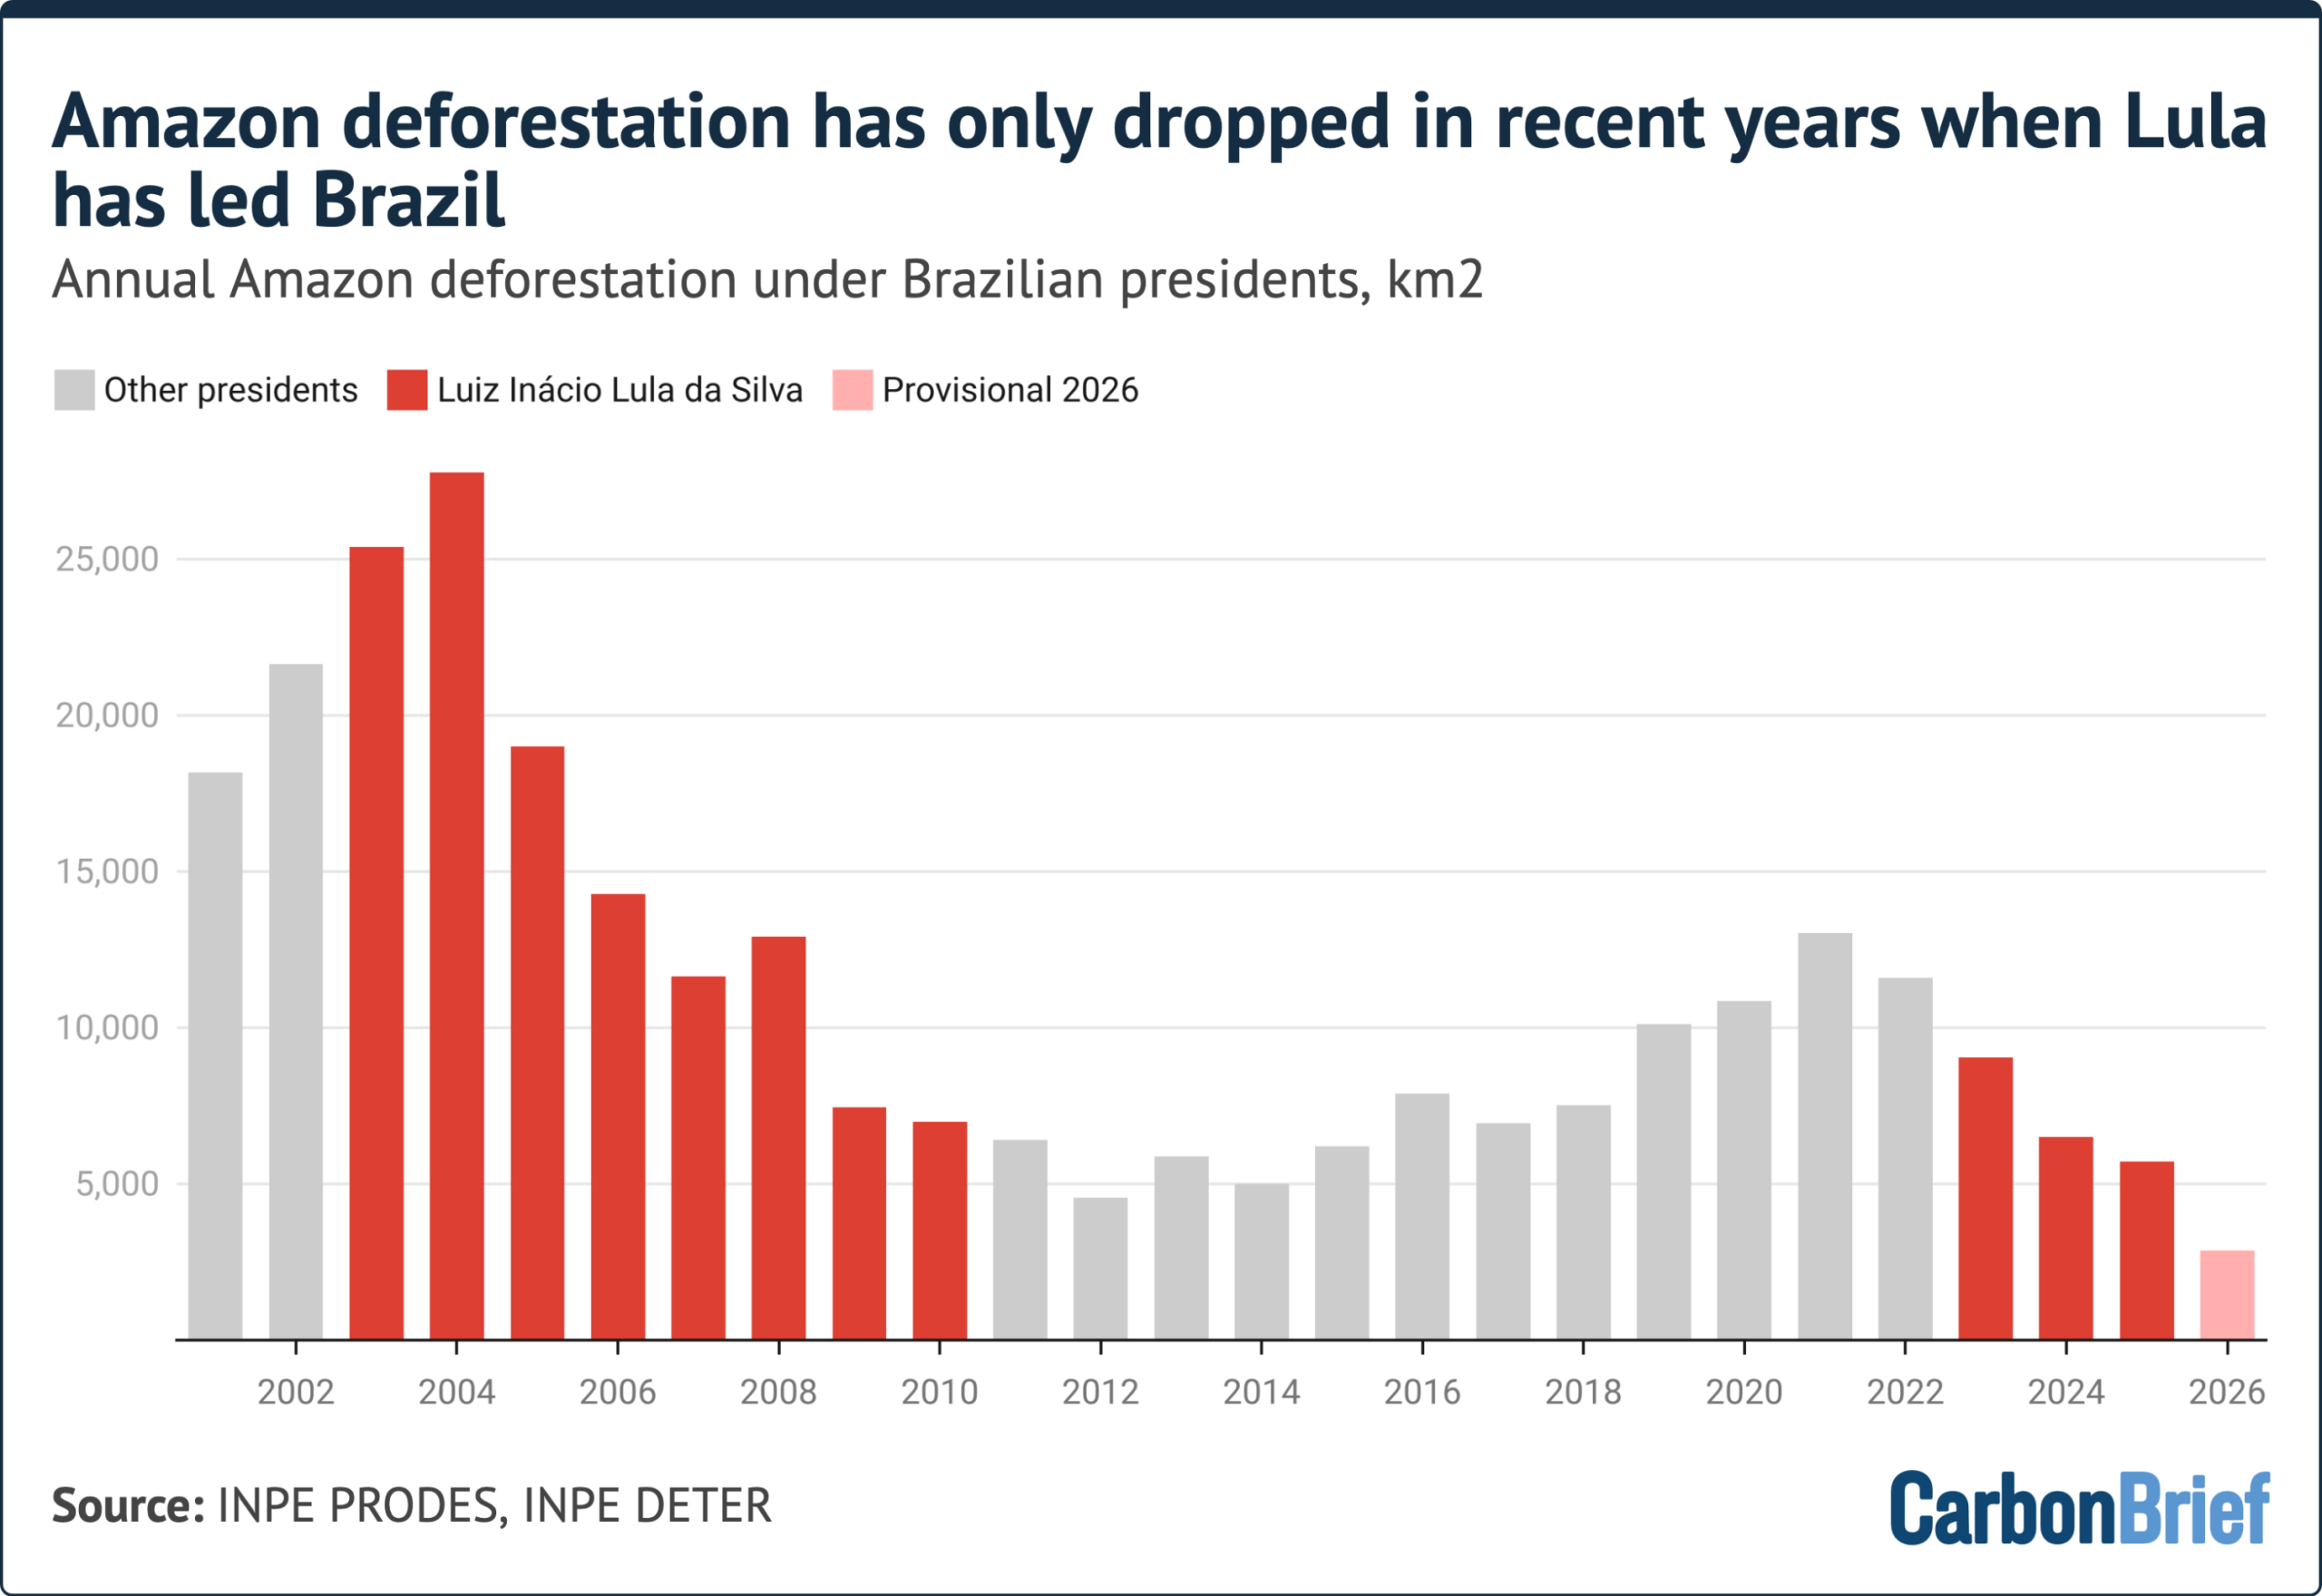
As the chart below shows, periods when Amazon deforestation fell in recent history all occurred during Lula’s three terms as president.
In contrast, experts say Flávio Bolsonaro, a climate sceptic who has indicated he will continue his father’s political agenda and favour agribusiness and mining, will likely drive a surge in deforestation. Angelo tells Carbon Brief:
“At the risk of sounding alarmist, I’ve been saying that Lula’s re-election is the only thing standing between us and a wide destruction of the Amazon.”
A Bolsonaro win would be a “tremendous disaster”, says Dr Patricia Pinho, deputy science director at the Amazon Environmental Research Institute, adding:
“I don’t think we can afford four years of increasing deforestation [and] violence against Indigenous peoples.”
Dr David Lapola, an ecologist focused on Amazon research at the University of Campinas in Brazil, says he believes deforestation “would certainly rise” and Brazil’s climate and deforestation goals “would be thrown in the trash bin”. He tells Carbon Brief:
“The Bolsonaro administration in the 2019-2022 period showed that the deconstruction of environmental policies and institutes can be done very, very quickly.
“In a matter of a few months, they can destroy what has been constructed over decades of environmental policy and activism in Brazil.”
‘Greenest’ policies
Lula has the “greenest” policy proposals of Brazil’s six top-polling presidential candidates, according to analysis by the Climate Observatory.
The analysis identifies 16 “positive and detailed” environmental commitments in Lula’s proposals, including reaffirming his “zero deforestation by 2030” goal.
Flávio Bolsonaro, on the other hand, has one positive environmental commitment and seven “clearly anti-environmental” proposals.
The right-wing politician has committed to zero “illegal” deforestation by 2029. However, he has also previously led an attempt to change the forest code, opening up large tracts of previously out-of-bounds forest for legal clearance by extractive industries.
Given this, Angelo tells Carbon Brief that he is sceptical about the 2029 pledge.
“The only way you can trust him on this is to think that he is going to revoke the forest code and make all illegal deforestation legal.”
Lula is also the only major candidate to list a clear target for cutting national emissions, sticking with Brazil’s existing goal to cut emissions by 59-67% by 2035, compared to 2005 levels.
Overall, the Climate Observatory notes that climate change and environmental issues “are off the radar for most candidates”, who are instead focusing on the economy and security issues.
Pinho adds that deforestation and the Amazon have not been at the “forefront” of this election, compared to 2022.
If Bolsonaro wins, up to 95% of the Amazon would fall under the leadership of right-wing national governments – including those in Bolivia, Colombia, Ecuador and Peru – reported Mongabay. It noted that presidents in all these nations “explicitly favour agribusiness and mining over environmental conservation”.
If no candidate receives a majority of votes in the first round of Brazil’s election on 4 October, a runoff will take place on 25 October, as has happened at every presidential election since 1998.
Soy moratorium and Brazilian congress
Other factors will also play a role in future deforestation in Brazil, regardless of the next president.
One is the effective end of the Amazon soy moratorium. This is a voluntary agreement signed by companies committing to not buy soya beans grown on land in the Brazilian Amazon that was deforested after 2008.
Conservation organisation WWF’s international director general, Kirsten Schuijt, previously described it as the “most impactful voluntary supply chain policy ever implemented”.
However, major grain traders withdrew from the agreement earlier this year, effectively bringing it to an end. Pinho describes this move as a “huge destruction” of Brazil’s environmental protections.
Research shows the moratorium prevented around 18,000km2 of deforestation in its first decade of operation from 2005-16.
In contrast, a 2026 study estimated that the end of the moratorium could result in 14,000km2 of additional deforestation in the Amazon by 2036.
Alongside choosing a new president on 4 October, Brazilian voters will elect state governors and members of congress, which will also factor into future environmental impacts.
Right-leaning parties, including the far-right Liberal Party linked to the Bolsonaros, currently hold half the seats of the two chambers of congress.
This has led to conflict between lawmakers and Lula. For example, in 2025, congress bypassed Lula’s veto of several aspects of a controversial piece of legislation dubbed the “devastation bill”.
Pinho says that the potential for a right-wing congress and president would be “devastating for the environmental and climate agenda”.
Lapola notes that a Flávio Bolsonaro presidency “would consolidate the view in Brazil that environmental protection is solely a matter of political preference, and not a crucial need of all people”. He adds:
“Land pillage, destruction of precious biodiversity and scorning of Indigenous peoples simply cannot be a nation’s project in the 21st century. We have got to be smarter than that, for sure.”
related
Q&A: What change of power in Colombia could mean for world’s fossil-fuel transition
Brazil’s biodiversity pledge: Six key takeaways for nature and climate change
COP30: Could Brazil’s ‘Tropical Forest Forever’ fund help tackle climate change?
Guest post: How Caribbean states are shaping climate legislation
The post Analysis: Lula presidency saved at least 20,000km2 of Brazilian Amazon since 2022 appeared first on Carbon Brief.
Analysis: Lula presidency saved at least 20,000km2 of Brazilian Amazon since 2022
This letter is a bit more direct and longer than most of those which I write, but I hope you will be okay with that, because the times seem to call for being plain.
A few weeks ago I got a text message from an old and dear friend —let’s call her Hannah.
I have enough shared life with Hannah that, whenever we talk, the conversation always feels current and effortless, despite gaps of months or even years.
Hannah has been talking with her son — we’ll call him Neil — who is a teenager and doing well in school, but wildly worried about the state of the world, including the imminent trajectory of global warming. Hannah and I don’t text each other other very often, but on this occasion she’s reached out with something visceral:
Neil has challenged me to point him to something hopeful, if I can find it. He says so far no one is showing any will to uphold the Paris Agreement. I am checking in to see how you still manage to have real hope.*
Then, just a few days later, the United Nations Environment Programme Limiting Overshoot report landed, containing the principal finding that it is likely the global temperature will soon exceed 1.5°C.
After that news, and the real time devastation in Nepal, and in the context of the broader state of the world, I found myself having multiple conversations with friends and colleagues about the structure of hope. I want to openly share that after a few of these exchanges, I metaphorically closed the blinds, and wondered how to feel, and what to do, because there is no avoiding the dreadfulness of the news, and what it means for the suffering of people and life on Earth.
But if you are fortunate enough to have time, space and security to do so, then after the darkness, you open the shutters and once again there is light. This is the structure of my innermost resolve.
* * *
Our lives — those of us living on our magnificent earth now — have the greatest possible purpose.
There is virtually no problem that we endlessly clever and creative, human beings cannot solve, when we work together.
And we are not just intelligent and ingenious; we are inherently social, nurturing and brave; capable of the deepest enduring love.
Each of the roughly 12,000 generations of humanity so far has made life possible for those who have followed, through acts of devotion.
Babies have been held and fed. Water and food have been found and shared. Shelter has been built. For 12,000 generations we have held the hands of our children.
Every single one of us was once carried in the arms of another, unable to walk ourselves. It is our thoughtfulness, kindness and care that have seen us through as a species. Sometimes this has been in the most exigent of circumstances, when enough of our ancestors did not give in, faced incredibly difficult things, to somehow make it through.
And so it comes to this. To what we now must do. We must do as 12,000 generations of people did for us.
The struggle to keep global warming to under 1.5 degrees may be over. The battle of return—to get our planet back to safe temperatures at emergency speed and scale — is just beginning. Upon this struggle depends the future of all we care about, and that of all life on Earth. The prospects of the next 12,000 generations are conditioned by our efforts now.
Our work now is to keep the overshoot as low as we can, make it as brief as possible, and do everything within our power to alleviate other pressures on nature. It is to take care of humanity — of one another — in the face of mounting climate and ecological damage. And by these efforts, create the conditions for future flourishing. Every fraction of every degree matters.
What must now be done is hard, much tougher than should have been necessary, because of the vested interests in coal, oil and gas and deforestation, and the failures of decision makers. And while renewable energy has surged, making the case for change much simpler, on the other side of the ledger there’s the reactionary and gangsterist turn of politics and the multiplier effects of wars and mass violence, with the existential destabilisation of big tech looming over all.
There is no sugarcoating the scale of difficulty. But what is necessary remains within our collective power. We must never, for one second, say that returning our planet to flourishing is impossible — many of the obvious solutions already exist; but even where transformation relies on reforms, technologies or capabilities that might sound fanciful, or historical changes that are unprecedented, this can be no barrier to our conviction. After all, much of what we take for granted today as ordinary features of social life, would have been considered impossible by every single generation before us.
The world has not been destroyed by nuclear war; we solved the growing hole in the ozone layer; Antarctica was kept sacrosanct from exploitation. Humanity has collectively triumphed before, and can do so again.
We can find the necessary social and political will to do what is needed because these are endlessly renewable resources. The necessary financial capital exists. Apart from the fossil fuel industry, the greatest barrier we face is to mistakenly concede that what lies before us is insurmountable. It is not.
We must avoid the siren song of fatalism. Because. It. Is. Never. Too. Late.
None of which is to be insensitive to the horrors already unleashed — the deadly and grotesque harm to people, places and species that cannot be undone; or to be blind to the impacts that are coming. But where we have the power to act, we also have the responsibility — and the extraordinary privilege — to do what must be done.
Although she is wounded, our planet is still alive and beautiful beyond all of our comprehension. Hundreds of billions of creatures live and thrive still upon this earth. Nothing has happened until it has happened, and life fights for life. Every beetle, every tree, all the fish in the ocean, the smallest of the geothermal shrimps, the greatest of the whales and the mightiest of the birds — all demand life every second of their existence, so that their species too may have future generations.
No individual has to know how to solve this alone. Indeed, finding some detachment and humility is essential to concentrate on the role that each of us can play.
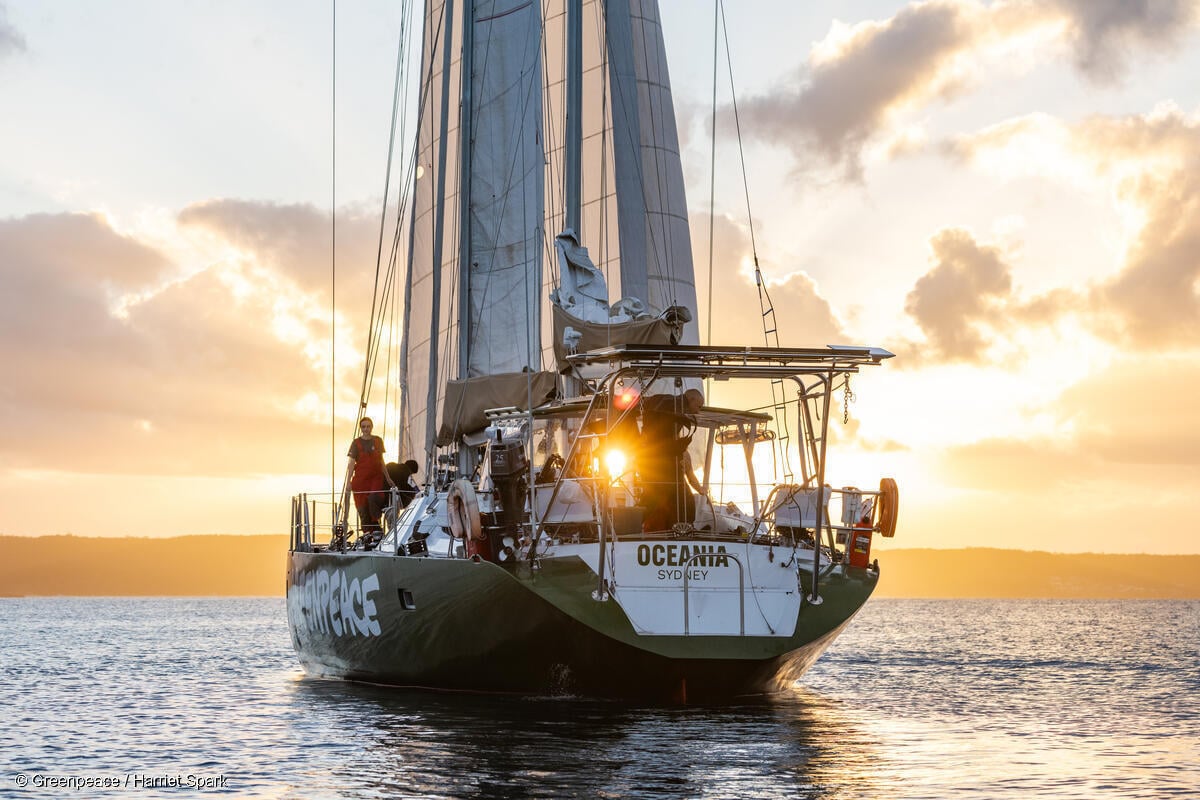
Hope is not merely a mindset or a story we tell ourselves. Collective power is not abstract; it is what we do, together, applying ourselves to the practical mechanics of change and contestation within society, by being part of the organisations and networks of people that are dedicated to effective strategies. It is why I am so committed to Greenpeace.
Working from without and within, there are opportunities to make rapid change within institutions, governments, businesses and communities to create the social, economic and political momentum for emissions reduction at speed and scale, reminding ourselves always of what remains possible, even if it hasn’t happened yet.
We can return the planet to safer temperatures. We can put technologies back in the service of people and life. We can return to the assumptions that seemed so obvious just one generation ago — that it is both possible, and our obligation, to build a better future for all people, and for life on Earth.
I did write back to Hannah and Neil, to say honestly to a treasured friend and her son, that yes, as a matter of faith, conviction, evidence and strategy, absolutely there is real hope. And this is a pledge not just to Neil and his generation, but to the next 12,000.
Together, we have the power. Together, we cross this bridge through the dark. To secure an Earth capable of nurturing life in all of its magnificent diversity.
We did not choose to carry this historic responsibility, but here we are. And it is so lucky that we are here.
I wouldn’t choose any other time to be here, alive on Earth, with you.



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19