Connect with us

Published

on

Current Global Climate Legislation, by Region

Our world is beginning to be dominated by the threats of the climate crisis. Governments globally are acting to mitigate greenhouse gas emissions and transition towards a future free from fossil fuel reliance. To maintain an understanding of the plethora of global climate legislation that is constantly being enacted and revised, keep reading!


United Kingdom Climate Legislation

The United Kingdom has implemented extensive legislation to maintain their commitment to being net-zero by 2050. Legislation has been enacted to promote clean energy, invest in climate change mitigation, and regulate corporate emissions.

UK Climate Legislation, at a glance

  • UK Emissions Trading Scheme (ETS)

    • a limited number of emission allowances are allocated to companies, which they can trade with each other

    • Forces corporations to mitigate their emissions or be subject to financial penalties

      • Emit more GHG → buy more allowances

    • Enacted in 1/2021 to replace participation in the EU ETS

    • Applicable to energy intensive industries, the power generation sector, and aviation

  • UK Green Finance Strategy

    • As of 2022, required the largest companies and financial firms (listed companies and large asset owners/managers) to make public how they are responding to financial risks and opportunities from climate change

    • Comply or explain basis, so no financial penalties yet


Read our in-depth guide here to learn more about UK Climate Legislation, how it could affect your corporation, and how DitchCarbon can help you!


European Union Climate Legislation

The European Union has committed to becoming the first climate-neutral continent through their establishment of a European Green Deal. By 2030, the EU plans to reach at least 55% less net greenhouse gas emissions than in 1990. To achieve this feat, they enacted the Fit for 55 legislative package. The EU has also been enacting legislation that requires public and large companies, both in the EU and beyond, to report their carbon emissions. 


EU Climate Legislation, at a glance

  • Corporate Sustainability Reporting Directive

    • In July 2023, required that specific companies provide detailed reporting on sustainability issues, publishing basically an Environmental Social Governance Report

    • Applicable to all public and large companies in the EU or those generating a net turnover of €150 million in the EU and which have at least one subsidiary or branch in the EU

    • Three stages of implementation

      • 1 January 2024 for companies already subject to the non-financial reporting directive

      • 1 January 2025 for large companies that are not presently subject to the non-financial reporting directive

      • 1 January 2026 for listed SMEs, small and non-complex credit institutions and captive insurance undertakings

  • Fit for 55 

    • Legislative package intended to reduce greenhouse gas emissions by at least 55% by 2030, using 1990 as a baseline

    • includes the EU Emissions Trading System (ETS), Effort Sharing Reduction (ESR), and Carbon Border Adjustment Mechanism (CBAM)

  • EU ETS

    • Cap-and-trade system where a limit is placed on GHG emissions from specific sectors each year

    • Created tradable emissions allowances and distributed to market participants

    • Forces corporations to mitigate their emissions (w/in allowances) or be subject to financial penalties by purchasing more

    • Applicable to the power, heat generation, energy intensive industrial sectors, aviation, and the maritime sector

    • Revised in 2021 to reflect an overall target of a 62% reduction in emissions from the sectors involved by 2030

  • EU ESR

    • Establishes bank and borrow system, similar to ETS but for the transport, buildings, and agriculture sectors

    • Emission allowances can be banked and used in the future or borrowed from subsequent year allowances

    • In May of 2023, revised regulation was enacted with a proposal to reduce emissions under ESR by at least 40% using 2004 as a baseline. 

  • CBAM

    • Enacted to prevent carbon leakage and the offshoring of emissions through imposing a price of carbon emitted during the production of goods entering the EU

    • Mirrors the EU ETS for foreign producers, but with harsher carbon emissions prices

    • Between now and the end of 2025, importers will have to report emissions embedded in their goods subject to CBAM without paying a financial adjustment in a transitional phase

    • CBAM encompasses cement, iron and steel, aluminum, fertilizers, electricity, and hydrogen 


Read our in-depth guide here to learn more about EU Climate Legislation, how it could affect your corporation, and how DitchCarbon can help you!


United States Climate Legislation

Climate legislation in the U.S. is highly susceptible to political agendas and varies among states with differences in the scope and the degree of the legislation. The Biden/Harris Administration maintains climate policy as a key aspect of their political agenda and has proposed legislation to promote the transition to a future free from reliance on fossil fuels. Certain states have committed to mitigating the impacts of the climate crisis and are promoting climate conscious agendas. 


Climate Legislation, at a glance

Federal Legislation

  • The Inflation Reduction Act

  • The Inflation Reduction Act is the most ambitious investment in combating the climate crisis, aiming to cut U.S. greenhouse gas emissions by up to 41 percent below 2005 levels by 2030 and designating $369 billion in funding for climate and energy-related purposes

  • Provides financial incentives for consumers and corporations through tax subsidies

  • The vast majority of this funding ($216 billion) is designated towards tax credits to corporations to catalyze private investment in clean energy, transport, and manufacturing

  • Enacted in 2022

  • Federal Supplier Climate Risks and Resilience Rule

    • An executive order to force federal contractors to publicly disclose their carbon emissions

    • Federal contractors receiving more than $50 million in annual contracts will be subject to these requirements:

      • disclose Scope 1, Scope 2, and relevant categories of Scope 3 emissions

      • disclose climate-related financial risks

      • set science-based emissions reduction targets

    • Federal contractors with more than $7.5 million in annual contracts but less than $50 million would be required to only report Scope 1 and Scope 2 emissions

    • Proposed by the Biden administration in November 2022

California Legislation

  • California’s Cap and Trade Program 

  • Minimizes GHG emissions by setting a limit on major emitters through extending businesses carbon allowances

  • Has been applied to emissions that account for around 80% of California’s GHG emissions

  • Each year, fewer allowances are created and the annual cap declines

  • Launched in 2013 

  • California’s Corporate Data Accountability Act

    • Requires that large corporations that do business in California publicly disclose their greenhouse gas emissions

    • Applicable to businesses that generate over $1 billion in annual revenue and either are engaging in any transaction for the purpose of financial gain within California, are organized or commercially domiciled in California, or have California sales exceeding either the threshold amount for that year or 25 percent of total sales 

    • Corporations must provide annual disclosures for scope 1 and scope 2 emissions starting in 2026 and must report scope 3 emissions starting in 2027

    • Enacted October 7th, 2023 

New York Legislation

  • New York’s Climate Leadership and Community Protection Act

    • Intends to reduce GHG emissions by 40% by 2030 and 85% by 2050 using 1990 as a baseline

    • Through the CLCPA, a cap-and-invest program has been implemented, similar to the cap and trade program in CA

    • Anticipated that corporations with large greenhouse gas emissions will be required to purchase emissions allowances

    • Enacted in 2019


Read our in-depth guide here to learn more about US Climate Legislation, how it could affect your corporation, and how DitchCarbon can help you!


Asia Climate Legislation

The leading economies in Asia are striving towards eventual carbon neutrality, and utilizing cap-and-trade systems to achieve this feat. China has committed to achieving carbon neutrality by 2060. Intending to generate 1,200 gigawatts of renewable energy by 2025, China is by far the global leader in solar and wind power production. As one of the fastest growing economies in the world, Indian climate policy is incredibly important to ensure that growth can be decoupled from increased emissions. India has committed to be net-zero by 2070 and to have 50% of its electricity generated from renewable energy sources by 2030. Currently, 40% of electricity is generated from clean energy as India is making significant investments in the construction of renewable energy sources, including green hydrogen.


Climate Legislation, at a glance

China

  • Emissions Trading Scheme (ETS)

    • Implemented to mitigate greenhouse gas emissions in the power sector through utilizing a cap-and-trade system

    • Corporations in the power sector are allocated a certain amount of emission permits and can trade these permits with a cap on total allocation.

    • Revised in 2021 included clause that all corporations subject to the ETS will have to publicly disclose their carbon emissions

India

  • Cap and Trade System

    • Initial stages of the cap-and-trade system intended to increase demand and supply of carbon credits in India, then will evolve into a mandatory emissions reduction structure in which sectors are granted emissions allowances

  • In July 2022, the parliament published a bill establishing the framework for a carbon credit trading scheme, enacting the first stage of the cap and trade system


Read our in-depth guide here to learn more about Asia Climate Legislation, how it could affect your corporation, and how DitchCarbon can help you!


Carbon Footprint

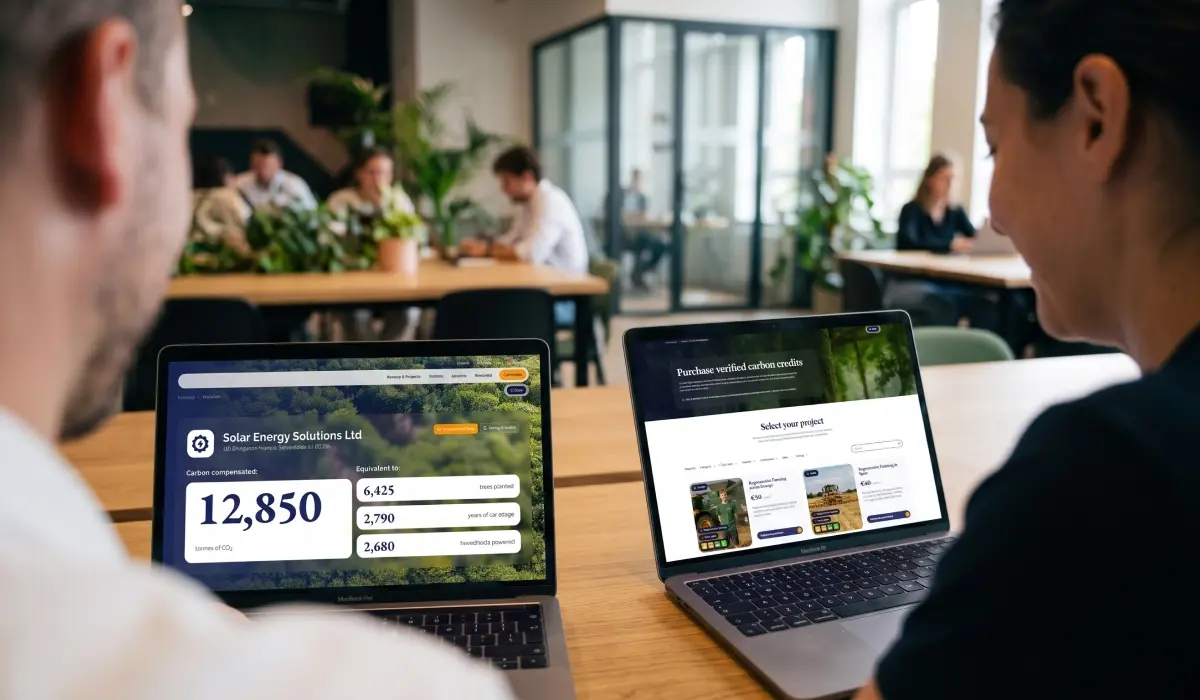
Want a simpler way to buy carbon credits? Discover our carbon marketplace

Published

on

Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

Continue Reading

Carbon Footprint

Climate-Linked Supply Chain Risk Is Already in Your P&L

Published

on

The earnings calls that quietly reframed climate from sustainability question to operating risk.

Three earnings calls in the last 18 months tell the story without any help from a press release.

Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.

You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.

Where climate risk has already appeared in earnings

The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.

Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.

Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.

What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.

The three commodity exposures that hit margin first

For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.

  • Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
  • Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
  • Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.

TCFD and ISSB disclosure changes

The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.

For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.

The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.

What procurement and finance can do now

Three actions matter near-term.

Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.

Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.

Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.

Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.

If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
Continue Reading

Carbon Footprint

Where should an SME start with a carbon action plan?

Published

on

More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.


Continue Reading

Trending

Copyright © 2022 BreakingClimateChange.com