

At the start of 2024, China introduced a new system of “capacity payments” designed to help coal-fired power stations shift into a supporting role, alongside low-carbon sources.
In theory, the payments should make it financially viable for coal plants to operate less frequently, switching off unless there is insufficient output from renewables and nuclear.
However, new Global Energy Monitor (GEM) analysis finds that, despite channeling 107bn yuan ($14.9bn) to China’s coal-plant owners during its first year, there is no clear evidence that the scheme has reduced the amount of hours during which coal plants are operating.
Moreover, the analysis shows that some 70-100% of China’s coal plants received payments, depending on the province, boosting their revenues by around 5-8%.
As such, the way the mechanism has been implemented continues to raise questions about its effectiveness in supporting renewable growth and China’s wider energy-transition targets.
Rather than encouraging operators to reduce operating hours and emissions, the loose application of eligibility “guardrails” means it could be prolonging coal-plant lifetimes instead.
A ‘supporting’ role for coal
Like many other countries, China faces the complex challenge of how to decarbonise its power sector while keeping the electricity grid reliable.
Following widespread power outages in 2021 and ongoing debates over how to manage the transition, the National Development and Reform Commission (NDRC), China’s powerful central planner, announced a new coal capacity payment mechanism in late 2023.
The policy, which took effect in January 2024, aims to maintain grid reliability, while supporting coal-fired power plants as they shift from a primary electricity source to a “regulating and supporting” role in China’s power mix, according to Han Xue, associate researcher at China Development Research Centre of the State Council.
The mechanism provides what is essentially a monthly “standby” payment to eligible public coal plants (see below). The payments are designed to help cover fixed operating costs during periods when coal plants’ output is low, often as a result of high renewable generation. They are also intended to ensure that coal plants are available to switch on during peak demand periods.
The national framework sets payment levels at either 30% or 50% of a benchmark coal plant’s total fixed costs, which the NDRC determined to be 330 yuan ($45.8) per kilowatt (kW).
The higher 50% rate applies in provinces where the role of coal power supply is transitioning rapidly, such as Chongqing and Sichuan in southwest China as well as Hunan in the south. However, from 2026 the rate will increase to at least 50% of the fixed costs nationwide.
To illustrate the mechanism’s impact, consider a 600 megawatt (MW) coal plant running at China’s 2024 average rates. It would be operating for 4,628 hours a year and selling electricity at 0.452 yuan ($0.063) per kilowatt-hour (kWh). This plant’s annual revenue would stand at about 1.2bn ($174m) yuan.
If it receives a 30% capacity payment, roughly 59.4m yuan ($8.2m) would be added to its bank account, driving up the revenue by 4.7%. If the rate is at the 50% level, the bump rises to 7.9%.
Capacity market criticism
From the outset, the policy drew questions and criticisms. Capacity markets in other countries have also sparked debate, including in the UK, Chile and Spain.
Early in the first year of implementation of China’s capacity payments, energy media outlet China Energy News quoted experts saying that the mechanism would gradually change the coal producers’ mindset of “the more they generate, the more they earn”.
However, other “restrictions” of the mechanism, such as the 330 yuan pay rate being “too low”, would “limit” its “effect” on transition, according to the outlet.
-
Sign up to Carbon Brief’s free “China Briefing” email newsletter. All you need to know about the latest developments relating to China and climate change. Sent to your inbox every Thursday.
Energy research institute the Regulatory Assistance Project (RAP) had pointed out that the mechanism is restricted to coal, excluding the “participation of alternative resources” able to offer similar services, such as energy storage or demand response.
Issues with the policy meant that it could encourage older coal plants to remain online, as well as potentially “exacerbating” the continued construction of new capacity, according to RAP.
After one year of China’s programme, GEM’s analysis finds that, while the policy has contributed to coal power plant revenue, there is still little definitive evidence to show that it is shifting coal to a “supporting” role, as intended.
This raises continued questions about the mechanism’s design, its implementation and whether it aligns with China’s long-term climate and energy objectives such as the “dual-carbon” goals.
Adding to the complexity, Lauri Myllyvirta, lead analyst at thinktank the Centre for Research on Energy and Clean Air, highlights a regional divide in China’s power mix from 2020 to 2024 in an article for Dialogue Earth.
He says that northern provinces have made more progress towards integrating clean energy than the southern regions, which have been “complacent” due to rich hydro resources. In contrast, others have invested more in wind and solar capacity, as well as in coordinating grid operation with neighbouring areas so as to better manage variable renewable output.
These regional disparities complicate any assessment of the capacity mechanism’s impacts.
Capacity payments ‘top 100bn yuan’
Only 12 provincial governments have released lists of qualifying plants, providing rare insight into how the capacity payment policy is being implemented.
These provinces represent just 38% of the country’s total operating coal capacity, meaning most of the national implementation remains undocumented in the public domain.
This partial picture makes it difficult to assess the policy’s broader outcomes, particularly as provinces appear to apply eligibility and enforcement criteria differently.
Based on the national policy’s payment levels and the 12 provincial recipient lists, the capacity payments in these provinces alone was more than 40bn yuan ($5.5bn) in the first year of the scheme, as shown in the figure below.
Combining the total operating capacity and payment numbers from the 12 provinces that have published data with GEM’s most recent national capacity figures, our analysis estimates that the total national payout in 2024 was approximately 107bn yuan ($14.8bn).
(This figure is uncertain. Greater transparency would help clarify how the mechanism is functioning and its role in shaping the future of coal in China’s power system.)

As shown in the figure above, capacity payments vary significantly across provinces. Of those 12 provinces with detailed published data, Henan in central China received the largest share, totaling approximately 9.4bn yuan ($1.3bn), driven by both its large eligible capacity of 56.9 gigawatts (GW) and the high payment rate (50% level).
Among the 12 provinces, Guangxi (20.5GW) and Yunnan (11.2GW) in southwest China, as well as Qinghai (2.9GW) in northwest China also applied the 50% payment rate, but their smaller eligible coal capacity resulted in comparatively lower total payments.
Broadly, the rankings of total capacity payments align with those of total operating coal capacity by province, which is expected given the direct link between capacity and payment eligibility.
However, the alignment is not exact. Yunnan, for example, ranks 11th out of 12 provinces in terms of operating capacity but 8th in total capacity payments.
This reflects how provincial differences in payment rates and eligibility shares, not just installed capacity, are shaping the financial impact of the policy.
Despite restrictions, most coal capacity is eligible
By cross-referencing provincial recipient lists with GEM’s Global Coal Plant Tracker (GCPT), it is possible to estimate the share of each province’s coal capacity receiving payments.
In almost all of the 12 provinces that published recipient lists, a large majority of coal capacity is eligible for payments, as shown in the figure below.

The NDRC national guidelines published alongside the policy announcement stipulate that only “compliant, public operating coal units” are eligible for the capacity payments. The guidelines identify three categories of coal-fired power plant units that are excluded:
- “Captive” units, which exclusively serve specific industrial or commercial entities and operate independently from the public power grid;
- Units failing to meet energy efficiency, environmental performance, or operational flexibility standards;
- Units not compliant with the broader “national plan”, a criterion that is not further clarified in the guidelines.
Despite these restrictions, most provinces with available data include between 70% and 100% of their total coal capacity under the mechanism, as the chart above shows.
In some cases, this appears inconsistent with the eligibility criteria. For example, the Mancheng Mill power station in Hebei in northern China has two 35MW combined heat and power (CHP) units, which started operating in 2018 to provide heat and power exclusively to a pulp and paper industrial park. This appears inconsistent with the “captive unit” exclusion.
In line with concerns raised by RAP, some newly built coal power plants were included in the initial provincial recipient lists, or added at a later date. For example, Beihai Bebuwan power station Unit 4 in Guangxi began operating in March 2024 and was added to the recipient list in September 2024. The inclusion of such projects could be interpreted as an incentive for new coal capacity, under the banner of grid reliability.
Although plant age is not explicitly disqualifying, coal power plants in China generally have a 30-year design lifespan. Yet older units are included in recipient lists in multiple provinces.
Shenhua Panshan power station Units 1 and 2 in Tianjin in northern China, for instance, began operating in 1994 and were retrofitted in 2023. Their continued inclusion raises questions about whether the policy supports transition, or extends the operational life of ageing assets.
It also highlights uncertainty around how retrofits will be treated, if undertaken after the policy entered force at the start of 2024, and whether such units will be firmly excluded from eligibility.
Finally, several provincial lists include smaller units, which may have limited ability to contribute to peak demand management. For example, five 57MW units from Shaoxing Binhai power station in Zhejiang, southeast China, built to provide heat demand for local dyeing and printing industries, were accredited for capacity payments.
Their actual contribution to evening peak load, when generation from solar and wind is low, is unclear from the list or other available provincial assessments.
More questions than answers?
There was only two months between the announcement of coal capacity payments and their implementation, leaving no time for pilot programmes or detailed feedback. This may help explain the ambiguities that have emerged during the provincial execution process.
Our analysis of the first year of the scheme suggests that provincial discretion has played a major role, with national criteria loosely applied in practice.
Moreover, there is no clear evidence to date that the mechanism has led to reduced coal utilisation hours, or significantly increased solar and wind generation.
While electricity generation from coal decreased in northern provinces during 2024, our analysis found that this was not the case in southern regions.
Different factors contribute to these regional differences, such as power demand and clean-energy resources. With only one year of data from the capacity payment scheme, it is not possible to attribute these changes solely to the capacity payment scheme.
To better align the mechanism with its stated goals, future adjustments could consider specifying coal-plant eligibility criteria more clearly and transparently.
Expanding the scheme to non-coal resources, such as energy storage, demand response or energy efficiency, could help it contribute to wider system flexibility and transition objectives.
Finally, ongoing monitoring of provincial implementation and energy trends will allow for a clearer assessment of how the policy evolves in the coming years.


The post Guest post: China’s ‘capacity payments’ boosted coal-plant revenue by up to 8% appeared first on Carbon Brief.
Guest post: China’s ‘capacity payments’ boosted coal-plant revenue by up to 8%

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
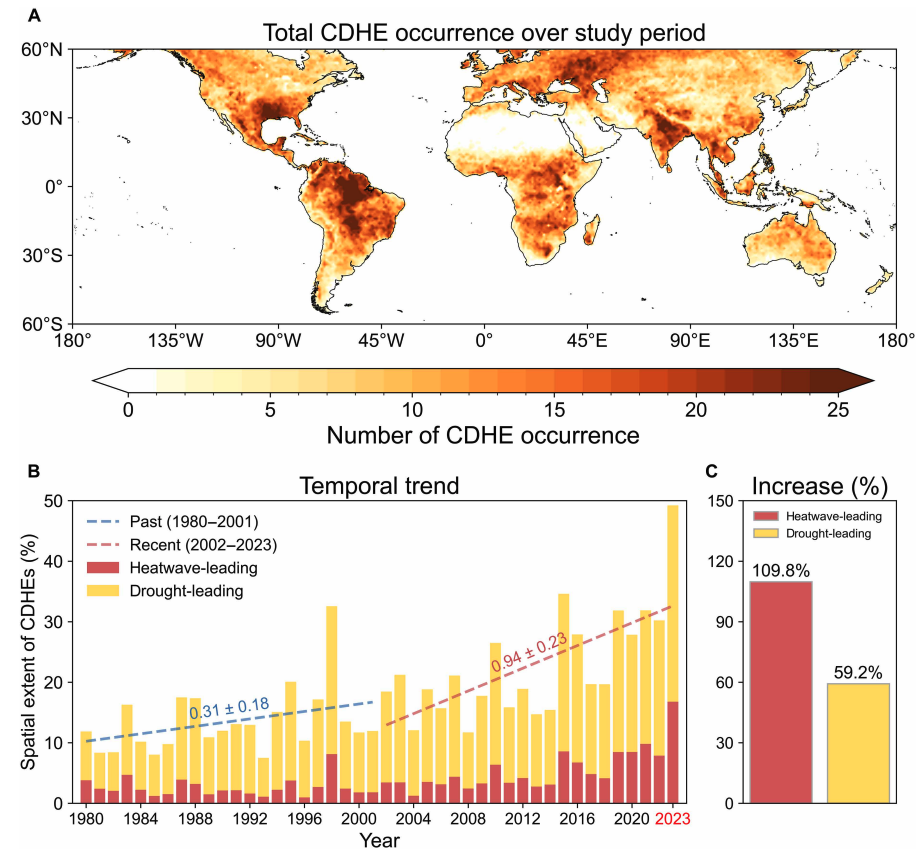
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: Bloomberg reported on increases in diesel prices in Europe and the US, speculating that rising fuel costs could be “a risk for president Donald Trump”. US gas producers are “poised to benefit from the big disruption in global supply”, according to CNBC. Indian government sources told the Economic Times that Russia is prepared to “fulfil India’s energy demands”. China Daily quoted experts who said “China’s energy security remains fundamentally unshaken”, thanks to “emergency stockpiles and a wide array of import channels”.
‘ESSENTIAL’ RENEWABLES: Energy analysts said governments should cut their fossil-fuel reliance by investing in renewables, “rather than just seeking non-Gulf oil and gas suppliers”, reported Climate Home News. This message was echoed by UK business secretary Peter Kyle, who said “doubling down on renewables” was “essential” amid “regional instability”, according to the Daily Telegraph.
China’s climate plan
PEAK COAL?: China has set out its next “five-year plan” at the annual “two sessions” meeting of the National People’s Congress, including its climate strategy out to 2030, according to the Hong Kong-based South China Morning Post. The plan called for China to cut its carbon emissions per unit of gross domestic product (GDP) by 17% from 2026 to 2030, which “may allow for continued increase in emiss