When General Motors (GM) committed $625 million to develop Thacker Pass in Nevada, it did more than fund a lithium project. It established a new model for how automakers secure critical minerals, and in doing so, it reshaped how investors should evaluate the next generation of U.S. lithium assets.
This was not a passive investment. It was a fully structured supply chain partnership, combining equity, long-term offtake, and pricing strategy into a single agreement.
For investors watching Nevada’s clay lithium sector, the implication is clear: the first project has been validated – now the market is looking for what comes next.
A Landmark Deal and a New Partnership Model
GM’s $625 million investment in Lithium Americas remains one of the largest commitments by an automaker into upstream battery materials. The structure of the deal matters as much as its size.
GM secured exclusive access to Phase 1 production, locking in long-term supply from Thacker Pass, which is expected to produce around 40,000 tonnes per year of battery-grade lithium carbonate. That output alone could support hundreds of thousands to up to 1 million EVs annually.
More importantly, the agreement evolved into a joint venture structure, with GM ultimately taking a 38% ownership stake in the project while securing long-term offtake rights. This started as a TopCo equity investment but changed into a JV.
John Evans, LAC CEO, said in an interview on the GM agreement:
“They view this as an investment as much as they do a hedge to ensure that they get low-cost lithium. They want to run this JV as a business.”
A key highlight of the Thacker Pass deal is GM’s offtake agreement, which now serves as a template for a world-class OEM arrangement. GM must purchase at least 20% of its North American lithium demand, with the option to increase to 100%.
The floor price is “meaningfully above” the August 2024 low (~$10,000/t) but below current prices (~$21,000/t), as noted by Evans. GM was given an effective discount at higher price levels, lightly structured when prices at that time were at ~$60,000/t.
GM provides rolling three-year forecasts, with the next year’s volume fixed, allowing Lithium Americas to commit remaining volume to third parties. The agreement covers up to three years of contracted volume at a time.
GM Moves Upstream: From Automaker to Lithium Investor
The GM–Thacker Pass agreement highlights a shift in the lithium market. Automakers are moving upstream, directly into mining, to secure supply, manage costs, and reduce geopolitical risk. This approach is driven by both market forces and policy, with the U.S. pushing for domestic sourcing of critical minerals to support EV supply chains.
Key elements of this emerging model include:
Equity participation in the mining project,
Long-term offtake agreements tied to production, and
Structured pricing mechanisms to manage volatility.
Thacker Pass sits at the center of that strategy. It is widely recognized as the largest known lithium resource in the United States, and with construction underway, it is moving from concept to execution.
Breaking the Clay Lithium Barrier
For years, sedimentary clay lithium has carried a persistent discount in the market. Unlike brine operations in South America or hard-rock mining in Australia, clay deposits had never been proven at a commercial scale. The uncertainty around processing, recovery rates, and operating costs limited investor confidence.
Thacker Pass is now changing that, with construction underway, production targeted later this decade, and processing planned using sulfuric acid leaching at an industrial scale. Once operational, it will mark the first large-scale commercial validation of clay lithium extraction.
In resource markets, once a new extraction method is proven, capital follows. Financing improves, development timelines accelerate, and the entire category begins to reprice. This is exactly what happened in Chile’s brine sector decades ago. Clay lithium in Nevada may now be entering a similar phase.
GM’s investment provides a real-world benchmark for what a bankable lithium project looks like in today’s market. It demonstrates that:
OEMs are willing to invest upstream
Long-term offtake agreements can anchor financing
Domestic lithium supply is now a strategic priority
It also answers a key question that has held back the sector: Will major industrial players commit to clay lithium at scale? The answer is now yes.
The Next Project in the Queue: NNLP
With Thacker Pass moving forward, investor focus naturally shifts to the next project capable of attracting similar strategic interest. That brings attention to Surge Battery Metals’ Nevada North Lithium Project (NNLP), a structurally aligned next-tier candidate.
NNLP is not competing with Thacker Pass as a first mover; it is emerging as a next-generation project within a now-validated category.
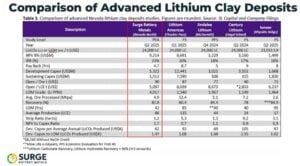
NNLP stands out based on core project metrics that directly impact economics. Its average lithium grade of 3,010 ppm is significantly higher than Thacker Pass Phase 1 material, which ranges from 1,500 to 2,500 ppm. Higher grades typically translate into more efficient recovery and lower processing intensity per tonne.
The project also benefits from near-surface mineralization and a low strip ratio of approximately 1.16:1. This may reduce mining complexity and indicate efficient material movement.
From a cost perspective, NNLP’s estimated operating cost of around $5,243 per tonne LCE compares favorably to LAC’s Thacker Pass guidance of roughly $6,200 per tonne.
Beyond geology, NNLP aligns with the same development framework that defines Thacker Pass. The project has secured a strategic partnership with Evolution Mining, funding up to C$10 million toward the Pre-Feasibility Study (PFS), while Fluor Corporation, the engineering firm involved in Thacker Pass, is leading the PFS at NNLP.
Leadership expertise also matters: Steffen Ball, a key member of the team, previously led battery raw material sourcing strategies at major automakers. These include Nissan North America and Ford Motor Company, aligning with the type of OEM agreements now seen in GM–Thacker Pass.
Scale, Market Tailwinds, and Second-Wave Opportunities
Scale is critical to attract major OEM partners. NNLP outlines a 42-year mine life with average annual production of approximately 86,300 tonnes of lithium carbonate equivalent. That output positions it to support long-term anchor offtake agreements, similar in structure to what GM secured at Thacker Pass.
Market fundamentals continue to support these developments:
Global lithium demand is projected to more than double by 2030.
EV production is scaling rapidly across major markets.
Governments are prioritizing domestic supply chains for critical minerals.
Even with recent lithium price volatility, long-term fundamentals remain intact. GM’s investment reflects a forward-looking strategy: secure supply today to avoid constraints tomorrow.
Thacker Pass carries the burden of being first, proving the process, building infrastructure, and validating the economics of clay lithium. This creates opportunities for projects that follow, like NNLP, which benefit from reduced technical uncertainty, clearer financing pathways, and a market that now understands clay lithium.
First Project Validated, Next Project Poised to Follow
GM’s $625 million investment was not just a bet on one project. It was a commitment to a new supply chain model for lithium—one that integrates mining, manufacturing, and long-term demand into a single structure. Thacker Pass is now proving that model, and NNLP is positioned to fit within it.
With higher grades, favorable mining characteristics, strong development partners, and the right scale, NNLP aligns with the criteria that attracted one of the world’s largest automakers to Nevada clay lithium in the first place.
For investors, the takeaway is straightforward: the first project is being built, the template is established, and the next project in the queue is becoming easier to identify.
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Surge Battery Metals Inc. (“Company”) made a one-time payment of $75,000 to provide marketing services for a term of three months. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: .
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
A plastic credit funds the collection of plastic waste in places where no formal system exists to collect it. Each credit represents a measured, independently audited quantity of plastic taken out of the environment or returned to use, tracked on a public registry.
EU carbon credit claims changed on 27 September 2026, the day the Directive (EU) 2024/825 began to apply across the European Union. The change is narrow. It changes how a company can talk about the credits it buys. A product can no longer be called neutral on the strength of compensation alone; however, every specific, evidenced statement about what a company measured, reduced, and funded stays fully available.