

Gabrielle Dreyfus is chief scientist at the Institute for Governance and Sustainable Development, Thomas Röckmann is a professor of atmospheric physics and chemistry at Utrecht University, and Lena Höglund Isaksson is a senior research scholar at the International Institute for Applied Systems Analysis.
This March scientists and policy makers will gather near the site in Italy where methane was first identified 250 years ago to share the latest science on methane and the policy and technology steps needed to rapidly cut methane emissions. The timing is apt.
As new tools transform our understanding of methane emissions and their sources, the evidence they reveal points to a single conclusion: Human-caused methane emissions are still rising, and global action remains far too slow.
This is the central finding of the latest Global Methane Status Report. Four years into the Global Methane Pledge, which aims for a 30% cut in global emissions by 2030, the good news is that the pledge has increased mitigation ambition under national plans, which, if fully implemented, could result in the largest and most sustained decline in methane emissions since the Industrial Revolution.
The bad news is this is still short of the 30% target. The decisive question is whether governments will move quickly enough to turn that bend into the steep decline required to pump the brake on global warming.
What the data really show
Assessing progress requires comparing three benchmarks: the level of emissions today relative to 2020, the trajectory projected in 2021 before methane received significant policy focus, and the level required by 2030 to meet the pledge.
The latest data show that global methane emissions in 2025 are higher than in 2020 but not as high as previously expected. In 2021, emissions were projected to rise by about 9% between 2020 and 2030. Updated analysis places that increase closer to 5%. This change is driven by factors such as slower than expected growth in unconventional gas production between 2020 and 2024 and lower than expected waste emissions in several regions.
Gas flaring soars in Niger Delta post-Shell, afflicting communities
This updated trajectory still does not deliver the reductions required, but it does indicate that the curve is beginning to bend. More importantly, the commitments already outlined in countries’ Nationally Determined Contributions and Methane Action Plans would, if fully implemented, produce an 8% reduction in global methane emissions between 2020 and 2030. This would turn the current increase into a sustained decline. While still insufficient to reach the Global Methane Pledge target of a 30% cut, it would represent historical progress.
Solutions are known and ready
Scientific assessments consistently show that the technical potential to meet the pledge exists. The gap lies not in technology, but in implementation.
The energy sector accounts for approximately 70% of total technical methane reduction potential between 2020 and 2030. Proven measures include recovering associated petroleum gas in oil production, regular leak detection and repair across oil and gas supply chains, and installing ventilation air oxidation technologies in underground coal mines. Many of these options are low cost or profitable. Yet current commitments would achieve only one third of the maximum technically feasible reductions in this sector.
Recent COP hosts Brazil and Azerbaijan linked to “super-emitting” methane plumes
Agriculture and waste also provide opportunities. Rice emissions can be reduced through improved water management, low-emission hybrids and soil amendments. While innovations in technology and practices hold promise in the longer term, near-term potential in livestock is more constrained and trends in global diets may counteract gains.
Waste sector emissions had been expected to increase more rapidly, but improvements in waste management in several regions over the past two decades have moderated this rise. Long-term mitigation in this sector requires immediate investment in improved landfills and circular waste systems, as emissions from waste already deposited will persist in the short term.
New measurement tools
Methane monitoring capacity has expanded significantly. Satellite-based systems can now identify methane super-emitters. Ground-based sensors are becoming more accessible and can provide real-time data. These developments improve national inventories and can strengthen accountability.
However, policy action does not need to wait for perfect measurement. Current scientific understanding of source magnitudes and mitigation effectiveness is sufficient to achieve a 30% reduction between 2020 and 2030. Many of the largest reductions in oil, gas and coal can be delivered through binding technology standards that do not require high precision quantification of emissions.
The decisive years ahead
The next 2 years will be critical for determining whether existing commitments translate into emissions reductions consistent with the Global Methane Pledge.
Governments should prioritise adoption of an effective international methane performance standard for oil and gas, including through the EU Methane Regulation, and expand the reach of such standards through voluntary buyers’ clubs. National and regional authorities should introduce binding technology standards for oil, gas and coal to ensure that voluntary agreements are backed by legal requirements.
One approach to promoting better progress on methane is to develop a binding methane agreement, starting with the oil and gas sector, as suggested by Barbados’ PM Mia Mottley and other leaders. Countries must also address the deeper challenge of political and economic dependence on fossil fuels, which continues to slow progress. Without a dual strategy of reducing methane and deep decarbonisation, it will not be possible to meet the Paris Agreement objectives.
Mottley’s “legally binding” methane pact faces barriers, but smaller steps possible
The next four years will determine whether available technologies, scientific evidence and political leadership align to deliver a rapid transition toward near-zero methane energy systems, holistic and equity-based lower emission agricultural systems and circular waste management strategies that eliminate methane release. These years will also determine whether the world captures the near-term climate benefits of methane abatement or locks in higher long-term costs and risks.
The Global Methane Status Report shows that the world is beginning to change course. Delivering the sharper downward trajectory now required is a test of political will. As scientists, we have laid out the evidence. Leaders must now act on it.
The post Curbing methane is the fastest way to slow warming – but we’re off the pace appeared first on Climate Home News.
Curbing methane is the fastest way to slow warming – but we’re off the pace

Climate Change
“Sink or swim”: WA Gov hugely underestimating decline in regional gas demand while sleeping on green exports, new report finds
PERTH, Tuesday 13 October 2026 — A new report from Greenpeace Australia Pacific and Springmount Advisory reveals green commodity exports are an untapped economic opportunity for Western Australia in a declining Asian gas market, while offering a genuine solution for decarbonising Asia.
From Gas to Green: Building Western Australia’s Future State is a comprehensive analysis of the declining gas market in Asia, and the untapped economic opportunity for WA to become a global leader in green commodity exports while driving the regional shift away from fossil fuels.
The report offers key recommendations for the WA Government to support regional decarbonisation through an orderly phase out of gas exports in favour of green iron and other green exports. It comes as global climate leaders from across business, politics and advocacy prepare to meet for the Global Citizen Now: Perth event focused on decarbonising WA.
Key findings:
- Gas demand is falling across WA’s core markets in Asia: Gas demand fell in 2025 and is projected to continue to decline, driven by a combination of global geopolitical factors and domestic concerns.
- Policy shifts in key markets since the war on Iran now prioritise renewables and nuclear over gas: Japan, South Korea and China have legislated energy plans that prioritise renewables and nuclear over gas.
- New WA gas would arrive in a saturated, uncertain Asian market filled with cheaper gas: The US is now the world’s largest liquefied gas producer and plans to double its capacity as it also targets Asian markets.
- Green commodities offer a real solution to sustain WA’s economy: WA can lead Australia’s green commodity exports, which by 2060 could be worth almost a trillion dollars.
- Exporting more WA gas is likely to delay or impede Asia decarbonisation: Despite claims by the gas industry, there is no evidence that WA gas is displacing coal in Asia, and in fact diverts resources from genuine decarbonisation options.
Geoff Bice, WA Campaign Lead at Greenpeace Australia Pacific said: “As our export partners in Asia shift away from expensive and polluting gas, the WA Government has a golden opportunity to pivot our economy to green exports, like green iron, which is the most effective way to help our region to decarbonise.
“The writing is on the wall: gas is in decline, renewables are our future. In this context, it makes zero sense for the government to encourage high risk projects like Woodside’s reckless Browse gas proposal at Scott Reef.
“This report clearly shows that the WA Government faces a choice: sink or swim. They can either allow the gas industry to keep ripping off West Australians and continue propping up its decline, or choose the path that will deliver enormous benefits to the state and the world by becoming a leader in the rapidly expanding green economy.”
Tom Quinn, Managing Director of Springmount Advisory: “Western Australia prospers when it looks to the future and builds for future demand. Twenty years from now, what the world needs is green commodities made using WAs abundant renewable resources. Just like it did with iron ore in the 1950s and gas in the 1970s, WA should look to the future and build what the world will need, not sunsetting industries like gas that are already past their peak.”
-ENDS-
Media contact
Kate O’Callaghan on 0406 231 892 or kate.ocallaghan@greenpeace.org
Lucy Keller on 0491 135 308 or lucy.keller@greenpeace.org
A report from Greenpeace Australia Pacific and Springmount Advisory reveals the untapped green economic opportunity for Western Australia in a declining Asian gas market, which also offers a genuine solution for decarbonisation in Asia.
Is Western Australia clinging to a fading gas industry while a thriving green future passes it by? As major Asian trading partners rapidly pivot away from volatile gas imports toward cheap solar and battery storage, this report exposes a high-stakes choice: risk becoming stranded in an oversupplied fossil fuel market, or harness WA’s unmatched sun and wind to lead the global clean energy transition.
Summary
From Gas to Green: Building Western Australia’s Future State reveals that Western Australia (WA) faces a critical juncture as falling Asian gas demand, geopolitical gas supply volatility and accelerating renewable energy deployment undermine the long-term economic viability of gas exports. By harnessing its world-class wind and solar resources, the report demonstrates that WA can execute an orderly phase-out of gas and pioneer a green commodity export economy that could generate $987 billion in economic value by 2060, create 24,000 ongoing jobs, and drive a 9.6% reduction in global greenhouse gas emissions.
Key Findings
- Gas demand is falling in Asia – WA can no longer rely on gas exports: Gas demand in core Asian markets fell in 2025 and is projected to continue to decline in 2026. Legislated energy plans in Japan, South Korea, and China now prioritise renewables and nuclear over gas.
- Asia is increasing renewables, importing gas just gets in the way: Evidence from markets like Thailand suggests that gas imports are increasingly crowding out cheaper renewable energy investments and battery storage rather than displacing coal, locking in more emissions over time.
- Green commodities offer a real solution to decarbonise Asia – this is a major win for WA: With world-class renewables, WA can lead Australia’s green commodity exports, which by 2060 could be worth almost a trillion dollars ($987 billion) and support a genuine 9.6% reduction in global emissions.
Recommendations to WA government
Recommendation 1: Plan an orderly gas phase-out aligned with a trading partner pivot plan
Implement a managed, orderly phase-out of gas exports aligned with trading partners’ decarbonisation pathways, rather than waiting for demand to collapse, by:
- Developing and implementing a staged phase-out of gas facilities aligned with feedstock supply expiry or typical end of facility lifespans.
- Committing to no new gas development for gas expansion, including Browse and Kimberley fields.
- Developing new, reciprocal trade relationships with existing gas trade partners, structured to progressively replace gas exports with green commodities – integrated with recommendation 2.
Recommendation 2: Develop an integrated green commodity export strategy, positioning WA as a global green iron manufacturing hub
Establish an integrated green commodity export strategy that immediately prioritises green iron development, positioning WA as a global green iron manufacturing hub, by:
- Committing to green commodity export targets to give industry and investors a clear demand signal.
- Prioritising green iron as the lead sector within the broader green commodity strategy, given WA’s iron ore endowment and first-mover potential.
Recommendation 3: Reject false solutions such as carbon dumping (CCS) and blue hydrogen
Reject carbon dumping (also described as carbon capture and storage, or CCS) and blue hydrogen as viable decarbonisation technologies, and prioritise green hydrogen and proven renewables for clean energy and fuel production by:
- Excluding blue hydrogen projects (and CCS-dependent projects) from all government support programs.
- Requiring existing hydrogen-based production (including ammonia, methanol, synthetic fuels) to have clear, near-term transition timelines to switch to green hydrogen production.

What you can do
Together, we can push for a prosperous green future.
You can help by:
- Sending an email to Environment Minister Murray Watt and Prime Minister Anthony Albanese, calling on them to reject Browse.
- Sharing this story to help more Australians understand what’s at stake.
- Encouraging your friends and family to take action.
REPORT: “From Gas to Green” Building Western Australia’s Future State
Cleaner cooking projects in the UN carbon market will have to set aside a share of their credits to insure against the risk that the trees they save are lost to fire, drought or logging, after the market’s regulator rejected calls to exempt the sector.
The requirement is part of a new rulebook that the Paris Agreement carbon market regulator – the Article 6.4 Supervisory Body – approved last Friday for programmes that aim to cut emissions by distributing new and cleaner cookstoves in regions that still burn wood or charcoal for cooking.
These are the UN mechanism’s first rulebooks for cookstoves, one of the carbon market’s most popular credit types and also one of its most criticised for overstating climate benefits.
They consist of two methodologies: one for programmes that aim to cut greenhouse gas emissions by distributing more efficient cookstoves that burn less wood or charcoal, and a separate methodology for projects shifting households to lower-emissions cookers running on electricity or liquid petroleum gas (LPG).
Mkhuthazi Steleki, the South African chair of the Supervisory Body, said “this decision gives cleaner cooking projects a new pathway under the UN carbon market, with clear rules to ensure that each credit represents a real and credible emission reduction”.
Industry and NGOs lobby to weaken UN carbon credit rules in “coordinated” push
In copycat submissions and a private briefing to government officials, the groups have opposed a proposal to tighten safeguards for emissions offsetsLaunch of Africa Energy Bank delayed again in blow to oil and gas hopes
Repeated delays are raising questions about the bank’s momentum and whether it can mobilise investment to finance Africa’s oil and gas ambitions in an era of energy transition

Exemption push rejected
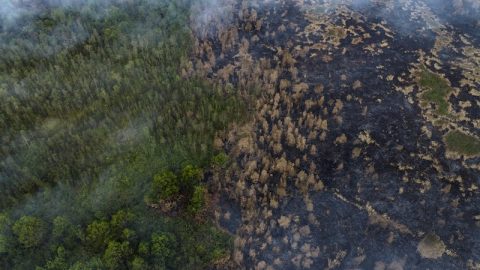
More efficient cookstove projects earn credits based on the amount of carbon they save by preserving trees that would have otherwise been cut down and burned for fuel. But if those trees later burn in a wildfire or are logged, the carbon stored would be released anyway, erasing the climate benefits of the credits.
Several carbon credit developers, conservation NGOs and the UN Environment Programme (UNEP) disputed that cookstove projects face this risk, in what critics described as a “coordinated lobbying campaign”.
They argued that, unlike forest protection schemes, this type of credit represents a “flow” of avoided emissions rather than a “stock” of stored carbon that can be released. They also warned that requiring a buffer would impose disproportionate costs and undermine the financial viability of these activities.
But the UN carbon market regulator was not persuaded by the argument. It decided that projects would have to protect against this reversal risk by handing over a percentage of credits to a so-called “buffer pool” instead of selling them.
‘New paradigm’
The amount of credits to be given up is calculated by applying different methods for natural risks, like wildfires, droughts or hurricanes, and human-caused ones, such as logging or land clearing.
For natural risks, project developers will need to apply local risk values derived from new modelling published by a group of independent scientists.
Campaigners have broadly welcomed the decision. Federica Dossi, an expert at Brussels-based advocacy group Carbon Market Watch, said it sets a new paradigm for calculating reversal risk based on empirical data. “This approach is grounded in science and we hope to see this now being adopted by other carbon crediting mechanisms in the voluntary market,” she added.
Backers claim this method is more rigorous than current practice in the voluntary carbon market, which largely relies on expert guesswork.
Pre-COP draws attention to Pacific’s climate plight and 1.5C goal
Pushback over science
As Climate Home News previously revealed, the same industry and NGO groups that sought an exemption from the “buffer pool”, along with some corporate buyers, criticised the use of a study backed by the UN carbon market’s experts that recommended the new risk assessment approach.
The groups pushed for more flexible rules that would have allowed natural risk values drawn from other sources, including national databases, or from the project developers themselves.
While the Supervisory Body rejected this approach, it gave project developers and countries the option to propose alternative values that would first need to be vetted by the mechanism’s expert panel and then approved by the regulator.
A carbon market expert told Climate Home News that, while it is too early to say how this provision will be used, they expect requests will have to be backed up with solid scientific evidence, lowering the risk of unfounded claims.

Policy discounts questioned
To guard against human-caused risks, projects will need to apply a flat 20% value set by the Supervisory Body, at the bottom of the 20-45% range recommended by its technical experts ahead of last week’s meeting.
That value can be further reduced by up to two-thirds if the host country has an emission-reduction plan covering forests, a long-term climate strategy and a framework for the UN’s REDD+ forest protection scheme.
Injy Johnstone, senior research fellow at the Munich-based Max Planck Institute, said that, while these are important governance measures, their existence does not necessarily demonstrate that the underlying risk of forest carbon loss has been reduced.
“It is important to distinguish between evidence of actual risk reduction and assumptions about the effectiveness of policy commitments,” she added.
Moving target
A UN source told Climate Home News that, under the approved formula, improved cookstove projects must set aside at least 9% of credits linked to saved wood if they operate in the lowest-risk areas and the host country can claim all available discounts. The share of credits rises significantly in regions with high natural risk values, such as Guyana, Sri Lanka and Timor Leste, or that do not have REDD+ programmes.
These factors could change in the future as the Supervisory Body asked its technical experts to recommend revisiting the risk values “should credible new evidence arise”.
Climate change is likely to make forest destruction events, such as wildfires or hurricanes, more frequent and more severe in certain regions. Meanwhile, national policies on forest protection can shift significantly depending on government changes.
Johnstone said the UN carbon market needs periodic reassessment to respond to new evidence showing that previously assumed levels of risk were too low.
“The integrity of credits is not guaranteed simply because a reversal risk tool exists,” she added. “The real test will be whether the mechanism provides equivalent atmospheric protection over time, rather than simply introducing another layer of accounting requirements”.
The post