


Trafigura Group, a global leader in commodities trading, is making a bold bet on the recovery of the carbon credits market. Despite its recent struggles, the company views emerging regulatory frameworks and international agreements as pivotal for mainstreaming carbon credits in emissions accounting.
With new policies creating clearer pathways for businesses to meet climate targets, Trafigura expects a surge in demand for record growth.
The Carbon Market Makeover: Regulations Reshape Voluntary Credits
The voluntary carbon market (VCM) allows companies and individuals to buy carbon credits to offset emissions voluntarily, rather than as part of regulatory compliance. These credits fund projects that reduce or avoid greenhouse gas emissions, such as renewable energy, reforestation, or community-based initiatives.
Unlike mandatory carbon markets governed by laws, VCM operates through independent standards and registries, providing flexibility for participants. As the VCM evolves, efforts to enhance quality and credibility are shaping its role in global climate action.
Hannah Hauman, Trafigura’s global head of carbon trading, highlighted the impact of increased regulations in Europe, the US, and Asia. These frameworks are designed to help companies achieve net-zero emissions, reinforcing the importance of a robust carbon credits market.
- RELATED: EU Regulations Poised to Catalyze Global Carbon Market Convergence, Says Trafigura’s Hauman
At the recent COP29 summit in Baku, negotiators finalized rules under Articles 6.2 and 6.4 of the Paris Agreement, laying the groundwork for a global carbon trading system.
Article 6.4 introduces a UN-backed mechanism with standardized guidelines for carbon credit quality. It offers a more transparent and structured approach. In contrast, Article 6.2 allows countries to set their own criteria for carbon credit exchanges, which some critics fear could weaken the market.
Danny Cullenward, senior fellow at the Kleinman Center for Energy Policy, warned that Article 6.2 could create an “anything goes” market. This can potentially undermine both Article 6.4 and broader climate efforts.
Industry Challenges and Corporate Retreats
The voluntary carbon market has faced criticism over greenwashing and the issuance of low-quality credits. In 2023, the market’s value dropped by 23% as shown in the graph below. This declining trend started in 2021 when critics began to shake the market. Moreover, key players like HSBC Holdings, Shell Plc, Delta Air Lines, Google, and EasyJet have scaled back their involvement.

Just recently, HSBC abandoned plans to build a carbon credits trading desk, while Shell began selling off a majority stake in its nature-based credit portfolio.
Despite these challenges, regulatory advancements have led to optimism. Hauman remarked that countries now have a “regulatory line of sight” to guide them through 2030, providing clarity for companies on expectations, investment strategies, and emissions reductions.
According to BloombergNEF’s data, Europe is leading the UN-backed carbon credit investment while Ghana gets the most funding for Article 6 projects.

Trafigura’s Sustainability Strategy: Restoring Forests, Reviving Markets
Trafigura is capitalizing on this evolving landscape. As the world’s largest trader of carbon-removal credits, the company is expanding its portfolio to meet rising demand.
In November 2024, Trafigura announced a $500 million investment in a carbon credits project to restore Africa’s Miombo woodlands. The project aligns with Article 6.4 guidelines, emphasizing quality and environmental impact.
In the same month, the giant commodity trader, alongside Temasek-owned GenZero, has pledged $100 million to Colombia’s largest nature-based carbon removal project. The project seeks to restore degraded land in the South American nation while generating carbon credits.
- SEE MORE: Colombia’s Largest Carbon Project Secures $100M Backing from Temasek-Owned GenZero and Trafigura
Hauman noted that carbon credits are evolving from experimental tools to investment-grade assets, thanks to regulatory shifts. This transformation is expected to enable companies to incorporate credits into their long-term sustainability strategies confidently.
The company itself is pursuing ambitious carbon reduction goals, aiming to:
- cut Scope 1 and 2 emissions by 50% by 2032, and
- achieve net zero by 2050.
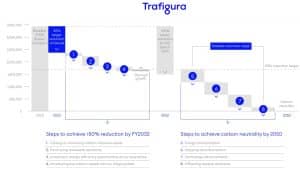
In addition to reducing its direct emissions, Trafigura is focused on lowering Scope 3 emissions intensity. This includes the impact of its traded products. To accelerate its energy transition, the company does these measures:
- Invest heavily in renewable energy, including solar and wind projects.
- Develop low-carbon fuels like green hydrogen and ammonia.
- Launched a $2 billion fund in 2023 to support energy transition projects.
The fund is also for advancing its emissions trading activities, helping clients offset their carbon footprints with high-quality carbon credits.
A New Era of Investment-Grade Carbon Assets
While the carbon market faces hurdles such as inconsistent legal definitions and price volatility, companies like Trafigura, Cummins, Bosch, Daimler, Toyota, and Volvo see potential for growth. Regulators across regions recognize the role of carbon credits, especially removal-based units, in helping businesses achieve net-zero emissions by mid-century.
COP29 also marked a turning point for reforestation and afforestation projects under the UN’s Clean Development Mechanism (CDM). These projects, previously stalled, have been transferred to the revamped Article 6.4 framework, benefiting countries like India and Colombia, which host 27 eligible projects.
The carbon market is moving away from being policy-driven to becoming a dynamic investment arena. Trafigura’s strategic partnerships and investments position it to lead this transition. The company aims to drive both market growth and meaningful climate action, by addressing regulatory requirements and maintaining high-quality standards.
As the industry adapts to new rules, Trafigura’s efforts show the shift toward a more structured and credible carbon credits market. It underscores the company’s readiness to thrive in the evolving carbon market landscape.
The post Trafigura Bets Big, $600M, on Carbon Credits Market Revival appeared first on Carbon Credits.

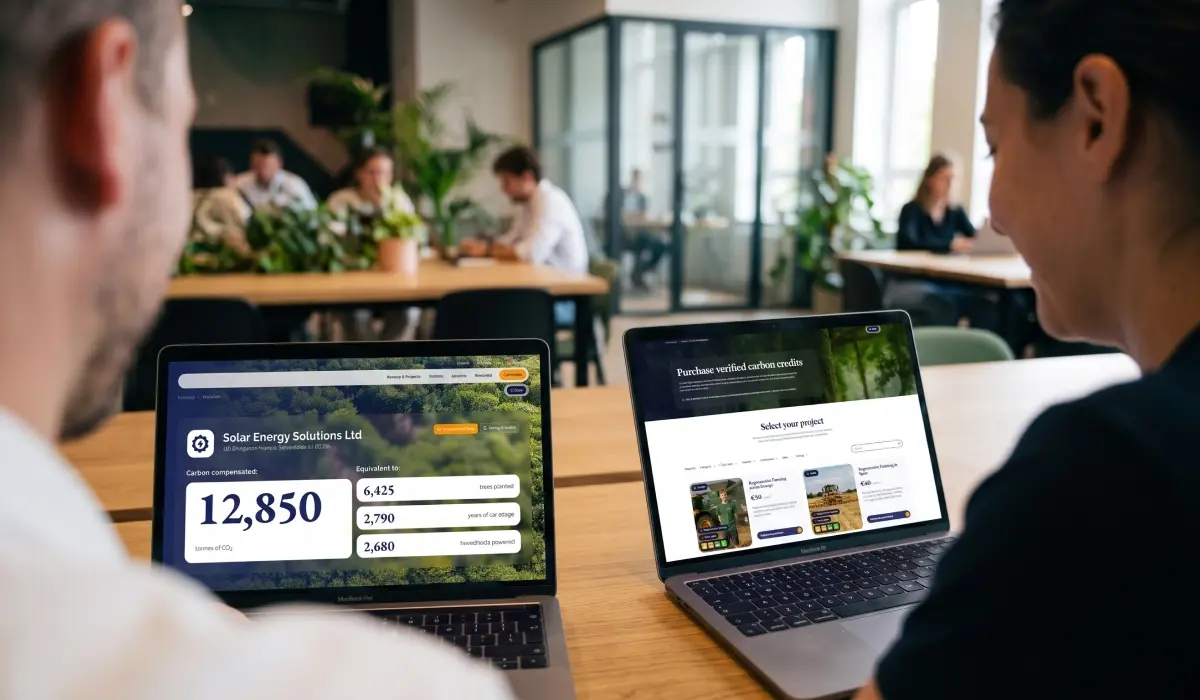
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits