


Disseminated on behalf of West Red Lake Gold Mines Ltd.
Gold mining has always been tough, but discovering and developing new mines is getting even tougher and rarer. Even when a new deposit is found, production can take years and sometimes decades.
S&P Global reported that gold exploration budgets dropped 7% to $5.55 billion in 2024, marking the lowest share in a decade. While gold still made up 45% of global exploration, the number of explorers fell 8% to 1,235. This decline came as big companies merged and fewer small explorers entered the market.

Even with record-high gold prices, companies are focusing on cutting costs and avoiding risks. Smaller explorers are struggling to get funding, making it harder for new projects to start. This is why there is a “rarity of a new gold mine today”.
Moving forward, the big question is: With a supply deficit and soaring gold prices, are gold stocks still a smart investment? Let’s take a look at how investors are responding to this market.
Glittering Gains: Gold’s Supply Crunch Boosts Stocks
Gold mining companies, especially those close to production, present strong investment potential. Global macroeconomic and political uncertainty, inflation, and a supply crunch of the metal are all combining to make gold stocks appealing. Add in record gold prices that have not yet lifted gold stock prices and optimism in the market remains high.
With gold prices at record highs and rising economic uncertainty, investors are once again turning to gold equities for big gains. However, not all gold stocks perform the same. Developer-to-producer companies have an advantage: they move from spending money on building a mine to actually producing and selling gold. This shift often triggers a stock re-rating, leading to significant returns for investors.
Investing in a Gold Bull Market
Gold, a traditional safe-haven asset, has surged to repeated record highs in 2025. On April 22, the spot price reached $3,424 per ounce and briefly touched $3,432 in early May before stabilizing around $3,244.
This rally has been driven by escalating trade tensions, a weakening U.S. dollar, and strong demand from both institutional and retail investors. Over the past year, gold has gained nearly 50%, reflecting investors’ search for stability and long-term value amid ongoing market turbulence.
The bullish momentum is further fueled by persistent inflation fears, geopolitical uncertainty, expectations of potential U.S. Federal Reserve rate cuts, and continued buying by central banks and exchange-traded funds (ETFs).

Moving on, if you’re looking to invest in gold during this bull market, here are your main options:
-
Major gold miners/indices
These provide steady exposure to gold’s price movements with lower risk. As gold prices rise, miners generate more revenue. However, their stock prices don’t generally give a lot of additional leverage to gold’s moves.
-
Developer-to-producer companies
These companies offer strong upside potential. Once a mine enters production, the company transitions from burning cash to generating revenue. This often leads to a stock price gain. Most projects that reach the construction phase successfully enter production. This makes them a relatively safe bet compared to exploration stocks.
Gold Mining Companies Gain Value
For years, Western investors ignored gold and favored tech stocks instead. But that’s changing. Rising inflation and new tariffs have pushed investors back to gold as a “safe haven”. Meanwhile, China, India, and the Middle East have been stockpiling gold for years. This has significantly strengthened their influence in the market.
The entire gold mining sector holds a market cap of $600 billion, while the top five tech companies combined are worth $15 trillion. A shift of just 1% of tech investments into gold miners could boost the sector’s market cap by 25%. If investors start to rotate some capital into gold stocks, the growth potential could be massive.
This also shows that as the gold supply tightens, existing mining companies will become more valuable.
A Rare Opportunity: West Red Lake Gold Mines Launching in 2025
Coming out of many years of investor disinterest in gold stocks, in 2025 very few single-asset gold companies will begin production. As per a BMO report from January 2025, West Red Lake Gold Mines (TSXV: WRLG; OTCQB: WRLGF) is the only single-asset company launching production in a tier-one jurisdiction this year.
There are four single-asset North American-listed companies starting up new gold mines this year. But…
- Artemis Gold: Already pouring gold and has re-rated.
- Two other projects in Mongolia and Guinea: These are riskier due to geopolitical concerns.
Thus, WRLG stands out as a strong opportunity for investors looking for growth in a safe and mining-friendly region.

Reviving the Madsen Gold Mine
West Red Lake Gold Mines Ltd. is a publicly traded company focused on restarting the Madsen Mine and exploring its 47 sq-km land package in Ontario’s Red Lake Gold District.
The Madsen Mine has a strong history, producing 2 million ounces of high-grade gold between 1936 and 1971. However, a recent attempt to restart operations failed due to an inaccurate resource model and lack of funding, leading to low gold production and high costs.
West Red Lake acquired the mine in early 2023 and has been working to fix these issues. The company just restarted the mine and is ramping up production over the second half of the year, aiming to unlock the mine’s full potential.
The Red Lake Gold District in Northwest Ontario is one of the world’s richest gold regions, with over 30 million ounces of high-grade gold mined to date.

Near-Term Producers Offer the Best Returns
West Red Lake Gold Mines believes, “Timing is everything in gold investing”.
The biggest gains typically happen when a company transitions from development to production. This phase is known as the “golden runway” because substantial stock price appreciation often happens. This pattern is illustrated in the Lassonde Curve, which is a roadmap for how mining projects typically grow in value: big value gains on discovery, valuation deterioration as a project slogs from discovery to build, and then often value gains once again as production finally draws near.
WRLG’s Madsen Mine in Ontario is already built and is ready to restart production in H2 2025. Most significantly, the company has already overcome the major hurdles of permitting, financing, and development.

Conclusion
As economic uncertainty grows, gold is becoming a top long-term investment. But with fewer new discoveries, future supply looks uncertain.
Investors can find the best opportunities in companies with strong growth potential.
-
- Established gold producers offer stability with proven success.
- Developer-to-producer companies like WRLG offer strong potential for major stock jumps.
- The biggest gains often come from companies moving into production, where investor interest surges.

With gold stocks back in demand, the potential for big returns is stronger than ever. In a market with few new mines, WRLG could be as a game changer.
DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers or financial advisers, and you should not rely on the information herein as investment advice. West Red Lake Gold Mines Ltd. made a one-time payment of $30,000 to provide marketing services for a term of 1 month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options in the companies mentioned. This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. This does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular Issuer from one referenced date to another represent an arbitrarily chosen time period and are no indication whatsoever of future stock prices for that Issuer and are of no predictive value. Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or constitute an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reading the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures. It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee it.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate”, “expect”, “estimate”, “forecast”, “planned”, and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties and other factors that may cause actual results to differ materially from the forward-looking information in this news release and include without limitation, statements relating to the plans and timing for the potential production of mining operations at the Madsen Mine, the potential (including the amount of tonnes and grades of material from the bulk sample program) of the Madsen Mine; the benefits of test mining; any untapped growth potential in the Madsen deposit or Rowan deposit; and the Company’s future objectives and plans. Readers are cautioned not to place undue reliance on forward-looking information.
Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility; the state of the financial markets for the Company’s securities; fluctuations in commodity prices; timing and results of the cleanup and recovery at the Madsen Mine; and changes in the Company’s business plans. Forward-looking information is based on a number of key expectations and assumptions, including without limitation, that the Company will continue with its stated business objectives and its ability to raise additional capital to proceed. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking information, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially from those anticipated in such forward-looking information. Accordingly, readers should not place undue reliance on forward-looking information. Readers are cautioned that reliance on such information may not be appropriate for other purposes. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis for the year ended December 31, 2024, and the Company’s annual information form for the year ended December 31, 2024, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release and the Company assumes no obligation to update or revise such information to reflect new events or circumstances, except as may be required by applicable law.
For more information on the Company, investors should review the Company’s continuous disclosure filings that are available on SEDAR+ at www.sedarplus.ca.
Please read our Full RISKS and DISCLOSURE here.
The post The Rarity of a New Gold Mine: West Red Lake Gold Could Be a Golden 2025 Opportunity appeared first on Carbon Credits.

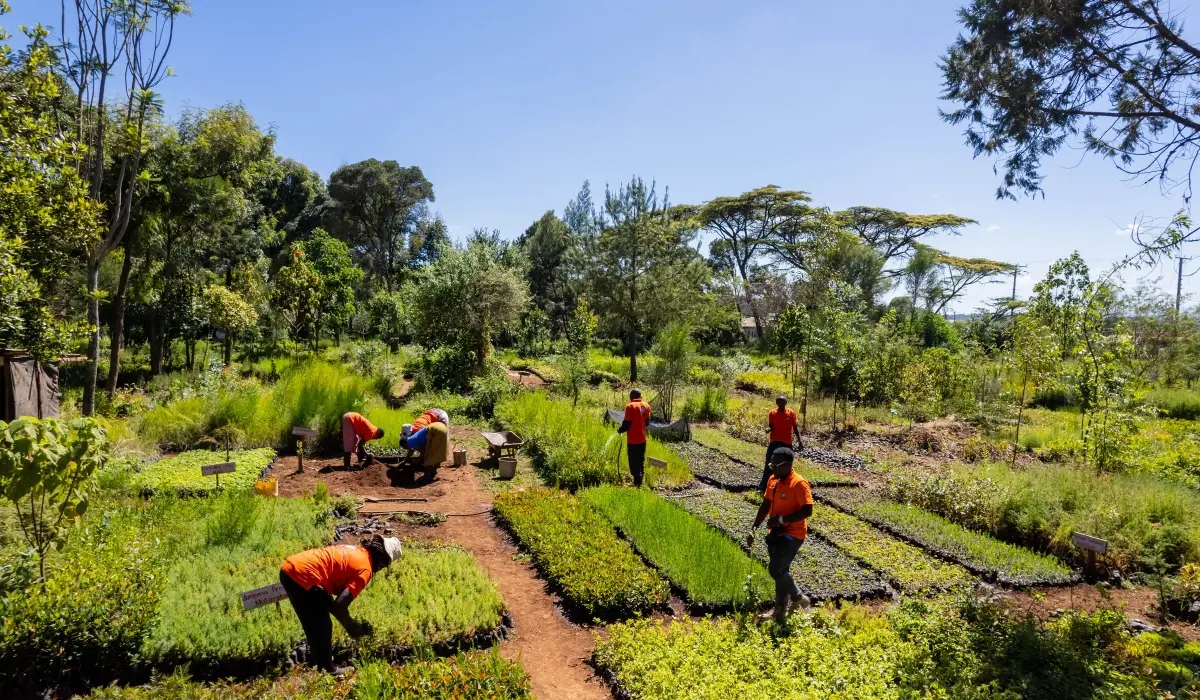
Carbon credit providers vs marketplaces is the first comparison many buyers try to make. In this comparison, a carbon credit provider is the project developer: the company that originates credits from its own projects and sells them directly. A carbon credit marketplace is a platform that lists credits from many projects at published prices.

Carbon Footprint
Democrats who call climate change an emergency should not defend a permitting system too slow to build the clean energy that would address it.”
Democrats, Take The Deal. New York Times editorial, Nov. 12.
Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
CCC’s MRV and Additionality article explains the separate evidence questions a project reviewer will ask.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Sources
[1] GHG Protocol, Land Sector and Removals Standard, version 1.1, and companion Guidance, June 2026: https://ghgprotocol.org/land-sector-and-removals-standard ; https://ghgprotocol.org/land-sector-and-removals-guidance
[2] Science Based Targets initiative, Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, especially pp. 16–17, 37, and 41: https://sciencebasedtargets.org/resources/files/SBTiFLAGGuidance.pdf
[3] Accountability Framework initiative, Accountability Framework and guidance for companies: https://accountability-framework.org/
[4] GHG Protocol, Frequently Asked Questions: Land Sector and Removals Standard, questions 10 and 18: https://ghgprotocol.org/blog/frequently-asked-questions-land-sector-and-removals-lsr-standard

‘COP-out’: COP31 fails to deliver the ambition needed to phase out fossil fuels and address climate breakdown
COP31 Bulletin Day 13: New draft retains electrification goal but delays adaptation finance and science decisions

How “Marie Antoinnete” Can We Get?

-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-
