

As 2024 passes its midpoint, the global climate continues to push into uncharted territory.
Carbon Brief’s analysis indicates a 95% probability that this year will surpass 2023 as the warmest year on record in the Copernicus/ECMWF ERA5 dataset.
This projection emerges amid a series of climate extremes that have marked the first half of 2024.
In the latest “state of the climate” quarterly update, Carbon Brief assesses the first full six months of 2024 and finds:
- The first six months of 2024 have each set new temperature records, extending an already remarkable streak of 13 consecutive record-breaking months dating back to 2023.
- On 22 July, the world experienced its highest absolute global daily temperature on record, reaching a scorching 17.15C.
- The heat has been felt globally, with 63 countries experiencing their warmest June on record. Over the past 12 months, a staggering 138 countries have recorded their hottest temperatures ever.
- July 2024 is very likely to be the first time in 13 months without a new record, coming in cooler than July 2023. However, it will still be more than 0.2C warmer than any July prior to 2023.
- With El Niño fading and modest La Niña conditions potentially developing later this year, it is unlikely that the extreme monthly temperature records set in the second half of 2023 will be surpassed in 2024.
- Antarctic sea ice extent has fallen to near 2023’s record lows in recent weeks, reflecting the broader trend of polar sea ice loss.
Record warm first half of the year
Global temperatures set a new record for each of the first six months of 2024, extending what was already a string of seven record setting months in 2023.
All in all, each of the last 13 months has been the warmest since records began in the mid-1850s.
The figure below shows how global temperature so far in 2024 (purple line) compares to each month in different years since 1940 (with lines coloured by the decade in which they occurred) in the Copernicus/ECMWF ERA5 surface temperature dataset.

Temperatures for each month from 1940 to 2024 from Copernicus/ECMWF ERA5. Anomalies plotted with respect to a 1850-1900 baseline. Chart by Carbon Brief.
Global temperatures in the latter half of 2023 exceeded prior records by at least 0.3C, peaking in September when 2023 surpassed the previous September record by 0.5C. While 2024 has continued to set records, the margins have been smaller:
- January to April 2024: About 0.1C above previous records (set in 2016)
- May 2024: About 0.2C above the previous record (set in 2020)
- June 2024: About 0.15C above the previous record (set in 2023)
It is important to note that June 2024 is being compared to the already high temperatures set in 2023. Compared to the last major El Niño event in 2016, June 2024 was about 0.4C warmer.
The figure below shows the margin by which global temperatures were set in each of the prior 13 record-setting months.

Margin by which new monthly temperature records have been set over the past 13 months. Using data from Copernicus/ECMWF ERA5. Chart by Carbon Brief.
In this latest quarterly state of the climate assessment, Carbon Brief analyses records from five different research groups that report global surface temperature records: NASA, NOAA, Met Office Hadley Centre/UEA, Berkeley Earth and Copernicus/ECMWF.
The figure below shows the annual temperatures from each of these groups since 1970, along with the average over the first six months of 2024. (Note: at the time of writing, June data was not yet available for the Hadley/UEA record.)

Annual global mean surface temperatures from NASA GISTEMP, NOAA GlobalTemp, Hadley/UEA HadCRUT5, Berkeley Earth and Copernicus/ECMWF (lines), along with 2024 temperatures so far (January-June, coloured dots). Anomalies plotted with respect to the 1981-2010 period, and shown relative to pre-industrial based on the average pre-industrial temperatures in the Hadley/UEA, NOAA and Berkeley datasets that extend back to 1850. Chart by Carbon Brief.
The globe, as a whole, has warmed more than 1C since 1970, with strong agreement between different global temperature records. However, there are larger differences between temperature records further back in time (particularly pre-1900) due to sparser observations and a resulting greater sensitivity to how gaps between measurements are filled in.
All show that the average global temperature for 2024 so far is higher than any prior annual record. However, annual temperatures may end up being a bit lower than those of the first six months of the year, as El Niño conditions have faded and a mild La Niña event is likely to develop later in the year.
The last two years – 2023 and 2024 – stand out as substantially warmer than any prior year in the temperature record. The chart below shows a heat map of daily global average temperatures in the Copernicus/ECMWF ERA5 dataset, with temperatures shown by colours ranging from blue (-2C) to red (+2C), with the pre-industrial average (1850-1900) set to 0C. The figure below shows each day since 1940 in the dataset.

A summer of temperature extremes
While global average surface temperature changes are an important indicator of long-term climate change, any month or year will have important regional warm or cool patterns in different parts of the world.
June 2024 saw particularly warm temperatures over much of South America, the southern US and Mexico, northern Africa, western Europe, central Asia and the Middle East among other regions.
The figure below shows the difference between temperatures in June 2024 and the baseline period of 1951-80, taken from Berkeley Earth (using their high-resolution temperature dataset). Red, orange and yellow shading indicate areas that have been warmer than average, while blue shows areas that have been cooler.

In total, 63 countries, mostly in Africa and South America, had their warmest national-average June on record. These included Brazil, Bulgaria, Cambodia, Colombia, Egypt, Ethiopia, Ghana, Greece, Israel, Ivory Coast, Jordan, Kenya, Lebanon, Libya, Nepal, Romania, Saudi Arabia, Somalia, South Africa, South Korea, Sudan, Syria, Turkey, Venezuela and Yemen.
The figure below shows which portions of the Earth’s surface experienced record high temperatures (deep red shading) in June 2024. It is noteworthy that almost no location on the planet experienced record cold temperatures.

Zooming out to the past 12 months (July 2023 to June 2024), 138 countries saw all-time records broken. This includes much of Central and South America, Canada, Africa, Europe, China, the Middle East and south-east Asia. Only an anomalous patch of east Antarctica saw record cold temperatures.

Very likely to be the warmest year on record
With half the year of data now available, Carbon Brief has determined that there is now an approximately 95% chance that 2024 will beat 2023 and be the warmest year on record, based on Copernicus/ECMWF’s ERA5 dataset. (Berkeley Earth separately estimated a 92% chance in their June update.)
By looking at the relationship between the first six months and the annual temperatures for every year since 1970 – as well as El Niño-Southern Oscillation conditions for the first six months of the year and projections for the remaining nine months – Carbon Brief has created a projection of what the final global average temperature for 2024 will likely turn out to be.
The analysis includes the estimated uncertainty in 2024 outcomes, given that temperatures from only the first half of the year are available so far.
The chart below shows the expected range of 2024 temperatures using the Copernicus/ECMWF global atmospheric reanalysis product (ERA5) – including a best-estimate (red) and year-to-date value (yellow). Temperatures are shown with respect to the pre-industrial baseline period (1850-1900).

Annual global average surface temperature anomalies from the Copernicus/ECMWF global atmospheric reanalysis product (ERA5) plotted with respect to a 1850-1900 baseline. To-date 2024 values include January-June. The estimated 2024 annual value is based on the relationship between the January-June temperatures and annual temperatures between 1970 and 2023. Chart by Carbon Brief.
Carbon Brief’s projection suggests that 2024 is very likely to be the warmest year on record, with a central estimate of 1.57C.
This is true even if – as the projection implicitly assumes – the remaining months in 2024 are below the records set in 2023. Because the first six months of the year were so warm – around 1.63C above pre-industrial levels – the second half of the year would have to be relatively cool (below 1.3C) for the year as a whole to not exceed 2023.
It is worth repeating that an individual year hitting 1.5C above pre-industrial levels is not equivalent to the 1.5C limit within the Paris Agreement. This limit refers to long-term warming, rather than an individual year that includes the short-term influence of natural fluctuations in the climate, such as El Niño. Even including data through to the present day, long-term global temperatures (excluding year-to-year variability) are unlikely to exceed 1.5C until the late 2020s or early 2030s.
The figure below shows Carbon Brief’s estimate of 2024 temperatures using ERA5, both at the beginning of the year and once each month’s data has come in. The central estimate remained relatively unchanged until June, after which it increased a bit as the month turned out a bit warmer than the model anticipated. The uncertainty has diminished with each additional month of data, as there are fewer remaining months in 2024 to substantially change the results.

Carbon Brief’s projection of global temperatures at the start of the year, and after January, February, March, April, May, and June ERA5 data became available. Chart by Carbon Brief.
There is reason to expect that global temperature anomalies will modestly decline over the remainder of the year as El Niño fades away and moderate La Niña conditions potentially develop. The figure below shows a range of different forecast models for ENSO for the rest of this year, produced by different scientific groups. The values shown are sea surface temperature variations in the tropical Pacific – the El Niño 3.4 region – for overlapping three-month periods.

There is a mix of projections across models, with many of the dynamical models expecting very modest La Niña conditions (<-0.5C Niño 3.4 sea surface temperature – SST – anomaly) to develop by October, while most of the statistical models expect ENSO-neutral conditions to persist.
July on track to end the record monthly streak
Global surface temperatures have set a 13-month streak of monthly records from June 2023 and June 2024. However, with more than two thirds of July temperature now available, it is looking increasingly likely that July 2024 will break that streak, coming in as the second warmest on record after July 2023.
The figure below shows daily temperature anomalies from the Copernicus/ECMWF ERA5 record for 2024 (purple line), 2023 (red line) and 1940-2022 (grey lines). It highlights that July 2024 has been at or below 2023 temperatures for all but the past few days.

Daily global temperature anomalies from 1940 to present (22 July 2024) from Copernicus/ECMWF ERA5, with daily values for each year plotted as a separate line. The colours indicate 2024 (purple), 2023 (red) and all other years (grey). Anomalies plotted with respect to a 1850-1900 baseline. Chart by Carbon Brief.
Current global temperature anomalies are back in record territory as of 22 July, at around 1.7C above pre-industrial levels.
This is still well below the anomalies of 2C or more briefly hit in late 2023 and early 2024. However, because the current temperature anomalies align with the warmest week of the year for global surface temperatures, they have resulted in a new record for absolute global temperatures. This is shown in the figure below, which features daily absolute global temperatures from the Copernicus/ECMWF ERA5.

Daily global absolute temperatures from 1940 to present (22 July 2024) from Copernicus/ECMWF ERA5, with daily values for each year plotted as a separate line. The colours indicate 2024 (purple), 2023 (red) and all other years (grey). Chart by Carbon Brief.
The prior daily absolute temperature record was 17.08C, set in early July 2023. This was exceeded both by 22 July (at 17.09C) and 22 July (at 17.15C).
While these daily absolute temperature records are not that climatically meaningful (and are only available in reanalysis data) – anomalies give a better sense of actual changes that are occurring – they nonetheless represent a symbolic milestone.
To determine where July 2024 temperatures will ultimately end up, Carbon Brief used a statistical model that extrapolates the final monthly temperatures based on the first 22 days of the month in all prior Julys since the ERA5 record began in 1940.
The figure below shows the expected range of July 2024 temperatures (black error bars) alongside a best-estimate (red diamond). Temperatures are shown with respect to the pre-industrial baseline period (1850-1900).

July global average surface temperature anomalies from the Copernicus/ECMWF global atmospheric reanalysis product (ERA5) plotted with respect to a 1850-1900 baseline. The estimated 2024 July value is based on the relationship between the first 21 days of the month and the final monthly temperatures between 1940 and 2023. Chart by Carbon Brief.
Here, Carbon Brief estimates that there is a very likely (>95%) chance that July 2024 comes in as the second-warmest July on record after 2023. However, it will still be quite warm, at more than 0.2C warmer than any July prior to 2023.
The extreme heat the world experienced in the latter half of 2023 makes setting new records over the remainder of the year less likely.
Low Antarctic sea ice extent
Antarctic sea ice extent spent much of early 2024 at the low end of the historical 1979-2010 range, though it has not quite exceeded record lows experienced in 2023.
However, in recent weeks Antarctic sea ice extent has rapidly dropped, and is now only modestly above 2023 levels.
Arctic sea ice extent has also spent most of this year at the low end of the historical range.
The figure below shows both Arctic and Antarctic sea ice extent in 2024 (solid red and blue lines), the historical range in the record between 1979 and 2010 (shaded areas) and the record lows (dotted black line). Unlike global temperature records (which only report monthly averages), sea ice data is collected and updated on a daily basis, allowing sea ice extent to be viewed up to the present.

Arctic and Antarctic daily sea ice extent from the US National Snow and Ice Data Center. The bold lines show daily 2024 values, the shaded area indicates the two standard deviation range in historical values between 1979 and 2010. The dotted black lines show the record lows for each pole. Chart by Carbon Brief.


The post State of the climate: 2024 now very likely to be warmest year on record appeared first on Carbon Brief.
State of the climate: 2024 now very likely to be warmest year on record

Anne Jellema is executive director of 350.org; Mads Christensen is executive director of Greenpeace International; and Amitabh Behar is executive director of Oxfam International.
On Monday, global petitions with a collective total of more than 2 million signatures were presented to the United Nations, calling on governments to introduce binding mechanisms to make fossil-fuel companies and the super-rich contribute to the costs of the damage they have created.
The petition signatures were received by Selwin Hart, the UN Assistant Secretary-General for Climate Action, in New York during the UN General Assembly, sending a clear message to governments: there is no more room for excuses.
If governments are serious about resilience, energy security and protecting people from an increasingly unstable world, they must make the companies profiting from the fossil-fuel economy pay their fair share. Because the crisis we are facing is no longer some distant threat. It is unfolding in real time, and it is exposing the extraordinary costs of an economy still built around fossil fuels.
-
Climate change and energy transition rise up national security agenda
Leaders highlighted the national security risks posed by global warming and fossil fuel dependency at New York Climate Week -
COP31 presidency announces AI pledge as UN climate chief says Big Tech ‘on thin ice’
Turkish minister Murat Kurum said AI companies should be transparent about their energy use and power their data centres with clean energy
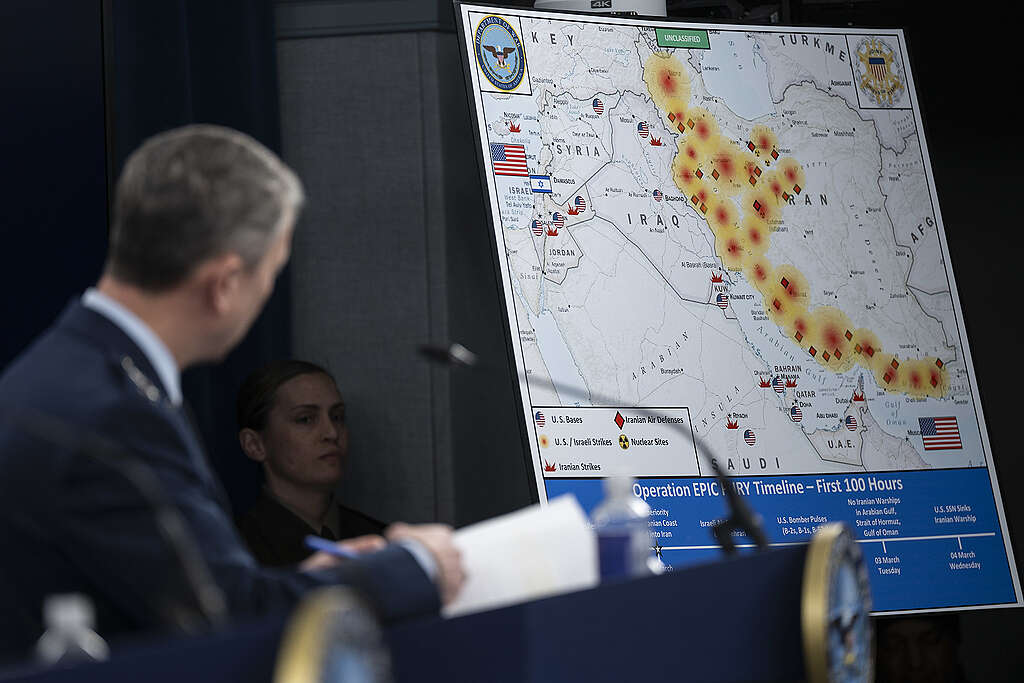
For more than six months, the Strait of Hormuz, the channel through which a fifth of the world’s oil once flowed without a second thought, has been closed, contested or effectively unusable. Tankers sit at anchor. Insurance premiums have gone through the roof. Petrol pumps from Los Angeles to Lagos have felt the tremor. It has taken a war to remind the world just how much of our daily lives still rests on a single, fragile artery of fossil fuels.
At the other end of the same emergency, a glacier came down on the Nepal–China border in the last week of August. A wall of ice, rock and water tore through the Bhote Koshi and Langtang valleys. It has been described as one of the deadliest disasters in the region’s modern history, unfolding in a landscape where the world’s glaciers are retreating and destabilising at a pace scientists have been warning about for years.
And this came only weeks after hundreds of thousands of people were displaced — not by ice, but by fire. Europe has experienced its worst wildfire season in more than a decade. Homes have been lost across Spain, Portugal, France, Greece and the UK. Firefighters and civilians have been killed battling the blazes, while damage and reconstruction costs continue to reach extraordinary levels.
These are not separate crises. They are different expressions of a world becoming more volatile, while the fossil-fuel economy continues to generate enormous profits for those at the top and pushes the costs onto everyone else.
Communities absorbing cost
Because the crisis we are facing is no longer some distant threat. It is unfolding in real time, and it is exposing the extraordinary costs of an economy still built around fossil fuels. One thread runs through all of these events: a global economy still organised around the profits of a fossil fuel industry that has known, for decades, exactly what it was doing to the planet.
At a moment when governments are gathering in New York for the UN General Assembly to talk about security, resilience and economic competitiveness, it is worth spelling out what “security” – or the lack of it, driven by our economy’s dependence on oil – actually means this year for ordinary people around the world: 35,000 excess deaths in Europe due to heat; the highest food prices in three and a half years; $700 billion in economic losses, threatening countless jobs and livelihoods, from a war and a closed oil chokepoint whose consequences are nowhere near over.
Meanwhile the companies that extracted, refined, shipped and sold the fuel behind all of this continue to report extraordinary profits. Households are paying more for energy. Governments are spending billions on disaster response, on reconstruction, on emergency deployments of firefighters and aid. Communities are absorbing the cost of a system they didn’t design and don’t control. We pay. They profit.
This is not a coincidence, and it is not inevitable. It is a political choice, repeated year after year, to let the companies most responsible for the climate crisis hoard the wealth they generate while the rest of us carry the risk.
Taxes and fines needed
That is why, together with communities and campaigners in dozens of countries have spent the last three years building the case for a simple, overdue idea: polluters should pay for the damage they have caused. Not through voluntary pledges or distant net-zero promises, but through binding mechanisms, climate damages taxes, surtaxes on fossil fuel profits, and fines ring-fenced for recovery and adaptation that put real money where the harm actually is. This is how we take the profit out of destruction and protect the generations to come.
The response has told us we are not alone in thinking this. Our petitions calling on governments to make polluters pay have now gathered a collective total of over 2 million signatures from people across every region of the world.
The case for making polluters pay has moved into the mainstream
That is not a fringe demand. It is what happens when people watch a choke-point war spike their fuel bill, watch a glacier take a thousand lives, watch their own summer holidays rearranged by fire. They draw the obvious conclusion: the people who caused this should be paying for it – not profiting from it.
We hear the objection already forming: that this is not the moment, with wars underway and economies fragmenting, to burden industry further. We would say the opposite is true. If governments can mobilise trillions for war, for bailouts and for new fossil fuel infrastructure, they can mobilise the political will to tax the companies that caused this crisis.
Money for clean energy and resilience
That money can go straight to the people paying for it, through cheaper, cleaner, more secure energy, and through funding for communities on the frontline of floods, fires and glacial collapse. There isn’t an excuse left. There is only a choice about where power and money go next. Every dollar we don’t spend now on adaptation, resilience and cutting emissions, we burn many times over later: on disasters we could have prevented and economies we scramble to fix too late.
This year’s UNGA should be the moment that choice gets made in public. Governments arriving in New York will talk about resilience, about energy security, about protecting their citizens from an unstable world. Let them explain on the record why a fossil fuel industry that has spent decades profiting from that instability should not be the one paying to fix it so wrecking the planet no longer pays off.
The fires, floods and storms won’t just go away. The system that keeps producing these disasters, and keeps paying the same companies for the privilege, will not change itself unless political leaders step up. It is on all of us to make sure they hear, as loudly as possible, that the time for excuses has run out.
The post After Hormuz, Nepal and wildfires, people demand action to make polluters pay appeared first on Climate Home News.
After Hormuz, Nepal and wildfires, people want action to make polluters pay
(and why it matters for the Global Plastics Treaty)
Originally posted by Greenpeace International.
The gravest consequences of the war are borne by people in Iran and across the region: lives lost, families displaced and essential infrastructure damaged. Its fossil fuel shock has also carried economic consequences far beyond the battlefield.
The war on Iran triggered an oil market crisis that sent shockwaves far and wide, and some consequences are still unfolding. Impacts rippled beyond energy and transport into shops and supermarkets, pharmacies and homes. People everywhere are still paying.
Nearly everything we buy, from shampoo bottles to strawberry packaging, is made from or with petrochemicals, wrapped in plastic, or both. But it does not have to be, and most people do not want it to be.
The war exposed a hidden risk in the plastics economy. Plastic depends on fossil fuel feedstocks and global petrochemical supply chains. When oil and gas supplies are disrupted, the cost and availability of packaging, medical supplies and everyday goods are disrupted too. Households, public services and communities ultimately pay.
The war has changed the terms of the debate around the Global Plastics Treaty. It has revealed the real costs of being tethered to the plastics supply chain. At the next round of treaty negotiations, governments have a choice. They can lock in deeper vulnerability to future price and supply shocks, or build economies resilient enough to withstand them.
Here are six things the conflict has shown us.
1. Plastic supply chains are vulnerable to fossil fuel shocks
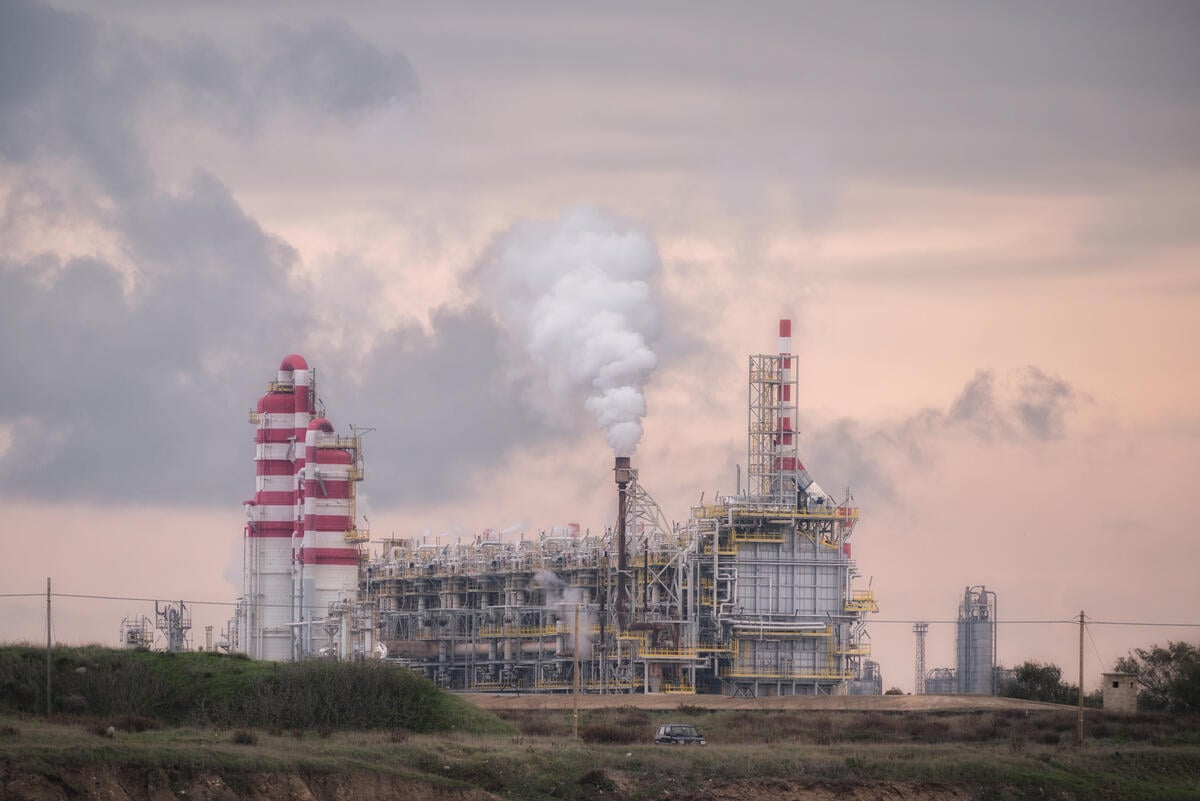
The war disrupted plastic production, imports, and exports at once, sending costs soaring worldwide. Formosa Petrochemical Corp (FPCC), one of the world’s largest plastic producers, was forced to declare force majeure. This is a legal term meaning it could not meet contractual obligations because of circumstances beyond its control.
In Japan, polyethylene production, a plastic widely used in shopping bags and packaging, reportedly fell 62% in March. Shortages then spread from factories to supermarket shelves.
The fallout reached beyond supply chains to hospitals, where South Korea had toban the hoarding of medical syringes. It reached household cupboards, where the price of body wash reportedly climbed 7.7% in a matter of weeks. It also reached children’s toy boxes. A US-based soft-toy manufacturer said its supplier in China had cited material cost increases of 10% to 15% within three weeks of the war starting.
Petrochemicals go into more than 6,000 everyday products, according to the US Department of Energy. The question is not whether every one of these products can change overnight. It is how many uses can be reduced, redesigned or replaced with safer, non-fossil-fuel alternatives.
2. The crisis created winners and losers
This conflict revealed new pressure points for countries whose industries depend heavily on plastics and petrochemical feedstocks. According to South Korean media, naphtha import prices rose 68% in a single month, while small and medium-sized manufacturers reported material shortages and cost increases of more than 20%.
As some producers were forced to scale back, China saw the conflict as a way to move beyond years of oversupply and low margins. Its own efforts to curb destructive overcapacity and price competition had struggled to resolve this problem. It increased exports to Asian markets, used accumulated inventory, ramped up idle capacity and absorbed demand left by disrupted competitors. One industry analyst has described this as a potentially lasting shift in market share.
Meanwhile, the US turned the same crisis into a windfall. Ethane-fed plants were less exposed to disruption at the Strait of Hormuz and kept input costs lower even as global prices climbed. Producers raised prices as markets tightened.Dow raised North American polyethylene prices by 10 cents a pound in March, then 15 cents in April, before doubling that increase days later. Another increase was announced in August.
LyondellBasell said its second-quarter earnings, excluding unusual items, rose nearly 600% year on year to US$1.4bn. Dow swung from a loss to a profitwithin a few quarters of the war’s start. This was not simply a story of market adjustment. Companies with less exposure to naphtha supply disruptions were better positioned to profit while producers and communities elsewhere absorbed the risks.
The benefits and harms of the petrochemical economy are not distributed fairly. Communities near extraction, refining and petrochemical facilities often carry pollution and health burdens, while countries dependent on imported fuel and feedstocks are exposed to prices they cannot control.
3. Households, public services and communities bear the costs

According to NielsenIQ data reported by Reuters, grocery prices in the US rose 2.9% year on year in the four weeks from the start of the war to 28 March. The same data showed bottled-water prices rising 5.8%, while nappies, pads and tampons, all of which contain plastics, rose by between 2% and 6%. School lunchboxes rose by more than 26%, the biggest increase of any school item, according to retail data.
Synthetic footwear could also become more expensive. With roughly 70% of synthetic shoe materials derived from petrochemicals, industry analysts project prices could rise by another 1.5% to 3% by late summer and autumn.
In Taiwan, the price of a basic plastic bag more than doubled, and Costco reportedly had to ration the number of food storage bags a single customer could buy. Companies and governments made the decisions that left economies exposed to this crisis, but it was ordinary people who paid for it. They paid through petrol, public transport, food, household goods and essential supplies.
The impacts are not shared equally. Lower-income households, small businesses, informal workers and countries reliant on imported fossil fuels and petrochemical feedstocks have far less room to absorb higher costs or shortages of essential goods.
4. Some governments are choosing reuse and resilience
In March, just weeks into the conflict, South Korea’s president, Lee Jae Myung, told his cabinet that the country’s deep reliance on petrochemicals made it difficult to predict where the next disruption would hit. He warned it ‘poses a serious threat to people’s daily lives’.
By April, he had moved from emergency response to longer-term reform, calling for a ‘plastics-free economy’. Taiwan’s government expanded reuse infrastructure to build a more resilient economy and reduce exposure to market fluctuations.
The lesson is not that scarcity or rationing is desirable. It is that planned, publicly supported reuse and reduction systems can protect people better than an economy dependent on volatile virgin plastic supply chains.
The question is whether enough governments act in time to avoid the next shockwave.
5. Reuse and reduction can work at scale

Industry has long argued that plastic is too convenient, too cheap and too embedded in everyday life to be meaningfully cut back. But when Taiwan’s plastic bags suddenly became scarce, the country continued to function. Retailers adjusted, the government expanded reuse programmes, and people brought their own bags.
As virgin plastic prices climbed, French retailer Carrefour committed to removing 5,000 tonnes of plastic from its packaging through refill formats and packaging reductions. It said it would pass the savings on to customers through lower prices.
This does not mean responsibility should fall on individuals. It means governments and businesses can build systems that make reuse, refill and less packaging easy, accessible and affordable.
Single-use plastic is embedded in retail systems, but it is not as indispensable as the industry claims. Cutting back is possible, and it can reduce costs as well as pollution.
6. Without structural change, the next shock is inevitable
The conflict is not over, and even when it is, disruptions will come again. A similar pattern played out in 2021, when the Ever Given blocked the Suez Canal for six days, disrupting global trade and adding to existing pressures on plastics supply chains.
Exposure is also set to grow. The IEA predicts that plastics and petrochemicals are on track to become the single largest driver of growth in global oil demand through 2050.
Plastic producers are not separate from the fossil fuel economy. Petrochemicals are made from fossil fuel feedstocks, so continued growth in virgin plastic production deepens demand for oil and gas. It also locks communities and economies into exposure to future price shocks.
At the next round of Global Plastics Treaty negotiations, governments have a critical opportunity to cut dependence on fossil fuels, reduce the health harms caused by plastics and build systems more resilient to the next disruption.
A binding treaty that meaningfully cuts plastic production is not only a win for public health, ecosystems and the climate. It could be a turning point for economic security, geopolitical stability and the resilience of the systems we all depend on.
A Global Plastics Treaty can help break the cycle
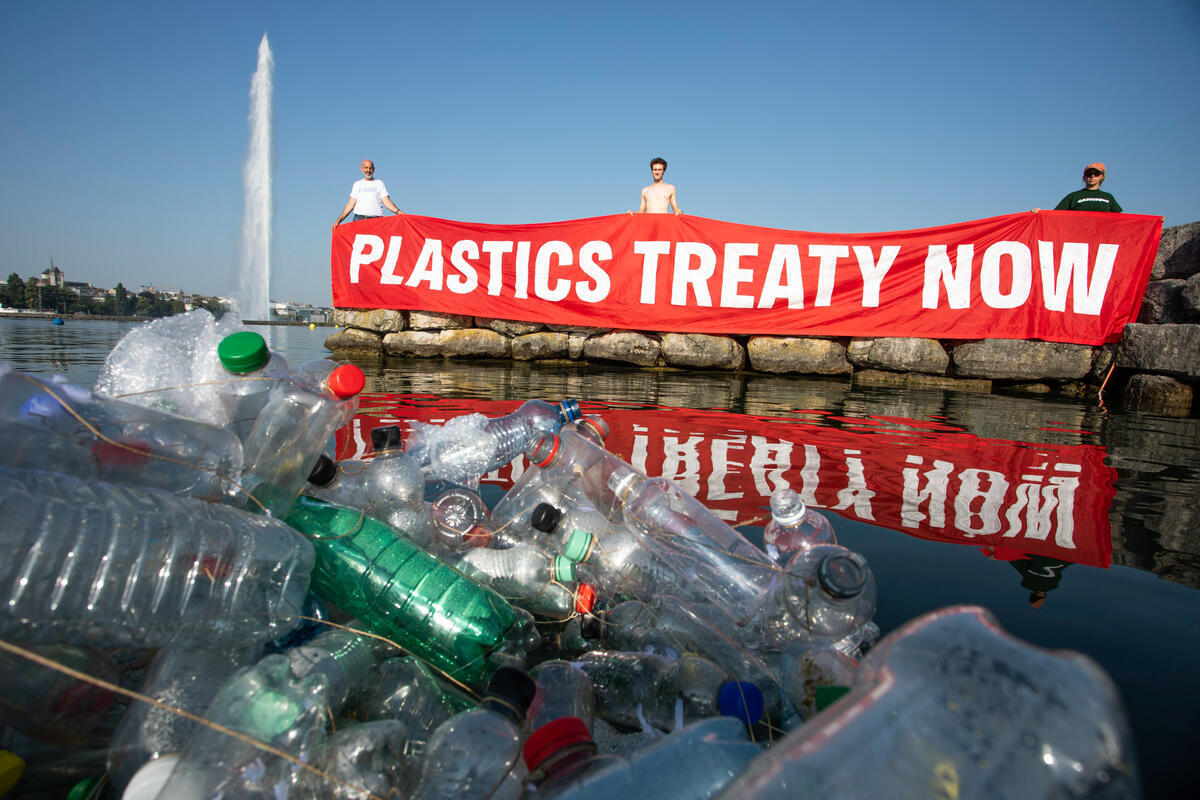
The lesson of the war on Iran is not that people should learn to live with shortages. It is that economies built around fossil fuels and ever-growing virgin plastic production are exposed to shocks they cannot control.
A strong, binding Global Plastics Treaty can help change that. By cutting plastic production, expanding accessible reuse systems and supporting a just transition away from fossil fuel dependence, governments can reduce pollution and help protect people from the next price shock.
Governments should protect people now while reducing future exposure. They should support reuse systems, invest in accessible refill and public services, and shift public investment away from fossil fuel and petrochemical expansion.
The people and communities least responsible for this system should not be the ones left paying for it. Governments must put public wellbeing, resilience and a liveable future ahead of the profits of fossil fuel and petrochemical companies.
For a more in-depth analysis, read our brief.
Lindsey Jurca is a Senior Plastics Campaigner at Greenpeace USA.
Governments need to start addressing climate change impacts and nature loss as a threat to national security and manage shocks before they hit rather than picking up the pieces afterwards, Britain’s foreign minister and other leaders told the opening of Climate Week NYC on Monday.
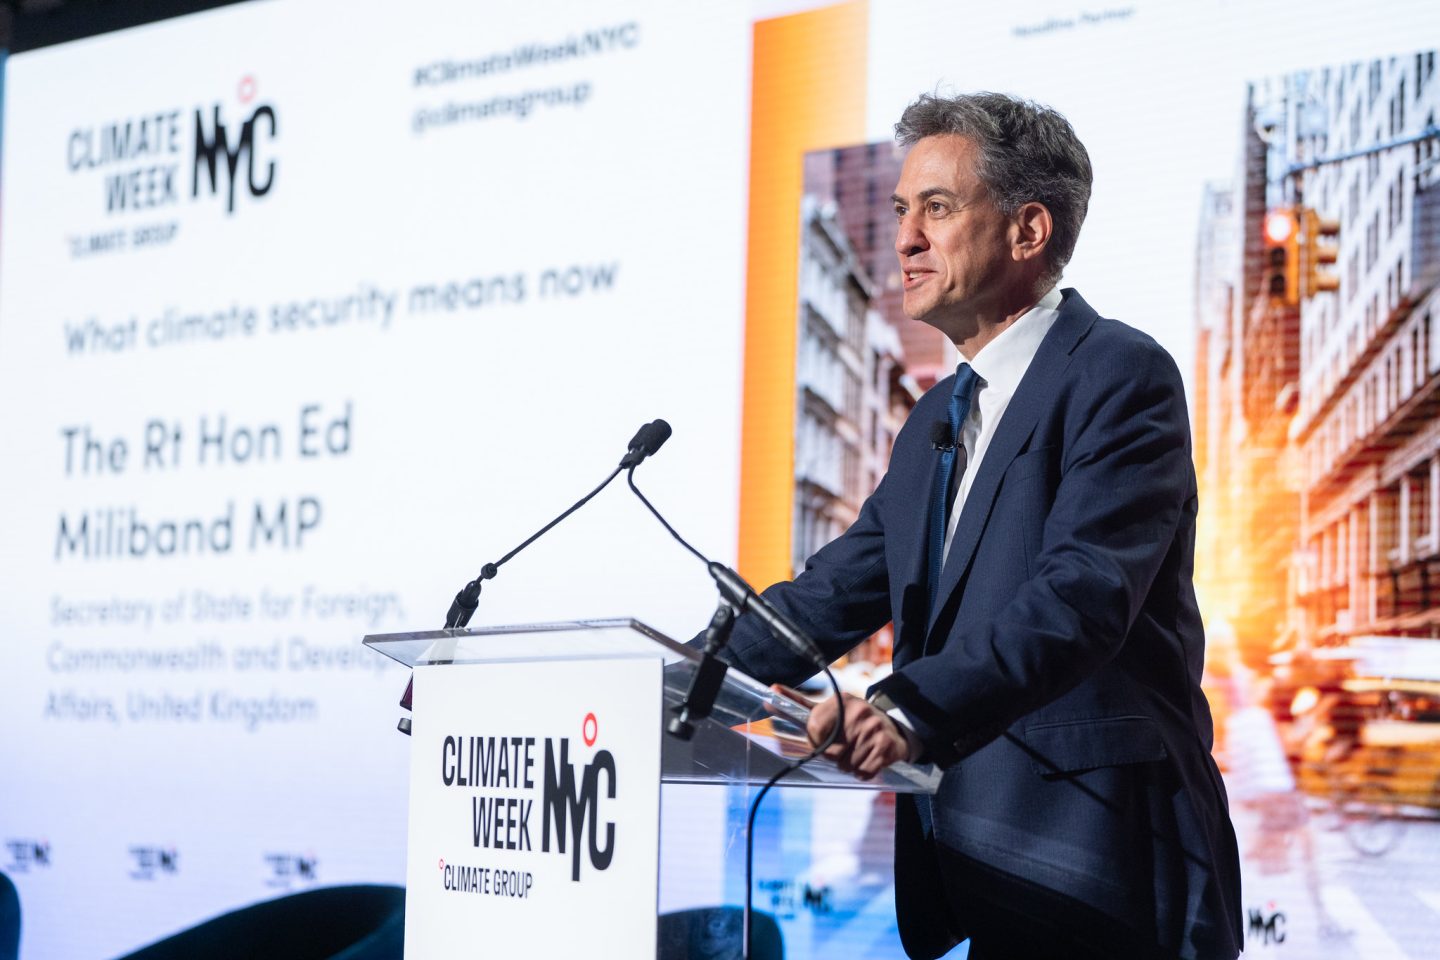
Ed Miliband – who was until July the UK’s energy minister – said the growing urgency and severity of extreme weather and related disasters require a shift in thinking, calling on governments to put the issues “front and centre”.
“Climate breakdown, in my view, must be an issue for foreign ministers and prime ministers, as well as energy and climate ministers – the security community, not just the activist community, the generals, not just the green campaigner,” he told an audience of policy and business leaders.
There is a need to assess risk differently, he added, by embedding climate and nature in national security systems, threat assessments and contingency planning. He also urged countries to pool information because climate shocks can travel fast through supply chains as well as influencing financial markets and migration patterns.
The framing of climate change as a threat to countries’ security and stability is not new, but it has gained greater emphasis as the impacts of global warming are biting harder in places like Europe, which is struggling with more intense heatwaves, drought and forest fires.
In mid-August, Miliband said in a social media post, reflecting on the UK’s hot and dry summer, that he would convene foreign ministers attending the UN General Assembly in late September to discuss how to respond to “this new national security threat” and build a coalition for action. But he did not give further details of that initiative on Monday.
-
Fossil fuel expansion threatens COP31 hosts’ credibility, experts warn
Türkiye and Australia are pushing coal, oil and gas at home with no national timeline for their own fossil fuel phase-out -
DR Congo’s power-hungry mining sector drives record solar surge
As solar deployment rapidly accelerates across Africa, miners in the DRC are driving significant demand for clean energy to replace expensive diesel
Australia calls for unified response
Other leaders in New York also reflected on the growing threat to their societies and economies from climate change impacts and exposure to volatile fossil fuel markets.
Australian Prime Minister Anthony Albanese said his country “understands the dangers of global warming and the urgency of climate action as well as any nation”.
“We have seen it up close – from increasingly intense bushfires and floods, to the damage warming oceans are wreaking on our vulnerable coastlines,” he said in a speech, adding that with a record-breaking El Nino forecast, Australia and Pacific nations are preparing for a potential summer of extreme heat, bushfires and floods.
With scientific forecasts of worsening impacts now coming to pass, “this means the global community cannot afford to be frozen in time as the world warms around us”, he added. People cannot be left to cope alone, he said, emphasising that as leaders, “we need to come together, to meet the problem head on”.
Australia will lead the negotiations at the upcoming COP31 climate summit, and has brought the existential threat to Pacific countries from sea level rise into the diplomatic limelight. The pre-COP gathering next month will be hosted in Fiji, with a visit by leaders to Tuvalu.
Speaking to Climate Home News in New York, Panama’s environment minister Juan Carlos Navarro said the small Central American country faces hundreds of millions of dollars in losses from drought in the Panama Canal due to El Niño.
The Panama Canal Authority estimates income could be reduced by between $225 million and $400 million due to slower maritime traffic passing through the strait.
“What a great irony,” Navarro said. “Panama being a small, carbon-negative country pays the price for the big carbon-emitting countries.”
Climate investment “critical” to stability
Amina J. Mohammed, deputy secretary-general of the United Nations, said there was a need for countries to stick with multilateral approaches to problems including climate change, despite the difficult geopolitical times the world is going through. She added, however, that it “does require your voices. It won’t happen by itself. We have to lean into it.”
The rest of the high-level UNGA week in New York will show the extent to which multilateral efforts to resolve the world’s problems – from climate change to poverty – have top-level support as leaders give their speeches, including the Brazilian and US presidents on Tuesday.
Kaysie Brown, associate director for climate diplomacy and geopolitics with think-tank E3G, said the statements by Miliband and other leaders at Climate Week NYC had underlined the political and government case to integrate climate considerations into security thinking and institutions at the highest level.
“In a world of escalating climate impacts and the record El Niño expected to heighten risks worldwide alongside energy volatility and geopolitical tensions, investing in global climate resilience and the clean energy transition are critical to credible strategies to enhance stability and national security,” she added in a statement.
Suneeta Kaimal from the Natural Resource Governance Initiative (NRGI) said that, while in previous years governments heavily focused their speeches on climate action, this year’s focus on energy security does not change the underlying challenge.
“The fact that the framing has changed from energy transition to energy security doesn’t change the reality that this transition needs to occur in energy systems. It’s just a different framework. It’s a more transactional framework, but it all points to the need for resilience,” she said.
Speaking at the opening session of Climate Week, Iceland’s Prime Minister Kristrún Frostadóttir described how her country had reacted to the spiralling costs it faced from the 1970s oil price crisis by investing in a large-scale district heating system fuelled instead by its abundant geothermal energy.
“Resilience wasn’t built while the crisis was happening. It was built in the years after – deliberately, patiently, as a national mission – so that the next shock wouldn’t hit as hard, if at all,” she said.
New COP goal on electrification
Speaking at a separate event on Monday, UN climate chief Simon Stiell pointed to a new voluntary target expected to be adopted at COP31 for 35% of global energy use to come from electricity by 2035 as a strategy that can help cushion countries, families and businesses from fossil fuel supply shocks and rising costs.
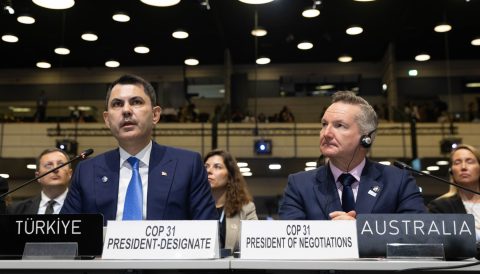
At the United Nations, the Turkish COP presidency gave more details of the electrification goal it first announced at the Bonn climate talks in June, including sharing with governments a final text of the pledge it wants them to get behind.
The pledge sets out a global ambition to advance electrification, highlighting the importance of supporting developing countries to identify their grid investment needs and access finance for electrification.
“It is a development strategy, an industrial strategy, a health strategy, and a security strategy,” Stiell said.
The post Climate change and energy transition rise up national security agenda appeared first on Climate Home News.
Climate change and energy transition rise up national security agenda



-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits