


The Voluntary Carbon Market (VCM) has been a vital tool for combating climate change, enabling organizations to offset emissions by funding projects that reduce or remove greenhouse gases (GHGs). Once viewed as a cornerstone for corporate sustainability efforts, the market is now at a critical juncture.
Challenges such as fraudulent practices, questionable project integrity, and waning buyer confidence have sparked concerns about its future. However, amid these setbacks lies an opportunity for transformation. Is the VCM truly on its last leg, or is it evolving to meet the demands of a more discerning global audience?
A Look Back: The Voluntary Carbon Market’s Evolution
What Are Carbon Credits?
Carbon credits represent the reduction or removal of one metric ton of CO₂-equivalent emissions. They are typically achieved through projects such as renewable energy, reforestation, and sustainable agriculture.
These credits are often purchased by companies to offset emissions they cannot reduce internally, allowing them to claim progress toward carbon neutrality.
The VCM differs fundamentally from compliance markets, which are regulated by governments and operate on a cap-and-trade basis. The unregulated nature of the VCM has allowed it to thrive, providing flexibility for buyers and enabling the development of innovative project categories. However, this lack of regulation has also led to vulnerabilities in accountability and standardization.
Exponential Market Growth and Who Drives It
From its origins as a niche market, the VCM has grown exponentially. By 2022, it was valued at $2 billion, driven by rising corporate commitments to net-zero targets.
Projections estimate the market could balloon to up to $25 billion by 2030, representing a 15-fold growth from its current size. This expansion has been fueled by increasing pressure on businesses to address climate change and the growing adoption of sustainability frameworks.

Initially, the VCM emerged as a voluntary alternative to compliance markets, allowing companies to take responsibility for emissions beyond regulated requirements. Over the years, major corporations like Microsoft, Google, and Starbucks have leveraged the VCM to achieve ambitious net-zero goals.
Key participants in the VCM include:
- Project Developers – These entities create carbon credits through verified environmental projects.
- Consumers – Private companies, governments, and individuals purchase credits to offset emissions.
- Retail Traders and Brokers – They bundle and market credits to buyers.
- Third-Party Verifiers – Organizations like Verra and Gold Standard ensure projects meet stringent standards for emissions reduction. These also include carbon rating agencies that provide more transparency and authenticity to carbon projects.
While plenty of companies operate in the VCM, some names stand out because of their major contributions to the space.
For example, Xpansiv operates the world’s largest voluntary carbon exchange through its CBL platform, offering transparent, efficient trading of carbon credits and renewable energy certificates. The platform connects over 1,000 verified projects and partners with major carbon standards like Verra and Gold Standard.
Xpansiv’s technology enables same-day settlement and reduces delivery risks, enhancing market accessibility and liquidity. It also bridges voluntary and compliance markets, facilitating products under programs like the Regional Greenhouse Gas Initiative (RGGI) and California Cap-and-Trade.
Another key player, Laconic Global, operates at the intersection of technology and the VCM, offering solutions that improve transparency and functionality. They utilize their proprietary SADAR Natural Capital Monetization (NCM) platform to provide real-time carbon market data, including live pricing, trade analysis, and portfolio valuation tools.
Finally, in the realm of carbon credit ratings, a London-based company, BeZero Carbon offers high specialization. It provides transparency and risk assessments for carbon markets through its BeZero Carbon Ratings. It evaluates the quality and risks of individual carbon credits, covering factors such as additionality, permanence, leakage, and policy risks.
These companies’ works are crucial to keeping the market alive and striving, despite mounting issues and challenges.
VCM’s Current Challenges and Setbacks
Integrity Under Scrutiny
The VCM has faced intense criticism for the questionable integrity of some projects. For example, certain REDD+ initiatives—aimed at reducing deforestation—have been accused of inflating baselines, leading to overestimated carbon savings. High-profile scandals, such as funds from Zimbabwe’s Kariba REDD+ project failing to reach local communities, have further eroded trust.
This scrutiny has translated into financial losses. In 2023, transaction volumes dropped by 56% from the previous year, and the market’s value plummeted to $723 million—a stark contrast to its 2021 peak of $2 billion.
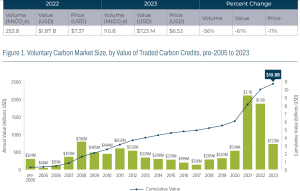
In effect, average credit prices fell to $6.53 per ton, a decline that reflects reduced buyer confidence. The chart below shows dampened market sentiment since 2021 when criticisms began, with number of credits demanded (retired) and produced (issued) decreased.
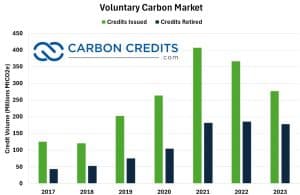
Media coverage has amplified the market’s vulnerabilities, highlighting instances of greenwashing and low-quality credits. This negative attention has deterred corporate buyers, many of whom fear accusations of insincere climate action. Companies are increasingly seeking transparency and accountability in the credits they purchase, placing additional pressure on the VCM to reform.
Signs of Recovery: Building a Stronger Market
Better Standards, Better Confidence
Despite these challenges, the VCM is evolving. The introduction of integrity frameworks such as the Core Carbon Principles by the Integrity Council for the Voluntary Carbon Market (ICVCM) and the Claims Code by the Voluntary Carbon Markets Integrity Initiative (VCMI) aim to restore buyer confidence.
These initiatives emphasize project transparency, robust verification processes, and adherence to high environmental and social standards.
Standards organizations are addressing past shortcomings. Verra, for example, introduced revised baseline calculations for REDD+ projects in 2023, aimed at resolving overestimation issues. These updates signify a shift toward greater accuracy and accountability, which could help rebuild trust among stakeholders.
More Than Just Carbon: Focus on Co-Benefits
In 2023, 28% of VCM transactions involved projects offering co-benefits such as biodiversity conservation or alignment with Sustainable Development Goals (SDGs). This reflects a growing buyer preference for credits that deliver tangible environmental and social outcomes in addition to carbon reductions.
Why the VCM Still Matters
Amid all the setbacks, the long-term outlook for the VCM remains optimistic.
Echoing this outlook, Xpansiv’s COO Ben Stuart remarked that:
“Despite ongoing challenges in the Voluntary Carbon Market (VCM), recent indicators suggest continued growth and renewed signs of market confidence. Notably, total retirements have increased year-on-year from 2023 to 2024, signaling a steady commitment from existing participants and an increase in new stakeholders engaging with the market.”
He further noted that the VCM is gaining validation through various international frameworks, which is helping to address concerns about market integrity, highlighting:
Last month, at COP29, countries reached a landmark agreement on the adoption of Article 6.4… In parallel, the International Civil Aviation Organization (ICAO) has approved standards…At the national level, the VCM continues to gain traction, with countries such as South Africa, Japan, and Singapore incorporating the VCM into their domestic carbon schemes. These are renewed signs of market confidence…”
Projections indicate a compound annual growth rate (CAGR) of 31% from 2023 to 2028. Key drivers include global net-zero commitments, regulatory alignment under frameworks like the Paris Agreement, and technological advancements in carbon removal.
Technological innovations help the market bounce back as advanced data gathering and sophisticated technologies produce more transparent and reliable verification processes.
Carbon removal technologies, such as direct air capture, are gaining traction. These solutions, which physically extract CO₂ from the atmosphere, are increasingly favored for their clear and measurable impact.
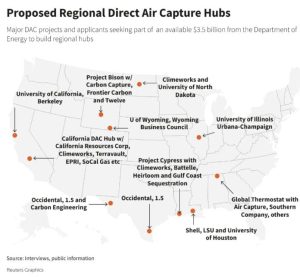
In 2023, removal credits commanded a 245% price premium over reduction credits, underscoring their value in meeting net-zero targets.
Emerging Trends in the VCM
Increased Demand for High-Quality Credits and Market Integration
Buyers are increasingly prioritizing quality over quantity, focusing on credits that are rigorously verified and offer co-benefits. The share of transactions from projects with co-benefits grew from 22% in 2022 to 28% in 2023, indicating a shift toward more impactful solutions.
Moreover, the VCM is becoming increasingly segmented, with distinct markets emerging for engineered solutions, nature-based projects, and co-benefit-driven initiatives. This differentiation allows buyers to tailor their investments to align with specific climate goals and organizational values.
More notably, as regulatory frameworks under Article 6 of the Paris Agreement are finalized, the boundaries between voluntary and compliance markets are becoming increasingly blurred. This integration offers opportunities for scaling the VCM while addressing systemic issues such as double counting and project accountability.
COP29: A Turning Point for Carbon Markets
The 2024 COP29 in Baku proved pivotal for the future of carbon markets, especially after the uncertainty surrounding the potential re-election of Donald Trump. Despite this looming challenge, the outcomes at COP29 gave a much-needed boost to the climate conversation, particularly following the disappointing results at COP28.
Progress on Article 6.2 and Article 6.4
Article 6 negotiations remained a focal point, with texts on both Article 6.2 and 6.4 evolving through the first week. After extensive deliberations, the final texts were ratified late on the second Saturday of the conference. These decisions provided much-needed clarity and a clear framework for the implementation of carbon markets, marking a significant step forward after COP28’s lack of progress.
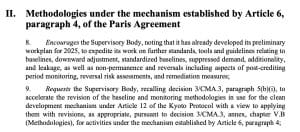
One of the most significant achievements was the establishment of clear rules for the transfer and tracking of carbon credits under Article 6.2. This mechanism, which allows for carbon credit trade between countries, is expected to drive substantial investment in climate action, particularly in developing nations.
A Historic Milestone for Carbon Markets
The final adoption of the Article 6 texts was hailed as a historic milestone for climate finance. These decisions provide developers, investors, and countries with much-needed certainty regarding how carbon credits are created and traded. The text’s adoption also set a path for the effective scaling of carbon markets, intending to contribute billions in funding for climate initiatives by the end of the decade.
Despite some pushback from carbon market skeptics, who argue that the system could provide a lifeline for the fossil fuel industry, the global community remains optimistic. The new rules aim to ensure greater transparency, reduce double counting, and enhance the accountability of carbon credits.
The next major milestone for Article 6 is expected in 2025 when the Supervisory Body for Article 6.4 meets to discuss further refinements. By then, the geopolitical landscape may have shifted, with a new US president potentially influencing the direction of international climate negotiations.
According to some accounts, 2025 will be the “moment of reckoning” for the VCM. Yet, given the past criticisms and current market challenges, the market has to overcome some major hurdles to move forward, as recommended by market experts.
Barriers to Address for Sustained Growth
- Regulatory Alignment: Clearer rules are needed to integrate voluntary and compliance markets seamlessly.
- Market Liquidity: Addressing the low liquidity of certain credit types is essential for maintaining market functionality.
- Trust and Transparency: Rebuilding buyer confidence through improved verification processes and independent oversight is crucial.
- Education: Buyers and the public need greater awareness of the nuances of carbon credits to combat misconceptions and rebuild trust.
Looking Ahead: Is the VCM Dead?
While the VCM has faced undeniable setbacks, it is far from dead. Instead, it is undergoing a critical transformation, driven by the need for enhanced quality and transparency. If integrity initiatives, gain traction, the VCM could emerge stronger and more impactful.
Tommy Ricketts, CEO and Co-Founder of BeZero Carbon, perfectly highlighted this, saying that:
“Carbon markets are restructuring after a turbulent couple of years. Carbon ratings, insurance, and accounting are working together to raise the bar for carbon credit quality…Market actors must recognize carbon credits for what they are: valuable but imperfect mechanisms to channel finance towards climate action. Bolstering the market for credits means buyers and market players must lean on the tools that exist to manage this risk.”
The market’s challenges underscore the importance of vigilance, innovation, and collaboration. As stakeholders refine frameworks and methodologies, the VCM holds the potential to bridge the gap between ambition and action, giving corporations and individuals the tools to fight climate change.
- FURTHER READING: COP29 Breakthrough: UN-Backed Global Carbon Market Takes Shape
The post Is the Voluntary Carbon Market Dead? appeared first on Carbon Credits.

Carbon credit providers vs marketplaces is the first comparison many buyers try to make. In this comparison, a carbon credit provider is the project developer: the company that originates credits from its own projects and sells them directly. A carbon credit marketplace is a platform that lists credits from many projects at published prices.

Carbon Footprint
Democrats who call climate change an emergency should not defend a permitting system too slow to build the clean energy that would address it.”
Democrats, Take The Deal. New York Times editorial, Nov. 12.
Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
CCC’s MRV and Additionality article explains the separate evidence questions a project reviewer will ask.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Sources
[1] GHG Protocol, Land Sector and Removals Standard, version 1.1, and companion Guidance, June 2026: https://ghgprotocol.org/land-sector-and-removals-standard ; https://ghgprotocol.org/land-sector-and-removals-guidance
[2] Science Based Targets initiative, Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, especially pp. 16–17, 37, and 41: https://sciencebasedtargets.org/resources/files/SBTiFLAGGuidance.pdf
[3] Accountability Framework initiative, Accountability Framework and guidance for companies: https://accountability-framework.org/
[4] GHG Protocol, Frequently Asked Questions: Land Sector and Removals Standard, questions 10 and 18: https://ghgprotocol.org/blog/frequently-asked-questions-land-sector-and-removals-lsr-standard

‘COP-out’: COP31 fails to deliver the ambition needed to phase out fossil fuels and address climate breakdown
COP31 Bulletin Day 13: New draft retains electrification goal but delays adaptation finance and science decisions

