

The year 2025 has seen exceptionally dry conditions in many parts of the UK.
At the time of writing, a large area of England is officially “in drought” and hosepipe bans are in force for more than 8m households.
This follows severe drought episodes in the summers of 2022 and 2018 – which raises the question of whether these events are part of a pattern towards a drier future.
However, the intervening periods between these drought events have been associated with major floods.
There is good reason to assume this “hydrological volatility” could be linked to climate change.
Writing for Carbon Brief in 2020, we explored how climate change might be impacting UK river flooding.
Here, we revisit this theme – but ask whether global warming is driving a long-term trend towards increasing drought severity in the UK.
To do so, we draw from the findings of a 2023 Environment Agency report, a chapter of which we authored and has now been accepted for publication in a peer-reviewed journal.
Key findings include:
- Future projections indicate hydrological droughts will become more severe in the UK, especially over the months of April to September, due to hotter, drier summers.
- However, observations from the past 50 years – and longer where records allow – do not provide evidence of worsening drought.
- This apparent conflict is largely because natural climate variability can obscure underlying trends driven by climate change.
- An increasingly variable climate in the UK means planners still need to prepare for more severe droughts, as well as more floods.
The 2025 hydrological drought
Droughts are complex events that vary in duration, time of year, location and severity.
They are often categorised into different types. For example, a meteorological drought is defined by a lack of rainfall – whereas agricultural drought is a period when there is not enough water for crops to grow.
Here, we are focusing on hydrological drought, which is when a lack of rainfall results in less water in streams, lakes, rivers and reservoirs.
In particular, we look at deficits in river flow. It is through dwindling river flows that droughts have some of their greatest impacts on society and the environment.
Over March-July of this year, flows for many UK rivers were at their lowest level on record. Hosepipe bans have been introduced by water companies, while the Environment Agency has imposed restrictions on extracting water from rivers and warned of widespread environmental impacts, such as fish die-offs and algal blooms in rivers, streams and lakes.
The map below shows how a significant number of rivers in the UK this spring saw exceptionally low flows (marked by a dark red circle) or notably low flows (marked by an orange circle) compared to the 1991-2020 average. This includes many rivers in northern parts of Great Britain – which is typically wetter the south-east.
The graphs on the right, meanwhile, show how flows in the River Derwent and the River Wye (black line) in 2025 have been at equivalent levels, or lower, than in major past droughts (red, green and orange lines). This includes the record-breaking drought of 1976 (orange line), often used as a benchmark.

How is climate change going to affect droughts in the UK?
Globally, climate change causes an intensification of the hydrological cycle. This means that both wet and dry extremes – floods and droughts – are likely to become more frequent and severe.
One way of understanding the impact of climate change on hydrological drought is to use rainfall and temperature projections from climate models to drive hydrological models that simulate how the flow of water through river catchments could change in the future.
There are numerous studies that provide such projections of UK drought. (A summary of these can be found in the chapter on modelling in the 2023 Environment Agency report, linked above.)
Across these studies, river flow models generally show that, in the future, the UK should expect lower summer river flows, increasing drought severity and decreasing minimum flows – in other words, the lowest flows in each year will get lower.
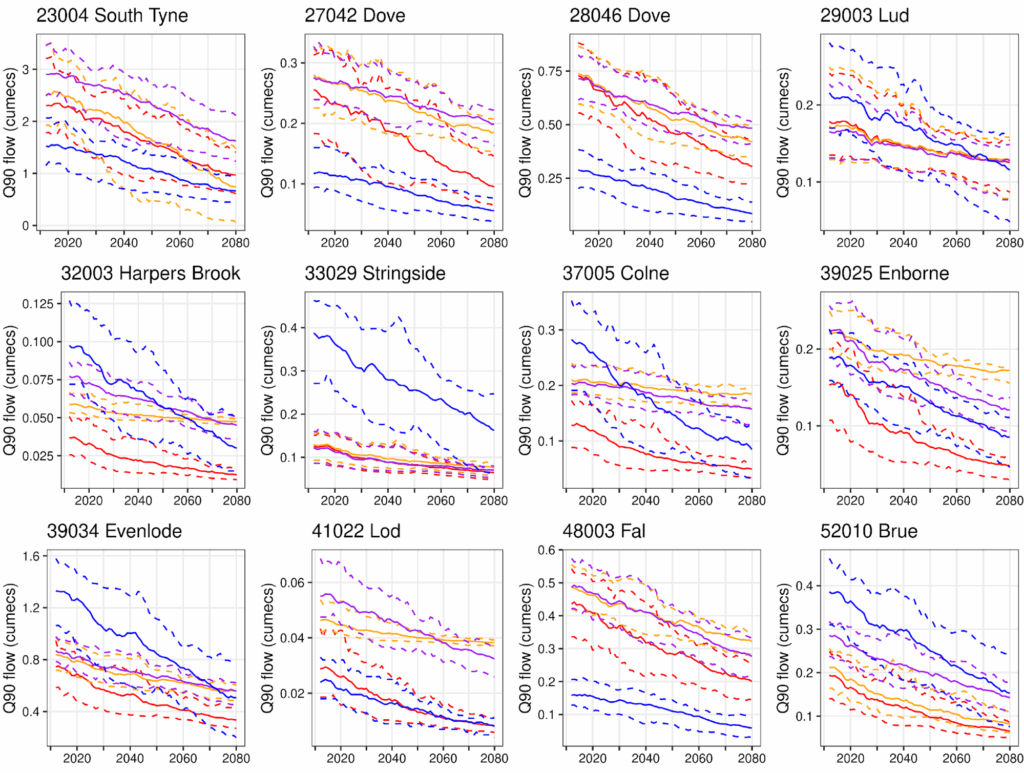
The graphs below show projections of changing low flows for a selection of UK rivers from the 1980s to the 2080s over consecutive 30-year moving averages (1983-2012, 1984-2013 and so on, through to 2050-79).
These projections are based on the “enhanced future flows and groundwater” (Eflag) dataset, which provides simulated river flows for 200 catchments around the UK, using four river flow models. These are driven by the “regional” projections from the Met Office’s UK Climate Projections 2018 (UKCP18), a 12-member climate model “ensemble” which uses the very-high-emission RCP8.5 scenario.
(For more on why this regional data is only available under this pathway, read Carbon Brief’s in-depth Q&A on UKCP18.)
The multiple lines on each plot – which indicate different projections for low flows – show the uncertainties arising from the different climate model runs and river flow models used.
The charts reveal that, across all rivers and different future trajectories, the trend points in the same direction – towards diminishing minimum flows. This suggests a drier future across the UK, most notably in the summer.
Past trends in drought
Given these projections, we would expect to see a similar trend of decreasing minimum flows emerging in observational data over the last few decades.
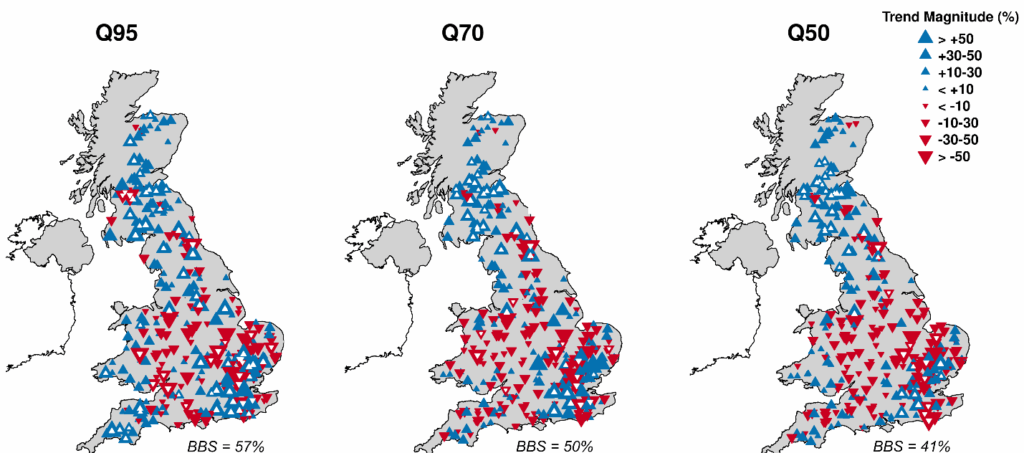
However, our research concludes that there is little compelling evidence for any evidence of a widespread worsening of UK droughts over the last half century – yet.
The maps below show how river flows have changed since 1965 across the UK for very low (Q95), medium-low (Q70) and median (Q50) flows.
For much of the north and west of the UK, the lowest flows in each year have, in fact, increased since 1965 (blue triangles). In the south and east of the country, there are decreases (inverted red triangles), but it is a mixed picture. Overall, the number of statistically significant trends is modest.
But, while these river flow records span more than 50 years, this is still a relatively short timeframe.
As a result, we also explored much longer records, including “reconstructed” river flows, which stretch back to 1890. Here, too, we find there is no consistent trend towards worsening drought over these long periods.
In fact, our research shows how trends in the last 50 years are often unrepresentative of longer-term changes. Some of the apparent decreasing trends from the maps above disappear when a longer view is taken.
Mismatch between past trends and future projections
There is a clear contradiction between future projections and past trends. We do not yet see much evidence of the drier future that climate models project.
However, this apparent contradiction is unsurprising once uncertainties inherent in both future projections and historical observations are considered.
Future projections are highly uncertain and span a wide range of possibilities – as shown by the multiple lines in the Eflag graphs above.
Caution is needed in interpreting trends in observations, too. While 50 years seems a reasonably long period, trends can be influenced by variability associated with natural atmospheric and oceanic circulation patterns.
The trends towards increasing river flows in the north and west are consistent with changes in the North Atlantic Oscillation (NAO) – the atmospheric pressure system that influences the UK’s weather on year-to-year and decade-to-decade timescales.
There is a growing list of drivers of drought variability, including the El Niño-Southern Oscillation (ENSO) and the role of the influx of freshwater into the North Atlantic due to the melting of the Greenland ice sheet.
In a recent paper, we highlighted that long-term trends in low river flows for many UK catchments may not be detectable for decades due to being obscured by natural climate variability.
This is shown by the plot below, which illustrates how projected trends of very low river flows over the 21st century (red line) contrasts with the estimated range of historical river flow variability (dashed lines). (The grey shading shows the range of different climate models.)
It shows that for some catchments – for example, the Lambourn River in south-east England – significant trends do not emerge until the 2050s.

Part of the mismatch between historical observations and climate projections for UK summer is due to a run of wet summers from the late 2000s onwards. This climate variability has ‘masked’ an underlying trend that could eventually emerge and bring a more worrisome consistency with the projections of climate models.
That this masking has often entailed living with an excess of water, in the form of widespread, damaging flooding, only highlights the challenges water managers face.
A drier and wetter future
Further research is required into how different types of hydrological drought will evolve.
We are confident we will see more droughts in April-September, typically associated with heatwaves, as in 2025, 2022 and 2018. This is because warming temperatures – which, unlike rainfall trends, are certain – will exacerbate droughts.
The increased likelihood of hot, dry summers also means more rapid-onset “flash droughts”, which have impacts on soil moisture as well as river flows.
As such, the droughts of recent years should be interpreted as a warning that hotter temperatures will worsen drought impacts.
However, we are much less confident that we will see more long, multi-annual droughts driven by dry winters that fail to replenish reservoirs and aquifers, such as those seen in 1988-93, 2005-06 and 2010-12. This is because climate models generally predict wetter winters for the UK. (These multi-annual droughts have, historically, posed some of the greatest challenges to water management.)
Nevertheless, climate variability means that even if winters get wetter, there will always be runs of dry years. This is a cause for concern, as the greatest problems occur when wet winters combine with dry summers. (It was the dry winter of 1975-76 which made the 1976 drought so severe).
Our finding that it is difficult to confirm whether droughts are, overall, becoming more severe offers little comfort to water managers preparing for the future.
Our research offers a number of recommendations for water planners trying to navigate this complexity. This includes using large climate model “ensembles” to test the resilience of water supply systems to different types of droughts. Although model projections are uncertain, they provide a way to assess the UK’s vulnerability to a range of future outcomes.
Furthermore, the hydrological volatility of the recent past indicates the importance of preparing for both a drier and wetter future in the UK.
The UK is known for its variable weather, but it will have a future climate that is even more variable and extreme.

The post Guest post: Is climate change making UK droughts worse? appeared first on Carbon Brief.

Several major banks that helped set up the UN’s now-defunct Net-Zero Banking Alliance (NZBA) in 2021 have since continued to lend money to coal companies, a new report has revealed.
Bank of America, Barclays, Citibank, Deutsche Bank and Santander were heavily involved in the NZBA and the associated Glasgow Financial Alliance for Net Zero (GFANZ) when it was launched by Mark Carney, then a UN climate envoy and now Canada’s leader, in the run-up to the COP26 climate summit in Glasgow.
Despite their involvement, data released this week shows those banks and some others did not reduce the amount of money they lent, nor the value of their underwriting, to coal activities between 2022 and 2025. Around half of the NZBA members who were engaged in coal financing over that time increased it and half cut it, according to the report by German environmental research group Urgewald.
Ana Botín, executive chair of Santander, was a member of the GFANZ CEO principals’ group and said at the time of the NZBA launch that her Spanish bank was “proud to be part of the founding members of this new alliance and to accelerate progress towards net zero”.
Since then, the report’s data documents that Santander has provided loans and underwriting worth hundreds of millions of dollars each year to coal companies, particularly American coal-power plant operators Duke Energy and the Southern Company. Santander did not respond to a request for comment.
Urgewald’s research adjusts the value of loans and underwriting provided to coal companies based on how much of a company’s revenues come from the most polluting fossil fuel. So a hypothetical $100 million loan to German utility RWE is valued at $21 million, as 21% of RWE’s revenue is from coal.
The research does not take account of whether companies are expanding their coal business or phasing it out for greener alternatives. Some banks have said their coal clients need to put in place transition plans by a certain date. Some also say that, by a certain date, they will stop lending money to clients that get more than a set percentage of their revenue from coal.
-
What’s on the climate calendar for October 2026?
Brazilians are heading to the polls, diplomats are gathering in the Pacific for Pre-COP, and it’s crunch time for the IPCC -
UN chief urges countries to adopt fossil fuel transition plans with timelines
In his last speech to the UN General Assembly, António Guterres for the first time called on every nation to deliver a plan to phase out coal, oil and gas while protecting workers

Most companies expanding coal are in Asian nations like China, India and Indonesia and are largely financed by banks from their own countries. But there are examples of NZBA founding members supporting companies that are actively prolonging the life of their coal businesses.
For example, Glencore, a Switzerland-based multinational that gets 4% of its revenue from coal, has just won preliminary regulatory approval to keep on coal mining in Australia’s Hunter Valley until 2045. Last year, the company was supported by loans and underwriting from Bank of America, Citigroup, Santander, Barclays, Deutsche Bank, HSBC and Standard Chartered.
Good and bad news
Some NZBA founding members like Swiss giant UBS have reduced their loans and underwriting for coal companies, the data suggests. Others – like Triodos and Kenya Commercial Bank – have provided no support for coal companies since at least 2021.
Urgewald researcher Hannah O’Neill told Climate Home News that “the banking sector is not moving in one direction. There is a growing divide between banks that are tightening their coal policies and reducing their exposure, and those where coal policies remain weak or where financing continues.”
Unlike the UN’s Race to Zero campaign, with which it partnered, the NZBA did not require its members to end financing for fossil fuels like coal, leading to accusations by climate campaigners that its rules were too weak.
Despite this, after Donald Trump’s re-election as US president in November 2024, several North American banks quit the alliance and the NZBA’s requirements were diluted in April 2025. After further withdrawals, the group shut itself down in October 2025.
Globally, the Urgewald report found that many banks in the European Union, Thailand, Malaysia, India and Taiwan have reduced their coal finance since governments agreed at COP26 to phase down coal power.
But with Chinese, American, Indonesian and South Korean banks increasing their support, total bank financing for the coal industry has remained broadly the same each year since 2022.
“Coal financing is not disappearing – but it is concentrating in banks and markets where coal policies are either missing or weak,” said Heffa Schücking, director of Urgewald.
Urgewald’s definition of coal companies includes firms and their subsidiaries that explore for, process, trade, transport and mine coal, or burn it in power plants to produce electricity, or manufacture equipment for the coal industry. It does not include companies that use coal to make cement or steel – and an adjustment is made to account for how much of the business model is coal-related.
Banks defend delays
At the time of publication, most of the banks named in the report for increasing their coal finance had not responded to requests for comment. But a spokesperson for Deutsche Bank pointed Climate Home News to its May 2026 announcement that it was delaying its requirement for existing clients to present it with transition plans and cut their coal exposure.
Instead of having to present these plans by the end of 2025, the bank has given them until the end of 2027. They will also have to ensure that their revenue share from thermal coal falls below half by then, the bank added. New clients need energy transition plans to access finance.
Deutsche Bank said at the time it was delaying its requirements because of the “increasingly complex regulatory environment as well as differing speeds of energy transition in various regions beyond what was anticipated by Deutsche Bank in 2023”.
Big banks’ lending to coal backers undermines Indonesia’s green plans
A spokesperson for Barclays told Climate Home News: “Many companies in this report are diversified energy or mining companies. We do not provide financing to companies that generate more than 30% of revenues from thermal coal mining or power generation, and we will phase out all financing by 2035.”
The Barclays spokesperson added: “Barclays is financing an energy sector in transition, providing finance to meet current energy needs and also financing the scaling of clean energy. Over the past three years, we have facilitated more than $300 billion of sustainable and transition finance, including billions to cleaner energy projects, and invested millions into climate tech.”
The post Big banks behind “net zero” alliance continued lending to coal firms appeared first on Climate Home News.
Big banks behind “net zero” alliance continued lending to coal firms
Harjeet Singh is the global convenor of the Fill the Fund campaign and founding director of the Satat Sampada Climate Foundation. Julie-Anne Richards is strategic campaign lead for the Make Big Polluters Pay campaign in Australia.
This year, a glacier collapse in Nepal’s Himalayan valleys swept away the lives of at least 1,500 people, with recovery costs of US$5 billion, or 10% of national GDP. But this was not a tragedy for which no one can be blamed. This was a crime with a balance sheet – one whose costs are paid by people who did nothing to cause it, and whose profits are booked by polluting corporations that did everything.
Across the Pacific, the calculation of injustice is now brutally clear. According to Oxfam Australia, the average yearly GDP loss of Pacific countries from climate disasters has increased four-fold over the last decade, reaching 14.3% of GDP. The number of Pacific people battered by climate disasters has risen by 700% in a decade. Whole villages are being packed up and moved as the sea takes the land beneath them.
-
What’s on the climate calendar for October 2026?
Brazilians are heading to the polls, diplomats are gathering in the Pacific for Pre-COP, and it’s crunch time for the IPCC
Let’s look at the other ledger. This year, as climate change and an oil shock drove up the cost of living for ordinary families, Woodside – touted as “one of Australia’s biggest winners” from the war in the Middle East – reported revenues jumping nearly 30% to AUD$6 billion in just three months.
In Australia, Oxfam finds that in 2023-2024, fossil fuel corporations paid only AUD$22.8 billion in corporate income tax – just 5% of their AUD$436 billion in total reported income – while 26 out of 80, or one in every three large fossil fuel corporations, did not pay corporate income tax at all.
The polluters are not struggling to pay for the damage they cause. They are choosing not to.
This is the moral obscenity at the heart of the climate crisis: the money exists. It is simply flowing in the wrong direction. And nowhere is that clearer than in the funds the world built to protect the vulnerable, now left to languish.
Funds struggle to fill their coffers
The Fund for Responding to Loss and Damage (FRLD) has received US$2.8 billion in requests from 119 countries. And Nepal has sought an urgent US$20 million for immediate needs. Yet the Fund has only US$342 million in total to give.
The Pacific Resilience Facility – a fund the Pacific designed for itself, to prepare its own communities – sits well short of even its modest US$500 million capitalisation target. And the Adaptation Fund is running on empty. While adaptation needs in developing countries could reach US$387 billion a year by 2030, according to the latest UNEP Adaptation Gap report, the Fund’s resource mobilisation target of a modest US$300 million for 2025 fell far short, with only US$135 million pledged.
This is a matter of priorities, not of resources. For decades, the world has accepted a simple principle – the polluter pays principle – whether through the OECD, of which Australia is a member, or Europe’s carbon pricing. New York and Vermont have already passed laws to make Big Oil pay into climate superfunds, and ten more US states are moving to follow.
The idea is neither radical nor new. It’s time to make big polluters pay.
Comment: After Hormuz, Nepal and wildfires, people want action to make polluters pay
What is urgently needed is the courage to apply it to the fossil fuel corporations that have spent decades avoiding it. In November, Australia takes up the presidency of the COP31 negotiations, committing to stand shoulder to shoulder with its Pacific neighbours.
Australia, together with the Turkish COP31 Presidency, must guide and inspire progress at the upcoming climate conference, including on new climate finance pledges by developed countries (which agreed to mobilise at least $300 billion by 2035) and triple the funds available to the FRLD, the Adaptation Fund and the other UN climate funds.
Rich countries agreed to these goals two years ago at COP29. Yet, the reality is that developing countries’ need for climate finance is in the trillions annually, while developed countries continue to delay providing even what they have already committed. A clear signal recognising the importance of delivering the promised climate finance must come at next week’s Pre-COP in the Pacific, and COP31 in Antalya must go on to deliver against existing promises or risk an irreparable breakdown in trust.
Time for a climate pollution levy
Countries must also ensure funding for loss and damage takes its rightful place as the third pillar of climate finance, alongside mitigation and adaptation, in negotiations regarding the UNFCCC climate finance work programme and Article 9 on shifting finance flows towards a low-carbon, resilient world.
Australia, as President of Negotiations and as a Pacific nation, cannot ask the world to fill these funds while it lets its own coal and gas giants off the hook. Australia should not only stop approving new and expanded coal and gas mines, it should also introduce a Climate Pollution Levy on big coal, oil and gas corporations – a charge on every tonne of carbon pollution they extract and profit from. Independent analysis shows such a levy could raise tens of billions of dollars a year, and can be designed so the cost falls on the corporations, not on households.
This is not charity – it is compensation. It is the beginning of accountability. And the public is far ahead of its leaders: eight in 10 people worldwide, and a clear majority of Australians, want fossil fuel firms taxed to pay for the damage they cause.
Fossil fuel expansion threatens COP31 hosts’ credibility, experts warn
The money must go where the harm lands. A Climate Pollution Levy should feed the funds frontline communities are relying on – fully capitalising the Pacific Resilience Facility this year, replenishing the Adaptation Fund, and delivering the billions the loss and damage fund needs.
It is essential for these funds to be able to provide grant-based finance that reaches communities directly, not more loans that push drowning nations deeper into debt. With Nepal’s recovery costs estimated at around 10% of the country’s GDP, if we leave it to fend for itself without loss and damage funding, Nepal will likely be saddled with debt and could fail to recover adequately, increasing poverty and inequality.
We have heard enough empty pledges. We have watched enough funds announced with fanfare, only then to be starved in silence. The era of asking polluters politely is over. Australia, as COP31 president, has a rare chance to prove that the polluter pays principle means something and apply it to those who have profited the most.
The post As COP31 co-host, Australia should make its polluters pay for climate damage appeared first on Climate Home News.
As COP31 co-host, Australia should make its polluters pay for climate damage
This is a republication of October’s edition of The Climate Agenda – a subscriber-only newsletter designed to keep you informed of the key events, negotiations and announcements happening every month. If you want to receive The Climate Agenda straight to your inbox at the start of each month, sign up as a subscriber today.
This month, we’ll be on the ground reporting from the Convention on Biological Diversity summit in Yerevan, Armenia later this month and following all the developments as we build towards COP31 in Antalya, Türkiye next month. Here’s what you need to know for October, why it matters and what to expect.
Brazilian Election
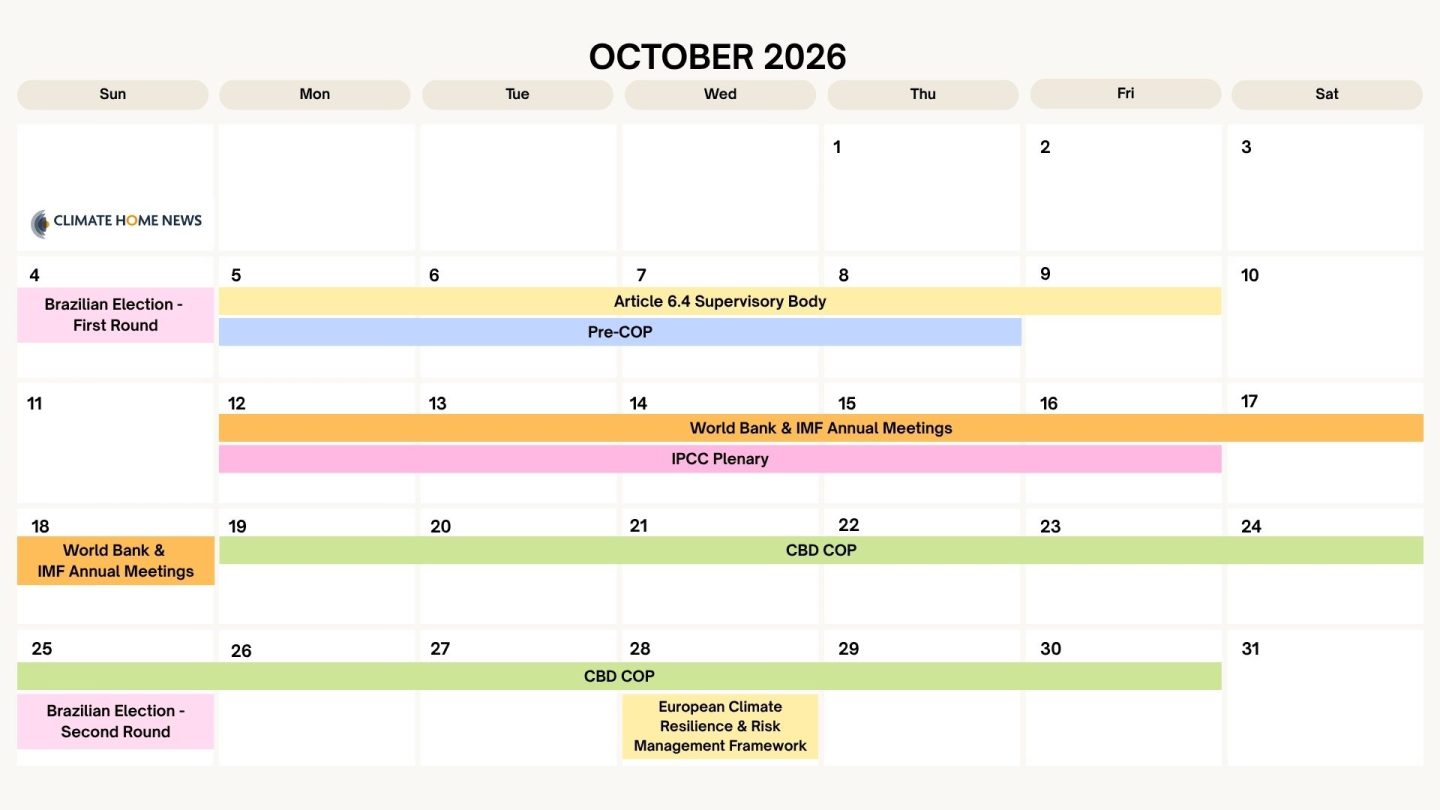
First round: Sunday 4 October – Second round: Sunday 25 October
This poll is being closely watched by Brazilian environmentalists as it’s likely to make a big difference to Brazil’s international climate politics and the health of the Amazon rainforest.
The two clear front-runners are current left-wing President Lula and right-wing Flávio Bolsonaro. Flávio is the son of Jair Bolsonaro, who ruled from 2019 to 2023 but was declared ineligible to hold public office because of his attacks on the electoral system and is now under house arrest.
In the unlikely event that either candidate wins more than half the votes in the first round, they will be elected as the country’s leader. Latest polls have Lula on 39% and Bolsonaro on 35% (though the numbers are shifting) with several minor candidates in the single-digits. If none of them get a majority, there will be a one-on-one run-off on October 25.
The Latin American nation is set to record its lowest-ever level of deforestation, as efforts to rein in illegal clearing and restore Indigenous rights progressed under Lula. But Brazilian experts are warning that the huge agribusiness lobby in Congress, whose interests shape what happens in the Amazon, will be emboldened if Bolsonaro takes power, with the Supreme Court also risking a turn to the right.
As for climate politics, some seasoned watchers fear that Flávio – a climate change denier like his dad – could even try to pull Brazil out of the Paris Agreement. That would leave other countries to take forward Brazil’s COP30 global roadmaps on transitioning away from fossil fuels (TAFF) and ending deforestation – both of which are due to be delivered by COP31.
For Brazil’s own TAFF roadmap – commissioned earlier this year but so far nowhere to be seen – the election may have less of an impact, given Lula is as keen as any other politician to extract oil and gas from the Amazon, amid cross-party support for fossil fuel production.
Read more: Brazil leads “encouraging” decline in global rainforest destruction in 2025

Pre-COP
Monday 5 October – Thursday 8 October – Fiji and Tuvalu
The annual Pre-COP meeting is usually a business-like gathering of government negotiators, sounding out each other’s positions and laying the groundwork for deals at the main COP summit. But this year’s “pre” has been jazzed up by Australia’s partnership with Pacific governments keen to elevate their climate issues on the international stage.
“We will bring the eyes of the world to our region, highlight the threat that climate change poses to it, and show how Pacific voices are shaping global action to counter it,” Australian PM Anthony Albanese said of the event.
On Monday, before the Pre-COP officially starts, a group of senior government figures – including a handful of leaders – will visit the world’s second lowest-lying nation Tuvalu, as UN boss Antonio Guterres did in 2019.
They will visit areas affected by sea level rise, see climate resilience projects and meet local communities before flying 2.5 hours south to Fiji to join up with the Pre-COP – which starts on Tuesday – and speak at a “Leaders’ plenary session” that evening.
The Pre-COP runs until Thursday. Governments are expected to try to advance on some kind of a roadmap for protecting oceans from climate change, while Fiji says Pacific nations will emphasise the need to follow science and step up efforts to limit warming to 1.5C.
Australia is also due to present an action plan to improve access to climate finance for small island nations and least-developed countries, so that governments, development banks and climate funds can endorse it ahead of the Antalya summit.
Alongside the official Pre-COP discussions, a “green zone” will host talks organised by civil society on topics like public transport, carbon markets and the International Court of Justice advisory opinion. Unfortunately, these events won’t be available to follow online.
Read more: Threatened by rising seas, small islands secure right to keep their statehood
Read more: At regional summit, Pacific islands ask for COP31 support for clean energy and finance
Article 6.4 Supervisory Body
Monday 5 October – Friday 9 October – Bonn, Germany
The UN carbon market’s rule-making body meets for one last jam-packed session ahead of COP31, with decisions pending on several high-stakes issues that could shape the future of the new crediting mechanism.
Top of the agenda is a rulebook for clean cooking projects, which aim to cut greenhouse gas emissions by distributing more efficient cookstoves. These projects generate some of the most popular carbon credits but have also drawn some of the heaviest criticism for overstating their climate benefits through lax accounting.
Technical experts have recommended the Supervisory Body tighten the rules compared to existing crediting programmes, including by forcing cookstove project developers for the first time to guard against the risk of the climate benefits of their credits – the trees saved from becoming cooking fuel – being wiped out by fire, drought or logging.
The proposal on the so-called reversal risk assessment has sparked a “coordinated” lobbying campaign from the industry, some conservation NGOs and UNEP, arguing that stronger protections could hike project costs and restrict the supply of credits.
Read more: Industry and NGOs lobby to weaken UN carbon credit rules in “coordinated” push
Intergovernmental Panel on Climate Change (IPCC) plenary
Monday 12 October – Friday 16 October – Addis Ababa, Ethiopia
Scientists and government officials will try, once again, to agree on a timeline to produce the highly influential AR7 assessment report from the UN’s climate science body.
The faultlines that have blocked a deal at several previous sessions are well established: a large group of predominantly developed countries, small island and progressive Latin American states and the poorest nations want the reports to be ready in time to inform the UN’s next global assessment of climate action, due to be completed in November 2028.
A small group of primarily big emerging economies disagree, claiming this timeline would put a burden on developing countries with limited resources and restrict their ability to provide scientific input into the process.
Three options will be on the table in Addis Ababa. Two of them would see all three flagship assessment reports approved by July 2028 and September 2028 respectively, just in time to feed into the second Global Stocktake.
The third, based on proposals from Saudi Arabia and India, would deliver only the Working Group 1 report, on the physical science of climate change, by May 2028. The reports from Working Groups 2 and 3, covering climate impacts and ways to cut emissions, would not be approved until mid-2029, well after the stocktake concludes at COP33.
Delegates are also expected to discuss the IPCC’s increasingly strained budget, made worse by a funding gap left by the withdrawal of the United States. The panel has warned that, without a sustained increase in contributions, its trust fund’s cash balance would run out by the end of 2028, putting the delivery of the AR7 set of reports at risk and forcing cuts to in-person meetings, translation and outreach.
Read more: Science ‘under attack’ from fossil fuel interests at UN climate talks
Read more: As science comes under attack at UN talks, climate movement splits over how to respond
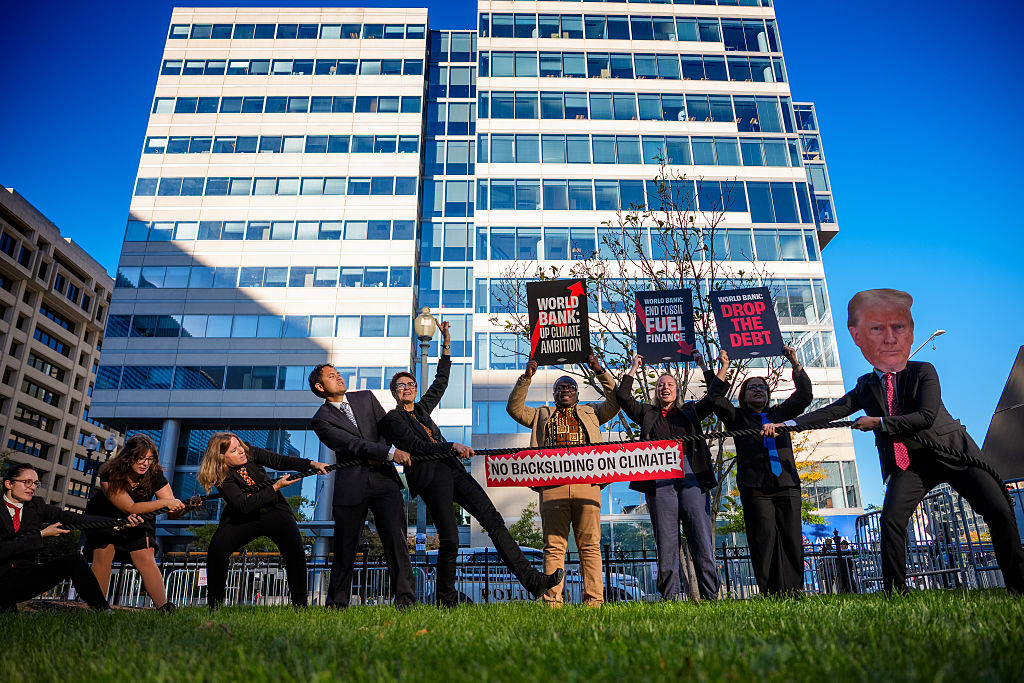
World Bank & IMF Annual Meetings
Tuesday 12 October – Sunday 18 October – Bangkok, Thailand
With their biggest shareholder – the US – resolutely opposed to climate action, the World Bank and International Monetary Fund (IMF) are likely to try to avoid mentioning climate change at their annual meetings in Bangkok – and there are no headline events on the subject.
But they aren’t in complete control of the agenda. Thailand will host a discussion on financing a green resilient economy and World Bank President Ajay Banga is likely to be challenged on climate at a live-streamed civil society townhall on October 12.
With tricky negotiations on the World Bank’s climate finance target concluded earlier this year (it was dropped), talks are moving on to the sustainability framework of the World Bank’s International Finance Corporation, which invests in the private sector. Civil society is calling for its rules on protecting people and the planet to be maintained and strengthened.
The IMF’s guidance note to staff – which shapes the circumstances under which climate can be included in IMF programmes – will also be negotiated. Longer term, the Resilience and Sustainability Trust, which channels funding to green projects, will be reviewed but not before 2028 at the earliest.
Read more: World Bank’s climate work can endure without finance target, experts say
Convention on Biological Diversity (CBD) COP17
Monday 19 October – Friday 30 October – Yerevan, Armenia
The biodiversity COP – a sister convention to the UN climate process – will for the first time take stock of progress towards key goals in its 2022 landmark agreement, the Global Biodiversity Framework (GBF). These include a headline target to protect and conserve at least 30% of the planet’s land and marine ecosystems by 2030.
A draft report prepared by a scientific panel warns that “unless collective implementation accelerates rapidly, the 2030 targets and mission will not be achieved”. In fact, governments are failing on 22 out of 23 targets. The final report is expected to be published ahead of COP17, where governments are expected to react strongly.
UN biodiversity chief Astrid Schomaker told journalists earlier this month that the most significant progress is expected to occur towards the end of the decade, as 174 countries took the first four years to develop national targets.
Finance, meanwhile, is set to become a contentious issue, as the draft report says developed countries fell short on a target to provide $20bn per year in international public finance for nature protection, reaching only about $17bn per year from 2020 to 2023. They have also yet to meet a wider goal to mobilise $200bn per year counting all kinds of finance.
Much like in climate talks, the EU has proposed to broaden the base of donors to include emerging economies who want to “voluntarily assume the obligations” of developed countries. Saudi Arabia and Qatar want nothing to do with this proposal. China has said bringing in new contributors should not weaken the obligations of developed countries. Expect a fight in Yerevan.
A preliminary meeting in Nairobi in August resulted in a heavily bracketed text that delegates will have to unravel in Armenia. One observer said countries had “overall missed the level of urgency” needed.
Keep an eye out for our webinar live from Yerevan later this month, where we’ll provide an update on the talks and how governments are responding to science’s demands for quicker action.
Read more: Mombasa ocean summit drives progress on marine protection, but threats persist
Read more: UN biodiversity talks agree finance roadmap, postponing decision on a new fund
European Climate Resilience & Risk Management Framework
Wednesday 28 October – Brussels, Belgium
Following a torrid summer beset by recurring heatwaves, drought and outbreaks of forest fires across the continent, the European Commission will present its keenly awaited climate resilience and risk management framework to help member states protect their populations from worsening climate change impacts.
As part of the policy package, the Commission will identify 100 of Europe’s most climate-vulnerable territories. And alongside an assessment of the risks, there will be guidance at which level they should be managed – regional, national or by the EU. Currently, confusion often arises over who is responsible for preventing, preparing for and managing disasters across the bloc.
The framework will also aim to make Europe a “champion in adaptation technologies” – such as drought-resistant crops, flood prevention or energy-efficient cooling – which have been described by EU President Ursula von der Leyen as “a huge emerging market”.
With only around a quarter of catastrophe losses in Europe covered by private insurance, the Commission also plans to set up a Climate Insurance Alliance to boost that figure.
READ MORE: WHO issues new guidance on heat-health action plans, as El Niño sets in
The post What’s on the climate calendar for October 2026? appeared first on Climate Home News.



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy12 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19