


- Formal negotiations
- Finance
- Global review
- Global report
- Digital sequence information
- Harmful subsidies
- Marine biodiversity
- Planning, monitoring, reporting and review
- Article 8(j) implementation
- Biodiversity and climate change
- Links with other bodies
- Around the COP
- Armenian presidency
- Protests
- Lobbying and influence
- Carbon and biodiversity markets

Donald Trump’s designs on Venezuela and Greenland have sent shock waves around the world. Canadian premier Mark Carney said they have created a “rupture in the world order”, as political alliances that have held for over 80 years are thrown aside.
And as the US seeks to carve out a Western Hemispheric sphere of influence, questions about the dollar’s future as the lynchpin of the global economy are growing louder. Many other parts of the world are switching to green energy sources as renewable energy becomes cheaper than fossil fuels, and countries forced to pay back loans in dollars are eyeing alternative currency options to free themselves from the penalty of fluctuating exchange rates amid unpredictable policy shifts.
As a result, the continued relevance of the petrodollar system – in which oil is traded in dollars and guarantees demand for US currency – may be less than assured.
What is the petrodollar system?
The petrodollar system was established in the 1970s following the collapse of the Bretton Woods system and is one of the most consequential monetary arrangements in modern history.
In 1944, the Bretton Woods agreement made the US dollar the anchor of the global monetary system, pegged to gold and with other currencies fixed to the dollar. The framework aimed to provide global financial stability following the economic fragmentation of the Second World War and cemented the dollar as the world’s reserve currency.
US President Richard Nixon abandoned the gold standard in 1971 to curb inflation after foreign central banks – increasingly reluctant to hold depreciating dollars – began converting their dollar reserves into gold. The petrodollar system emerged as an alternative means of keeping the dollar as the backbone of international transactions.
The petrodollar system refers to the pact that Gulf Cooperation Council (GCC) states – including Kuwait and Saudi Arabia – made with the US, agreeing to price oil in dollars and to recycle revenues into US Treasury securities in return for military protection and sales of advanced weaponry.
-
Vanuatu pushes new UN resolution demanding full climate compensation
The Pacific island nation wants the UN General Assembly to enforce last year’s landmark court decision on states’ climate responsibility, a first draft shows
Andrés Arauz, former Ecuadorian minister and central bank director, told Green Central Banking that ramifications for the global economy were immense: “So oil and gas [are traded in dollars], but then also downstream with all the derivatives, but then also all the chemical elements derived from the oil industry and petrochemical industry. And then likewise, upstream with all the technology and inputs required to extract the oil, [it] created a dollar-denominated value chain with global and international repercussions.”
Arauz also notes that international accounting standards set by institutions like the IMF reinforce the system by requiring central banks and organisations to report reserves in dollars, solidifying the greenback as the default unit of account.
For decades, this system delivered guaranteed demand for dollars, recycled oil revenues into safe-haven US debt markets, and provided outsized geopolitical leverage to the US Federal Reserve given the need of other countries to accumulate dollars to conduct global transactions.
Fadhel Kaboub, associate professor in economics at Denison University, explains how this “exorbitant privilege” distorted the global economy in the US’s favour. “All countries operate … within a system where they have to accumulate reserves not in gold anymore but in dollars and countries that have debt, their debt is denominated in dollars. So that created a locked-in system that gives the US dollar a privilege as the dominant payment system and gives the opportunity to weaponise this system.”
The petrodollar system has also encouraged and amplified US consumption of fossil fuels and its contribution to greenhouse gas emissions. Kaboub, who is also a member of the United Nations High-Level Advisory Board on Economic and Social Affairs, says the system has “rewired” the global economy into an extractive model that promotes environmentally destructive industries.
But as decarbonisation accelerates and renewable energy displaces fossil fuel value chains, the petro-lynchpin of dollar dominance faces unprecedented strain.
Is the petrodollar in decline?
Signs of discontent are increasing, placing the dollar’s decades-long dominance under unprecedented pressure.
BRICS countries are discussing new financial mechanisms that will make trading within the bloc easier but may also reduce reliance on existing dollar-dominated channels. Both India and Brazil have denied that linking BRICS digital currencies is part of moves towards de-dollarisation, but such a move will likely cause concern in the US.
Meanwhile, European Central Bank President Christine Lagarde made headlines in May 2025 with her blunt assessment that the current global landscape presents a significant opportunity for a “global euro moment”, as investors “unsettled by unpredictable US economic strategies” increasingly reduce their exposure to dollar-denominated assets.
These developments reflect deeper structural shifts. The dollar’s share of global reserves has declined from 71% to 56.3% since 2008, with central banks purchasing over 1,000 metric tons of gold annually for three consecutive years. China slashed its US Treasury holdings from US$1.3tn in 2013 to just $682bn by November 2025, while simultaneously expanding yuan-based trade across Asia.
Africa records fastest-ever solar growth, as installations jump in 2025
This shift was triggered by what Arauz describes as “eroding trust” in US financial systems.
“Perhaps the most serious element that has accelerated this diversification has been the weaponisation of the hegemonic banking system,” Arauz said. “[Through] sanctions, through asset freezes, through confiscation of international reserves in many countries … [these] have definitely stirred things up and made countries reflect about the reliance on this previously thought of neutral system that is now, on the other hand a threat, to their national sovereignty and economic policies.”
The climate crisis is also acting as a catalyst. As the world transitions away from fossil fuels, structural strain is placed on the demand for dollars, and the more the US clings to fossil fuel dependency in order to maintain monetary dominance, the deeper the cracks become.
Gulf states have long-term plans to diversify away from oil and reinvest a substantial portion of their oil revenues in green value chains, challenging the core pact which upholds the petrodollar system that US currency dominance has long depended on.
And while economists expect the dollar to remain the primary reserve currency in the near term, it has also been noted that once transitions to a new system are underway, they can happen very quickly. Speaking at the World Economic Forum in Davos in January, Jeffry Frieden, political science professor at Columbia University, warned of “an erosion of confidence in the dollar” amid mounting doubts about the safety of US Treasuries as “the most important financial asset in the world”.
‘US pulling itself out of the picture’
The Trump administration’s response to a shift away from the dollar has been to double down on arms sales and fossil fuel infrastructure – what Kaboub calls a “long-term strategic failure” that fundamentally misreads the changing dynamics of global power.
Trump’s recent $142bn arms deal with Saudi Arabia aims to tether Gulf revenues to the dollar through military exports. However, economists like Maya Senussi at Oxford Economics and John Sfakianakis of the Gulf Research Centre warn that financing such deals alongside decarbonisation projects will strain GCC budgets, and Bloomberg estimates it will require oil prices to be at least $96 a barrel just to break even. Brent oil prices currently hover around $67-68.
And in the Global South, higher oil prices may inadvertently threaten dollar dominance by exacerbating debt burdens by increasing repayment costs, pushing countries towards cheaper (and greener) energy systems. America’s transition to net fossil fuel exporter status means higher oil prices now strengthen rather than weaken the dollar, creating a triple blow for dollar-indebted countries in Latin America and Africa: higher energy costs, escalating debt servicing and constrained fiscal space.
The very mechanism designed to strengthen dollar ties – expensive arms deals premised on elevated oil prices – accelerates the search for alternatives among countries holding critical transition minerals like lithium, copper and cobalt. This pushes the US further from the green value chains of the future.
“The US is pulling itself out of the picture, it’s divesting from the green technologies and green industries. Which means it’s moving away from its interest in critical minerals,” says Kaboub. “So the remaining big player is China, and it’s a friend of the Global South.”
Today, China controls 85-90% of global rare earth processing and offers renewable energy equipment that remains attractive to the GCC despite US and EU tariffs. This is thanks to competitive pricing and comprehensive infrastructure approaches that western competitors have largely failed to match.
‘America needs you’: US seeks trade alliance to break China’s critical mineral dominance
Kaboub says that Trump’s minerals-for-security deals, such as in Greenland and elsewhere, may secure short-term market access but erode global trust in US foreign policy, a cornerstone of confidence in the dollar. “The isolated backwards technology bloc is going to be the United States,” he says.
As Lagarde observed, investors increasingly seek “geopolitical assurance in another form” by directing investments toward regions perceived as “dependable security allies” – but this no longer automatically defaults to the US as its government criticises its one-time allies and jeopardises the future of NATO.
Yet the petrodollar system faces challenges that extend far beyond the geopolitics of sanctions; climate change has introduced structural pressures making the core foundations of dollar dominance increasingly untenable.
However, given Trump’s bellicose stance on Venezuela and Greenland, there is a risk that American policymakers will not recognise this new reality until it is too late.
This article was originally published by Green Central Banking.
The post Explainer: What is the petrodollar and why is it under pressure? appeared first on Climate Home News.
Explainer: What is the petrodollar and why is it under pressure?
Continue Reading
Countries have completed the first “global review” of their progress towards reversing nature loss by 2030 at the COP17 biodiversity talks in Yerevan, Armenia.
The review “notes with deep concern” that, unless action is “rapidly accelerated”, the goal to reverse nature loss and meet a set of 23 targets by 2030 “will not be achieved”.
It “urges” countries to accelerate action, including by “increased ambition in addressing the gaps”.
Much of the discussions in Yerevan focused on how to raise the necessary funds to help developing countries protect nature.
Some major economies pushed to expand the range of nations that are expected to provide finance, with countries agreeing at the end of the two weeks of talks that non-donors that want to contribute can “signal interest” before COP18.
This came after developed countries failed to meet a target to significantly ramp up nature finance over the last few years.
It also came as a landmark fund agreed at COP16 in Colombia to pay communities for the genetic resources derived from nature stands nearly empty two years on.
The Yerevan talks marked the halfway point of the “Kunming-Montreal Global Biodiversity Framework” (GBF), the “Paris Agreement for nature” first made in 2022 and due to be achieved by 2030.
During the nearly 12-hour-long final plenary, countries voted for Quito, Ecuador, to host the COP18 nature talks, which will be held in 2028.
Countries managed to sign off on all the major negotiation texts, marking a stark contrast to COP16, which ran so far over time that the Colombian presidency lost “quorum”, forcing talks to resume in Rome months later.
Below, Carbon Brief has detailed analysis of all of the key outcomes from COP17.
Formal negotiations
Finance
Finance, predictably, was at the heart of the discord and deadlock at the Yerevan talks.
At COP17, discussions on finance had to achieve several outcomes.
The first part – to take stock of biodiversity finance mobilised so far to meet the nature deal’s goals – fell under the global review.
As the global report noted, developed countries failed to meet their commitments to raise “at least $20bn a year by 2025” for nature. Delegates pointed to falling aid levels and a sharp 27% decline in environmental funding for the 2026-30 period.
The second part was to agree on how to mobilise resources for the next four years, to meet the GBF’s goals and targets.
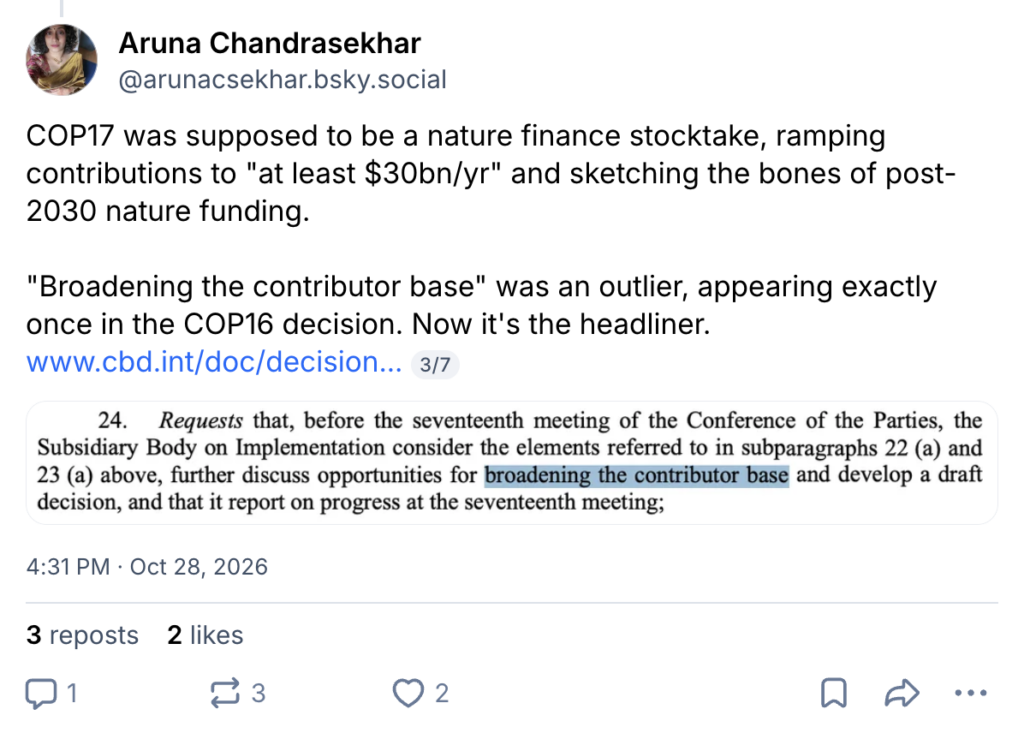
Calls to “broaden the contributor base” of who pays to protect nature – and whether that should include emerging economies – became the most fraught element of the talks.
Eventually, countries agreed on what Switzerland described as a “super, mega-delicate” text. It hinged on major “political compromises”, with “no major winner or loser”, according to Kenya.
Per the decision, countries that want to be included on a list of developed country donors can “signal interest” through bilateral, confidential consultations before COP18 and every alternate COP after.
Finally, countries also agreed on criteria to shape and resource a new, permanent financial mechanism to protect nature after 2030.
However, this did not immediately take the form of a new fund under the COP that biodiverse countries have demanded since 2022, deferring the mechanism’s institutional structure to COP18.
Resource mobilisation discussions at the GBF’s halfway mark were supposed to agree on how to close the “biodiversity finance gap” and to “increase resources from all sources” to “at least” $200bn per year by 2030, as set out in target 19 of the GBF.
The talks were largely dominated by a push, led by the JUSCANZ bloc of developed countries, to “broaden the contributor base”. This could see emerging economies, such as Qatar, China, Saudi Arabia and India, being added to the list of countries that pay to protect nature.
Article 20 of the UN Convention on Biological Diversity (CBD) states that developed countries “shall provide new and additional financial resources” to developing countries to meet the costs of implementing measures to protect nature.
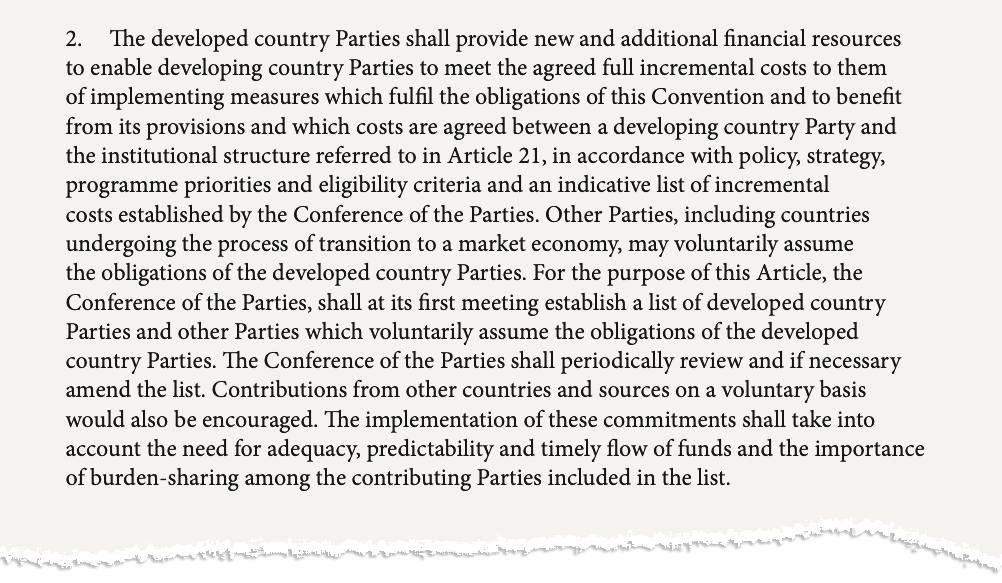
The text states that other countries – including emerging economies – may “voluntarily assume” these obligations to pay. However, it adds that this list of developed countries “shall” be reviewed periodically and amended “if necessary”.
The list was last amended in 2006.
(See this “jargon buster” which explains the specific meaning and legal weight of various terms and verbs used in UN formal documents.)
Discussions around this fraught subject had reached a dead end at intersessional talks this year, but resurfaced in Yerevan.
The first “non-paper” had four different options for expanding the contributor base. These ranged from using the World Bank’s country income groups “as a proxy” to identify high-income countries, to commissioning a study on the impacts of being included on the list.
By 21 October, the number of options swelled to eight, including two from Saudi Arabia and one from Peru.
Some countries “expressed concern” that certain options were based on a CBD secretariat study on “what constitutes a developed country”, Earth Negotiations Bulletin reported.
By the end of the first week, it was clear that the finance deadlock would have to go into informal ministerial consultations for any consensus to emerge.
At a press conference on 28 October, Christopher O’Sullivan, Ireland’s nature minister and representing the EU delegation, told Carbon Brief:
“Our position isn’t that we want to pull back in terms of contributing…but it’s been 20 years since that list was added to, times have changed and there are new realities. We just simply want those new realities reflected. I don’t fully understand why there’s so much opposition to that.”
The EU chose not to comment on which countries it would like to see on that list.
Lim Li Ching from the Third World Network, meanwhile, called the push for others to “assume the obligations” of developed countries “sheer hypocrisy”, adding that any country could make a voluntary contribution. She told Carbon Brief:
“At a forum like the CBD, this linking of income status with finance does not take into account where historical and current responsibilities lie. If you want to generate more funding for biodiversity, let’s look at sovereign debt burdens and rules, which are inequitable for developing countries. But if you can fund wars, and provide resources for your defence industry, then you know where the priorities are.”