

Welcome to Carbon Brief’s China Briefing.
Carbon Brief handpicks and explains the most important climate and energy stories from China over the past fortnight. Subscribe for free here.
Key developments
US-China climate deal paves way for Xi-Biden meeting and COP28
SUNNYLANDS STATEMENT: Following talks between US and Chinese climate envoys John Kerry and Xie Zhenhua, the two nations released statements “to jointly tackle global warming by ramping up…renewable energy with the goal of displacing fossil fuels”, the New York Times reported. Both countries pledged to “pursue efforts to triple renewable energy capacity globally by 2030”, a key goal in COP28 negotiations, it added. The statement backed the “success of COP28”, which Reuters said was “crucial” to coming to a consensus in Dubai. However, while the statement supported a broad political outcome from the “global stocktake” at COP28, there was no agreed language on fossil fuel phaseout, noted Carbon Brief’s Simon Evans on Twitter. The BBC quoted Bernice Lee, distinguished fellow at Chatham House, as saying that it had likely “proven to be too difficult to find the form of language that works for both” on fossil fuels. Similarly, while there were commitments in the statement to hold policy dialogues on energy efficiency, doubling the rate of efficiency improvements by 2030 was not mentioned.
EMISSIONS PEAKING: The two countries “expect meaningful cuts to be made to power sector emissions before 2030”, Bloomberg reported, quoting Joanna Lewis, an expert in international policy at Georgetown University, as saying this implies “a reduction in emissions from China’s coal plants very soon”. (This aligns with recent analysis by the Centre for Research on Energy and Clean Air (CREA) for Carbon Brief, see below.) However, on Twitter, senior Politico climate correspondent Karl Mathiesen spotted a slight difference between the readouts – in the US version, power sector emissions cuts are tied to “this critical decade of the 2020s”, whereas in the Chinese readout, reductions are not linked to any date. Reductions will likely be driven in part by carbon capture, utilisation and storage (CCUS), with Chinese energy outlet BJX News reporting that “the two countries aim to promote at least five large-scale [CCUS] cooperation projects in industry and energy…by 2030 in each country”.
‘RESTARTING’ COOPERATION: Kerry and Xie’s meeting was followed by a meeting between presidents Joe Biden and Xi Jinping on the sidelines of the Asia-Pacific Economic Cooperation (APEC) summit, at which the two leaders discussed maintaining “high-level communications” and cooperating “on trade, agriculture, climate change and artificial intelligence”, Reuters said. Le Monde reported that the US and China will restart bilateral energy dialogues and establish working groups to cover key areas of concern. US treasury secretary Janet Yellen and Chinese vice premier He Lifeng also agreed to improve climate change and global debt relief cooperation in earlier talks, the South China Morning Post reported.
‘Structural decline’ in carbon emissions expected from 2024
2024 DECLINE: In analysis for Carbon Brief, Lauri Myllyvirta, lead analyst at CREA, estimated that China’s carbon emissions “could peak this year before falling into a structural decline” due to “a historic expansion of the country’s low-carbon energy sources”, reported the Guardian. Covering the analysis, Chinese energy news site IN-EN.com said rapid growth in power generation from low-carbon energy sources, a consequent decline in coal’s share of energy consumption and China’s real estate sector downturn “lays the groundwork” for declining emissions. Myllyvirta noted that solar energy saw the “most significant increases”, with 210 gigawatts (GW) of solar power set to be installed this year, the news platform Guancha reported. These record additions are “all but guaranteed to push China’s fossil-fuel electricity generation and CO2 emissions into decline in 2024”, Business Green said in its coverage. Myllyvirta spoke on state broadcaster CGTN to discuss the findings, which were also reported by CNN, Reuters, Bloomberg, Global Times and South China Morning Post.
COAL SPOILER? In a parallel piece in Foreign Policy, Myllyvirta and his co-author Byford Tsang, senior policy advisor at climate thinktank E3G, wrote under the headline: “China pledged to ‘strictly control’ coal. The opposite happened.” Yet Myllyvirta also noted in his analysis for Carbon Brief that a surge in China’s investment in manufacturing capacity for low-carbon technologies is creating an increasingly important interest group in the country, which could affect its approach to domestic and international climate politics. This is “setting the scene for a showdown between the country’s traditional [coal] and newly emerging interest groups”, Agence France-Presse noted in its coverage.
OVERSEAS FREEZE: Meanwhile, China’s two development banks did not make any new energy sector loan commitments in 2022 for “the second year in a row”, according to a new policy brief by the Boston University Global Development Policy Center. In an article for the China Global South Project, co-author Cecilia Springer wrote that this was driven by “ongoing domestic economic woes” and “heightened debt distress in borrowing nations”.
China compensates coal power plants for spare capacity
CAPACITY COMPENSATION: China will give “guaranteed payments” to coal power producers under a new coal capacity compensation mechanism effective 1 January 2024, the country’s top economic planner, the National Development and Reform Commission (NDRC), announced in a notice released on Friday, Reuters reported. It added that the “widely-anticipated” move aims to ensure the financial viability of “seldom-utilised, backup” coal power and counter challenges with the variability of renewable energy. The mechanism will allow coal power plants to recover their fixed costs through a capacity tariff set at either 30% or 50% of 330 yuan per kilowatt per year through 2025, depending on their location, reported energy news website BJX News. From 2026, provinces will raise the tariff to “no less than 50%” of the 330 yuan benchmark. A representative from the state-owned China Energy Investment Group wrote in power sector outlet Dianlian News that the policy will adjust the role of coal-fired power units in the power system from “being primarily quantity providers to becoming capacity providers”.
REFORM LAG? Economic news outlet Jiemian quoted the NDRC as saying the policy will have a “positive impact on the electricity costs for end-users in the short and long term”. However, the mechanism has major implications for market reforms, Anders Hove, a senior research fellow at Oxford Institute for Energy Studies told Carbon Brief. “The segregation of long-term contracts, spot markets and ancillary services markets already hinders the ability of market prices to convey investment signals,” he said. While the initial policy on a national electricity market design had suggested the possibility of a market-based capacity mechanism, China ultimately chose a flat capacity payment made only to coal, he added. David Fishman, a senior manager at energy consultancy the Lantau Group, posted on Twitter that it “could distort market signals, which would ordinarily force expensive or inefficient generators out of the market”. Still, Reuters quoted Fishman saying: “It adds a lot of flexibility to the grid system and should allow more intermittent generation (like wind or solar) to enter the generation mix without compromising grid stability or energy security.”
Spotlight
What does China’s new methane plan mean for its climate goals?
In November, China published its long-awaited plan to reduce methane emissions. Carbon Brief explores how effective the plan may be for the world’s largest emitter of methane.
What does the plan say?
The plan described China’s approach as to “control methane emissions in a scientific, rational and orderly manner”, with a specific focus on the energy, agriculture and waste sectors.
It included 20 “key tasks” in emissions monitoring, technological innovation, development of policy frameworks, global cooperation and other areas.
During the 15th five year plan period (2026-2030), monitoring and accounting of methane emissions will be “significantly enhanced”, it added. Methane utilisation, emissions control technologies and policy frameworks will be “effectively improved”.
Other notable pledges included that by 2030 oil and gas producers will “strive” to “gradually” eliminate flaring, and utilisation of coal mine methane will reach 6bn cubic metres annually.
(This “corresponds to about 10%” of the coal mining sector’s total methane emissions, said Lauri Myllyvirta, lead analyst at Centre for Research on Energy and Clean Air (CREA).)
Where do methane emissions come from in China?
China is responsible for 10% of all human-caused methane emissions, with two estimates in 2021 placing its annual output at 58m tonnes (Mt) and 65Mt respectively, equivalent to 1.7-1.9bn tonnes of carbon dioxide (CO2) equivalent.
Around 40% of China’s methane emissions are gas that escapes during the mining of coal, according to the Innovative Green Development Program (iGDP), a Chinese thinktank. Another 42% is from agriculture, including livestock and rice cultivation, it said.
Coal mine methane emissions are particularly challenging to detect, according to the International Energy Agency (IEA), as they are “diffuse”. It added that abandoned mines, which could contribute “almost one fifth” of global methane emissions, cannot be included in calculations as “reliable data” is often unavailable.
Climate Home reported, however, that according to Global Energy Monitor (GEM) research, “the real figure for coal mine methane is almost double what the government claims”. Shanxi province could emit as much methane from its coal mines as the rest of the world combined, according to GEM.
Why is tackling methane important?
Methane is a potent greenhouse gas, with around 30 times the warming power of carbon dioxide 100 years after it is emitted. It is responsible for around 30% of the rise in global temperatures since the industrial revolution.
Cutting methane by 30% by 2030 – the target of the global methane pledge – is the “fastest way to reduce near-term warming” and keep 1.5C “within reach”, according to a US and EU factsheet.
Will China’s plan be effective in curbing emissions?
The Environmental Defense Fund (EDF) wrote on WeChat that it believed “in the long term”, the plan will provide “a clear guiding framework” for methane reduction efforts.
It pointed to the role the plan could play in establishing a monitoring, reporting and verification (MRV) system that could underpin a carbon pricing methodology for methane.
Dr Chen Meian, program director and senior analyst at iGDP, tells Carbon Brief that some of the “sector-specific targets mentioned in the methane plan can help China to reduce methane emissions” in coalbed methane and other areas.
However, she added, it is “difficult” to set hard targets for cutting emissions by specific amounts, due to challenges in data monitoring, “[which is why] China also listed the improvement of methane emissions MRV” as a key task.
Others are less convinced. The plan is “too ambiguous”, “descriptive” and lacking in quantitative targets, Refinitiv lead carbon analyst Yan Qin told Reuters.
Ember’s methane analyst Anatoli Smirnov told Climate Home that the “only real solution to reduce methane emissions is to close coal mines”. The outlet also quoted CREA’s Myllyvirta saying there is a lack of “political will and buy-in” to curb methane in China.
“I think China is trying to be realistic in target-setting [for its] coal sector emissions,” Chen tells Carbon Brief. She adds that China “used to set ambitious targets” for coalbed methane capture and utilisation in its five-year plans, but that it repeatedly missed them.
She added that it would be important for local governments to “set their own methane plans…tailored to local conditions” and to improve data monitoring.
What does this mean for global cooperation on methane?
A week after the plan was released, the US and Chinese climate envoys John Kerry and Xie Zhenhua issued a declaration on enhancing climate cooperation, known as the “Sunnylands statement”.
It included commitments to establish a working group that will look at several areas of cooperation, including methane emissions, and to create another working group to focus on “building on” their current national methane plans.
In addition, they commit to include “actions/targets” on methane reduction in their next climate pledges under the Paris Agreement, which will also cover other non-CO2 greenhouse gases. They will host, with the UAE, a summit on non-CO2 gases at COP28.
Without the plan’s public release, Li Shuo, director of the China climate hub at the Asia Society Policy Institute told Bloomberg, there “certainly wouldn’t have been further deals”.
However, differences in the sources of the US and China’s methane emissions could hamper cooperation. Dr Teng Fei, deputy director of the Institute of Energy, Environment and Economy at Tsinghua University, told China Dialogue that the main source of EU and US methane emissions is oil and gas, compared to coal mining for China.
Tackling coal mining methane emissions is harder and more costly than oil and gas. This could be why China has not signed up to the global methane pledge, which may be easier for the EU and US to meet, Teng added.
Watch, read, listen
COAL ADDICTION: Michael Davidson, assistant professor at the University of California, San Diego, explained in Foreign Affairs how “the need for energy security, the structure of China’s climate goals and…local interests” keeps China committed to coal, even though it “makes little financial sense”.
SOLAR DEBATE: In a video interview, Wall Street Journal reporter Phred Dvorak outlined how different countries are responding to dropping prices of Chinese solar panels in an effort to protect their own manufacturers.
EV RACE: Bloomberg published a podcast looking into how China became the dominant player in the electric vehicle industry, and what this could mean for the global economy.
GREEN BRI: A symposium summarised in Environmental Politics examined how environmental governance is practised in China’s belt and road initiative (BRI), with focus areas including China’s political mechanisms to “green” the BRI and the dynamics influencing the effectiveness of BRI renewable energy projects.
SUPPLY CHAIN RISKS? The Royal United Services Institute assessed the threat of China’s “near monopoly” of rare earth production and manufacturing of “net zero technologies”, finding that risks are “currently limited by low levels of manufacturing of these technologies in the UK”.
New science
Weather and Climate Extremes
A new study estimated that “compound” extreme weather events under a high-emissions scenario may become “10 times and 14 times more likely” through the mid-21st century and end of the century respectively. The study authors used the compound event of heavy precipitation and heatwaves in China in 2020 to identify the dynamic and thermodynamic factors contributing to the such events. They defined spatially compounding events as those occurring “when multiple connected locations are concurrently affected by the same or different hazards, thus inducing an aggregated impact”.
Global Change Biology
New research investigating recent trends in blooms of microalgal “red tides” and macroalgae in China found that microalgal blooms have been decreasing in frequency since 2003, while macroalgal blooms have generally been rising since 1999. It attributed the growth of macroalgae around China over the past 30 years to “eutrophication, climate change and grazing stress”, which it said indicated “a fundamental change in coastal systems in the region”.
China Briefing is compiled by Anika Patel and edited by Wanyuan Song and Simon Evans. Please send tips and feedback to china@carbonbrief.org.
The post China Briefing 16 November: Sunnylands statement; China methane plan; Coal capacity payments appeared first on Carbon Brief.
China Briefing 16 November: Sunnylands statement; China methane plan; Coal capacity payments

A temporary breach of the 1.5C global-warming limit is now “inevitable” following “decades of insufficient climate action”, says the UN Environment Programme (UNEP).
In its “sobering” annual assessment of the global “emissions gap”, UNEP says that exceeding the Paris Agreement’s 1.5C limit is “imminent and unavoidable”.
This year’s report, titled “The point of return”, says the “task now” is to minimise the size and scale of a temperature “overshoot” and to “establish a credible return path to 1.5C by the end of the century”.
Even the “lowest possible” overshoot scenario for 1.5C would first see global warming peak at around 1.7-1.8C in the middle of the century before declining, says the report.
This scenario – which is “still aligned with the long-term temperature goal of the Paris Agreement” – would require global emissions cuts of 18% by 2030 and 45% by 2035, while ramping up “removals” of carbon dioxide (CO2) from the atmosphere, says UNEP.
In contrast, it notes that the current climate pledges by countries around the world – even if fully implemented – would only reduce emissions by 5-8% by 2030 and 11-15 % by 2035, relative to 2025 levels.
Nonetheless, the report identifies “ample opportunity to accelerate action”, concluding that “countries can still limit peak warming, shorten the duration of overshoot and keep the goals of the Paris Agreement within reach”.
(See Carbon Brief’s detailed coverage of previous reports in 2014, 2015, 2016, 2017, 2018, 2019, 2020, 2021, 2022, 2023, 2024 and 2025.)
Emissions ‘comparable’ between 2024 and 2025
The report says that emissions in 2025 were “comparable” to those of 2024.
Global greenhouse gas emissions in 2025 totalled 58.4bn tonnes of CO2 equivalent (GtCO2e), according to the report. This is around 0.16GtCO2e lower than 2024 levels – albeit, with high levels of uncertainty around the numbers.
In addition, because the figures presented in the 2025 report are “provisional”, the report says, it is “not possible to conclude on the overall direction of emissions in 2025”.
The emissions growth rate has been slowing down in recent decades: the growth rate over 1990-2015 was, on average, 1.7% per year, while emissions have increased by an average of 0.8% per year since 2016.
The chart below shows the total human-driven emissions between 1990 and 2025, separated by greenhouse gas: CO2 from fossil-fuel combustion (dark grey), methane (light grey), nitrous oxide (blue), fluorinated gases (orange) and CO2 from land-use change (green).
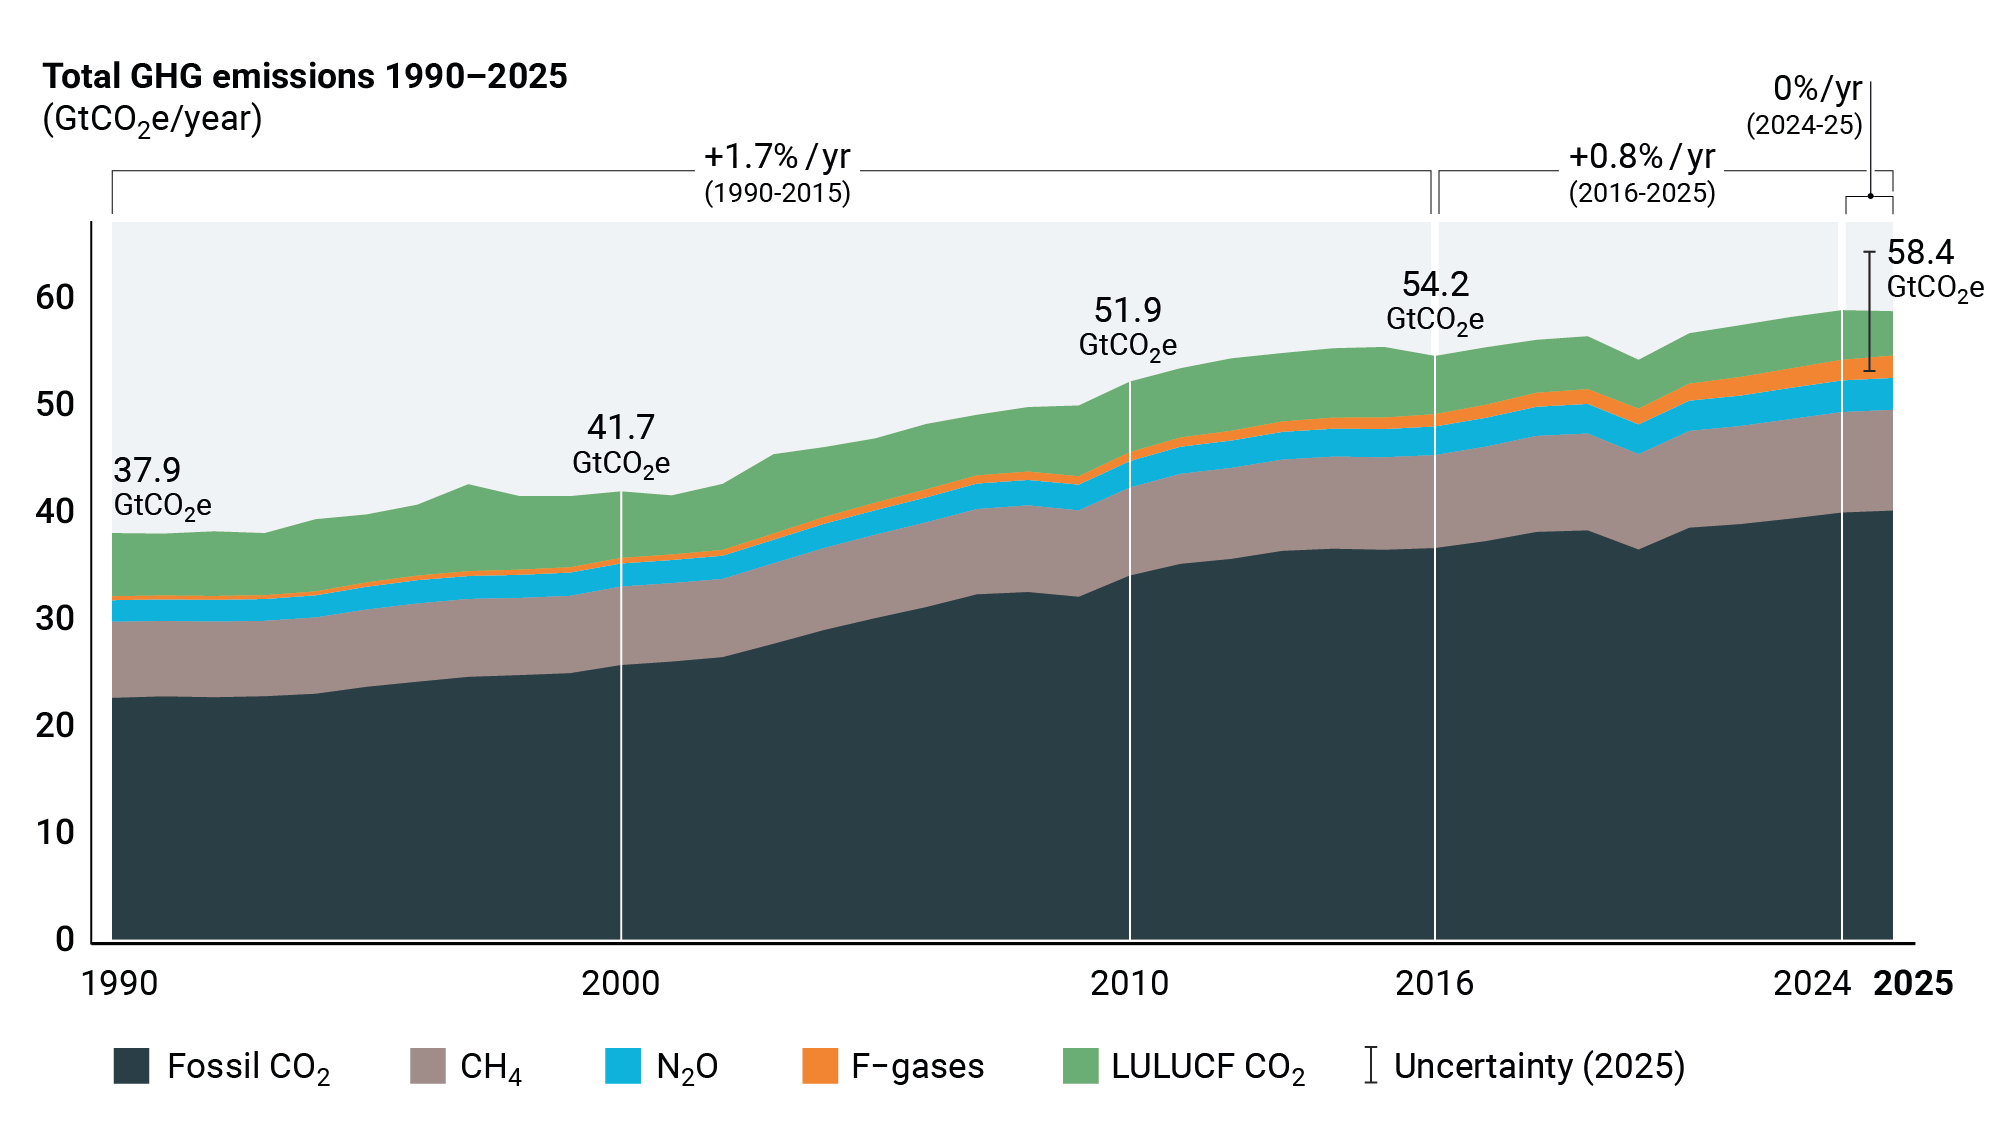
Compared to 2024, emissions from fossil fuels increased slightly, by between 0.4-1.1%, says the report. Emissions of both nitrous oxide and fluorinated gases increased by even higher rates, but since these comprise such a small part of total greenhouse gas emissions, “their contribution to the overall trend is relatively less significant”, it adds. Methane emissions remained steady over that time.
A reduction in the CO2 emissions from land use, land-use change and forestry (LULUCF) “slightly overcompensates” for the rise in emissions of fossil-fuel CO2 and other gases, according to the report. (For more on falling land-use emissions, see Carbon Brief’s explainer.)
The decrease in LULUCF emissions was “partially driven” by a decline in global wildfire emissions, particularly in Africa, South America and parts of south-east Asia. The report notes that these decreases were “likely connected to the ceasing of El Niño conditions”. The ongoing “super” El Niño is likely to cause LULUCF emissions to increase in 2026.
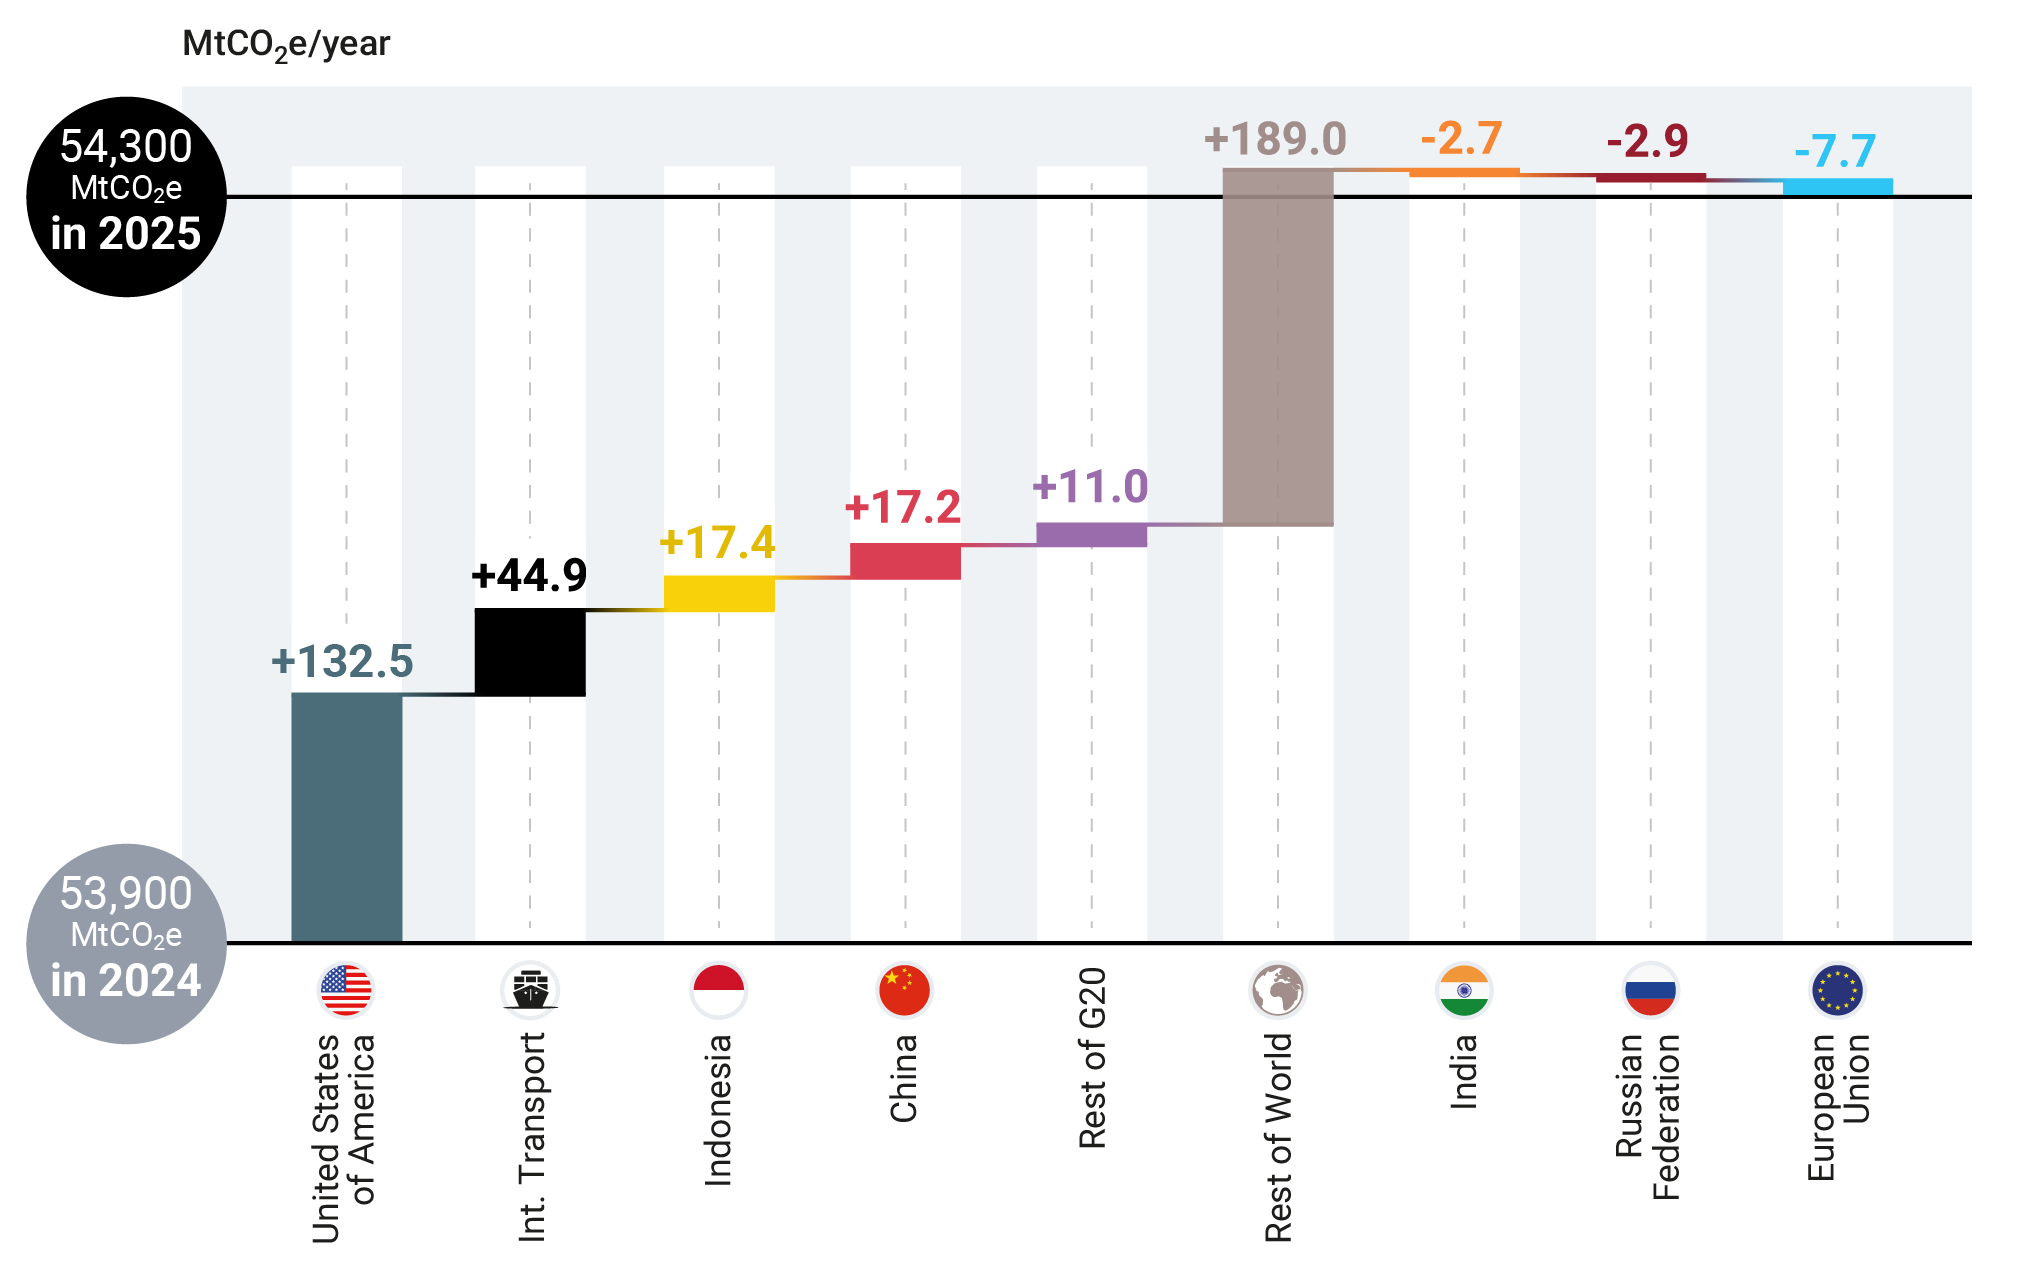
The report also examines countries’ contributions to the increase in greenhouse gas emissions – although here, it excludes LULUCF due to a lag in national-level emissions inventories for the sector.
Among the top six emitters, only the US saw a notable increase in 2025, says the report, whereas emissions in China, the EU, India, Russia and Indonesia were relatively flat. Emissions in the US grew by 133m tonnes of CO2e (MtCO2e) in 2025, due to increased electricity demand and a “rebound” of coal power. This growth in US emissions is likely due to a combination of market factors, including increased heating demand due to a colder winter, higher gas prices and overall increased electricity demand.
The changes for the six largest emitters, the rest of the G20 countries, international transport and the rest of the world can be seen in the chart below.
Across most sectors, progress towards decarbonisation has been “modest”, says the report. The most notable decreases have occurred in the power sector and the transport sector, due to the growth of solar power and electric vehicles. The report notes:
“There are emerging signs of transport sector electrification and decarbonisation, but at rates and levels that are not yet sufficient to drive emissions reductions at the global level.”
However, emissions from the transport sector have continued to grow, due to increased demand for international aviation and shipping.
The report notes that while electricity demand from data centres is “projected to double” by 2030, data centres at present account for less than 1% of total emissions.
New NDCs would reduce emissions ‘far from what is needed’
All countries were meant to submit new UN climate pledges for 2035, known as the third nationally determined contributions (NDCs) to the Paris Agreement, by February 2025. However, 95% of nations missed this deadline.
Many countries came forward with their third NDCs at a UN climate summit in New York in September 2025 and at the COP30 climate summit in Brazil in November 2025.
By the end of COP30, 122 – or 63% – of countries had produced their third NDCs.
The report says that figure had risen to 124 by 1 September 2026, with pledges now covering 75% of global emissions.
This is more than double the number of third NDCs available at the time of the 2025 emissions gap report – allowing a “more robust basis