

UK government targets for “sustainable aviation fuels” (SAFs) will only cut emissions from the sector to 0.8% below current levels in 2040, Carbon Brief analysis shows.
From 2025, flights taking off from the UK must use a fixed share of SAFs, which are largely made from waste products. This share will gradually rise from 2% next year to 22% in 2040.
The government says its “SAF mandate” will cut aviation emissions by 6.3m tonnes of carbon dioxide equivalent (MtCO2e) in 2040.
However, Carbon Brief analysis of government forecasts shows this being almost entirely wiped out by rising demand for air travel, meaning emissions would only fall by 0.8% overall.
The SAF mandate is the most substantial policy to date under the UK government’s “jet-zero” strategy for decarbonising air travel, which eschewed efforts to limit demand. The mandate relies heavily on fuels made from used cooking oil and other waste products, which are in limited supply.
No change
The SAF mandate will require jet fuel suppliers to ensure that an increasing share of the product they supply is “sustainable”. This is meant to encourage investment in new facilities to produce SAFs.
Fuels described as SAFs include those made from waste, such as used cooking oil, household waste and offcuts from the forestry sector.
Despite their name, SAFs produce just as many emissions as fossil fuels when burned to power planes.
However, they generally – although not always – have a lower overall “lifecycle” carbon footprint than petroleum-based jet fuel. This is due to CO2 emissions absorbed from the atmosphere when growing plants for biofuels, or emissions that are avoided by diverting waste products to be used as fuels.
These emissions savings are counted towards the UK’s aviation sector as a whole.
(The government says that, for the time being, it will not support SAFs made directly from crops, which tend to have relatively high carbon footprints due to changes in land use.)
The new UK mandate starts in 2025 with a requirement that 2% of total jet fuel demand is SAF, increasing to 10% in 2030 and 22% in 2040. The government says there is currently not enough certainty in the SAF market to set targets beyond that date.
These measures will cut overall aviation emissions by 2.7MtCO2e in 2030 and 6.3MtCO2e in 2040, according to the government.
Based on government forecasts for jet fuel use, this change will be almost totally offset by a growth in flights, leaving UK aviation emissions virtually unchanged between now and 2040.
Emissions in 2025 are expected to be 36.0MtCO2e, while 15 years later they are set to be 35.7MtCO2e, according to Carbon Brief analysis. This is a drop of just 0.3MtCO2e, or 0.8%. This is illustrated in the chart below, with the SAF mandate merely preventing an increase in emissions resulting from higher jet fuel use in 2040.
These figures are derived from the government’s “central case”, cited in its underlying analysis for the SAF mandate, which sees jet fuel use increasing from 11.5m tonnes (Mt) in 2025 to 13.3Mt in 2040. This, in turn, is based on policies in the government’s “continuation of current trends” scenario, with the SAF mandate included.

The government expects far more flights to take off from the UK in the coming years, resulting in higher jet fuel use. It has resisted pressure to curb the demand for air travel, despite warnings from experts that such actions are vital for reducing aviation emissions.
In its jet-zero strategy, the government stated that it is aiming for a “high ambition” scenario, which would see aviation emissions fall faster in the coming years. However, as it stands, it has not introduced policies to drive further emissions reductions in planes.
The SAF mandate assumes that SAFs reduce lifecycle emissions from jet fuel by 70%. Certificates will be issued to fuel suppliers for each tonne of SAF produced, using this baseline emissions reduction goal as the standard.
However, Prof Bill Rutherford, an Imperial College London biochemist who contributed to two major assessments of low-carbon aviation fuels in the UK last year, tells Carbon Brief he is sceptical about lifecycle emissions analysis that shows such high emissions benefits:
“Lifecycle analysis is a very fuzzy science…You can basically get what you want out of it.”
For example, in its analysis, the government assumes that SAFs made from used cooking oil – which are expected to make up virtually the entire UK supply in the short-term – cut lifecycle emissions by roughly 95-98% compared to conventional jet fuel.
Dr Andrea Fantuzzi, another Imperial College London chemist who also worked on the low-carbon fuel assessments with Rutherford, says such figures seem “way too high”. He estimates that the savings would be closer to 70%.
Fantuzzi adds that even this does not account for the land originally used to produce the oil, and assumes that the oil would otherwise be thrown away – rather than used to power road vehicles, for example. (For more on waste oils, see: More cooking oil.)
Additionally, Rutherford points out that the use of SAFs has no impact on non-CO2 emissions from planes, which could account for up to two-thirds of their climate impact. He concludes:
“The only way you can make aviation any more sustainable is to do less of it.”
More cooking oil
The only SAFs that are currently available in the UK are fuels made from used cooking oil and other waste oils, which are collected from restaurants and factories.
However, the SAF mandate includes a limit on the amount of waste oil-based fuels within its overall targets. This is partly to “incentivise the development of new technologies” and partly due to concerns that waste oil supplies will be insufficient.
For the first two years, these fuels will be allowed to make up 100% of UK SAFs. This then falls to 71% in 2030 and 33% in 2040. Overall, waste oil-based SAFs would account for 2% of total jet fuel use in 2025 and up to 7.8% in 2040.
Despite these limits, waste oil-based SAF use is expected to rise around 15-fold from current levels within a decade. This huge increase in demand for waste cooking oil under the SAF mandate is illustrated in the figure below.

The Aviation Environment Federation said in a statement that the amount of waste oil being allowed into UK jet fuel under the UK’s SAF mandate is “much higher than we, and many others, were expecting, and appears to be the result of airline pressure”. The looser cap on these fuels was “welcomed” by industry body Airlines UK.
It raises the question of where the UK will source the required volume of waste oil to meet SAF targets.
Studies have shown that there is nowhere near enough waste cooking oil produced domestically, within the UK, to supply jet fuel demand. “We’re not about to start eating more chips, so we will have to start importing more waste oil,” Matt Finch, UK policy manager at the NGO Transport and Environment, tells Carbon Brief.
The government itself acknowledges this, saying that production of these SAFs within the UK is likely to be constrained by the availability of waste cooking oil from 2029 onwards.
It notes that their availability will therefore be “highly dependent” on how much waste oil the UK can import.
As of 2023, waste cooking oil collected in the UK only accounted for 7% of the country’s SAF production. This share has shrunk in recent years, such that imports from other countries – particularly China – have driven most of the growth in production, as the chart below shows.

There is mounting evidence that the demand for imported cooking oil in the UK and Europe is being met with virgin palm oil that has been fraudulently passed off as waste. This would cancel out the fuel’s emissions savings, due to the land clearances for oil palm plantations.
The UK’s aviation sector will have to compete not only with other countries for a limited pool of waste cooking oil, but also with other sectors.
Most of the UK’s waste cooking oil supplies are currently used to make biofuels for trucks and other road transport. Again, diverting resources from road fuel use would undermine the emissions savings from using them in SAFs.
The government acknowledges this, noting that “the SAF mandate may divert feedstocks which would have been utilised in other sectors of the economy and this may increase emissions in other sectors”. However, it says this is justified because “there are limited alternatives to decarbonise aviation by 2050”.
One of the scenarios modelled by the government assumes that SAF targets are met, but insufficient waste cooking oil means there is not enough biodiesel for road vehicles. This reduces the cumulative emissions savings between 2025-40 from 53.9MtCO2e to 43.0MtCO2e.
New fuels
The government is also supporting new types of SAF production in the UK, including fuels made from “black bin bag waste” and residues from farming or forestry.
In the newly released documents, the government says the UK will be a “leader” and a “first mover” in these technologies, spurred on by the cap on waste oil fuels and supported by the Advanced Fuel Fund.
Unlike waste oil-based fuels, the government says there will be “sufficient” materials available to meet production demand for these advanced fuels until at least 2040. From that point onwards, it says lack of materials “may become a constraining factor”.
However, a 2023 report by the Royal Society highlighted the limited availability of some waste materials to produce SAFs. It estimated that forest offcuts, for example, would be able to provide no more than 1.7% of current jet fuel demand.
Moreover, many waste sources are already recycled or burned to generate electricity and the government has targets in place to cut household waste in the coming years. “Most waste is already used for something that’s not jet fuel, so we know supplies of waste-based SAF will be limited,” Finch tells Carbon Brief.
Finally, the government’s mandate also includes another target, within the overarching SAF goal, for scaling up the production of “power-to-liquid” fuels.
These fuels can be made using green hydrogen and carbon captured from the air. Unlike most SAFs, they could cut up to 100% of CO2 emissions compared to conventional jet fuel, but they are currently less developed than other options.
The target for power-to-liquid fuels will start in 2028 at 0.2% of total jet fuel demand, reaching 0.5% in 2030 and 3.5% in 2040.
These targets are lower than the ones introduced in the EU, which is aiming for 35% of its jet fuel to be power-to-liquid by 2050. The bloc is also targeting 70% of aviation demand to be met with SAFs by 2050, whereas the UK’s targets stop at 22% by 2040.

In its “balanced net-zero pathway” for UK aviation, government advisors the Climate Change Committee (CCC) proposed that SAFs should make up 25% of jet fuel by 2050, with one-third of this made up of power-to-liquid fuels – roughly 8% of total jet fuel. The government targets are roughly in line with this trajectory.
Thinktank Green Alliance laid out three scenarios for SAF expansion in 2022, including higher ambition goals, with power-to-liquid fuels reaching 28% and 50% of total jet fuel by 2050.
However, it noted that such a rollout could be constrained by the large amounts of additional green hydrogen and renewable power required to produce these fuels.
The report stated:
“It could be argued that aviation should not be a priority use of renewables as there are other options to cut carbon in the sector, such as managing the number of flights taken.”


The post Analysis: Benefits of UK ‘sustainable aviation fuel’ will be wiped out by rising demand appeared first on Carbon Brief.
Analysis: Benefits of UK ‘sustainable aviation fuel’ will be wiped out by rising demand

Israel’s bombardment of Gaza during the conflict that broke out in October 2023 has wrecked progress towards adapting the enclave to climate change and left two million Gazans vulnerable to heatwaves, drought and disease, the Palestinian Authority (PA) said in a new climate plan submitted to the United Nations.
Palestine’s third nationally determined contribution (NDC), uploaded to the UN climate body’s website this week, says that while “the aggression on the Gaza Strip did not make the climate worse”, “it removed the housing, water and sanitation systems, health facilities, energy networks, roads and livelihoods through which people absorb a climate they were already struggling with.”
The 91-page document lists the types of infrastructure it says Israel has destroyed and notes how the destruction will worsen the impacts of climate change. It says the bombing of hospitals and rising hunger have make it harder for Gazans to cope with the health impacts of climate-driven heatwaves and waterborne diseases.
The destruction of water tanks, boreholes and desalination plants, meanwhile, have left Gazans struggling with the effects of water shortages and drought, while mass unemployment reduces people’s ability to afford climate-driven price rises. The erasure of most of the Strip’s homes makes it more difficult for people to avoid the sun’s increasing heat, the NDC said.
Many Gazans are now living in the ruins of collapsed buildings or in makeshift shelters and tents that offer little or no protection from high temperatures.
Palestine’s previous goals to cut emissions and adapt to climate change in Gaza, expressed in its last NDC five years ago, were based on a pre-war baseline that “no longer describes anything that exists”, the NDC says. Progress made since 2021 has now been destroyed, it adds.
Green reconstruction of Gaza
Instead of continuing to aim for these adaptation and emissions-reduction goals, the PA is now calling for the green reconstruction of Gaza. It says buildings should be constructed again in an energy-efficient manner with solar panels and served with modern water, waste and transport systems.
While the PA, controlled by the Fatah political party, continues to claim legitimate control of Gaza, the strip was effectively governed by Fatah’s rival Hamas between 2007 and the recent war. Control is now split between Israel and the political wing of Islamist militant group Hamas, after a US-backed ceasefire took effect in October 2025, although a UN-backed committee plans to take over.
-
Germany uses funding to pressure climate groups on Israel-Gaza war
Many Global South climate groups are funded by the German government, a political ally of Israel, and feel unable to criticise Israel’s military action in Gaza -
Loss and damage fund urged to hold crisis meeting on Nepal
The new fund is coming under pressure from developing nations to respond quickly to climate disasters rather than just financing longer-term projects -
More support needed to power Africa’s food systems with renewables, experts say
Renewable energy could help African food businesses boost productivity and competitiveness, but the upfront cost, fragmented markets and limited financing stand in the way

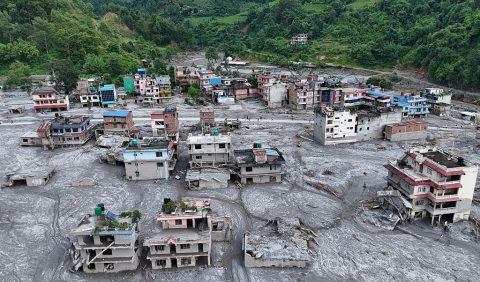

The United Nations, European Union and World Bank have jointly estimated that Gaza needs $71.4 billion of investment in the next two years to recover and build back. This process should be Palestinian-led, they said in April.
But US President Donald Trump has said the US should “take over” and “own” Gaza and redevelop it as the “Riviera of the Middle East”. Israel’s right-wing prime minister Benjamin Netanyahu has said that Israel should control the territory with civil administration managed by Palestinians favourable to Israel.
With occupation, targets conditional
In the other part of Palestine, the West Bank, the Palestinian Authority carries out some government functions, but ultimate control rests with Israel, which has occupied the West Bank since 1967.
Because Israel controls planning in most of the West Bank, the NDC argues that the PA cannot pursue all the climate projects it wants. In addition, Israel restricts the movement of PA officials, making data collection difficult, and controls the West Bank’s electricity supply meaning that the PA cannot control whether it comes from dirty or clean sources of energy.
Given this situation, the NDC says that all of Palestine’s new climate targets are conditional but it will aim to reduce emissions 12.8% below a business-as-usual baseline by 2035 and 17.1% by 2040. If the Israeli occupation ends and Palestine regains full sovereignty over its land and resources, it will aim for reductions of 15.1% and 19.1% by 2035 and 2040 respectively under an “independence pathway”.
That could allow, for example, for greater electrification and reducing emissions per unit of growth, the document said.
To achieve the 2035 emissions-reduction target and adapt to the impacts of climate change, the PA says it needs $8.6 billion in total. This funding would be spent on measures like encouraging solar farms and rooftop solar and scaling up solar water heating to cover four-fifths of households. To complement the planned increase in solar power, the authority wants to modernise the electricity grid and install battery storage.
In the transport sector, it aims to promote the uptake of electric vehicles, develop bus rapid transit corridors and scrap old polluting trucks and buses. In Gaza in particular, it wants to deploy 66 electric buses when the conflict ends.

To adapt to climate-driven drought, the NDC includes initiatives to reuse wastewater through treatment plants, build desalination plants in Gaza to remove salt from seawater, and promote irrigation for farmers.
The new climate plan was prepared by Palestine’s Environment Quality Authority, with support from the United Nations Development Programme and the governments of Britain and Spain.
The United Nations recognised Palestine’s statehood in 2012 and it joined the UN’s climate convention and signed the Paris climate agreement – which requires countries to submit more ambitious NDCs every five years – in 2016.
The Israeli foreign ministry did not respond to a request for comment. But in late 2024, then Israeli climate envoy Gideon Behar told Climate Home News that the war and the resulting environmental destruction in Gaza was the fault of Hamas.
The post Palestine: Israel’s bombing has left Gaza vulnerable to climate change appeared first on Climate Home News.
Palestine: Israel’s bombing has left Gaza vulnerable to climate change
Solar power generation in the UK reached a new record over the summer of 2026, as temperatures across the nation soared, according to new analysis by Carbon Brief.
Collectively over June, July and August, solar farms and rooftops generated 8.8 terawatt-hours (TWh) of electricity in the UK*, as shown in the chart below.
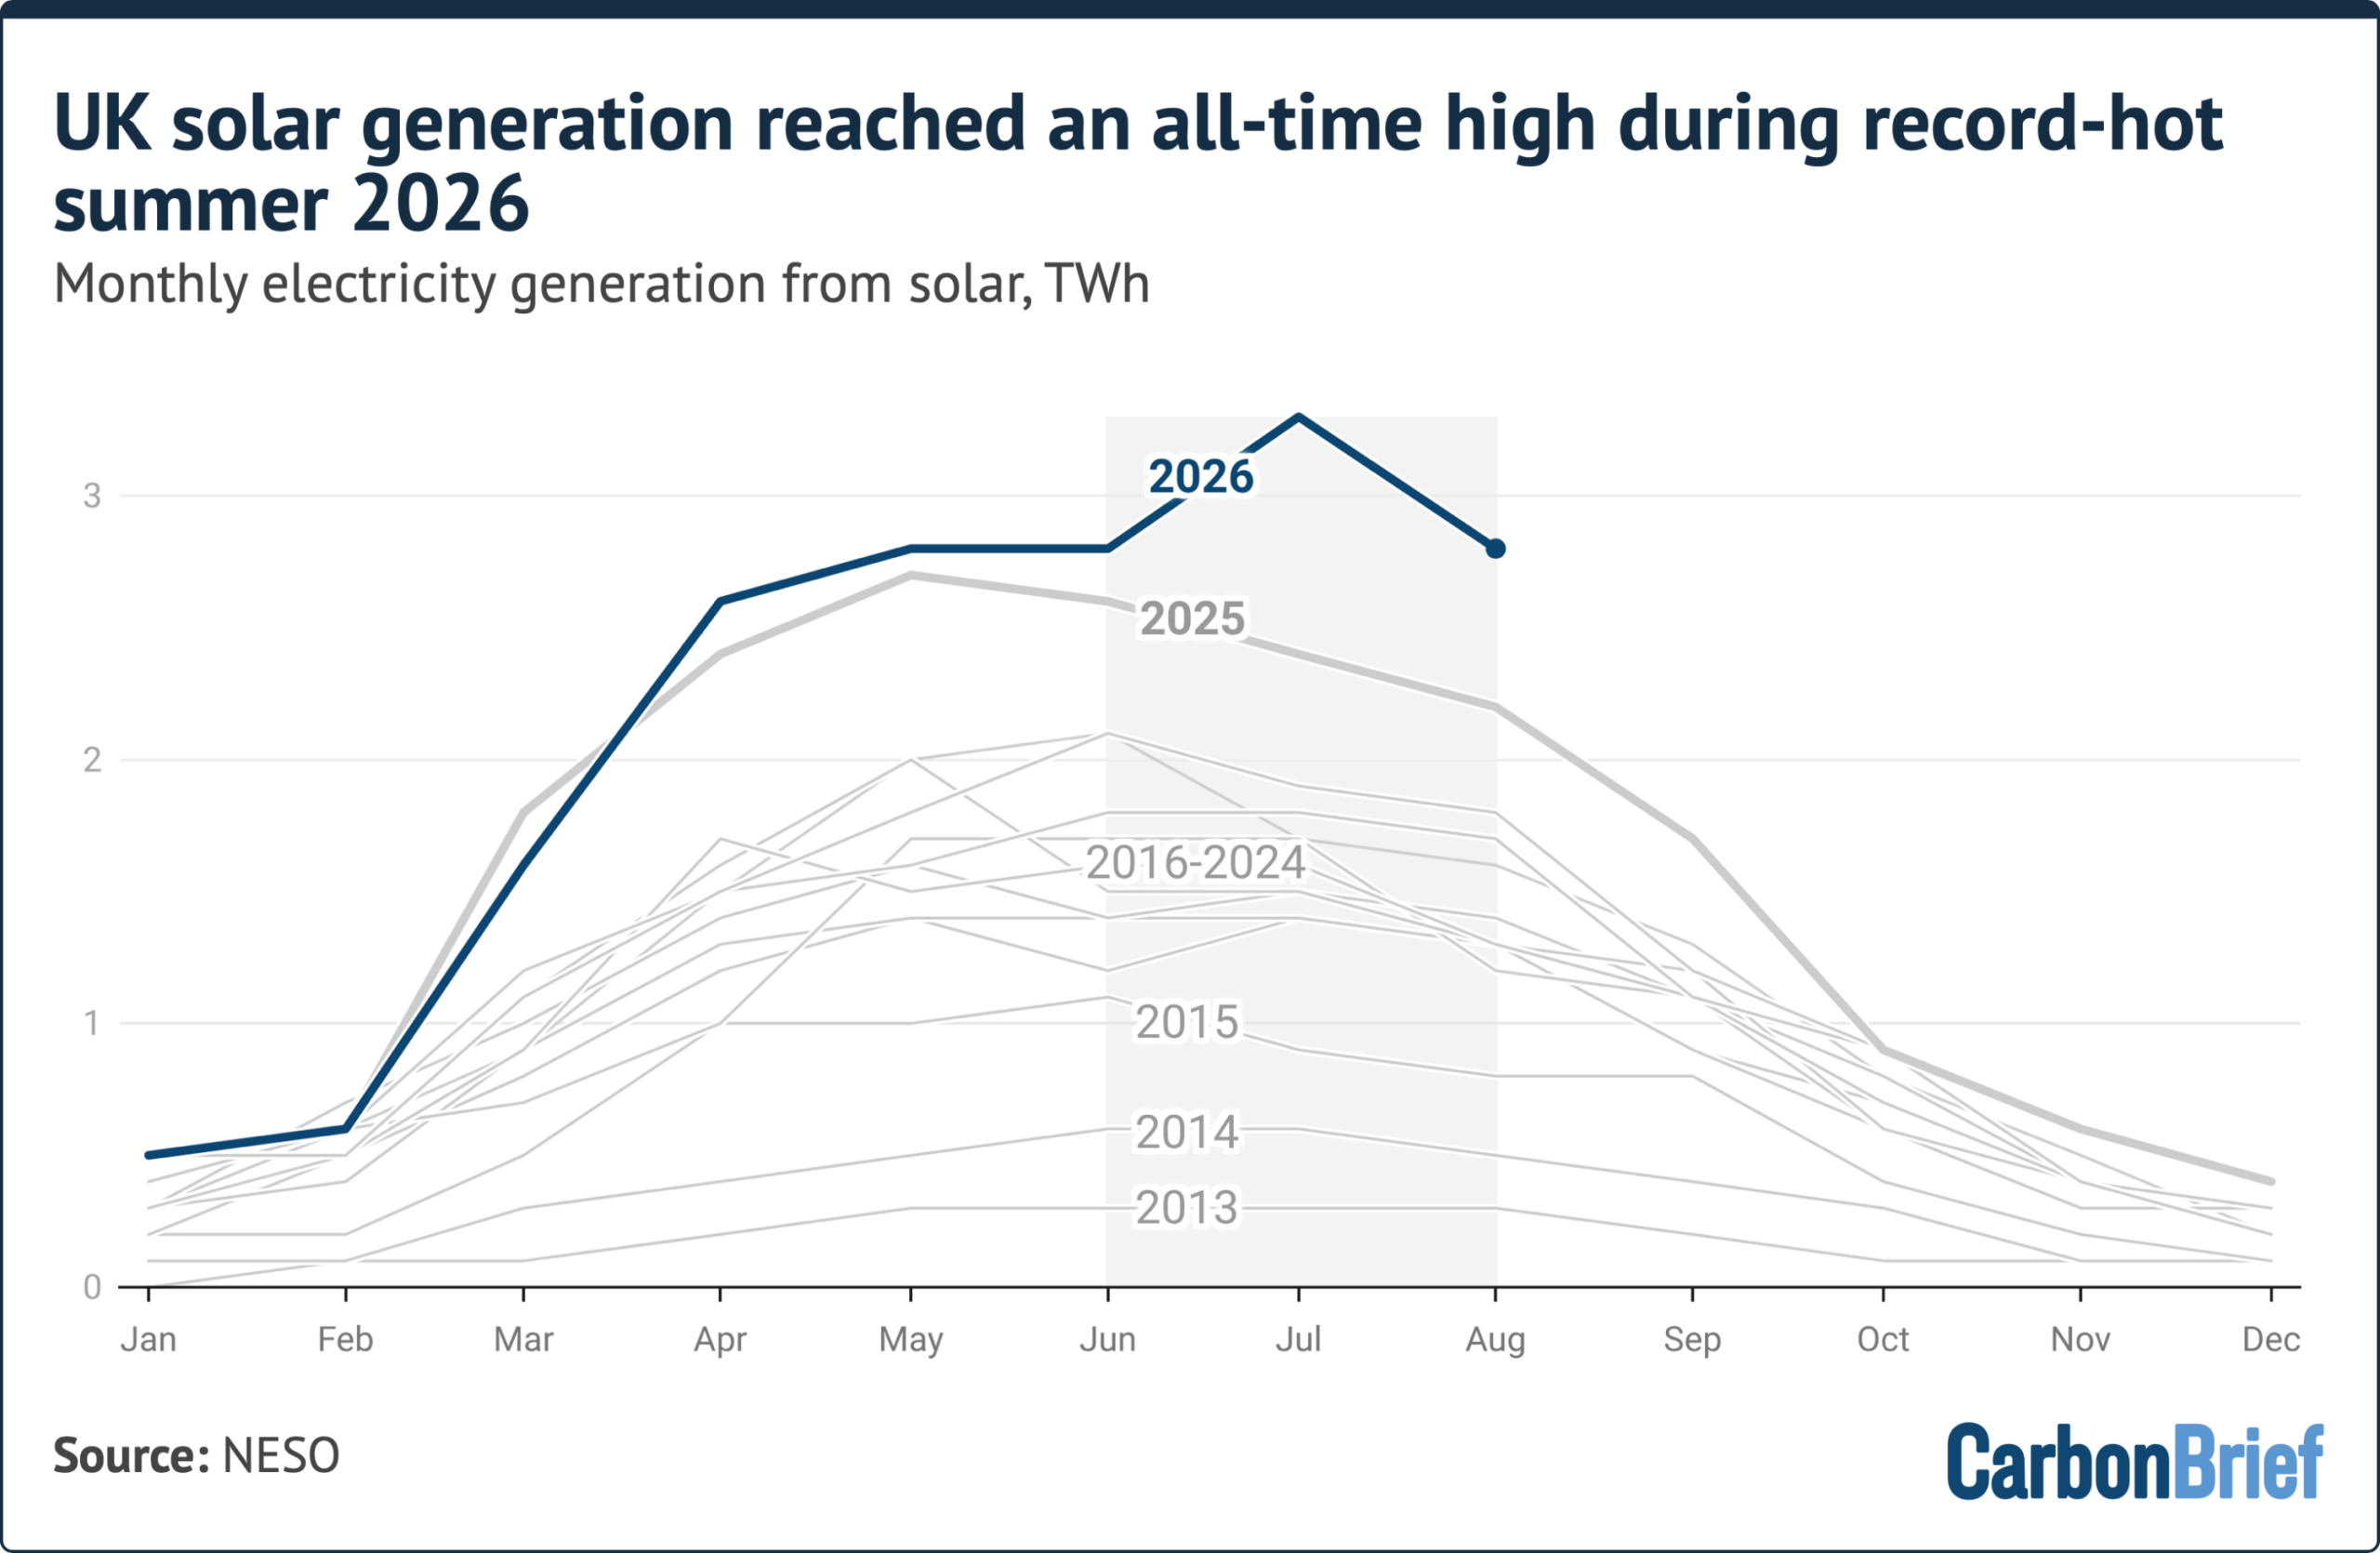
Speaking to Carbon Brief, Chris Hewett, chief executive of trade association Solar Energy UK welcomed the new record, adding that it was driven by “clear skies and continued growth in deployment”.
This surge in generation took place amid the hottest summer on record in the UK, with five heatwaves between May and August.
Summer 2026 was the sixth sunniest on record, with more than 620 hours of sunshine, according to the Met Office. England and Wales – which experienced the most extreme heat – saw their second-sunniest summers on record.
June 2026 was the hottest June in England since records began in 1884, according to Met Office data, while Wales and the UK as a whole experienced their second-warmest June.
It was the driest July for England and Wales since records began in 1836, with some parts of London seeing no rain at all in the month, while Wisley in Surrey had no rain for 62 days.
In England, temperatures peaked at 38.1C at Kew Gardens in London on 13 August.
According to the Met Office, this summer’s record mean temperature was made 130 times more likely by climate change.
Amid these hot and sunny months, solar power generation increased 23% from the same period in 2025. This is double the level of solar generation over the summer of 2021, according to Carbon Brief analysis.
While solar panels can be affected by periods of extreme heat, the longer hours of daylight and higher levels of irradiation over the summer more than offset any efficiency losses.
June, July and August all saw solar set new monthly records for solar generation – July saw the highest solar generation in a calendar month ever, with 3.3TWh meeting 15% of overall electricity demand for the month.
As of the end of August, the total UK solar generation in 2026 stood at 17TWh – 13% higher than the same point in 2025.
The number of solar farms and rooftop installations has grown substantially in recent years, helping to boost generation. Domestic rooftop solar accounts for around 29% of total capacity.
In 2025, the UK’s solar capacity reached 21 gigawatts (GW) by the third quarter of the year, according to UK government figures. This is a jump of 3GW, or 18%, year-on-year, as Carbon Brief reported in January.
(Capacity is the maximum output possible from an electricity generation, whereas generation is what was produced over a certain time period, such as a day, month or year.)
According to the University of Sheffield, the installed solar capacity is now nearly 24GW.
This includes nearly 172,000 solar installations that have been fitted across the UK since the start of 2026, according to recent government figures. In July alone, more than 19,800 rooftop solar panels were installed – the equivalent of one installation every two minutes.
In total, nearly 1.7m households in the UK now have solar panels installed.
Over 26 heatwave days this summer – periods of at least three days when temperatures exceed the Met Office’s county-level heatwave temperature threshold – UK households with rooftop solar panels avoided an estimated £86.7m in electricity costs, according to analysis by Utility Bidder.
Talking about the surge in solar generation this summer, Hewett says:
“[It] not only kept bills down for people with solar and batteries in their homes, but helped keep overall power prices much lower than they would have been if Britain had been relying on more gas generation during the day”.
Despite the record generation, no new half-hourly solar power output record was set in the summer of 2026. This still stands at 15.2 megawatts (MW) on 23 April 2026.
* This article refers to the UK throughout, but strictly relates to the island of Great Britain, made up of England, Scotland and Wales. Northern Ireland is part of the separate, all-Ireland electricity system.
related
Factcheck: 10 flaws in the Conservative report on ‘cheap power’
Q&A: What is ‘long-duration energy storage’ – and why does the UK need it?
Q&A: What does China’s 15th ‘five-year plan’ for renewables mean for climate change?
Analysis: Wind and solar power overtake fossil fuels in Germany for first time ever
The post Analysis: UK solar power hits record high over summer 2026 appeared first on Carbon Brief.
Farmers around Europe are dealing with the aftermath of a summer of extreme heat, drought and wildfires that were exacerbated by climate change.
Human-caused climate change is increasing the severity and likelihood of many extreme weather events around the world, which is increasing volatility for food producers.
This summer resulted in, for example, shrunken potatoes in the Netherlands, reduced carrot harvests in France, dried-up rice fields in Italy and scorched olive groves in parts of the Mediterranean region.
Global food prices are currently at their highest level since early 2023 due to “heatwaves and energy price dynamics”, according to the UN Food and Agriculture Organization.
Other factors such as blocked fertiliser supplies in the Strait of Hormuz and high fuel costs have also played a role in this year’s agricultural outputs.
In the six charts below, Carbon Brief provides a snapshot of the impact this summer’s extremes are considered to have had on crop production and yields across Europe.
1. Most EU countries expect to see declines in cereal production this year
2. Most countries are recording reduced crop yields
3. Around €2bn worth of cereal losses after June heatwave
4. UK yields of wheat, barley and oats are all due to drop in 2026
5. Maize production in France is due to hit a four-decade low
1. Most EU countries expect to see declines in cereal production this year
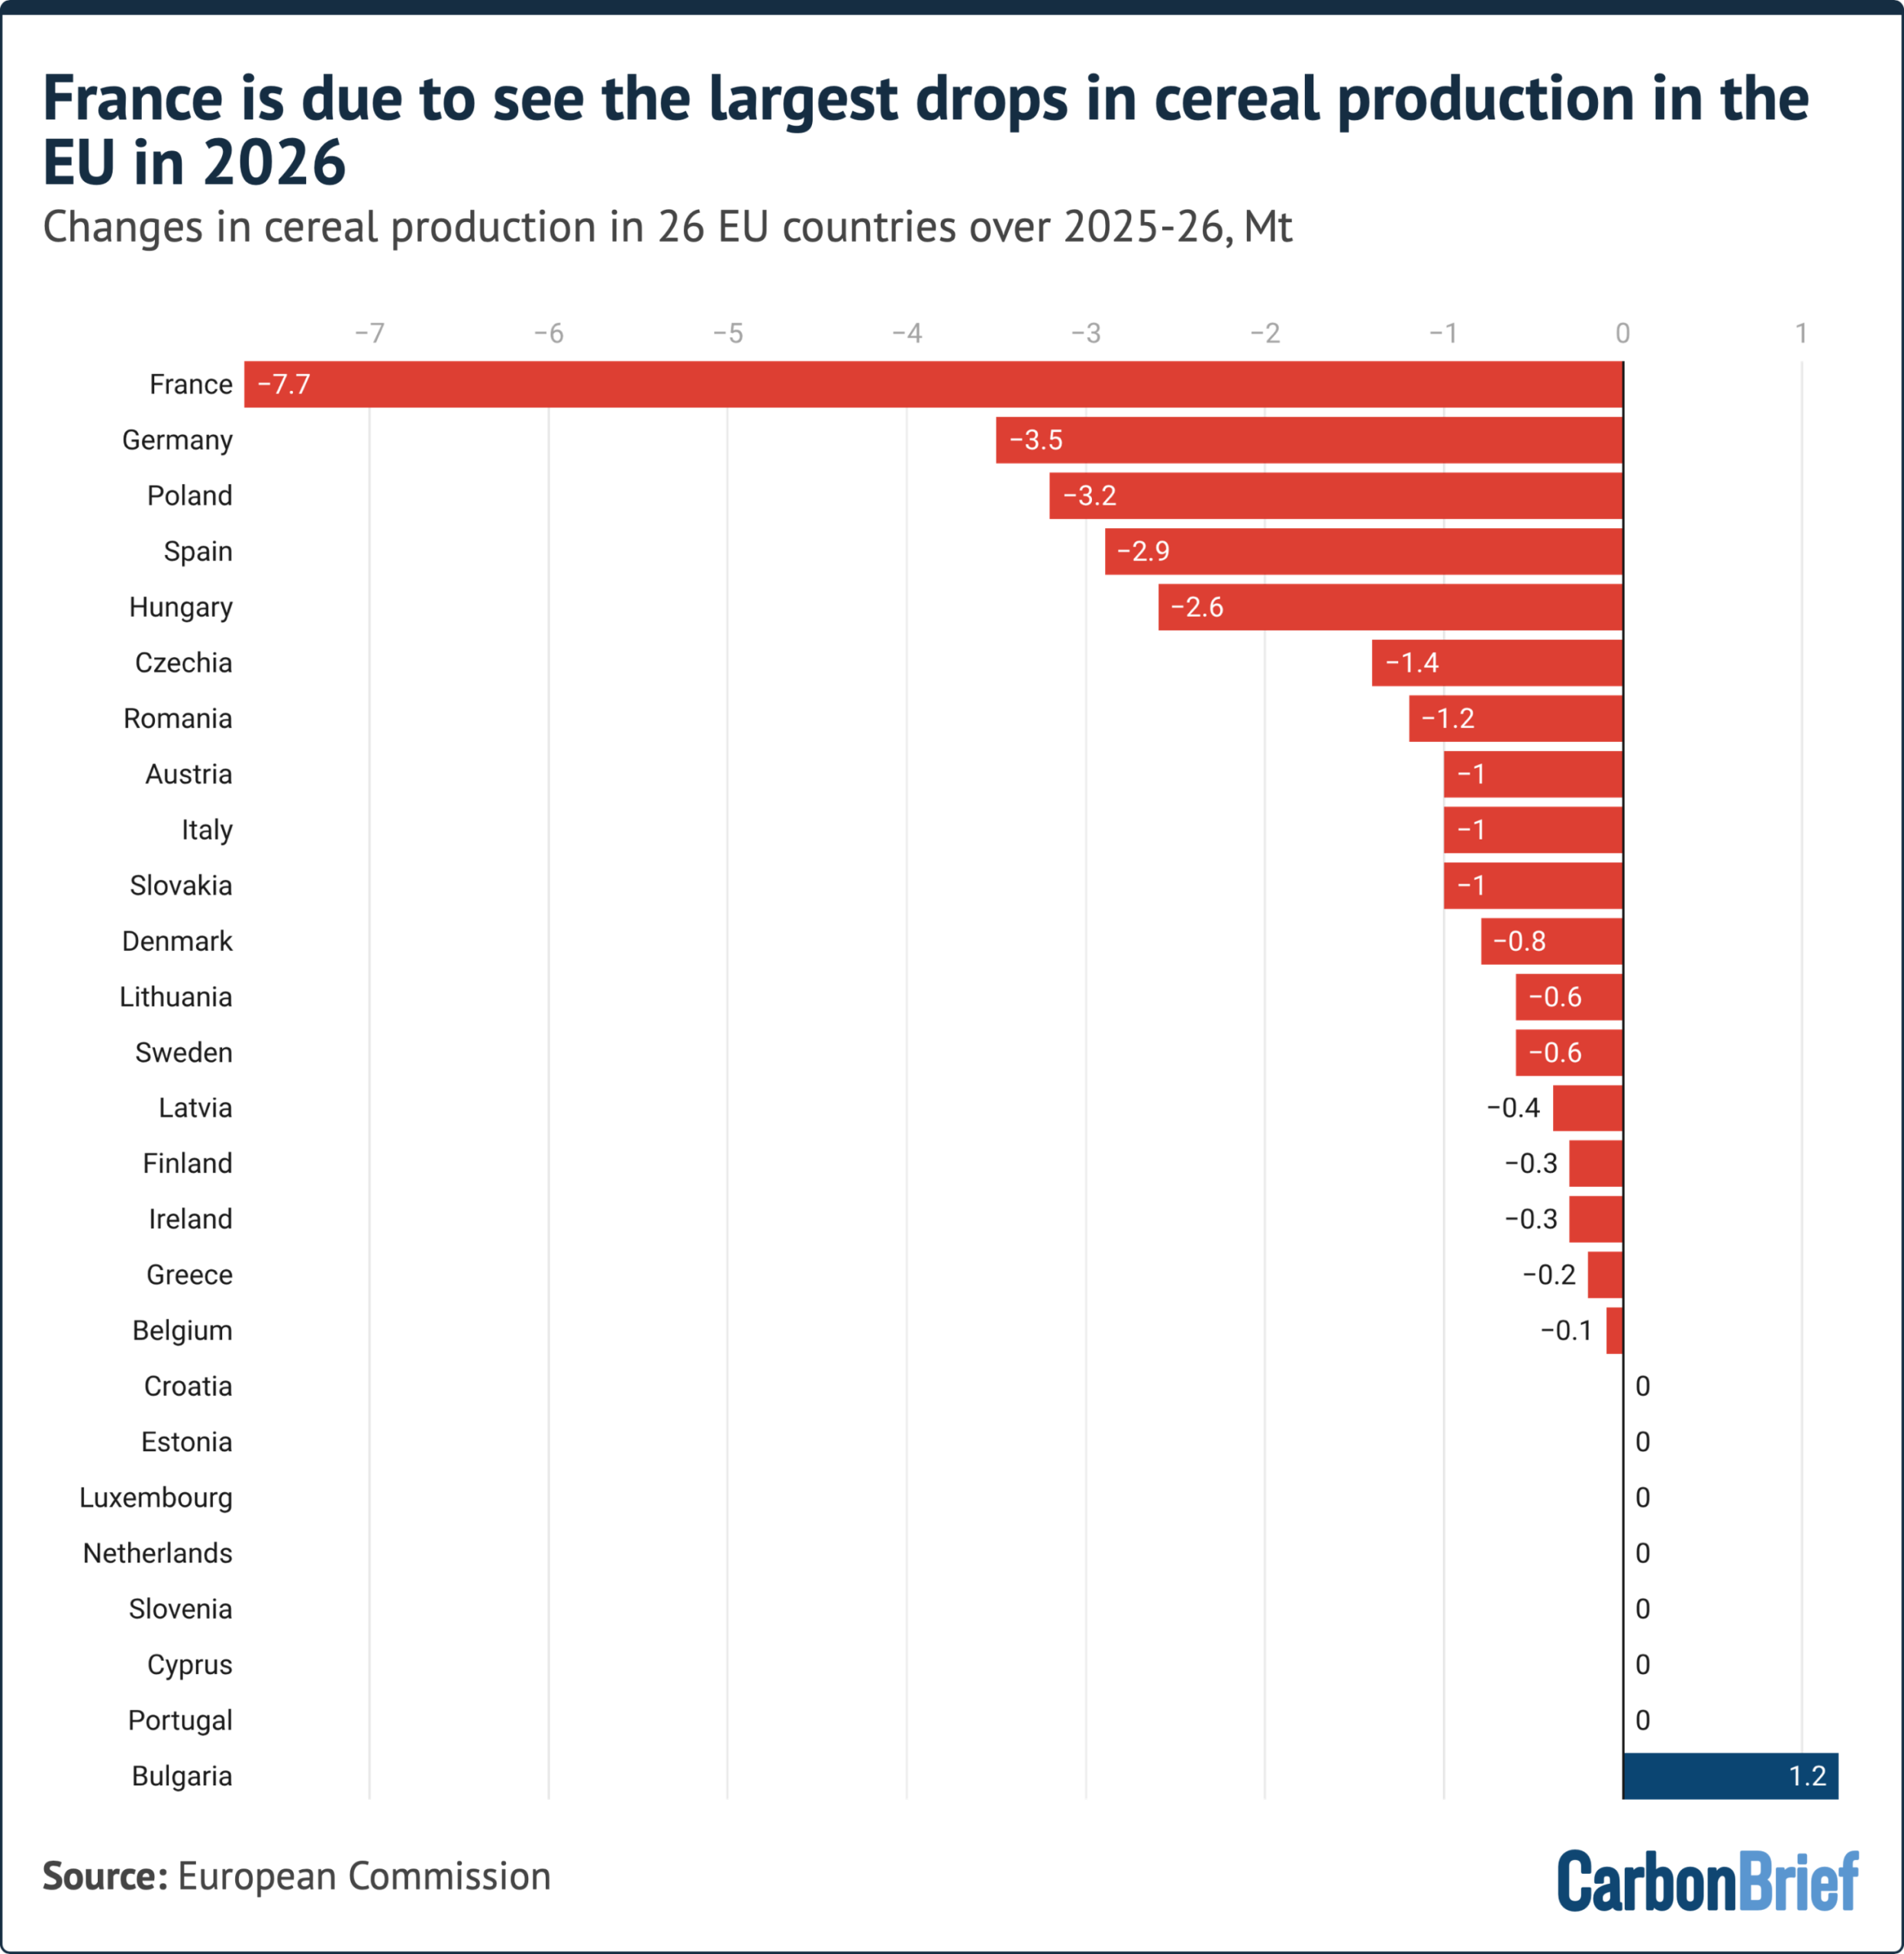
France, in particular, will see heavy losses in the amount of cereals – such as wheat, barley and oats – it produces this year, according to European Commission data.
French cereal production is expected to drop by almost 8 megatonnes (Mt) in 2026, compared to 2025.
The chart above shows that most European countries, aside from Bulgaria, will also see production losses this year.
Germany is due to see the second-largest losses in production, dropping by almost 4Mt compared to 2025.
Prof Til Feike, a cropping systems expert at the Julius Kühn-Institut, says many areas in Germany and Austria, as with other parts of Europe, have been “hit hard by a long-lasting dry period in combination with record-high heatwaves”.
This has resulted in dry grassland for animals and lower yields of maize, which is a “key fodder crop” for livestock. He tells Carbon Brief:
“In the long run, farming must adapt better to more extreme weather conditions, not only heat and drought, but also prolonged wet periods. So, there is no one-fits-all solution for climate change adaptation.”
2. Most countries are recording reduced crop yields
Heat and a lack of water have “substantially worsened” crop expectations this summer in western and most of central Europe, according to a recent bulletin from the EU Joint Research Centre.
Yields are expected to be “significantly reduced”, with local crop failures “likely” in areas such as France, southern Germany, northern and central Italy, and Hungary, it added.
The chart below shows that yields of cereal grains – which, here, refers to the tonnes of a grain grown per hectare of land – are expected to fall in most EU countries in 2026.
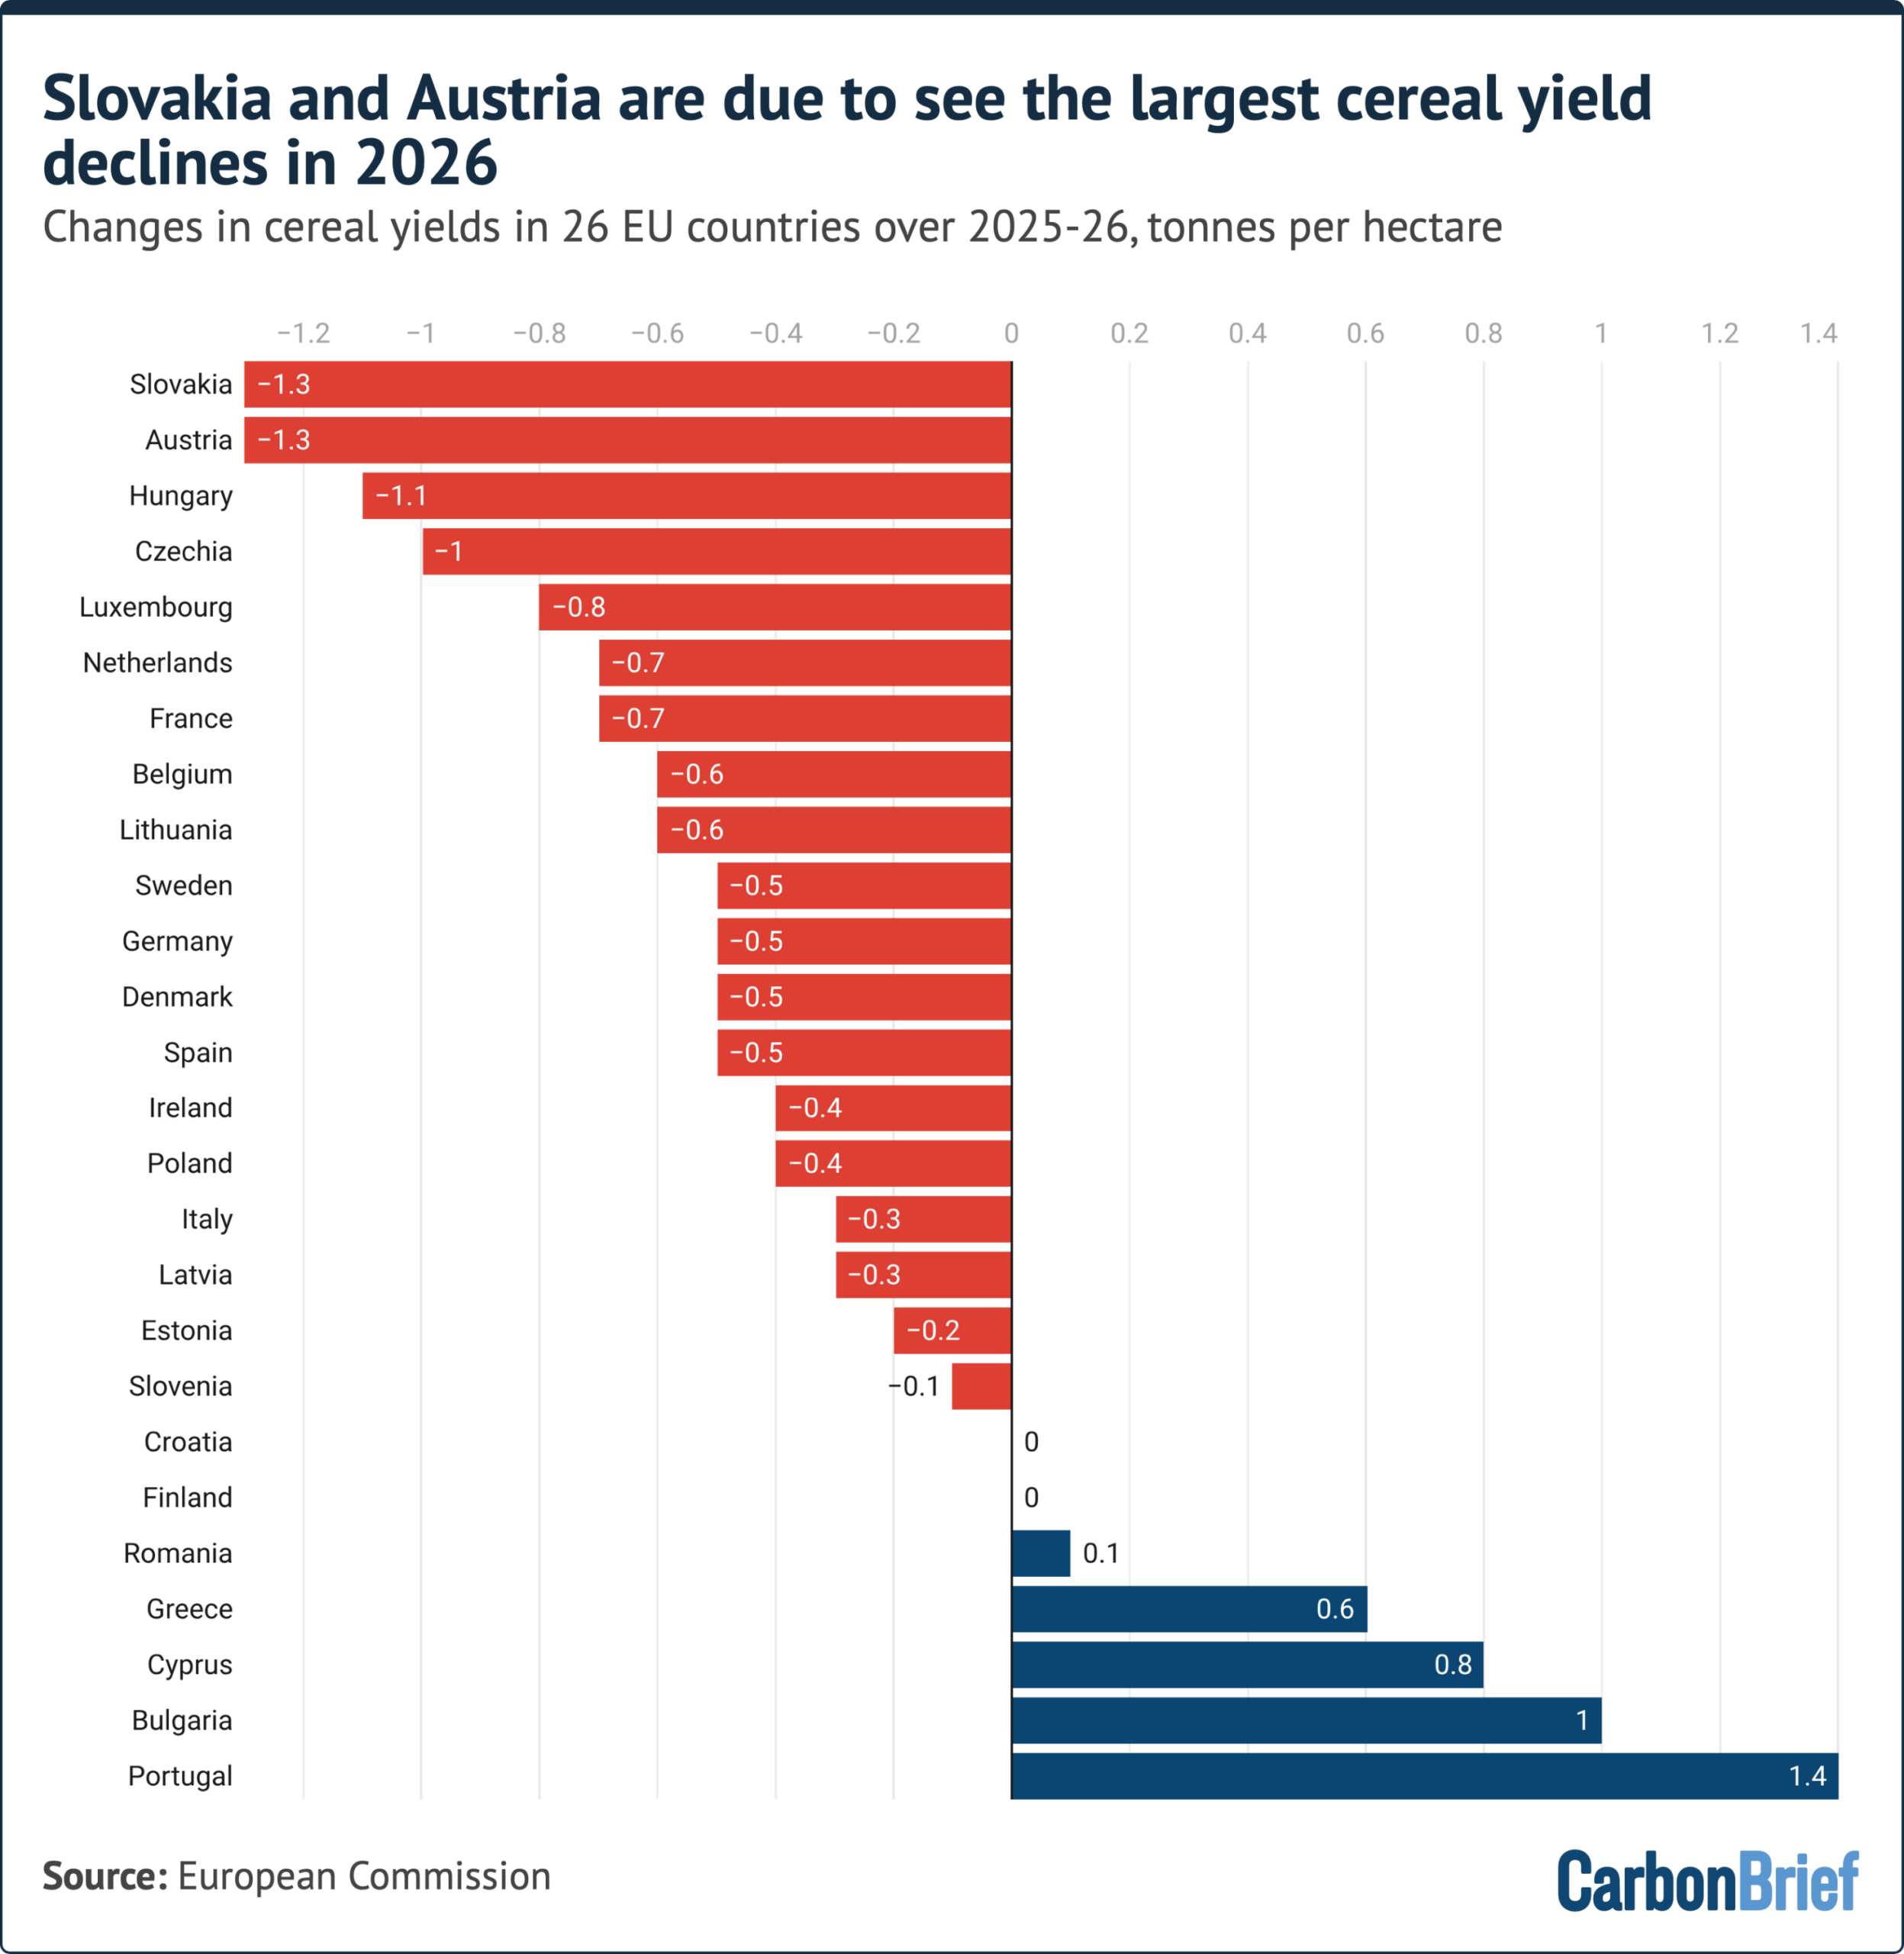
Slovakia, Austria and Hungary are expected to see the largest declines in cereal yields, reducing by more than one tonne per hectare in 2026 compared to 2025.
The recent EU bulletin noted that irrigated crops performed well in Portugal this summer – the country with the largest yield increases. Other crops relying on rainfall showed growing signs of heat stress, it added.
3. Around €2bn worth of cereal losses after June heatwave
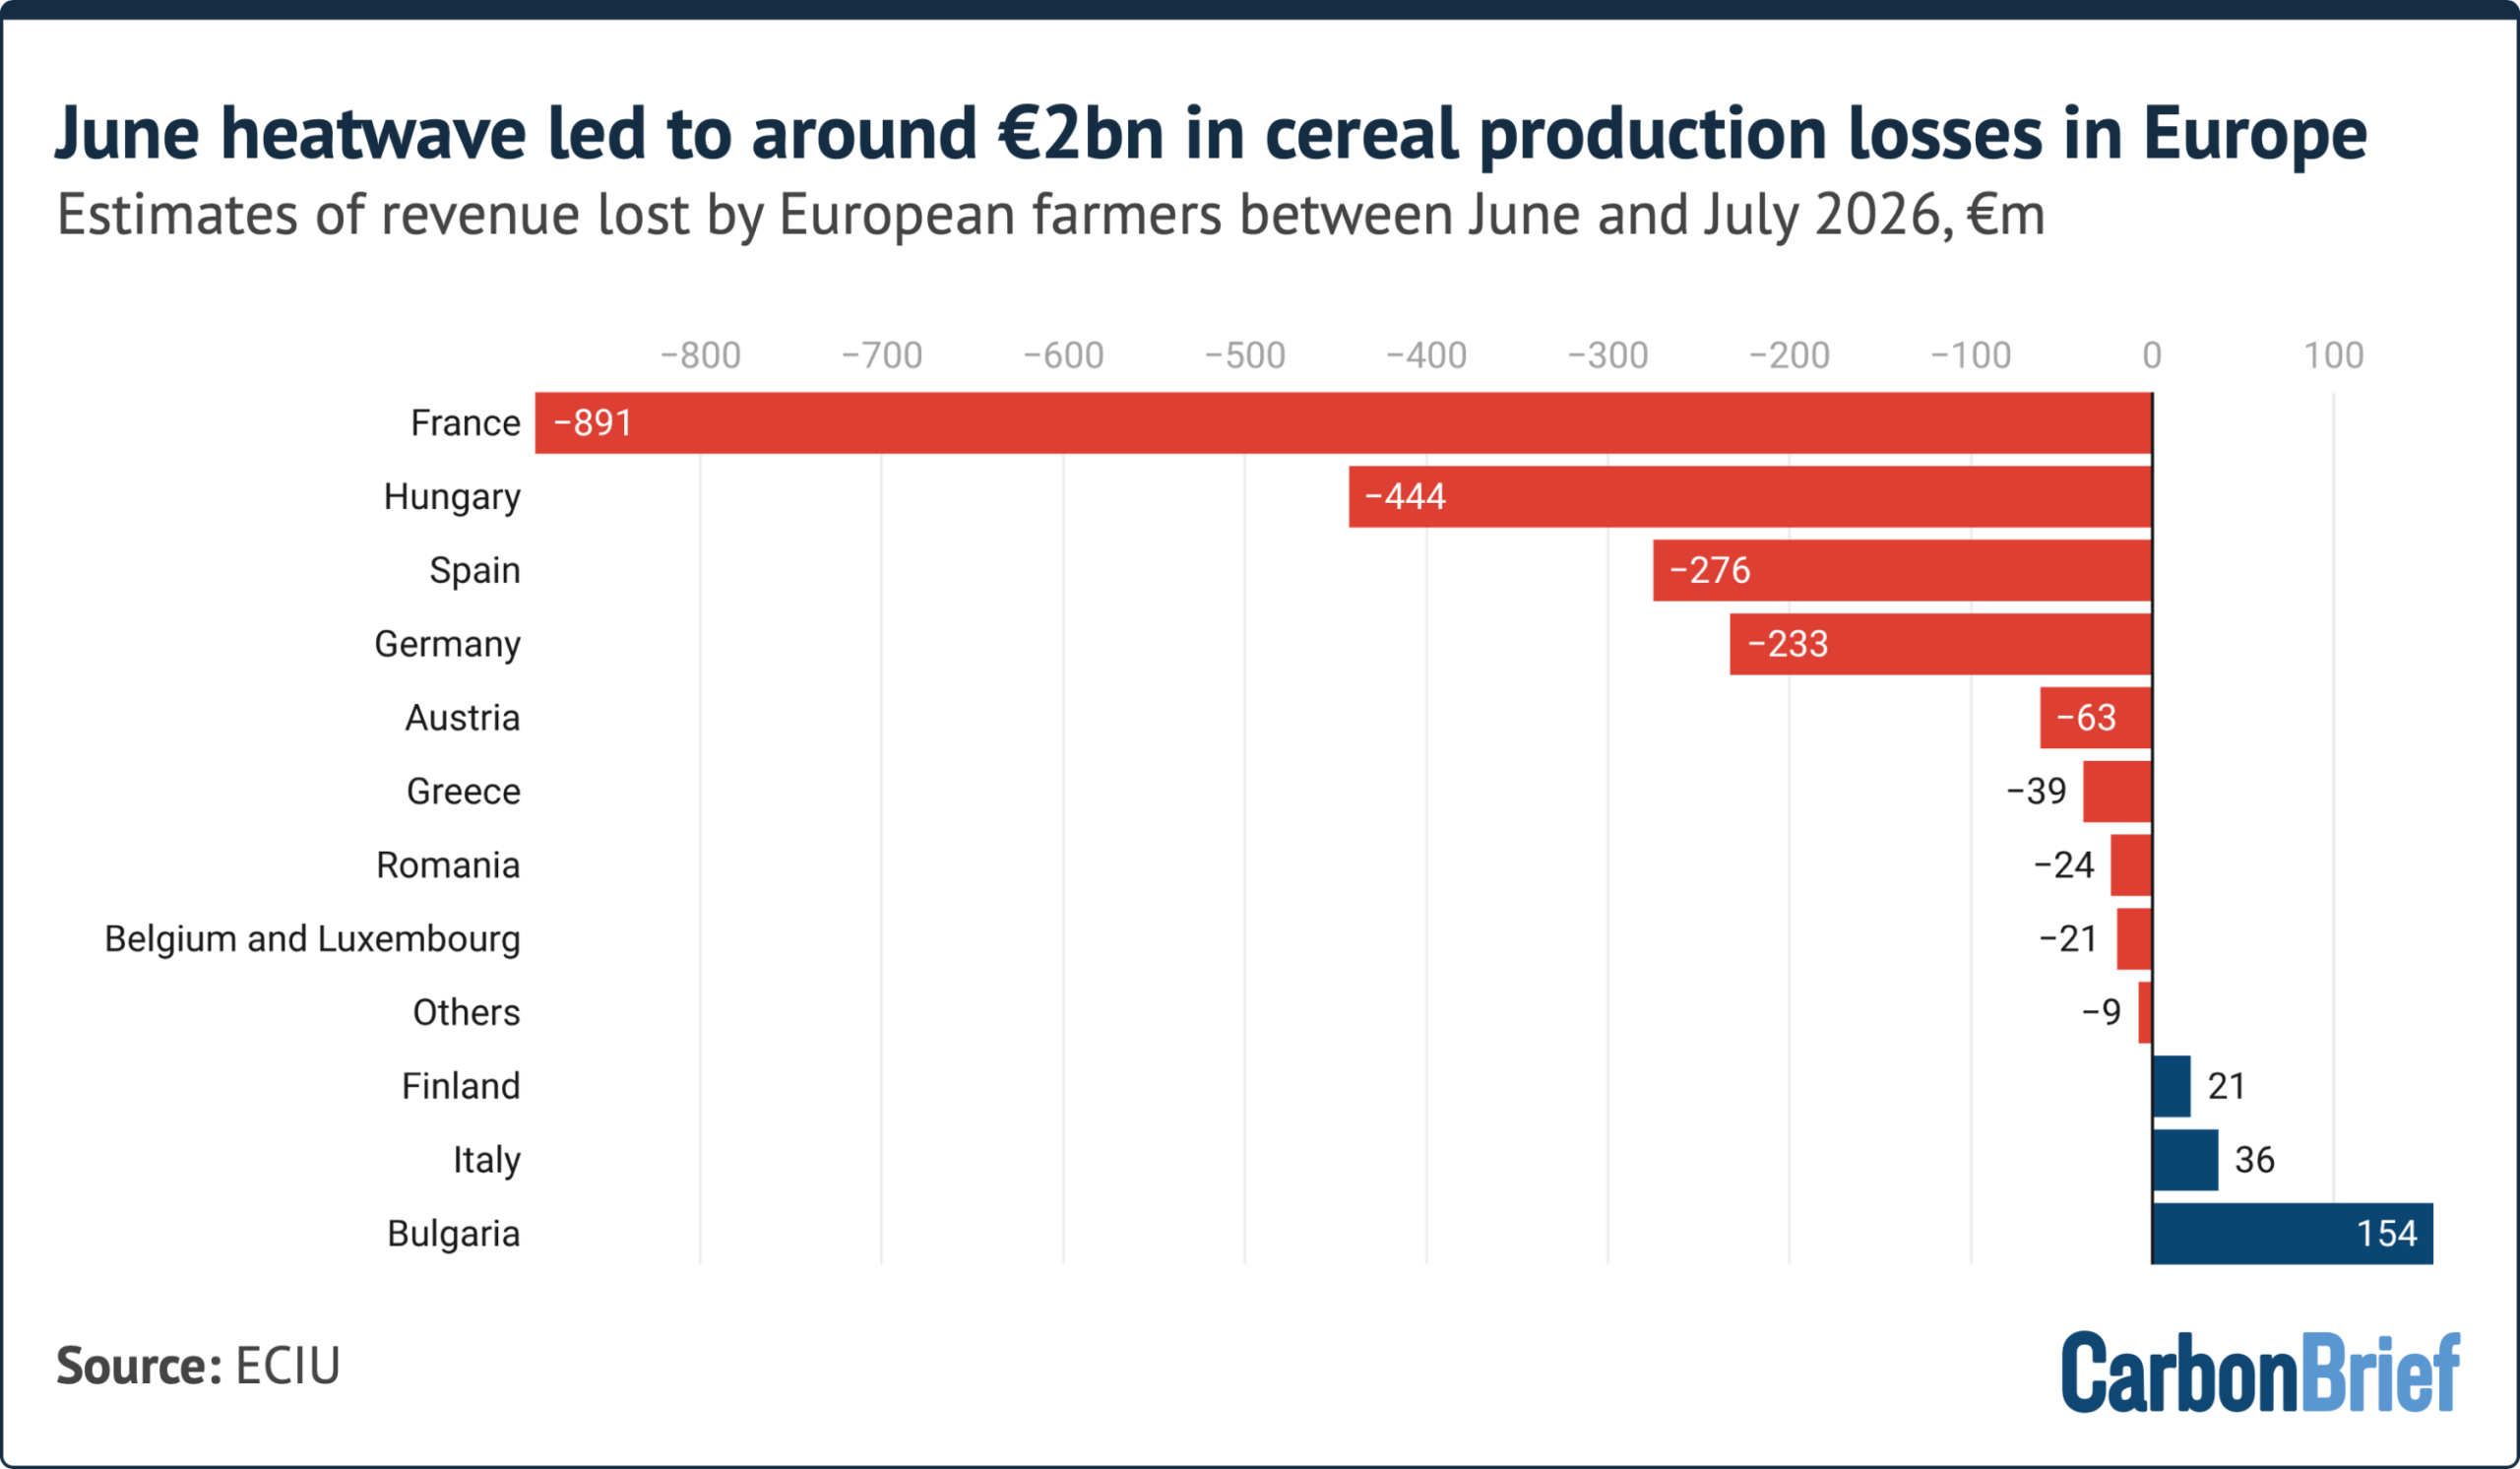
The record heatwave that hit many parts of Europe in June contributed to an estimated €2-2.3bn in cumulative grain production losses, as shown in the chart below.
The intense June heat in western Europe would have been “virtually impossible” just 50 years ago, according to a rapid climate attribution study. It was the region’s hottest June on record.
The Energy & Climate Intelligence Unit (ECIU) thinktank analysed June and July 2026 grain forecasts from Coceral, a European grain traders association.
ECIU estimated lost supply by multiplying the change in tonnes of grains between these two months by prices for harvest delivery in 28 European countries.
Major grain producers France, Germany, Hungary and Spain accounted for 86% of the lost revenue, according to the ECIU.
Extreme heat is also expected to have a wider economic impact across the continent. Analysis from Triodos Bank found that this summer’s extreme weather could reduce the EU’s gross domestic product (GDP) by around 1% this year, or around €180bn.
4. UK yields of wheat, barley and oats are all due to drop in 2026
If current trends continue, the average yields for cereals and oilseeds will result in the UK’s worst harvest since detailed records began in 1984, according to ECIU.
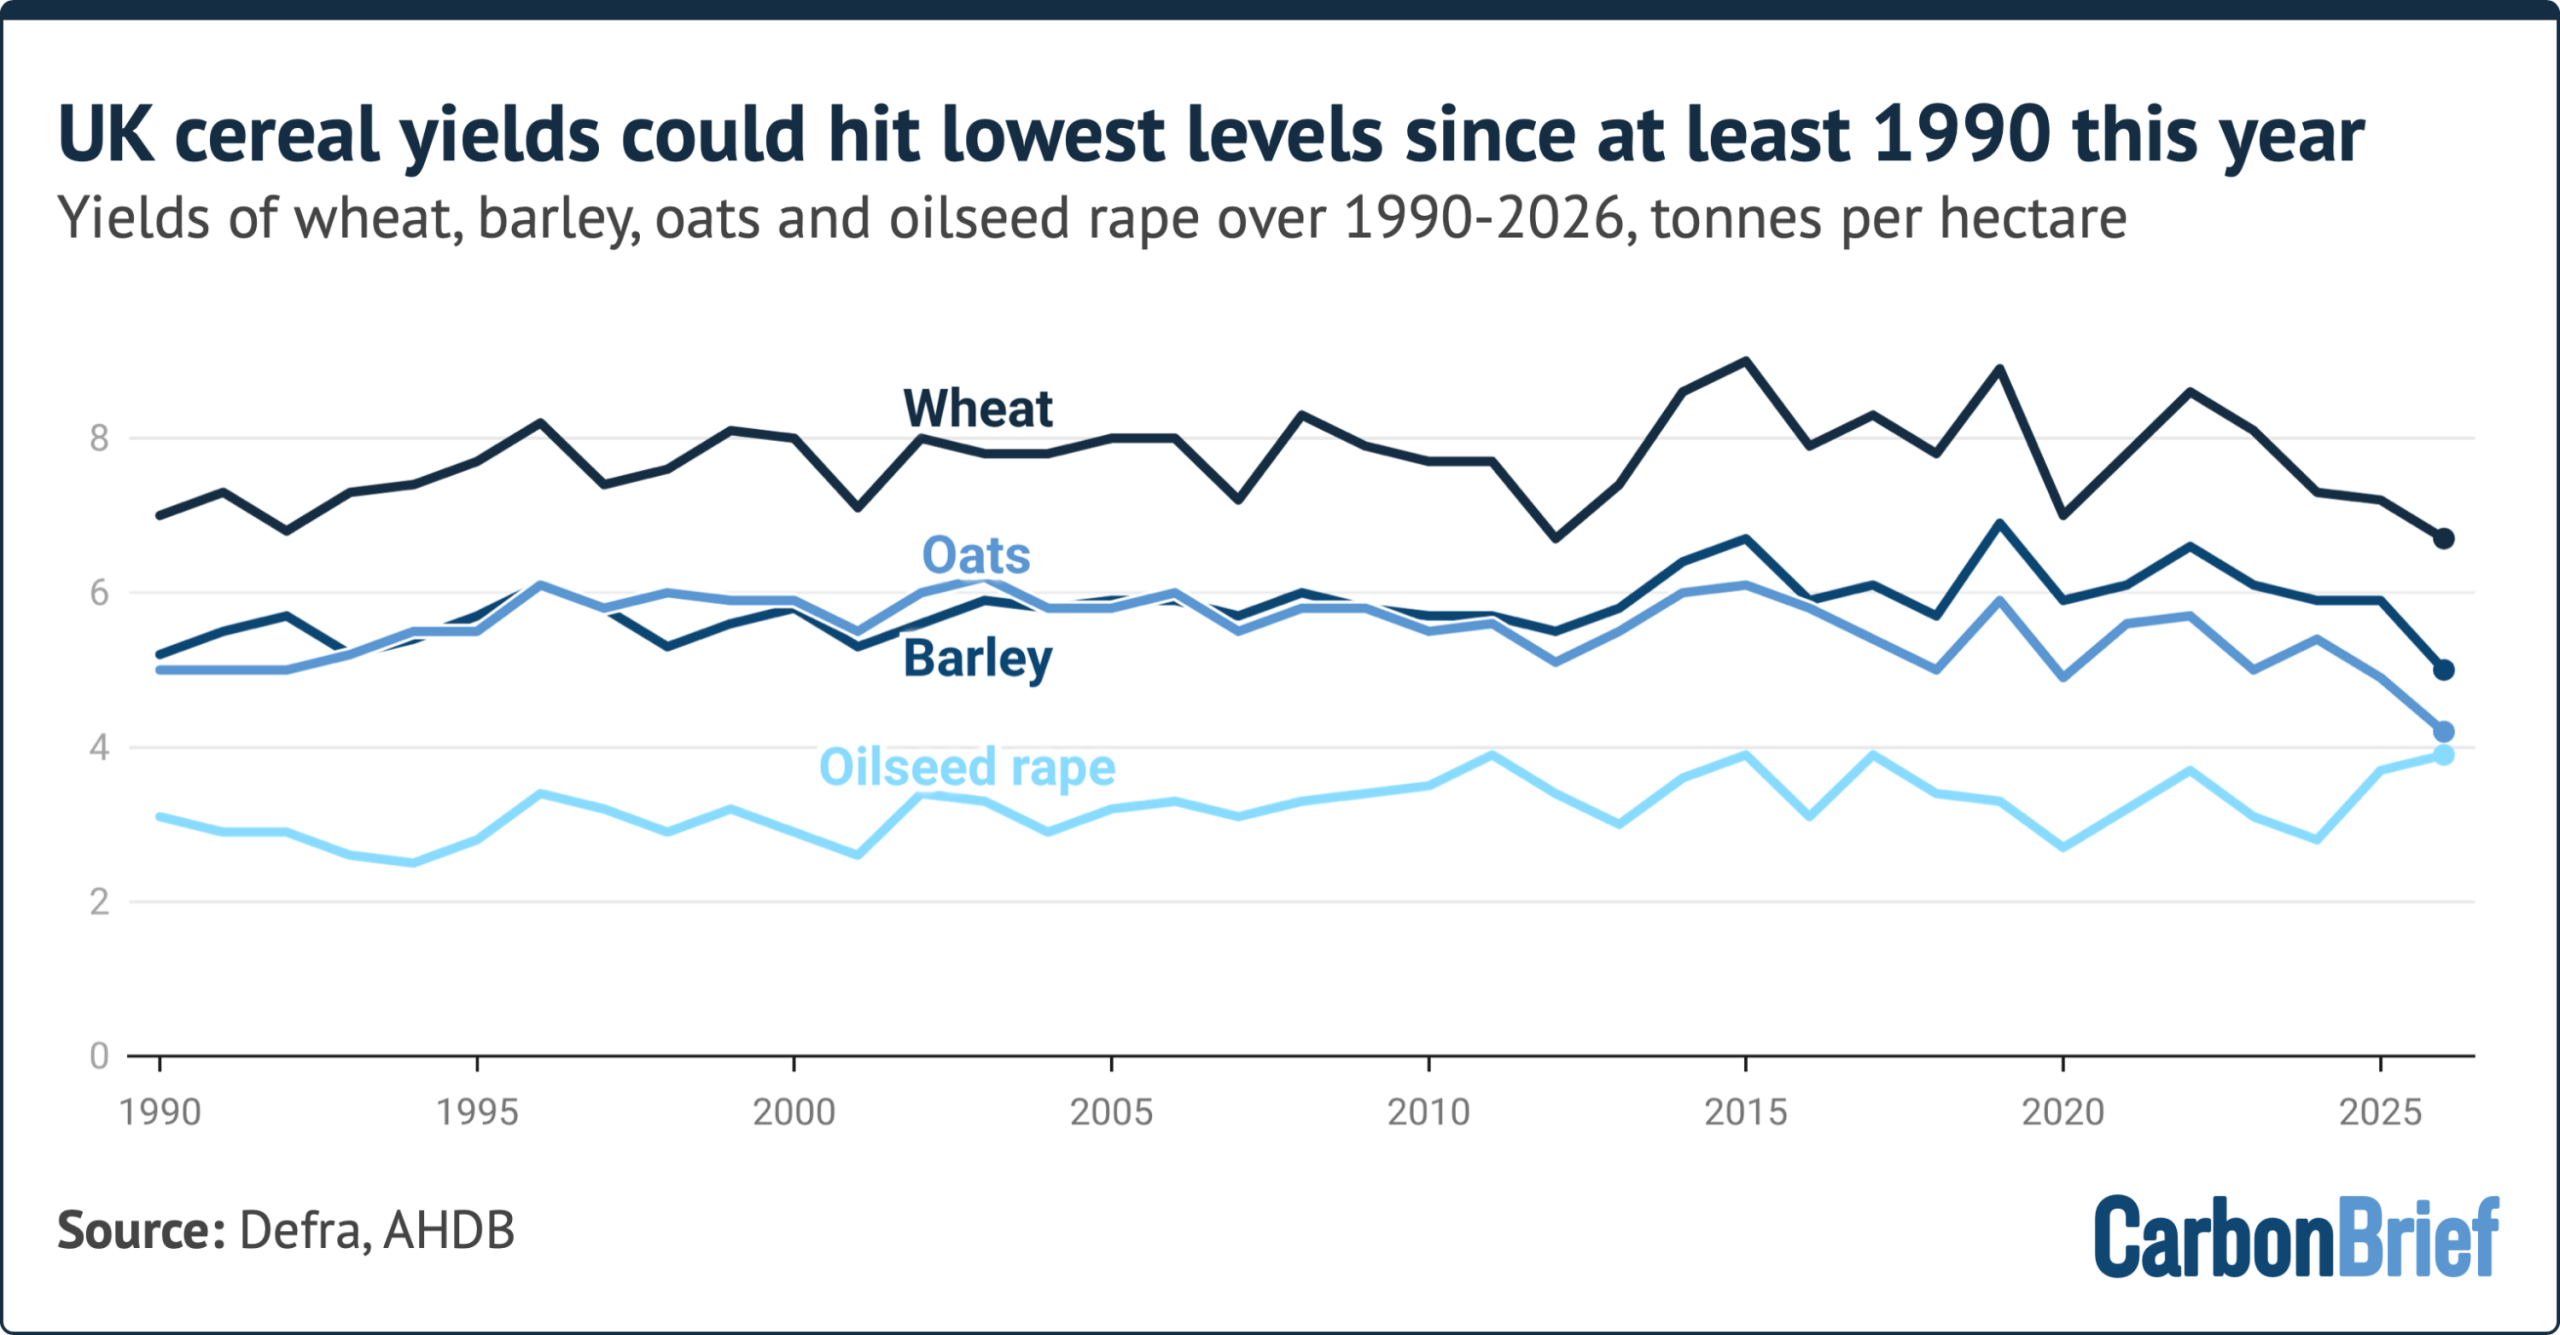
Barley yields could fall by 15%, oats by 14% and wheat yields by 6% year-on-year, according to 2026 harvest surveys from the Agriculture and Horticulture Development Board, a non-departmental public body that provides agricultural data to the UK government.
ECIU said that, even if the situation improves, this year is still expected to be one of the five worst harvests on record. This means that four of the five worst harvests in the UK have occurred in the past decade.
Consumers will likely see higher prices and/or smaller vegetables in supermarkets as a result, Tim O’Malley, chairman of UK company Nationwide Produce, told BBC News in August.
Other crops, such as berries, have grown successfully in the extreme heat. But the Guardian noted fears this could dip later this year “as plants become exhausted from heavy cropping during the heatwave”.
5. Maize production in France is due to hit a four-decade low
France has been acutely affected by this summer’s extreme weather, with more than 7,300 excess deaths during heatwaves and a record number of weather stations recording temperatures of above 40C.
The country is the EU’s largest agricultural producer, but heat, drought and wildfires have affected many crops.
The chart below shows that maize production is set to drop by more than one-third (35%) year-on-year.
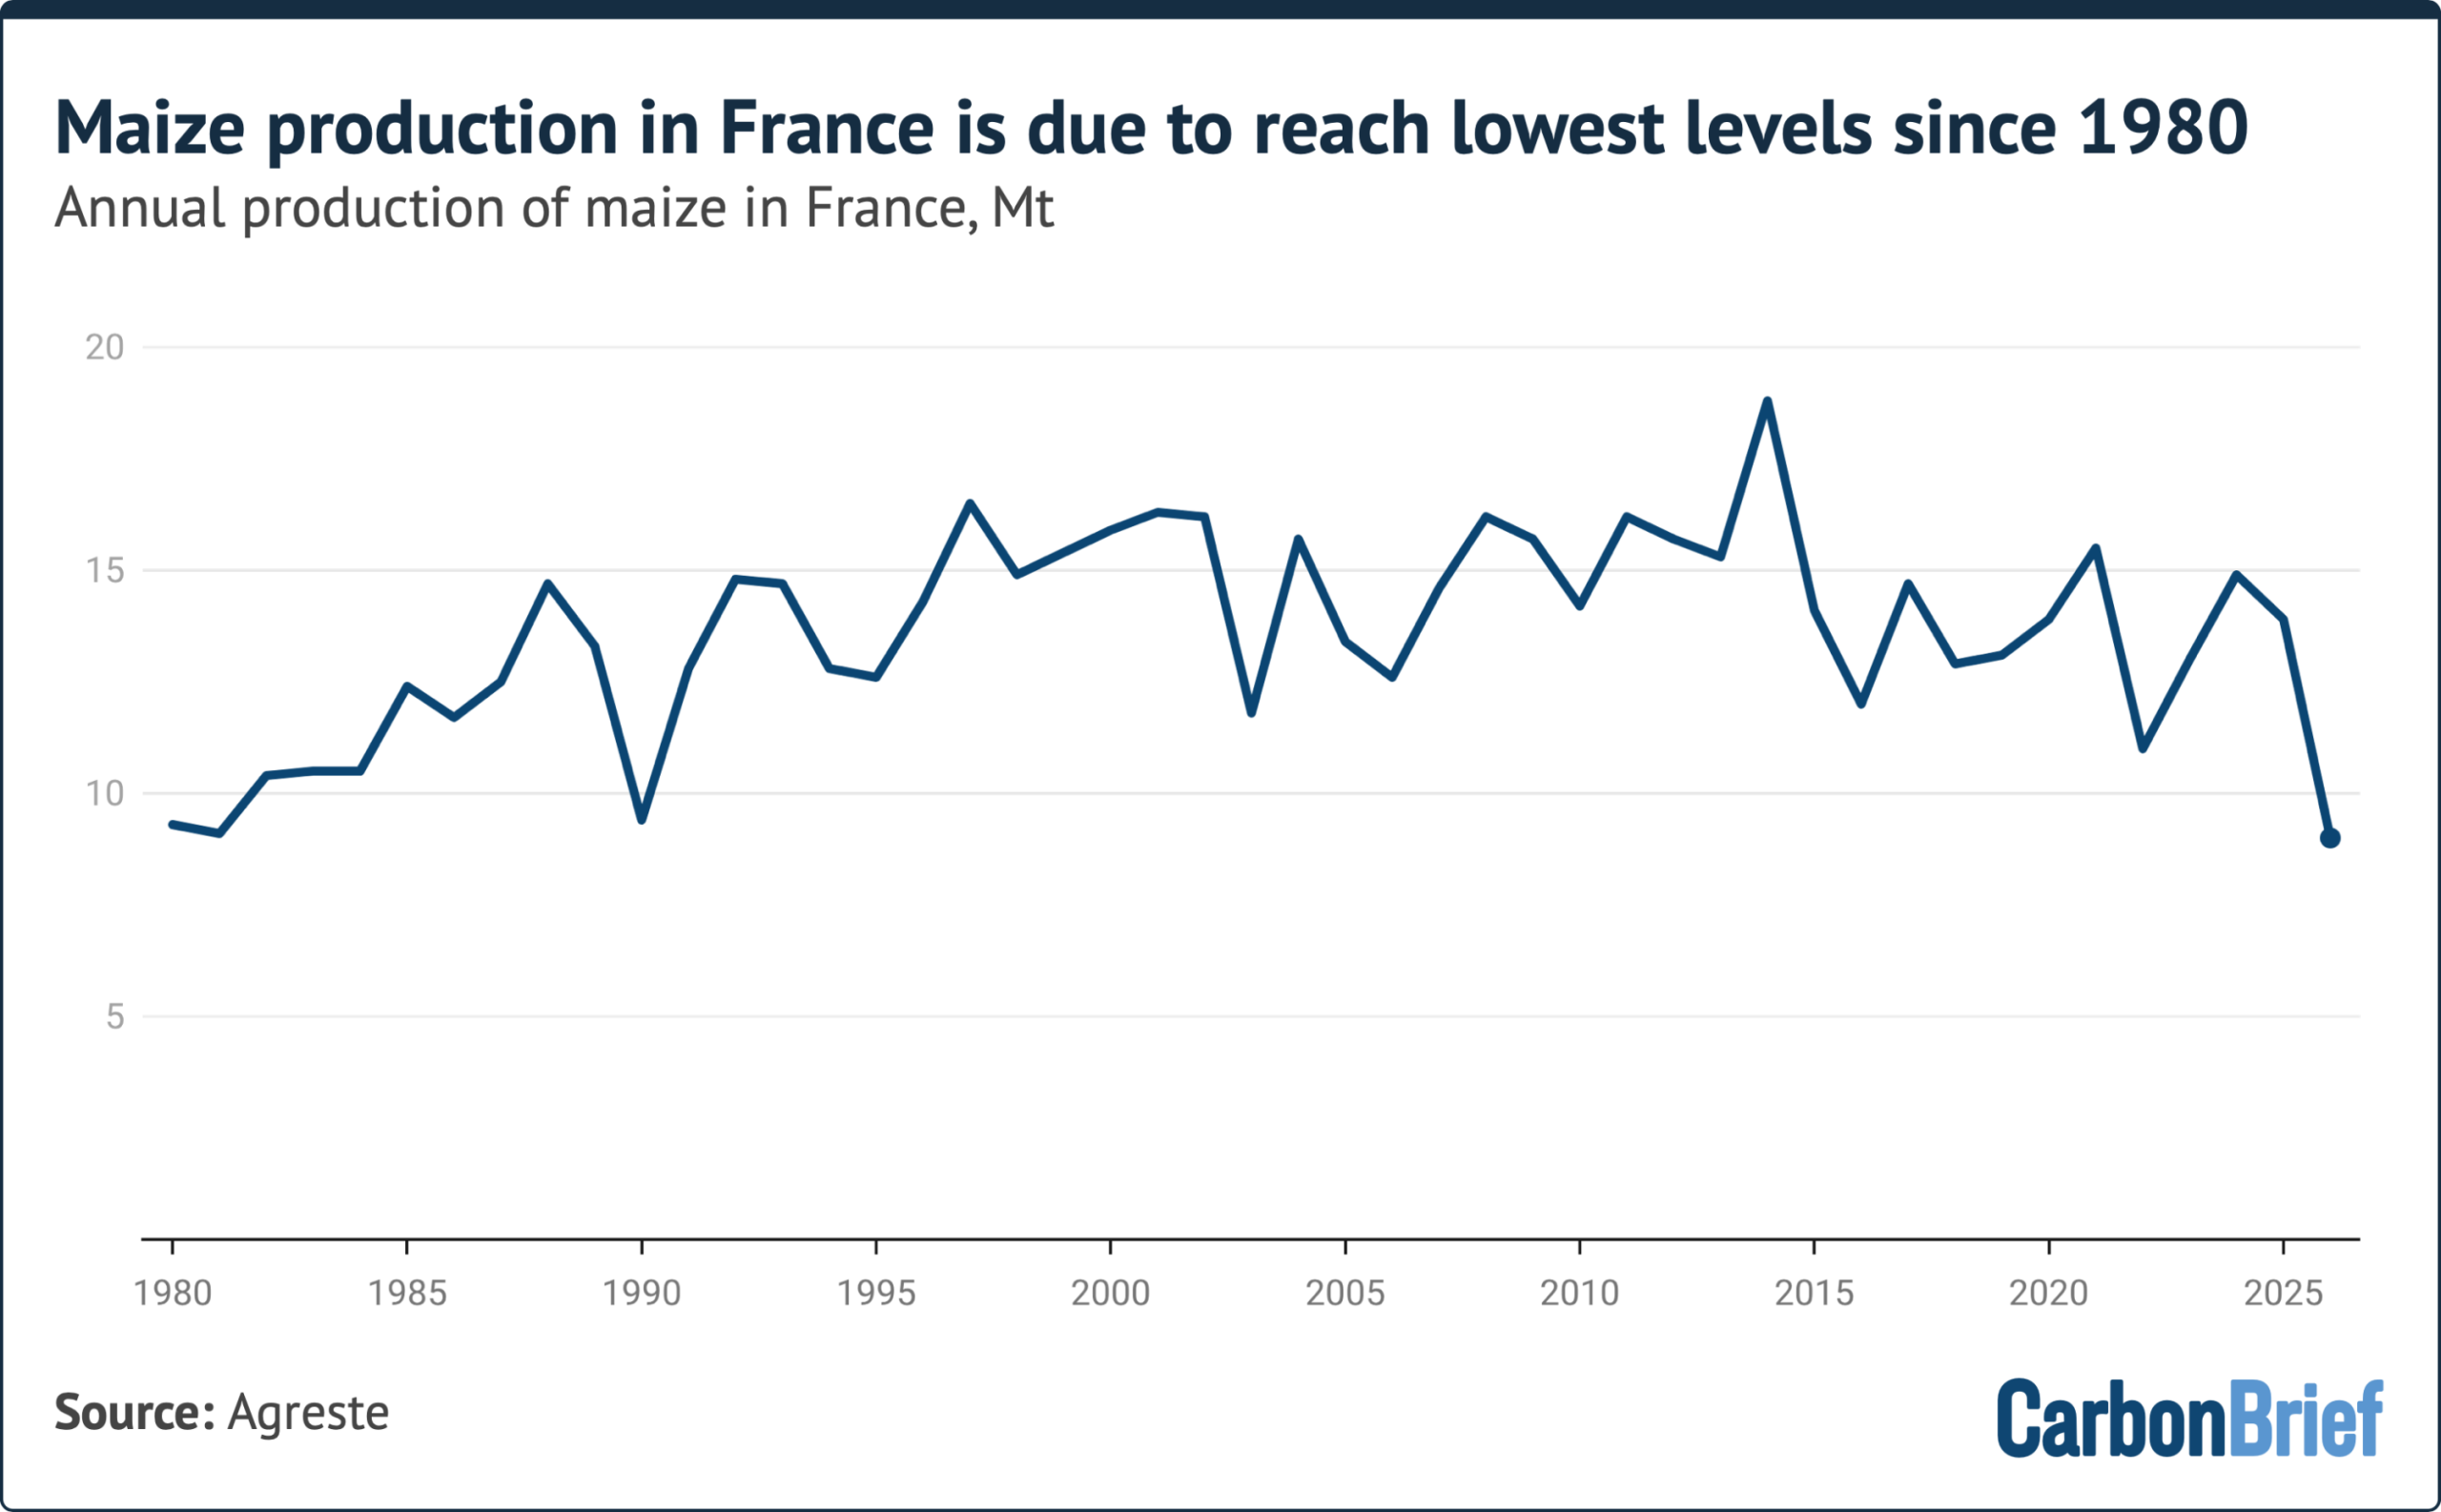
This could result in France’s lowest maize production since 1980, according to data from Agreste, the country’s agriculture ministry’s statistics service.
Due to the heat, “record-early” grape harvests have also been recorded in various parts of the nation since mid-July, reported Le Monde. In some cases, this means “smaller, less juicy grapes, which will yield less wine”, explained the newspaper.
6. Declines in EU grains since 2025
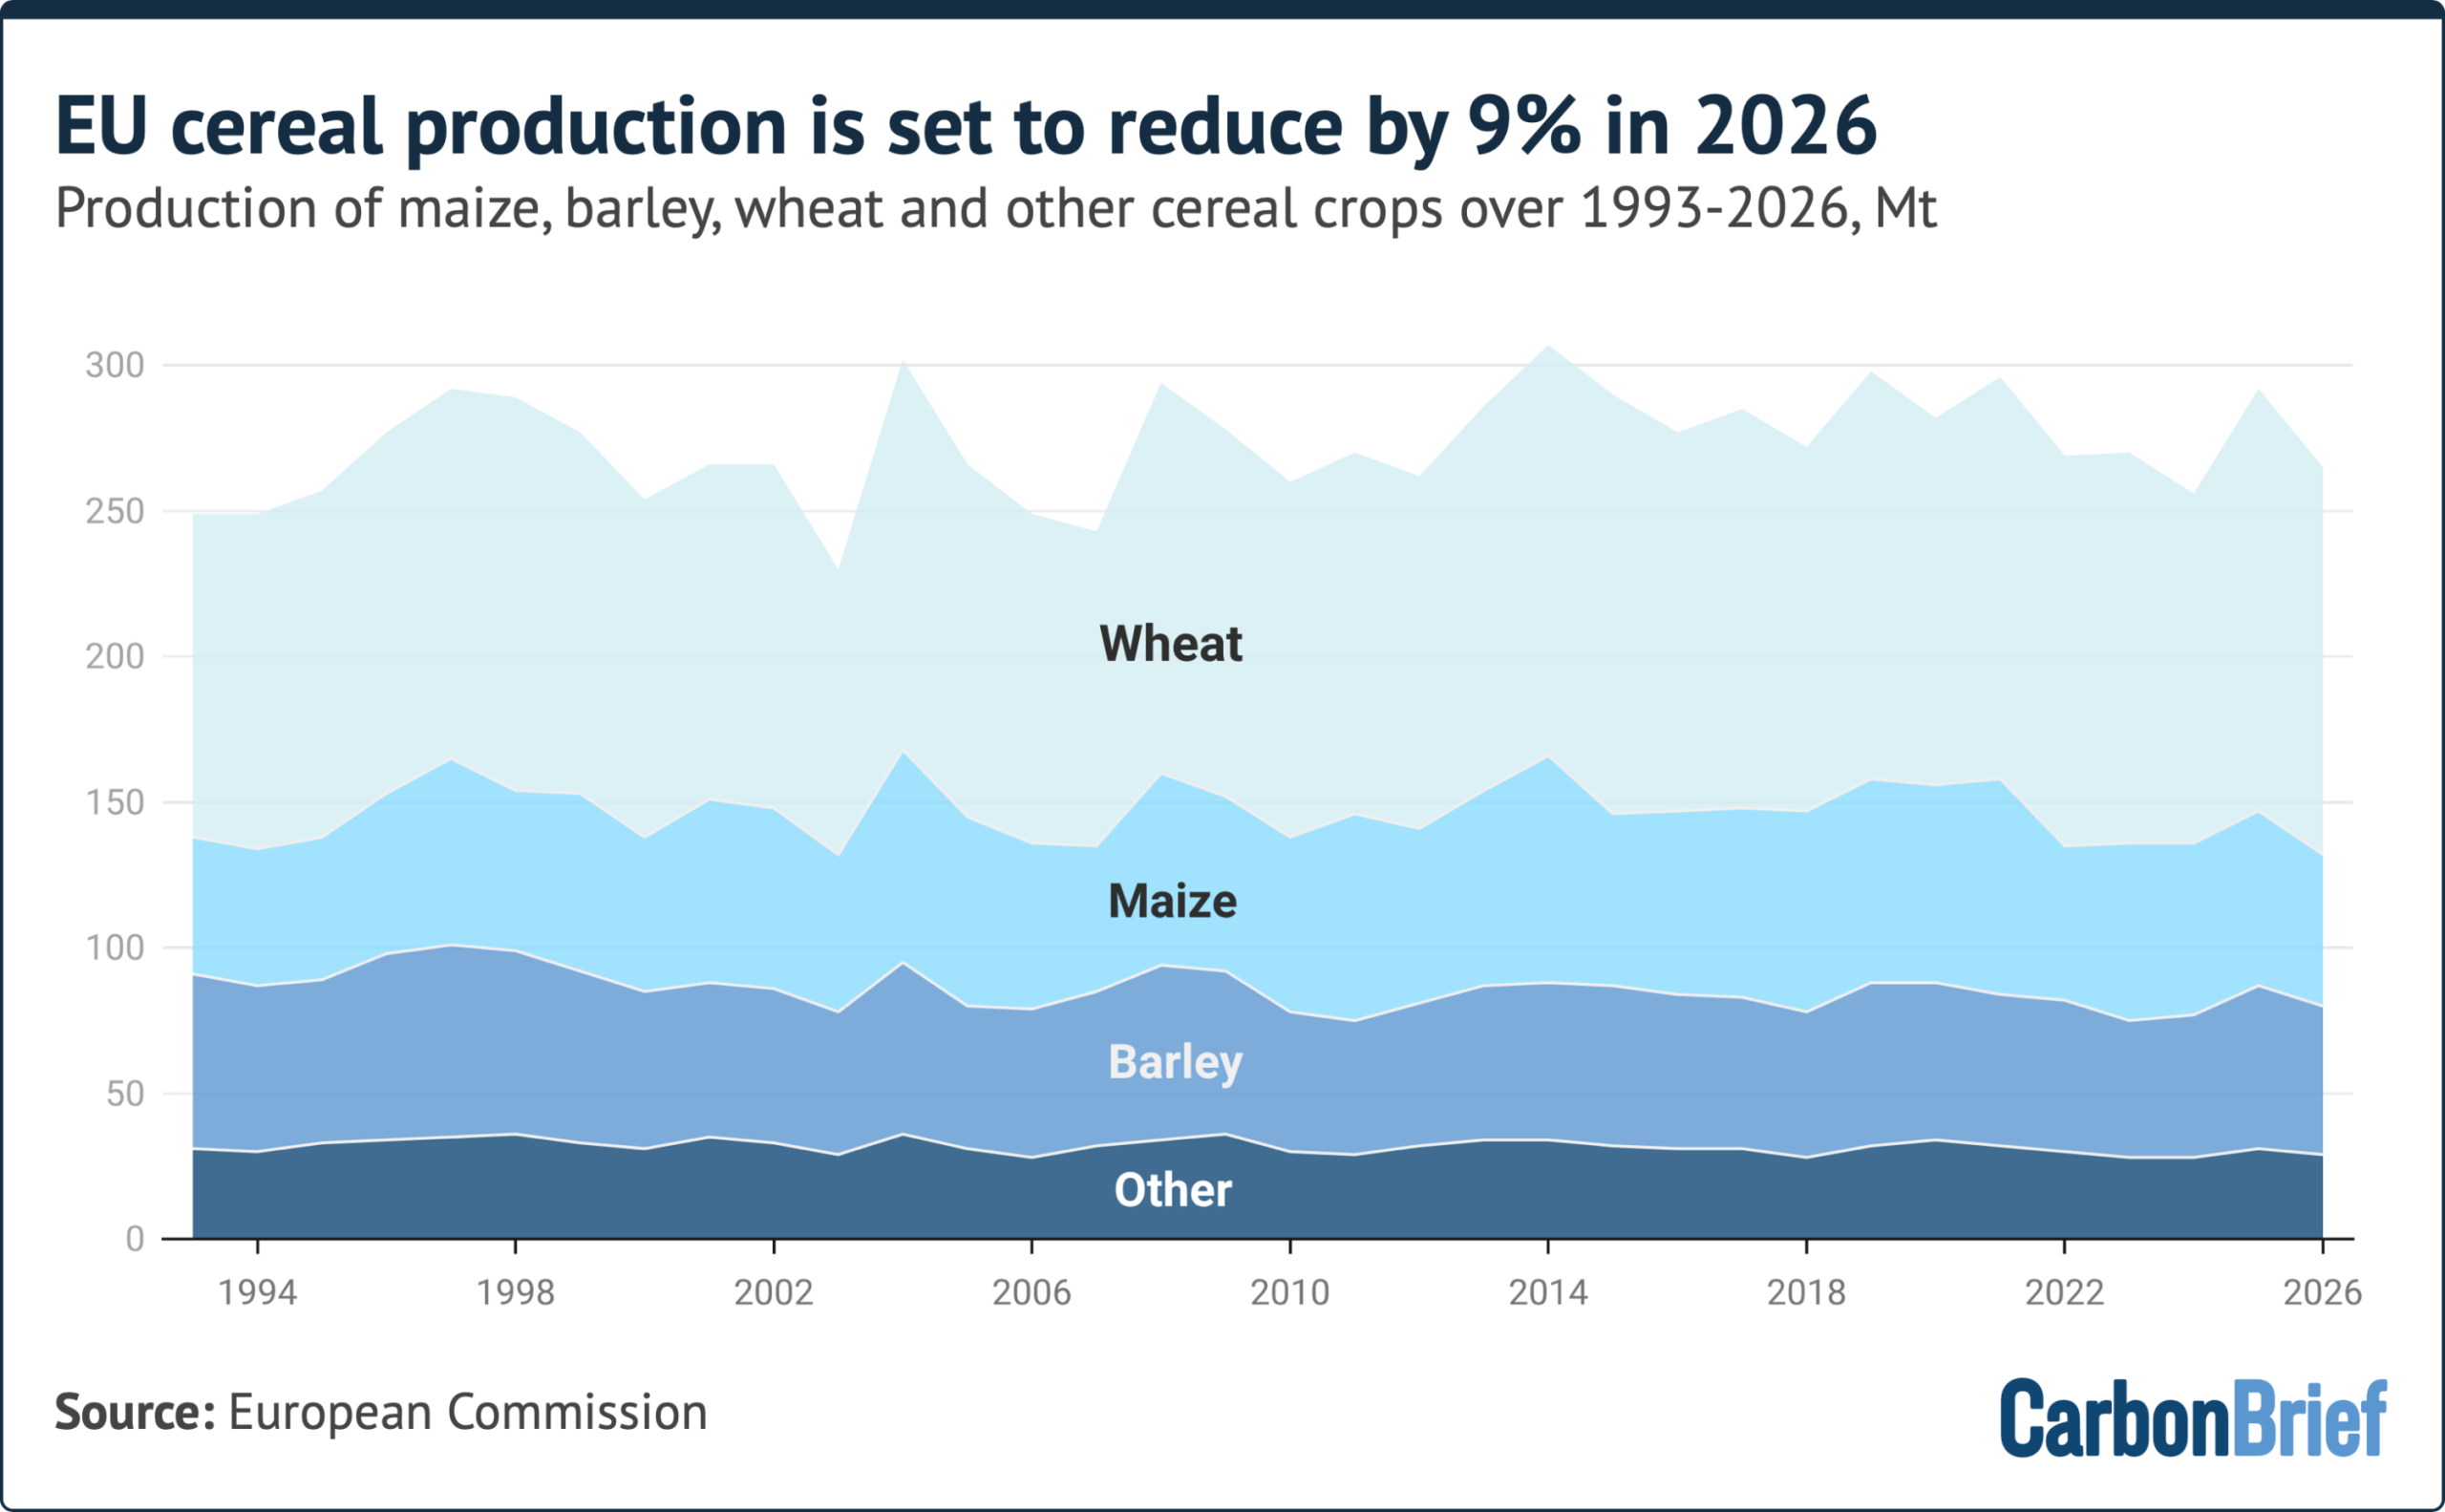
Overall in the EU, data and projections indicate declines in the output of cereal grains this year.
Cereal production is set to fall by 9% compared to 2025, according to the European Commission.
Just one year in the past decade – 2024 – recorded lower production levels.
Maize production is set to be particularly affected, with projections indicating a 13% drop, to 52Mt – the lowest level in the EU since 2007.
The post How this summer’s heat and drought impacted crops in Europe – in six charts appeared first on Carbon Brief.
How this summer’s heat and drought impacted crops in Europe – in six charts



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits