

中国的气候和能源政策呈现出一种悖论:在以惊人的速度发展清洁能源的同时,也未停下新建燃煤电厂的步伐。
仅在2023年,中国就新建了70吉瓦(GW)的煤电装机容量,比2019年增长了四倍,占当年全球新增煤电装机容量的95%。
煤电产能的激增引发了人们对中国二氧化碳(CO2)排放和气候目标能否实现,以及对未来出现搁浅资产风险的担忧。
由于光伏和风能发电量不稳定,中国政府将煤炭作为保障能源安全和满足快速增长的用电高峰的手段。
与此同时,中国的电力行业在成本、需求模式、监管和市场运作方面正在发生重大变化。我们的新研究表明,用于证明新煤炭产能合理性的传统经济计算方式可能已经过时。
我们使用一个简单的分析指标来评估能满足用电高峰需求的最经济方式是什么。结果表明,光伏加电池储能的组合可能是比新建煤电更具成本效益的选择。
中国电力格局发生了怎样的变化?
在过去十年里,可再生能源和电池储能的成本大幅下降,高峰时段的住宅和商业用电需求激增,电力交易市场获得了更大的吸引力。
与此同时,中国还宣布了“双碳”目标,即在2030年前实现碳达峰、2060年前实现碳中和。鉴于这些转型,建设更多未减排的煤电厂与中国的长期气候承诺相冲突,而且对满足用电需求对增长来说,可能不再是最具成本效益的选择。它还占用了清洁能源系统转型急需的资金。
替代指标如何评估成本?
我们的研究引入了一种替代指标,用于计算在满足不断增长的高峰用电需求的情况下,所需的最优成本投资。

这一指标,即“净容量成本”(net capacity cost),是满足用电高峰需求所需的基础设施投资的年化固定成本,减去该设施带给电力市场的收入,或其“系统价值”(system value)。 在该指标中,负数意味着这些投资将带来利润,而非支出。
为了探索在中国使用的情境,我们使用了一个简单的例子:在一个假定省份,高峰用电需求增加了1500兆瓦(MW)、全年需求增加了6570吉瓦时(GWh)。
然后,我们概述了满足高峰和全年能源需求的五种策略(情况),其涵盖了从严重依赖煤电到光伏和电池储能相结合的方式。
在不同的案例中,资源衡量的规模基于它们能够可靠地满足高峰供应需求和年度能源需求的程度。
- 情况1:新的煤炭发电能力可满足高峰和年度能源需求的所有增长。
- 情况2:光伏可满足70%的年度能源需求增长,煤炭可满足30%的年度能源需求增长;光伏可满足525兆瓦的高峰供应需求(由于光伏发电可能不在高峰期间,因此基于“容量可信度”进行折减),而煤电可提供剩余的975兆瓦。
- 情况3:光伏可满足所有年度能源需求增长;光伏和煤炭均可满足750兆瓦的高峰供应需求,同样通过容量可信度对光伏发电量进行折减。
- 情况4:光伏满足所有年度能源需求增长;光伏和电池均为高峰供电需求提供750兆瓦;电池提供调频储备(用于管理精确至分钟的供需差异的备用电源)。
- 情况5:光伏满足所有年度能源需求增长;广泛和电池均为高峰供电需求提供750兆瓦;电池提供能源套利(在价格或成本较低时充电,在价格或成本较高时放电)。
如下图所示,我们针对每种情况都计算了单个资源(煤、电池或光伏),以及整个系统每年获得1千瓦(kW)发电容量的年净成本,单位为人民币元。
表上半部分的资源净容量成本是指该资源的净成本(即年化固定成本减去该资源从提供能源和辅助服务,如调频,所获得的年收入)。正数表示电网运营商在增加或获取该资源时的净成本。
表下半部分的系统总净容量成本,是在每种情况下利用资源组合满足高峰需求增长的净成本。
我们用于计算系统净成本的权重是基于装机容量与高峰需求增长的比率。
不同能源组合满足用电需求的成本
| 情况 1 | 情况 2 | 情况 3 | 情况 4 | 情况 5 | |
|---|---|---|---|---|---|
| 资源净容量成本 (元/千瓦/年, 每千瓦装机容量) | |||||
| 煤炭 | 424 | 424 | 512 | ||
| 电池 | 248 | 781 | |||
| 光伏 | -128 | -128 | -128 | -128 | |
| 系统净容量成本 (元/千瓦/年, 每千瓦满足高峰用电需求且折减容量可信度后) | |||||
| 煤炭 | 471 | 306 | 236 | ||
| 电池 | 138 | 434 | |||
| 光伏 | -223 | -319 | -319 | -319 | |
| 总计 | 471 | 83 | -83 | -181 | 115 |
为了对这一简单分析进行压力测试,我们研究了不同来源的各种价格的敏感性。
由于中国的光伏价格已经很低,我们的敏感性分析主要集中在煤炭、电池和其他分析所需投入的价格上。
满足高峰用电需求最经济的方法是什么?
我们的结果表明,当电池储能提供调频储备时(情况4),光伏和储能的组合是满足高峰用电需求增长最具成本效益的选择。
在这种组合下,每获得1千瓦发电装机容量,电网运营商的成本为-181元(约-25美元或-20英镑)。
相比之下,新建煤电产能以满足高峰用电需求增长(情况1)是最昂贵的方案,每获得1千瓦装机容量的净容量成本为471元(约合65美元或52英镑)。
情况3,即大型煤电厂仅用作备用电源(几乎不发电),在中国可能出于政治原因而至少在短期内不可行。
另外两种情况(情况2和情况5)更具可比性,但鉴于自本分析报告发布以来,电池价格下降了30%以上,约为每瓦时(Wh)1元人民币(约合0.14美元或0.11英镑),因此情况5中的电池可能比情况2中的煤炭更具经济吸引力。
我们的解决方案如何助力中国实现气候目标?
我们的分析表明,为了应对不断变化的形势,在满足中国日益增长的能源需求的同时,实现其气候目标的近期战略是将电池储能纳入电力市场。
目前,中国政府允许包括电池在内的“新型储能”参与电力市场。然而,详细规定尚不明确,电池的参与可以更简单。
例如,电池储能不被允许提供“运转储备”,即为应对意外的供需误差所预留的发电量。如果允许电池储能提供运转储备,将增强其商业价值。
允许电池储能更多地参与市场将促进电池储能系统的持续创新和降低成本,同时为系统运营商提供宝贵的运营经验。
这种策略将与市场效益相符,并反映美国和欧洲近期的电力市场经验。
这也将有助于解决近期的产能和能源需求,因为电池和光伏发电通常比燃煤电厂的建设速度更快。
此外,它还有助于缓解未来新增燃煤发电与可再生能源之间的冲突。主要作为可再生能源发电备用电源的新建燃煤电厂要么很少运营,要么侵占了其他现有煤炭发电厂的运营时间和净收入,从而产生新搁浅资产的风险。
通过继续进行电力市场改革,也将促进对可再生能源发电和电力储存进行更有效的投资。
允许市场制定批发市场电价、允许可再生能源发电和电力储存参与批发市场,这可以提高其收入和利润。
此外,改革还将鼓励高效利用储能,这是我们的关键发现。储能可以为电力系统提供多种功能;批发电价有助于引导储能运营以最低的成本实现具有最高价值的功能。
中国国家能源局最近发出指令,要求将新型储能设施(非抽水蓄能)纳入电网调度运行,这是向我们概述的改革迈出的一步。
可能需要进一步确定适当的补偿机制,例如在某些省份对此类储能设施提供的所有服务进行容量补偿,以促进这些储能设施的可持续发展和并网。
最后,仅靠增加供应不太可能成为满足中国电力需求增长的最低成本方式。提高终端使用效率和“需求响应”也有助于降低供电的总体成本。
随着中国电力市场改革的不断深入,连接多个省份的区域市场设计,以及鼓励省份间资源共享的区域资源充裕性规划,也有助于以最具成本效益和最低碳的方式满足中国不断增长的用电量和高峰需求。


The post 嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠” appeared first on Carbon Brief.

At India’s ocean technology institute in Chennai, scientists have been developing a range of hi-tech mining equipment that can operate 5 or 6 kilometres underwater – from a remote-control submarine to a seabed soil tester and slurry pump.
Their task: to ensure that India is ready if deep-sea mining takes off by building the technology and knowledge about how – and where – critical minerals can be extracted from the depths of the ocean, even as dozens of nations call for a moratorium on this activity.
After a series of successful deep-water equipment tests in recent years, government officials say big strides have been made.
“(India) has made significant progress in building the scientific and technological foundations for deep-sea mining,” a spokesperson for the Ministry of Earth Sciences, which oversees the institute, told Climate Home News.
Deep-sea ambitions
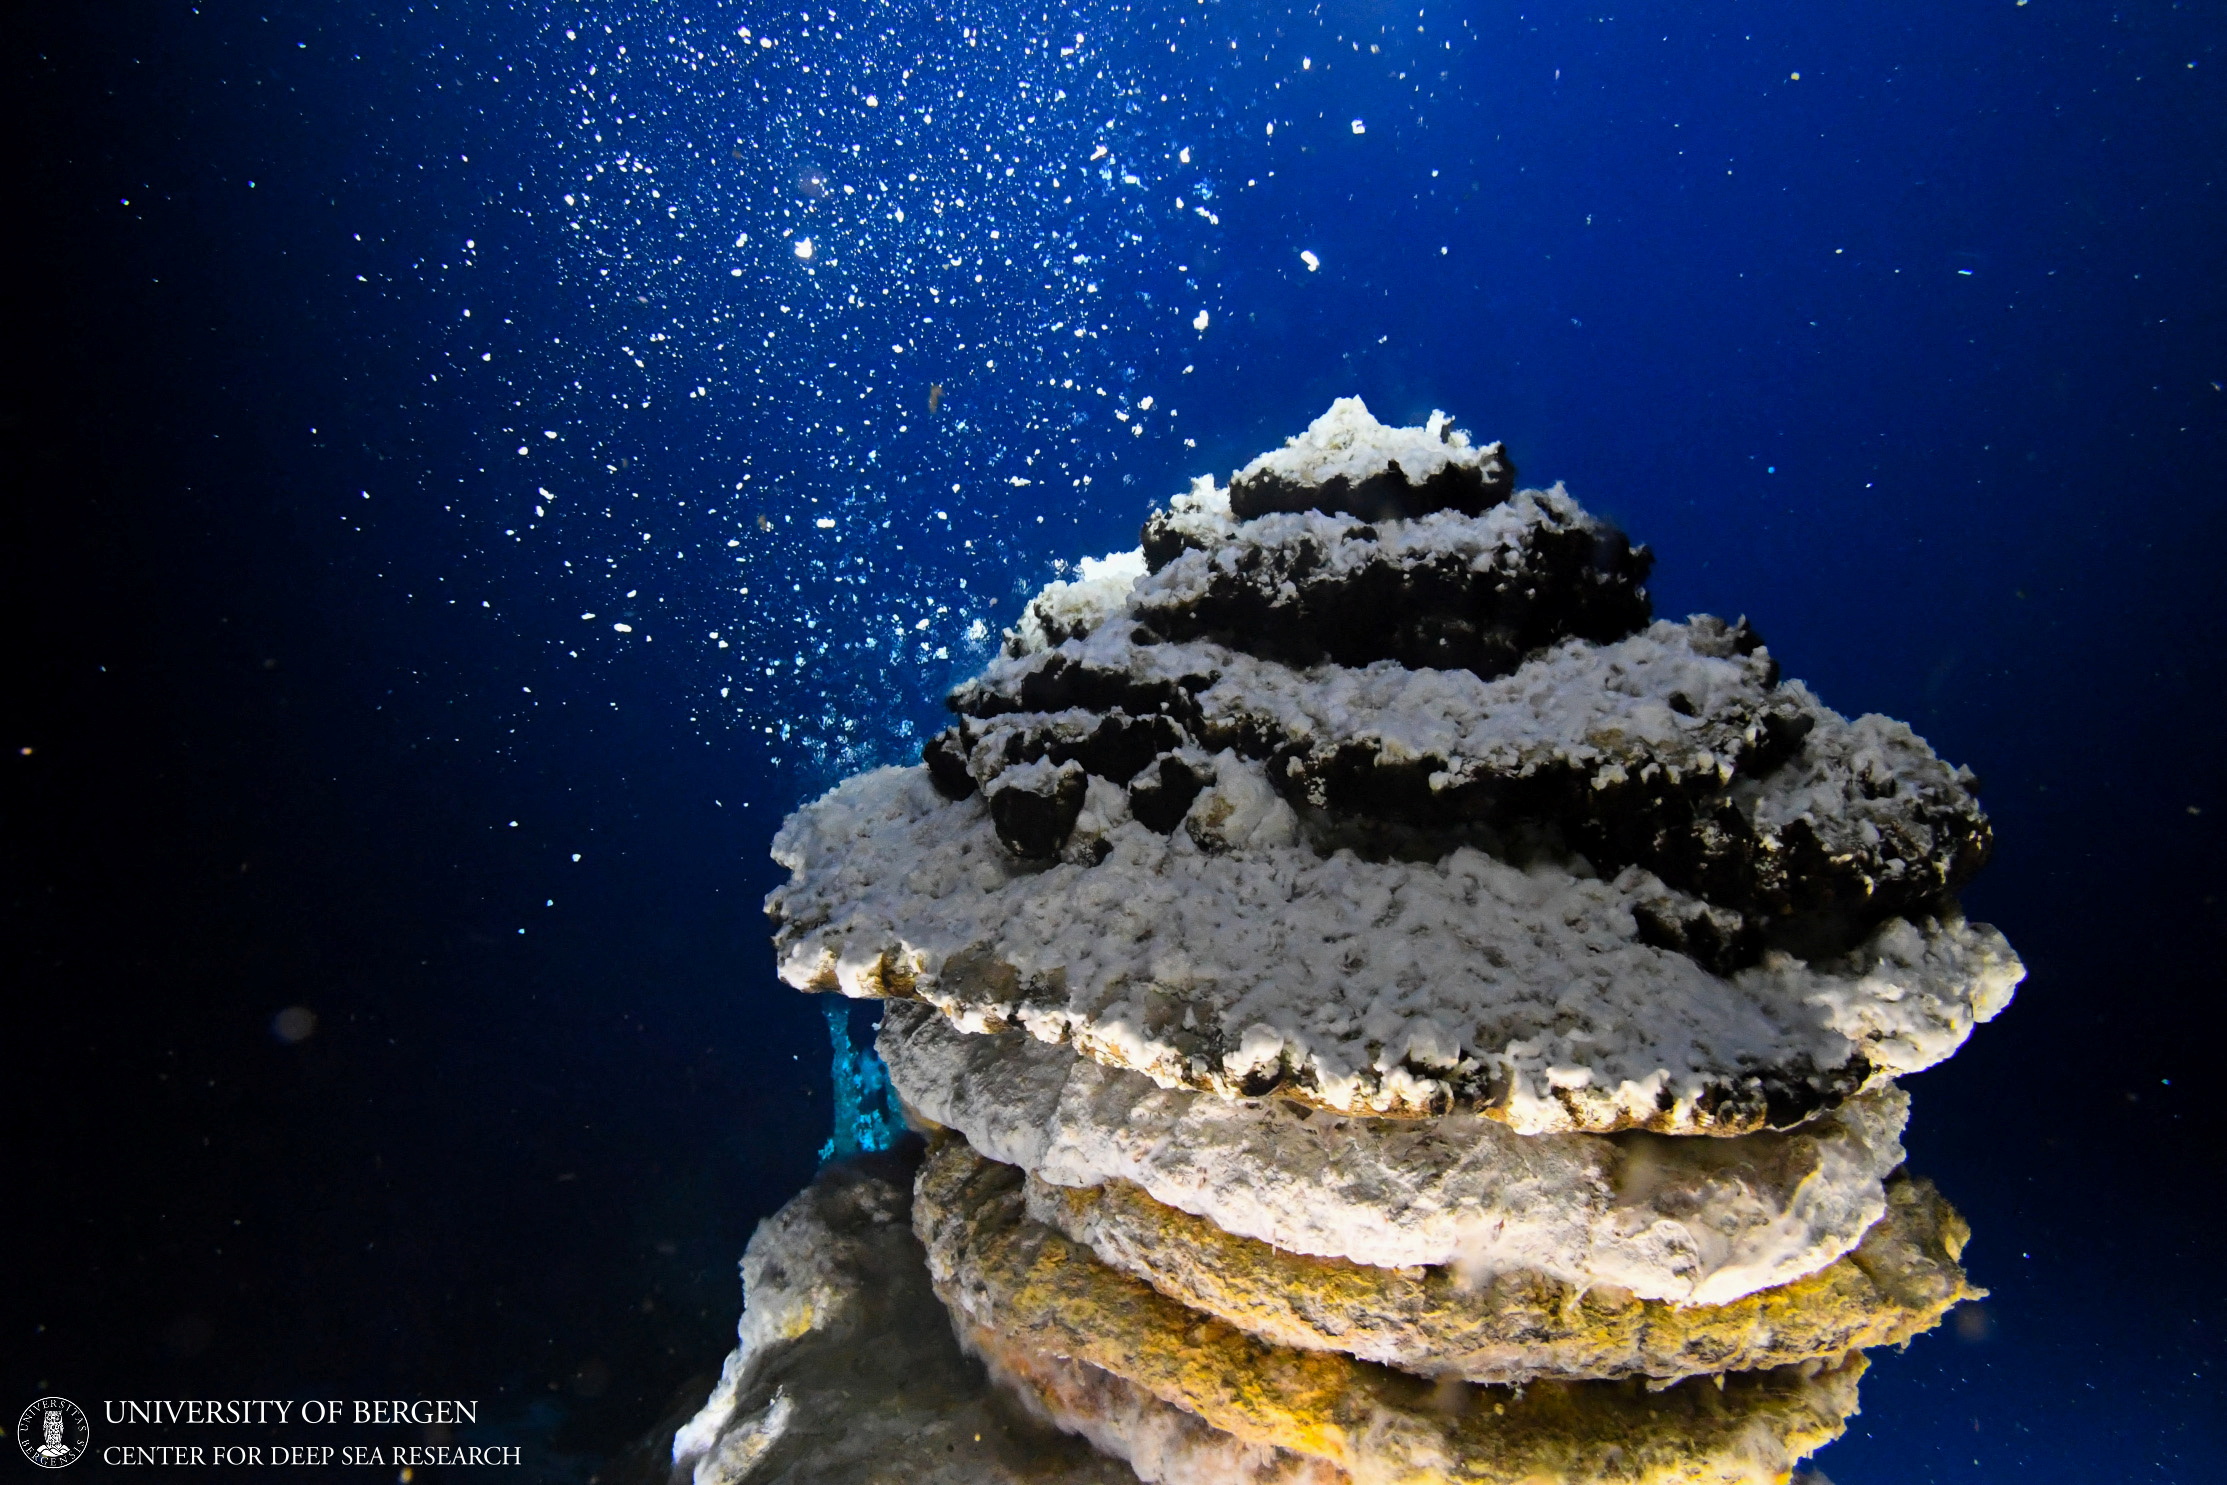
Highlighting the country’s ambitions, it signed a second contract last year with the International Seabed Authority (ISA), the UN body that regulates the deep ocean floor, to explore polymetallic sulphides, which contain minerals such as copper and zinc – key ingredients in clean energy technologies such as wind turbines and storage batteries.
Besides the two polymetallic sulphide contracts, it holds an ISA exploration contract for polymetallic nodules in the Central Indian Ocean Basin. China and South Korea are the only other countries with three ISA exploration contracts directly under government control.
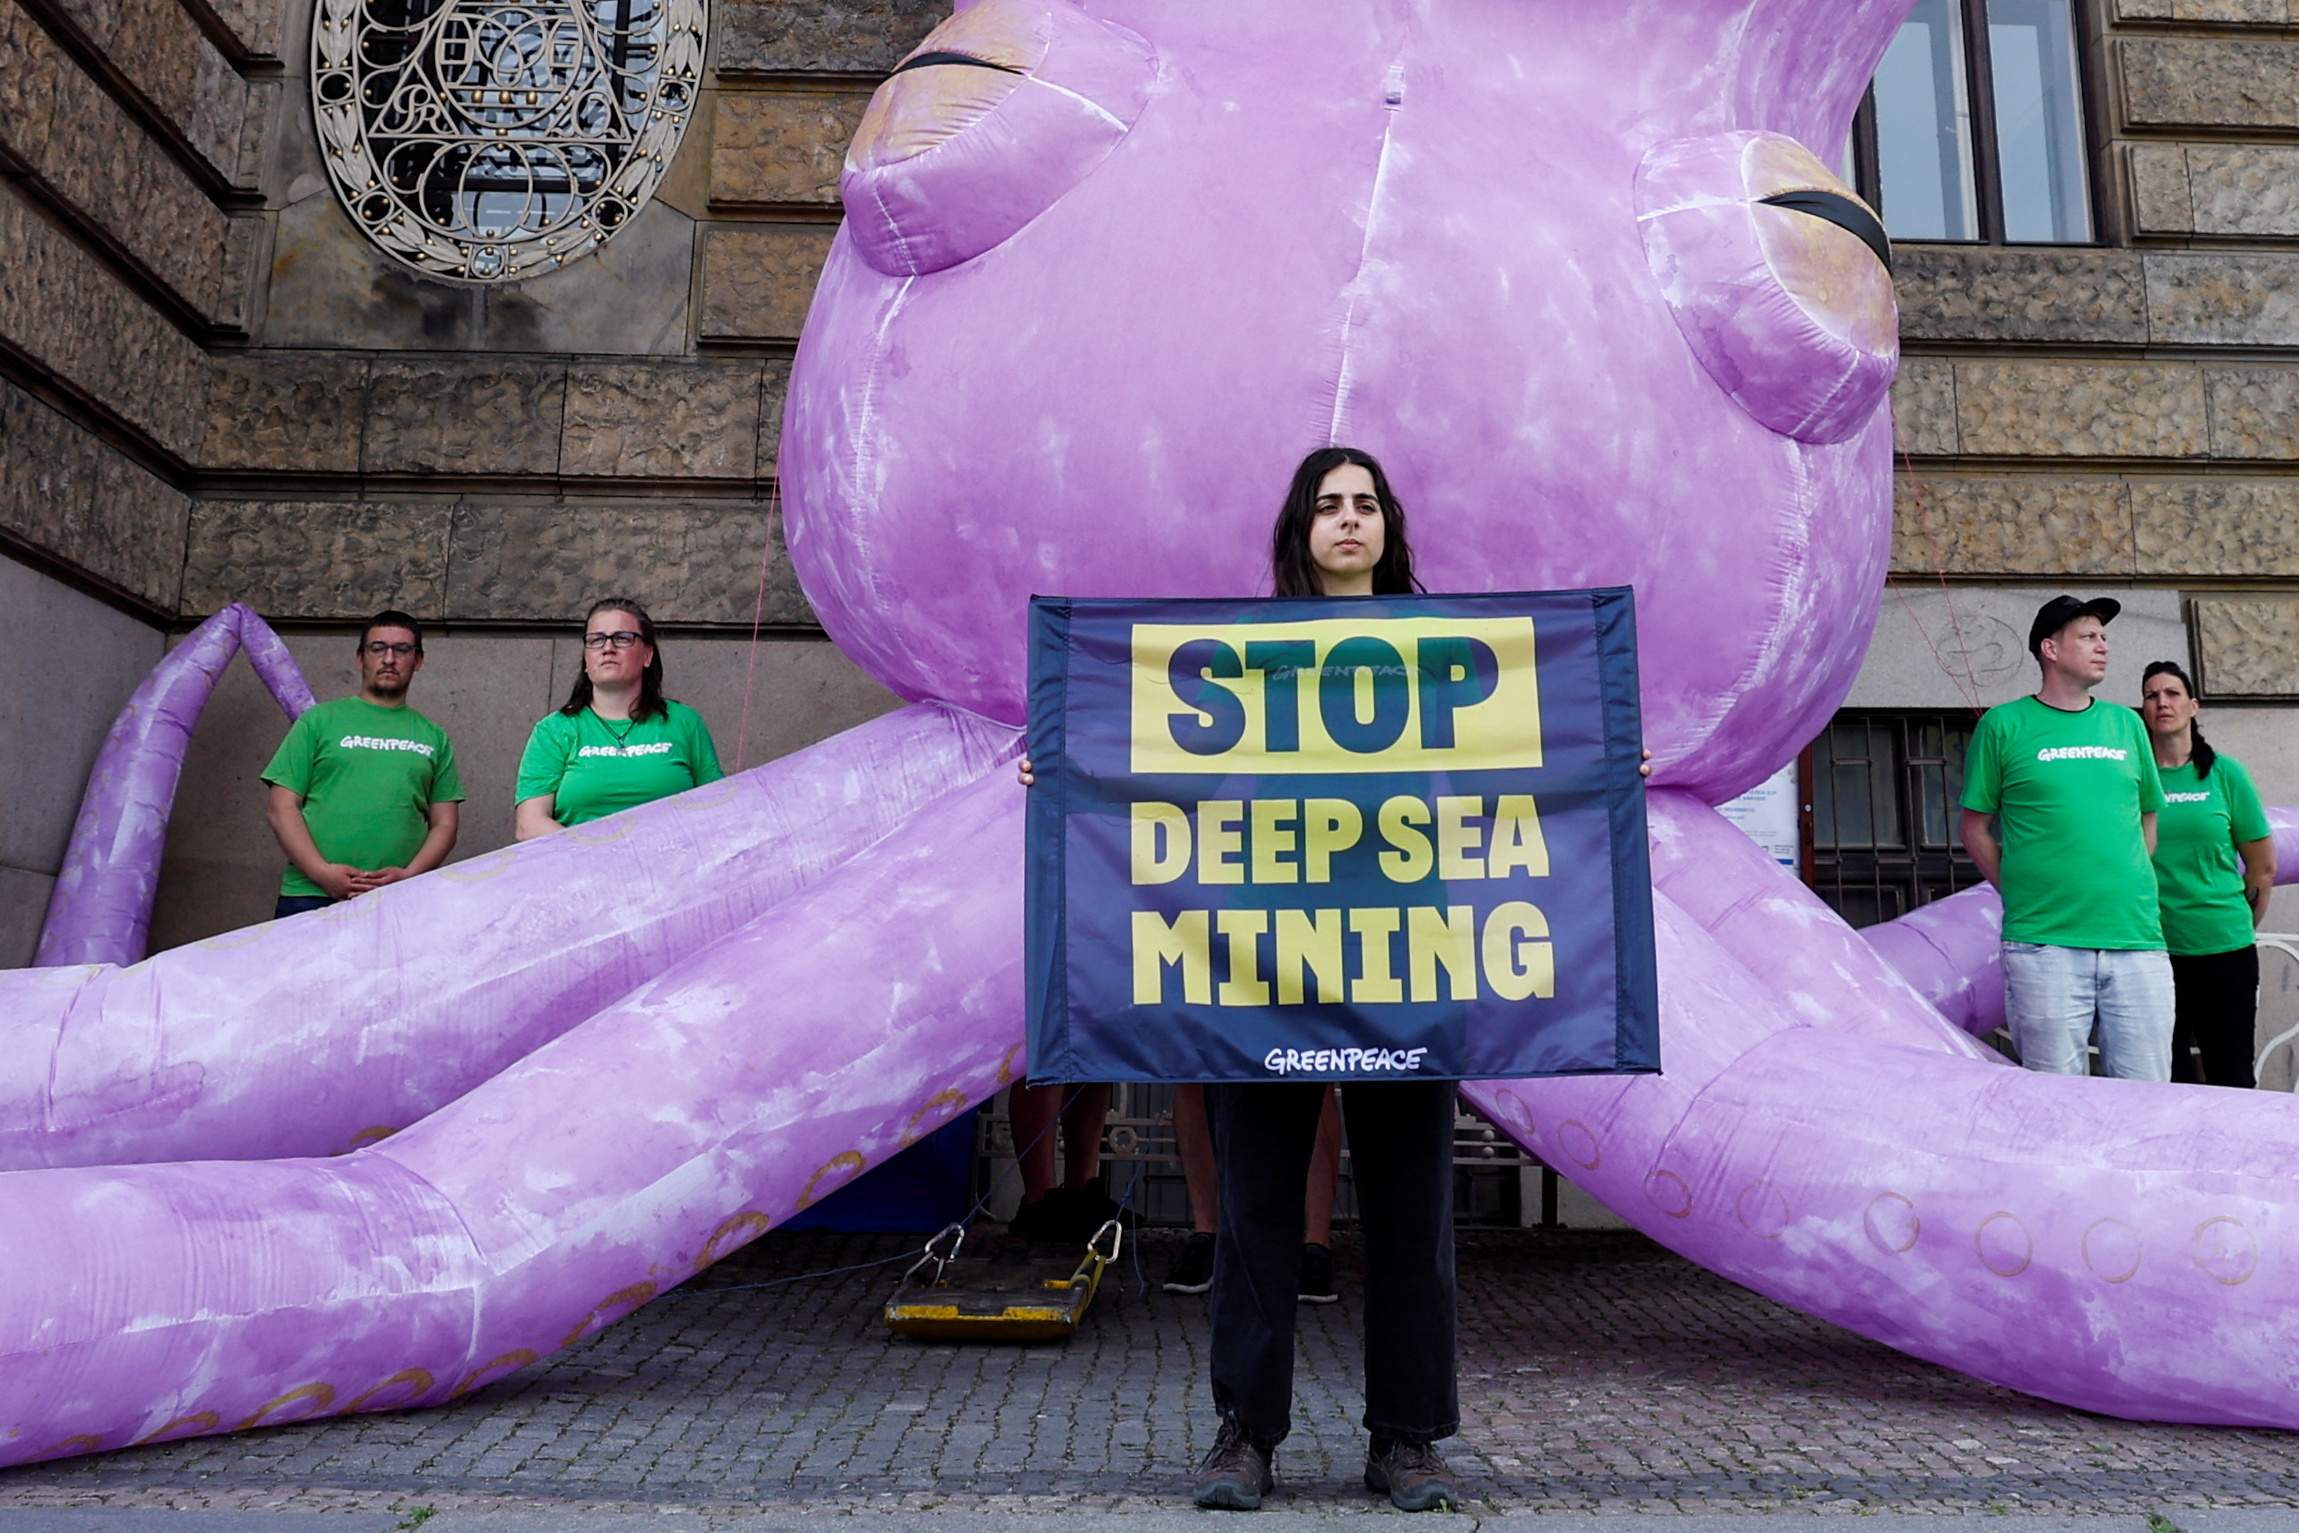
Yet deep-sea mining is controversial for its potential impacts on the ocean floor, a little-studied, undisturbed ecosystem that should be protected by a precautionary pause on the activity, marine scientists say.
A coalition of 46 countries is pushing for a moratorium on deep-sea mining, until enough scientific evidence shows the ecosystem impacts can be reduced.
Despite this push, ISA contract-holders are still racing to develop the technical capabilities to mine the ocean floor, betting that commercial-scale operations will eventually be permitted and prove economically viable. India, an emerging clean-tech powerhouse, does not want to fall behind competitors, government officials told Climate Home News.
-
Race to host High Seas Treaty HQ heats up as Chile reaffirms bid
Chile’s ocean protection record and concerns over a rival Chinese bid keep it in play, despite questions over the Kast government’s environmental policies -
As marine heat breaks records, countries seek ocean roadmap at COP31
Africa and the EU are leading a push for COP31 to deliver a roadmap that lays out measures to protect fast-warming oceans -
Governments weigh response to US going alone on deep-sea mining
At annual talks in Kingston, the International Seabed Authority (ISA) launched legal processes to challenge a unilateral US push for deep-sea mining
Since India obtained its first ISA exploration contract more than two decades ago, extensive survey work has been undertaken in the 75,000-square-km contract area in the Central Indian Ocean Basin, which is estimated to hold hundreds of millions of tonnes of polymetallic nodule resources, according to the Indian government.
More recently, survey work has identified several potential locations in the polymetallic sulphide areas.
The seabed survey work and the deep-sea mining tools being developed in Chennai put India among only a small group of countries to have made such progress. China is another leader in mapping the ocean floor for potential mineral resources that could one day be extracted.
At a meeting in Jamaica in July, the ISA continued negotiations on rules for commercial deep-sea mining but failed to adopt the Mining Code. Delegates agreed that further work had to be carried out to resolve outstanding issues, with the ISA tasked with devising a roadmap towards hopeful adoption.
Technical and regulatory hurdles
Even if a regulatory framework is established, commercial development remains a distant prospect in the exploration contract areas awarded to India by the ISA, government officials and experts say.
“There is still quite a distance to be covered to convert the resource to reserves,” the ministry spokesperson said.
Pradeep Singh, an ocean governance expert at the Oceano Azul Foundation, a Portugal-based international nonprofit, described India’s deep-sea mining programme as being firmly in “an exploratory phase”.
“There is still a lot more work left to be done in order to achieve sustained extraction technology, address operational hurdles (such as shipboard processing and trans-shipment), and develop onshore refining,” Singh told Climate Home News.
“It would also appear, from publicly available information, that none of the programmes will be ready to move into the exploitation phase anytime soon,” Singh added.
Deep-sea real estate
Instead, the government’s longer-term vision for India’s ISA contracts is centred on “a combination of mineral/resource security, indigenous technology development, scientific capability and eventual industrial readiness”, the ministry spokesperson said.
But for as long as deep-sea mining remains commercially unviable, Singh said securing exploratory licences may be more about “real estate and as a projection of dominance”.
“The competition at the moment – if any – is more about investing in deep-sea operational capabilities rather than mineral resource extraction itself (which is currently not competitive),” Singh said.
Threat to ocean biodiversity
In tandem with India’s deep-sea mineral survey work, years of research by government environmental scientist Dr. Rengaiyan Periasamy on Indian Ocean ridges highlight the risks that future deep-sea mining poses to ocean biodiversity.
“Our studies have led to the discovery of more than 10 new species,” Periasamy told Climate Home News from the Kochi-based Centre for Marine Living Resources & Ecology, which also operates under the Ministry of Earth Sciences.
They warn that deep-sea mining could cause habitat destruction, persistent sediment plumes and disruption of ecosystem processes throughout the water column, with potentially irreversible impacts occurring before many species and ecosystems are fully understood.
