

The bulk of steelmaking around the world still relies on coal-based blast furnaces.
As a result, the steel and iron industry is responsible for 7% of greenhouse gas emissions and 11% of carbon dioxide emissions globally, according to the consultancy firm Global Efficiency Intelligence.
This is more than the total emissions from all the world’s cars and vans.
With steel critical to the building out of decarbonised energy infrastructure, production is expected to continue to rise over the coming years, meaning the potential for decarbonisation is “enormous”, according to not-for-profit data organisation Global Energy Monitor (GEM).
GEM’s annual “Pedal to the Metal” report reveals that 93% of new steelmaking capacity announced thus far in 2024 promises to use lower emission electric arc furnaces (EAFs).
It also shows that 49% of the world’s steelmaking capacity under development now uses EAFs, up from just 43% in 2023 and 33% in 2022.
Of this, nearly all of the capacity announced since the beginning of 2024 operates using EAFs, the non-governmental organisation’s Global Steel Plant Tracker (GSPT) shows.
The tracker covers 2,207m tonnes per year (mtpa) of operating steelmaking capacity and an additional 774mtpa of steelmaking capacity under development globally, across 1,163 individual plants in 89 different countries, analysis of which is captured in its annual report.
However, while the report suggests a positive progression towards lower emission technologies in the sector, the increase in the announced projects is not yet leading to a construction of EAF overtaking coal-based production methods.
Coal-based blast furnace-basic oxygen furnaces (BF-BOFs) – where blast furnaces are used to produce iron from ore and oxygen converters then turn this, with some additional elements, into steel – continue to dominate the projects under construction, meaning “pressure must be maintained all the way through to project completion if real progress is to be seen”, the report finds.
Growth of EAFs
Incoming steelmaking capacity is more heavily EAF-based than ever before, according to GEM’s new report.
There is currently 774mtpa of steelmaking capacity under development, of which 223mtpa is in the advanced development stage.
Based on data from April 2024, the GSPT shows that nearly half of the capacity under development (337mtpa) is EAFs.
Just 36% of steelmaking capacity announced in 2020 with a known production route used EAFs, while in 2023 that number had increased to 92% according to GEM. This grows to 93% of capacity when looking at steelmaking capacity under development announced in 2024.
This “indicates a significant shift toward electric arc furnace steelmaking in the years to come”, the report notes.
Meanwhile, of the 212mtpa of steelmaking capacity slated for retirement, 88% if BOF-based.
However, a net increase in BOF-based capacity is expected over the coming years. If all planned developments and retirements take effect, an additional 171mptpa of BOFs is expected to be added to the global fleet, along with 310mtpa of EAF and 80mtpa of unknown technologies.
Despite this growth in BOFs, the surge of EAF means the steel sector is getting increasingly close to meeting the International Energy Agency’s (IEA) suggested 2030 target.
In its net-zero by 2050 roadmap, the IEA suggests that the share of steel produced by EAF should grow from 24% in 2020, to 37% by 2030 and then 52% by 2050.
Considering all planned capacity and retirements, GEM now estimates that the global steel fleet is expected to reach 36% EAF by 2030, noting: “This is still not sufficient to meet the IEA [net-zero] climate target, but with heightened momentum the goal is increasingly attainable.”

Continuing to construction
While EAF-steelmaking is being announced at “record rate”, GEM finds that less than 14% of this potential capacity has moved into construction.
Of those that have moved into construction, around 46% are still BOF-based. As such, “while we may be within reach of net-zero targets based on proposed electric arc furnace capacity, actually achieving these goals requires follow-through”, the report notes.
Caitlin Swalec, program director for heavy industry at GEM, said in a statement:
“The progress is promising for a green steel transition. Never before has this much lower-emissions steelmaking been in the pipeline. At the same time, the buildout of coal-based capacity is concerning. What the industry needs now is to make these clean development plans a reality, while backing away from coal-based developments.”
As well as the buildout of new coal-based capacity being out of alignment with a net-zero future, it poses a threat of carbon lock-in and stranded assets, GEM notes.
Blast furnaces are becoming riskier investments given the limited options to mitigate emissions from both the furnaces themselves and the upstream emissions from the metallurgical coal mining, it adds.
Estimating an investment of $1-1.5bn per mtpa capacity at an integrated BF-BOF site, GEM found that the future stranded-asset risk could be as high as $554bn in 2023, falling to $400bn in 2024 due to the continued fall in BOF capacity under development.
Astrid Grigsby-Schulte, project manager for steel at GEM tells Carbon Brief:
“As we grow closer to key decarbonisation milestones, coal-based developments get further out of alignment with the direction the industry is moving and present a greater risk of stranded assets to steelmakers. Coal-based, emissions-intensive blast furnaces represent significant investments that often require decades to recoup. This makes them extremely risky for developers, particularly in countries with stated net zero commitments.”

The limited options for mitigating the climate impact of BOF-steelmaking was also highlighted within a recent report from the thinktank Sandbag.
While carbon capture, utilisation and storage (CCUS) is often touted as a “catch all” solution, its effectiveness varies widely across applications, Sandbag’s “Steel & CCS/U” report finds.
For steel production, BF-BOFs with carbon capture are unlikely to be cost-competitive with EAFs, the report finds. Although given the slow pace of technological and market development, Sandbag anticipates capturing carbon will play a limited role in the steel industry.
China transitions to EAFs
India has now replaced China as the top steel developer globally, with a pipeline of 258mtpa of capacity, of which 177mtpa is BOFs, according to GEM.
China has a pipeline of 150mtpa meaning, collectively, China and India are responsible for 53% of all developments globally.
Asia operates 68% of all steelmaking capacity (1,508mtpa), the majority of which is in China (1,075mtpa), India (123mtpa) and Japan (109mtpa).
When looking specifically at emissions-intensive BOF production, Asia’s share of total operating capacity increases to 80% (1,181mtpa), of which 918mtpa is in China.
Currently, China has 157mtpa of operating EAFs (22% of the global capacity), followed by the US, Turkey, Iran and then India.
According to a new report from the Centre for Research on Energy and Clean Air (CREA), China did not issue any new permits for coal-based steelmaking in the first half of 2023. This is the first time this has happened since the nation’s “dual carbon goals” were announced in September 2020.
During the first six months of 2024, Chinese provincial governments permitted 7.1mtpa of steelmaking capacity, all of which were EAFs marking a “turning point” for the country’s steel industry, CREA notes.
Xinyi Shen, researcher at CREA and the report’s lead author, tells Carbon Brief: :
“China’s EAF steelmaking has been developing rather slowly in the past few decades, mainly due to the constraint of scrap supply. However, as China’s steel demand reaches its peak and more scrap becomes available, a major opportunity arises to reduce emissions in the next 10 years. The government has accelerated plans to expand the national ETS to include the steel sector by the second half of 2024. By implementing carbon pricing on carbon-intensive products, EAF steelmaking would become more economically competitive and continue the growth.”
Despite India now overtaking China in terms of announced steelmaking capacity, China remains the biggest developer of EAF capacity overall, GEM’s report states. And while India has the most steel in development, 84% has not moved into construction.
As such, there is still an opportunity for India’s plans to change, with the percentage of BOFs to EAFs less set.
Chris Bataille, adjunct research fellow at the Columbia University Center on Global Energy Policy and lead author at the global Net Zero Steel project tells Carbon Brief:
“India’s core demand for steel is set to increase from 125mtpa to ~450mtpa by 2050, especially to meet key building and infrastructure needs. Our modelling suggests EAFs consistently rise from ~35 to 150mtpa by 2050. So the +250mtpa BF-BOFs is just barely feasible, but only over ~25 years and with some exports of BF-BOF steel.
“The difference will be between a world where strong climate policy succeeds and fails. If it fails and coal based BF-BOFs are built, then the +258mtpa looks barely feasible. If it succeeds, India is short on the necessary gas and especially clean electricity to power this amount of steel production. While the country does build a lot of EAFs, it builds up to 250mtpa of clean iron making over time, making the short term shortfall with clean HBI iron imports.”


The post ‘Significant shift’ away from coal as most new steelmaking is now electric appeared first on Carbon Brief.
‘Significant shift’ away from coal as most new steelmaking is now electric

SYDNEY, Thursday 30 October 2026 — In response to reports that the Albanese government is set to introduce draft legislation this year that would seek to ban data centres in Australia’s suburbs, Joe Rafalowicz, Head of Climate and Energy at Greenpeace Australia Pacific, said:
“These reports are a testament to the growing community opposition to these completely inappropriate AI factories that have sprung up across our suburbs, and Big Tech corporations should take heed — the data centre build-out must not happen without the endorsement of the Australian people.
“But the government can’t simply ship this problem out to regional Australia without addressing the fundamental issues with this extractive new industry.
“We’re already seeing a trend of AI data centre proposals moving to the regions, in areas that are more water-scarce, more environmentally sensitive, and next to sources of fracked and coal seam gas to support their massive BYO gas-fired power plans — a pattern we’ve seen play out in the United States.
“From the Beetaloo Basin in the NT to the Western Downs in Qld, we’re seeing a wave of AI data centre proposals that would see new gas fast-tracked to support their massive energy demand, and threaten to completely derail Australia’s energy transition.
“Just as suburban Australians are asking, “what for?”, regional communities like Berry Springs and Dalby do not want dirty data centres setting up shop with absolutely no benefit to their communities. Greenpeace is calling for a moratorium on AI data centre developments until strict and enforceable safeguards are in place to protect our climate and our communities.”
-ENDS-
Media contact
Kate O’Callaghan on +61 406 231 892 or kate.ocallaghan@greenpeace.org
AI data centre ban in suburbs would not address fundamental issues: Greenpeace
In the thick of the COP29 climate summit in Azerbaijan in 2024, the UN climate talks were rattled by what can only be described as a major PR disaster. The BBC, Reuters and The Guardian all carried headlines, attributed to leading climate policy experts, that the COPs were “no longer fit for purpose”.
The articles outlined a series of reforms called for in an open letter signed by 22 eminent scientists and politicians, including a former UN secretary-general and previous UN climate chief, with a further 150 lending their support. The headlines shook confidence in the COP process, just as governments were wrestling over a new climate finance goal.
The Club of Rome – which handled the media relations for the letter – hurried to say that its “constructive, supportive ideas” had been “misinterpreted”. Negotiators kept calm(ish) and carried on, in the end landing the finance goal after some high-stakes drama on the final day.
-
Early speakers’ list suggests few powerful leaders will attend COP31
Just 77 heads of state or government are scheduled to address the COP31 climate summit in Antalya, a third less than the COP28 peak -
Africa wants adaptation finance on COP31 agenda, raising risk of a fight
The African Group wants dedicated space on tripling adaptation finance, the Green Climate Fund and trade, setting up a possible clash

To my surprise, when I went back this week to read the letter again, I could not find the offending line about the COPs not being fit for purpose. The Club of Rome has yet to respond to my query about its disappearance.
Whatever happened to the wording, that sentiment has been widely shared. COPs have ballooned in size while the importance of their outcomes seems to have diminished since the 2015 Paris Agreement (with the exception of the 2023 COP in Dubai where countries agreed to transition away from fossil fuels in energy systems).
The same on the surface
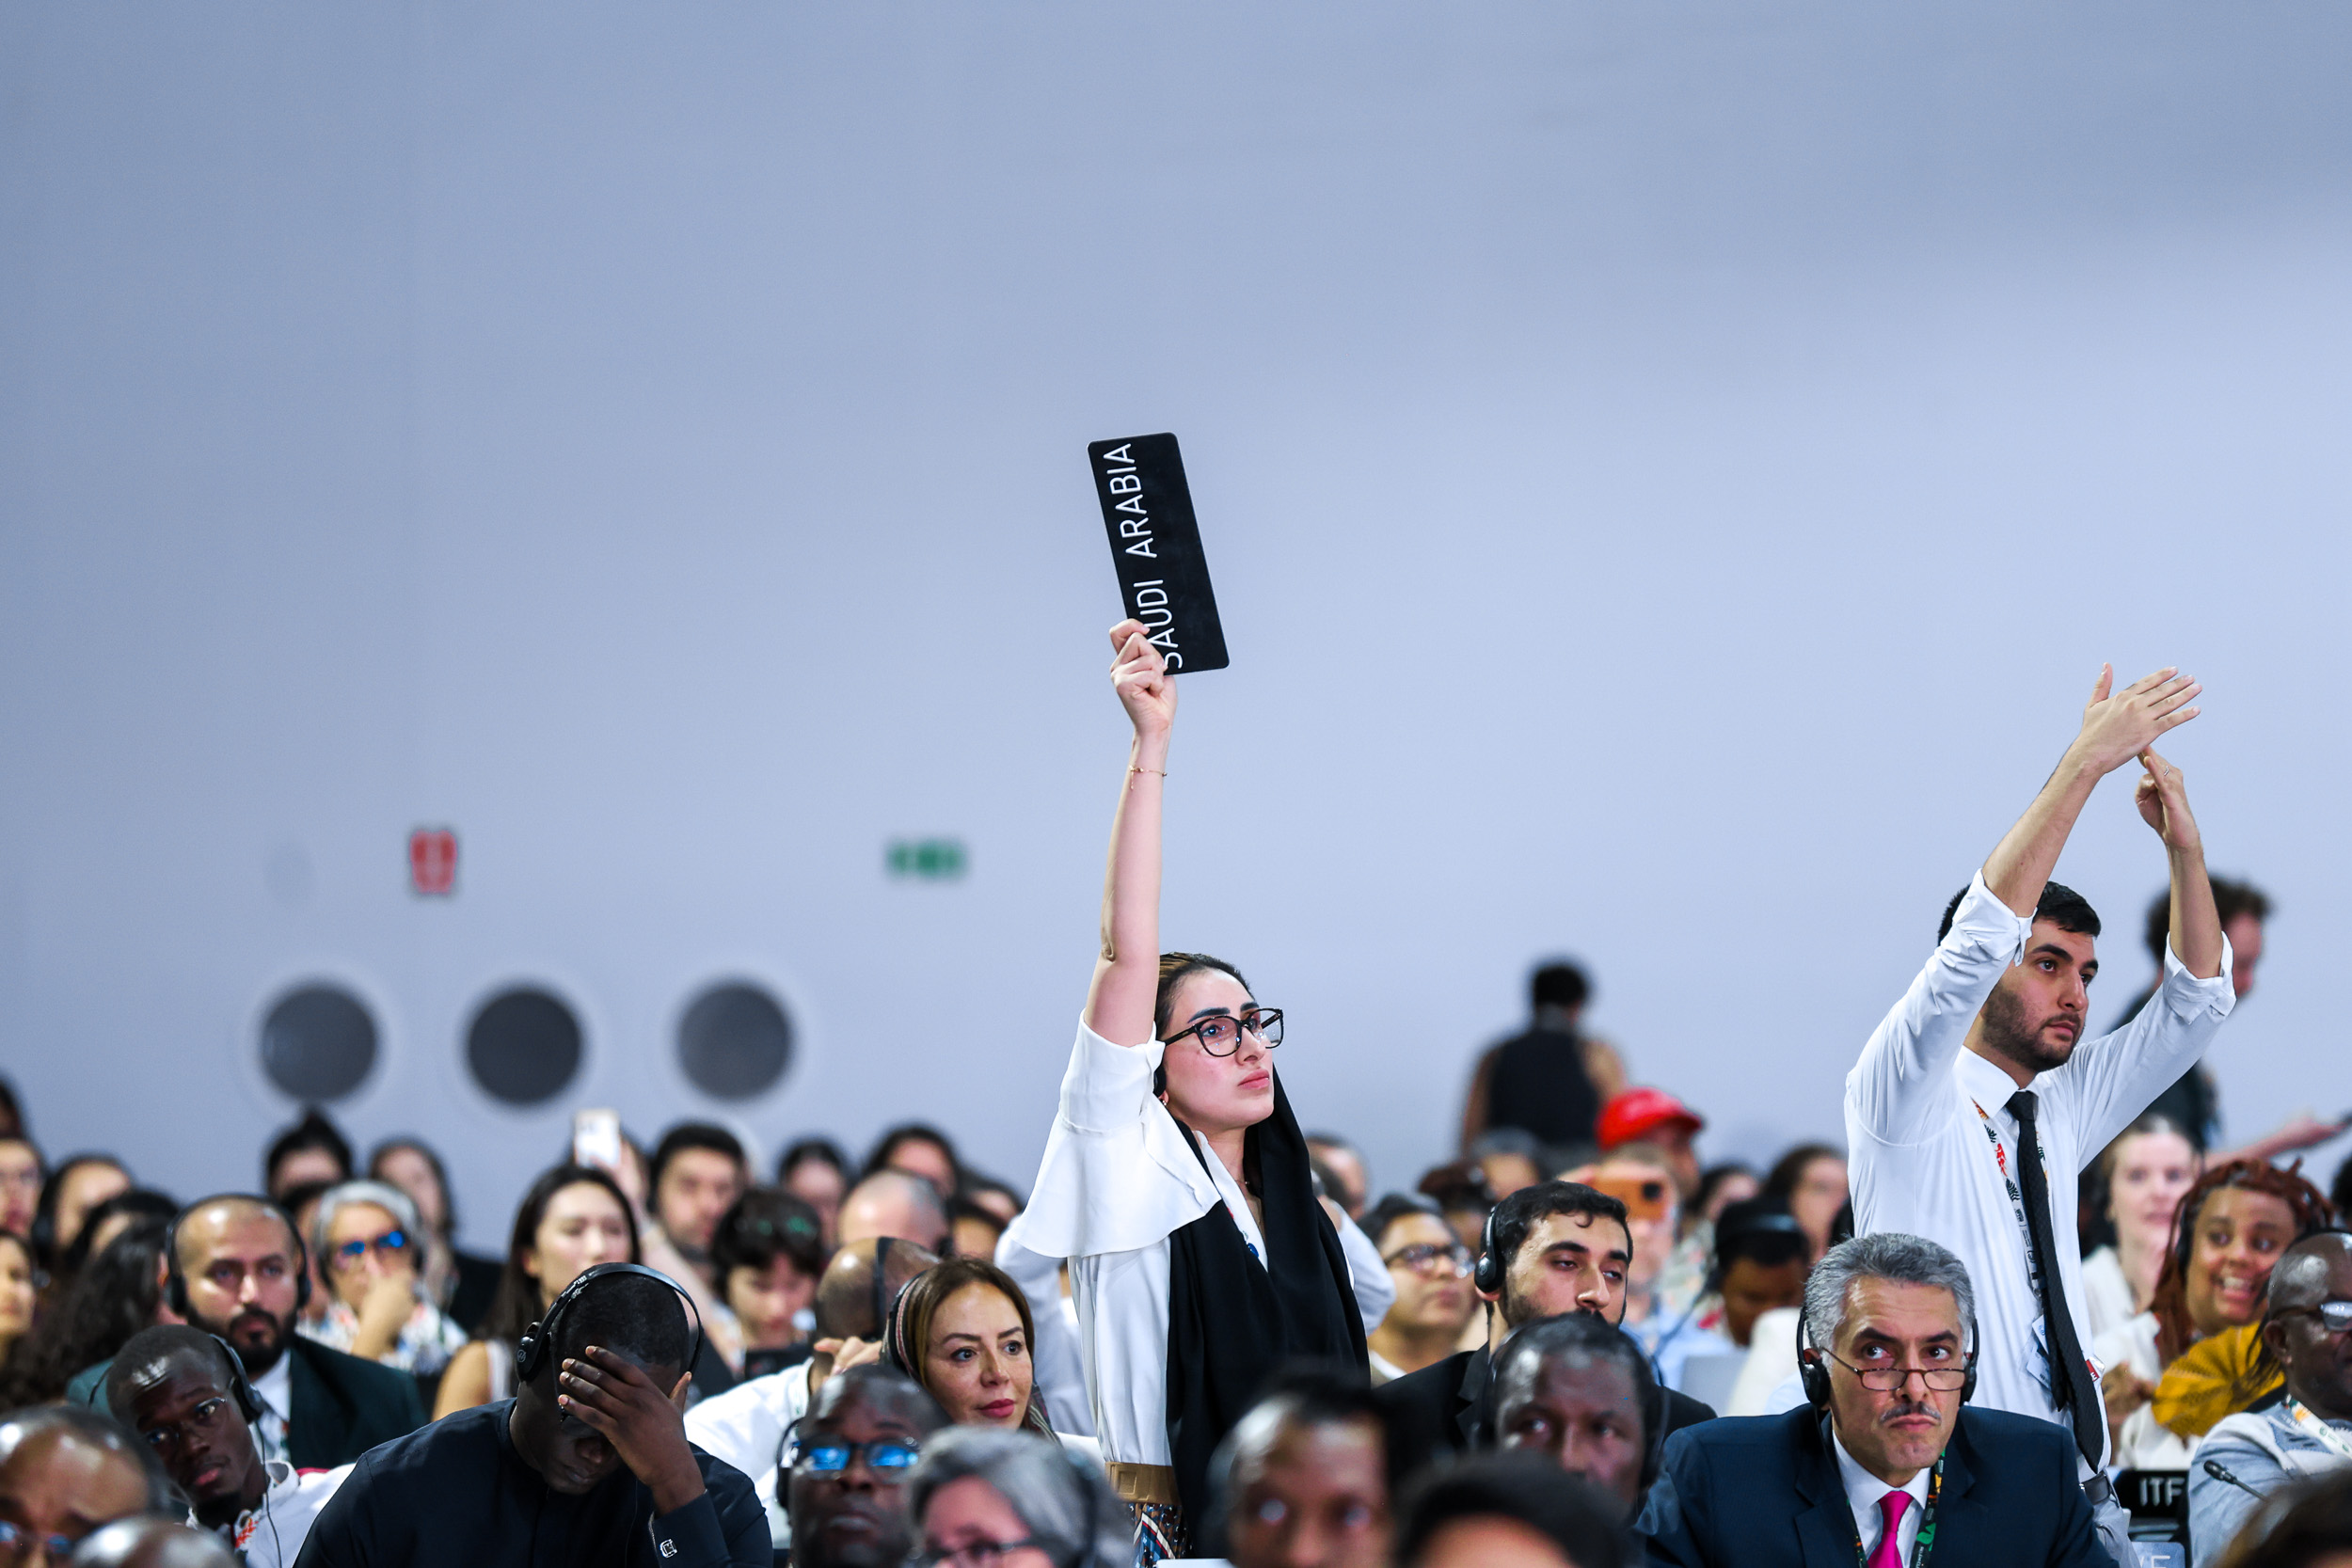
Two years on from those painful headlines in Baku, has anything changed for the better? You might be forgiven for thinking not. Official decisions are still made by consensus rather than the majority voting some have called for to stop blockers.
Tens of thousands of officials, activists and business execs still scurry around the halls to an ever-growing list of side events, roundtables and dialogues, while deals still come down to rows, all-nighters and jargon-filled texts adopted to rounds of applause.
But it would not be true to say that COPs have completely failed to respond to the very real need to translate the words of the Paris Agreement into action in the outside world.
Global warming is projected to be around 1.3C lower this century than it would have been if the world had not committed to tackle the climate crisis under that accord. Developing countries have a valued space at COPs in which their voices have equal weight in decision-making, unlike in many other international fora. And most importantly, perhaps, there has been a subtle shift, tipping the balance away from negotiating towards doing.
Brazil branded last year’s summit in Belém as the “COP of Implementation”, corralling the sprawling Action Agenda into six axes. This was a bid to impose some structure on the mushrooming efforts between governments, UN agencies, cities, businesses and civil society to set targets and spur faster results on their pet issues, from methane emissions to health and adaptation in conflict zones. COP30 alone saw the launch of 120 “plans to accelerate solutions”.
COP30 roadmaps off the cuff
Meanwhile, as the formal negotiations drew to a close, it was clear that consensus decision-making was evolving into something a little more improvised.
With only around half of all countries on board with the idea of a roadmap to transition away from fossil fuels, COP30 President André Corrêa do Lago announced his team would put one together over the coming year, along with another on how to meet a global goal to halt deforestation by 2030. Those roadmaps will be launched next week, presented and discussed at COP31, though it’s still unclear whether or how they’ll be incorporated into the formal negotiating agenda.
Some leading policy-makers don’t think that matters too much. Speaking to journalists before the Antalya summit, COP30 CEO Ana Toni and Dutch climate minister Stientje van Veldhoven said “coalitions of the willing” can move ahead without needing consensus from the COPs. This, they said, was evident this year at the first global conference on TAFF, co-chaired by van Veldhoven and attended by 60 countries.
“Consensus or no-consensus in the general COP doesn’t make a difference for the choices I have to make in my country to get my country to phase out fossil fuels,” said the Dutch minister. The Netherlands recently became one of the first to publish a national TAFF plan.
COP31 banks on flagship voluntary initiatives
This thinking has permeated the management and expected outcomes of this year’s COP too. Earlier this year, Türkiye, supported by international energy agencies, floated the idea of a voluntary goal to boost electrification to 35% of the world’s final energy consumption by 2035 – and this is now being touted as one of the main results to be expected from Antalya.
Türkiye is also championing a pledge on AI and climate, while co-host Australia is pushing to ease access to climate finance for least developed countries and small island states.
COP31 presidency announces AI pledge as UN climate chief says Big Tech ‘on thin ice’
None of these needs consensus. But with a political cover decision already in the works, as trailed by the COP presidents, they – and perhaps the fossil fuel roadmap – may find a home in the official text if language acceptable to most can be found, giving them them additional weight.
UNFCCC reform process in the shadows
Formal reform is underway too, if quietly. UN climate chief Simon Stiell is leading a review informed by ongoing consultations with a group of 15 well-respected climate policy experts, three of whom signed the open letter in 2024.
Among them is leading Swedish climate and sustainability scientist Johan Rockström who has strong ideas about how to make COPs function better, including a switch to majority voting. He told the same press briefing nothing stands in the way of this, because the rules of procedure for making decisions at COPs have never been formally agreed.
Still, to get away from the default setting of consensus would require agreement on a new system that may be impossible to achieve given the rise in bullying tactics by fossil fuel heavyweights.
Comment: The UN climate process was built for negotiation – now it must support implementation
The deliberations with the high-level policy gurus, as reflected in a summary of June’s session in Bonn, largely echo what’s already happening organically, calling for stronger partnerships and accountability both in and between the Action Agenda and negotiations. It doesn’t mention voting.
A general overview of the reform exercise says that “improving and optimizing the [UN climate] process over the medium to long term… will be critical to fostering trust, enhancing collaboration, and catalyzing increased ambition”.
In the short term, don’t hold your breath for anything concrete on reform at COP31 but watch for signs in what ends up dominating the headlines from Türkiye.
The post Editor’s Desk: COP reform is happening quietly, behind the headlines appeared first on Climate Home News.
Editor’s Desk: COP reform is happening quietly, behind the headlines