


Lithium and electric vehicles (EVs) have taken center stage in decarbonizing the transportation sector. The demand for lithium—a crucial component in battery technologies—is surging alongside the rapid growth of EV adoption. A recent report by the International Council on Clean Transportation (ICCT), “A Global and Regional Battery Material Outlook”, captured this trend.
The report further highlights the dynamics of lithium supply and demand, the technological advancements shaping battery performance, and the role of EVs in achieving global sustainability goals. We crunch these aspects in the report, with the following key insights.
Lithium Gold Rush Fueling the EV Boom
Lithium, often called “white gold,” is the backbone of the global push toward electrification. Its role in powering lithium-ion batteries makes it indispensable in EVs, consumer electronics, and renewable energy storage systems.
- In 2023, vehicles accounted for 80% of lithium-ion battery demand, a figure expected to rise significantly as EV adoption accelerates worldwide.
With EV battery sizes increasing—offering longer driving ranges—lithium demand is set to quadruple by 2030. Annual requirements could exceed 622 kilotons by 2040 under baseline scenarios, with EVs contributing the lion’s share, per the ICCT report.

Lithium-ion batteries’ energy density and lightweight nature make them ideal for applications requiring portability and high performance.
However, lithium’s significance extends beyond EVs. Renewable energy systems, which rely on grid-scale storage solutions, rapidly drive demand for lithium-based batteries. With governments globally pushing for greener grids, the need for reliable, efficient energy storage has surged, further solidifying lithium’s critical role in the energy transition.
Cracking the Code: Innovations Tackling Lithium Supply Challenges
Meeting surging lithium demand comes with substantial hurdles. Mining and refining capacities need rapid expansion, but several challenges stand in the way. Environmental concerns, land access issues, and lengthy regulatory approval processes often slow the pace of new projects.
Geopolitical dependencies further complicate lithium supply. China controls around 60% of the global lithium refining capacity, creating vulnerabilities in supply chains heavily reliant on a single region.
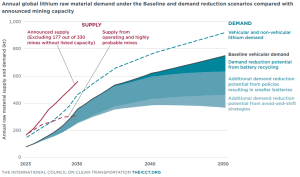
Efforts to diversify these operations are underway, with the United States, Australia, and Canada ramping up their domestic capabilities. To mitigate supply risks, the industry is exploring innovative solutions.
Recycling used lithium-ion batteries presents a significant opportunity. By 2030, recycled lithium could account for up to 10% of global supply, reducing the need for virgin material.
Companies like Redwood Materials and Li-Cycle are advancing recycling technologies, recovering lithium, cobalt, and nickel from spent batteries to reintroduce them into production cycles.
Government policies are playing a vital role in alleviating supply challenges. For example, the Inflation Reduction Act in the United States incentivizes domestic mining and processing, while Europe’s Critical Raw Materials Act aims to build a resilient lithium supply chain within the region.
Despite these efforts, achieving a balance between lithium demand and supply will require sustained investments, technological breakthroughs, and international collaboration.
EVs Transforming Transportation Worldwide
Electric vehicles (EVs) are reshaping global transportation, offering sustainable alternatives to internal combustion engine (ICE) vehicles.
EVs are more than a technological shift—they are essential in fostering a cleaner energy future by:
- Decarbonizing economies,
- Reducing greenhouse gas emissions, and
- Minimizing dependence on fossil fuels.
- By 2030, annual EV sales could surpass 40 million units, comprising nearly half of all light-duty vehicle sales.
This rapid growth is driven by continuous advancements in lithium-ion battery technology, which has increased energy density and reduced costs. EV ownership is projected to match or undercut ICE vehicles by 2027 in many regions, thanks to innovations like silicon anodes for better energy storage and solid-state batteries for enhanced safety and efficiency.
Despite these advancements, challenges persist. Inadequate charging infrastructure limits widespread adoption, though governments and private entities are rapidly expanding networks.
Europe plans to install over 1 million public chargers by 2025, while similar initiatives are underway in China and the U.S., the largest investors in charging infrastructure.
Global Trends: How Regions Are Leading the EV Charge
The global EV market also shows notable regional dynamics, with China, Europe, and the United States leading the charge. However, emerging markets are beginning to carve out their niches as well.
China: The Global Leader
China continues to dominate the EV market, accounting for more than 60% of global EV battery production and nearly half of EV sales in 2023. The nation’s stronghold on battery manufacturing comes from significant investments in gigafactories and raw material processing facilities. It is also coupled with government subsidies that make EVs more affordable for consumers.
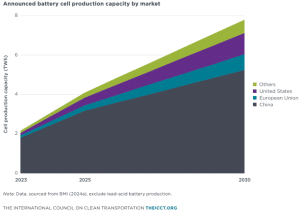
Additionally, local manufacturers like BYD and NIO are competing directly with global players like Tesla, offering diverse EV models across various price points.
United States: Scaling Domestic Production
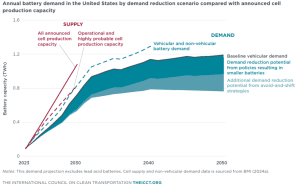
The U.S. is accelerating efforts to localize its EV supply chain, supported by initiatives such as the Inflation Reduction Act (IRA) and significant private investments in battery gigafactories. Companies like Tesla, General Motors, and Ford are ramping up EV production.
Meanwhile, partnerships with battery producers, such as Panasonic and LG Energy Solution, are strengthening domestic capabilities.
The IRA has spurred investments in mining and refining operations within North America, reducing dependency on overseas supply chains. By 2030, the U.S. aims to manufacture at least 20% of global battery capacity, a substantial leap from its current share.
Europe: Prioritizing Sustainability
Europe is positioning itself as a global leader in sustainable EV production. The European Union’s stringent emissions regulations and its Green Deal policies have accelerated the adoption of electric mobility across member states. Countries like Norway, Germany, and the Netherlands are at the forefront, offering generous subsidies and tax incentives for EV buyers.
In addition to fostering demand, Europe is heavily investing in battery production to reduce reliance on imports. Projects like Northvolt in Sweden and partnerships with automakers such as Volkswagen and Renault underscore the region’s commitment to building a self-sufficient EV ecosystem.
Emerging Markets: A New Frontier
While developed regions dominate the EV market, emerging markets are beginning to embrace electric mobility. Southeast Asia and South America, for instance, are focusing on smaller, more affordable EV models and two-wheelers to cater to their unique transportation needs.
Countries like India and Brazil are introducing policies to encourage domestic EV production and charging infrastructure development.
In Africa, EV adoption remains in its infancy, hindered by limited infrastructure and higher costs. However, renewable energy integration into charging networks and international investments in sustainable mobility projects are slowly opening opportunities for growth.
The Road Ahead for Lithium and EVs
The outlook for lithium demand and supply as well as EVs remains promising but requires coordinated efforts across industries and governments. Scaling battery productions and fostering technological innovation will be critical to meeting the ambitious targets for EV adoption and emissions reduction.
As the EV market grows, addressing supply chain issues and environmental concerns will ensure the viability of this transformative technology. And ultimately, lithium and EVs can power a cleaner, more resilient future with the right support and innovation.
The post Lithium is Driving the EV Boom: Demand to Quadruple by 2030 appeared first on Carbon Credits.

Carbon credit providers vs marketplaces is the first comparison many buyers try to make. In this comparison, a carbon credit provider is the project developer: the company that originates credits from its own projects and sells them directly. A carbon credit marketplace is a platform that lists credits from many projects at published prices.

Carbon Footprint
Democrats who call climate change an emergency should not defend a permitting system too slow to build the clean energy that would address it.”
Democrats, Take The Deal. New York Times editorial, Nov. 12.
Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
CCC’s MRV and Additionality article explains the separate evidence questions a project reviewer will ask.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Sources
[1] GHG Protocol, Land Sector and Removals Standard, version 1.1, and companion Guidance, June 2026: https://ghgprotocol.org/land-sector-and-removals-standard ; https://ghgprotocol.org/land-sector-and-removals-guidance
[2] Science Based Targets initiative, Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, especially pp. 16–17, 37, and 41: https://sciencebasedtargets.org/resources/files/SBTiFLAGGuidance.pdf
[3] Accountability Framework initiative, Accountability Framework and guidance for companies: https://accountability-framework.org/
[4] GHG Protocol, Frequently Asked Questions: Land Sector and Removals Standard, questions 10 and 18: https://ghgprotocol.org/blog/frequently-asked-questions-land-sector-and-removals-lsr-standard

‘COP-out’: COP31 fails to deliver the ambition needed to phase out fossil fuels and address climate breakdown
COP31 Bulletin Day 13: New draft retains electrification goal but delays adaptation finance and science decisions

How “Marie Antoinnete” Can We Get?

-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19
-

 Climate Change1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Renewable Energy5 months ago
Send a Bible to a Starving Child
-

 Green Living2 years ago
Our Picks for the Top 2024 Black Friday and Cyber Week Sales From Sustainable Brands