

China’s carbon dioxide (CO2) emissions are set to fall in 2024 and could be facing structural decline, due to record growth in the installation of new low-carbon energy sources.
The new analysis for Carbon Brief, based on official figures and commercial data, shows China’s CO2 emissions continuing to rebound from the nation’s “zero-Covid” period, rising by an estimated 4.7% year-on-year in the third quarter of 2023.
The strongest growth was in oil demand and other sectors that had been affected by pandemic policies, until the lifting of zero-Covid controls at the end of 2022.
Other key findings from the analysis include:
- China has been seeing a boom in manufacturing, which has offset a contraction in demand for carbon-intensive steel and cement due to the ongoing real-estate slump.
- The emissions rebound in 2023 has been accompanied by record installations of low-carbon electricity generating capacity, particularly wind and solar.
- Hydro generation is set to rebound from record lows due to drought in 2022-23.
- China’s economic recovery from Covid has been muted. To date, it has not repeated previous rounds of major infrastructure expansion after economic shocks.
- There has been a surge of investment in manufacturing capacity, particularly for low-carbon technologies, including solar, electric vehicles and batteries.
- This is creating an increasingly important interest group in China, which could affect the country’s approach to domestic and international climate politics.
- On the other hand, coal power capacity continues to expand, setting the scene for a showdown between the country’s traditional and newly emerging interest groups.
Taken together, these factors all but guarantee a decline in China’s CO2 emissions in 2024.
If coal interests fail to stall the expansion of China’s wind and solar capacity, then low-carbon energy growth would be sufficient to cover rising electricity demand beyond 2024. This would push fossil fuel use – and emissions – into an extended period of structural decline.
- Emissions are set to fall in 2024
- Why emissions grew in Q3 of 2023
- Coal expansion threatens China’s international commitments for 2025
- Solar, wind and hydropower set to surge in 2024
- Continued clean-power growth can peak emissions in 2024
- Why did clean energy investments surge during and after Covid?
- What comes next for China’s emissions peak and decline
- Data sources
Emissions are set to fall in 2024
China’s CO2 emissions have seen explosive growth over recent decades, pausing only for brief periods due to cyclical shocks.
Over the past 20 years, its annual emissions from fossil fuels and cement have climbed quickly almost every year – as shown in the figure below – interrupted only by the economic slowdown of 2015-16 and the impact of zero-Covid restrictions in 2022.
While CO2 is rebounding in 2023 from zero-Covid lows (see: Why emissions grew in Q3 of 2023), there have also been record additions of low-carbon capacity, setting up a surge in electricity generation next year. (See: Solar, wind and hydropower set to surge in 2024.)
Combined with a rebound in hydro output following a series of droughts, these record additions are all but guaranteed to push fossil-fuel electricity generation and CO2 emissions into decline in 2024, as shown in the figure below.
Year-on-year change in China’s annual CO2 emissions from fossil fuels and cement, million tonnes. Emissions are estimated from National Bureau of Statistics data on production of different fuels and cement, China Customs data on imports and exports and WIND Information data on changes in inventories, applying IPCC default emissions factors and annual emissions factors per tonne of cement production until 2019. Monthly values are scaled to annual data on fuel consumption in annual Statistical Communiques and National Bureau of Statistics annual Yearbooks. Chart by Carbon Brief.
Moreover, with the power sector being China’s second-largest emitter and with other major sectors, such as cement and steel, already seeing CO2 falling, this drop in power-sector emissions could drive a sustained, structural emissions decline for the country as a whole.
This is because – for the first time – the rate of low-carbon energy expansion is now sufficient to not only meet, but exceed the average annual increase in China’s demand for electricity overall. (See: Continued clean power growth can peak emissions in 2024.)
If this pace is maintained, or accelerated, it would mean that China’s electricity generation from fossil fuels would enter a period of structural decline – which would also be a first.
Moreover, this structural decline could come about despite the new wave of coal plant permitting and construction in the country. (See: Coal expansion threatens China’s international commitments for 2025.)
In addition, record additions of low-carbon energy deployment have been accompanied by rapid expansion in related manufacturing capacity. (See: Why did clean energy investments surge during and after Covid?)
This could create tension with traditional interests in the country’s coal industry, yet it also boosts the economic and political case for China to continue supporting low-carbon growth, both at home and abroad. (See: What comes next for China’s emissions peak and decline.)
Why emissions grew in Q3 of 2023
China’s CO2 emissions continued to rebound in the third quarter of 2023, increasing an estimated 4.7% year-on-year, but slowing to 1% in September.
This follows rapid growth in the first and second quarters of the year, after the same periods in 2022 had seen emissions decline by record amounts.
China’s quarterly CO2 emissions from energy use and cement production are shown in the figure below, with the third quarter of each year highlighted in red.
China’s quarterly CO2 emissions from fossil fuels and cement, million tonnes of CO2. Emissions are estimated from National Bureau of Statistics data on production of different fuels and cement, China Customs data on imports and exports and WIND Information data on changes in inventories, applying IPCC default emissions factors and annual emissions factors per tonne of cement production until 2019. Monthly values are scaled to annual data on fuel consumption in annual Statistical Communiques and National Bureau of Statistics annual Yearbooks. Chart by Carbon Brief.
The reasons for the emissions rebound this year are predictable. Most significantly and obviously, oil demand has risen from zero-Covid lows, following almost three years of pandemic controls.
Oil consumption is now approaching the pre-Covid trendline and does not yet show any sign of abating, increasing by an estimated 19% year-on-year in the third quarter. This is shown by the large light blue bar at the top of the figure below.
Electricity demand also rebounded from Covid lows in sectors that had been affected by pandemic controls, making power-sector coal use the second-largest driver of rising emissions in the third quarter of the year (the lowest grey bar).
The increase in power-sector demand happened almost entirely in July, before hydropower generation began to rebound from historic lows caused by low rains in 2022 and early 2023.
Annual change in quarterly CO2 emissions broken down by sector and fuel, millions of tonnes. Emissions are estimated from National Bureau of Statistics data on production of different fuels and cement, China Customs data on imports and exports and WIND Information data on changes in inventories, applying IPCC default emissions factors and annual emissions factors per tonne of cement production until 2019. Chart by Carbon Brief.
Coal use outside the power sector fell (grey chunks), due to a major drop in building materials driven by the ongoing contraction of real-estate construction and construction of associated infrastructure. This is also reflected in the drop for cement emissions (red).
Other uses of coal increased, particularly the use of coking coal (black chunks). The increase in coal use for steelmaking was larger than the increase in steel output, indicating a shift from electric arc to coal-based steel production.
Investment growth – for example, investment in electrical machinery manufacturing grew 38% year-on-year and investment in railways grew 22% – has supported demand for energy-intensive commodities, despite an ongoing contraction in real estate, generally the main user of metals.
Gas use continued to fall (dark blue), reflecting a drop in demand and a shift from gas to electricity and coal due to high prices.
Coal expansion threatens China’s international commitments for 2025
The pattern of economic growth in China, both during and after the Covid-19 pandemic, was highly energy- and carbon-intensive. This has put China off track against the CO2 and energy intensity targets – aimed at reducing CO2 and energy use per unit of GDP – that it promised in its updated climate pledge (nationally determined contribution, NDC) in 2021.
This would mark a departure from previous progress, with China having exceeded its energy and CO2 intensity targets during the 11th (2006-2010) and 12th (2011-2015) five-year plan periods, as shown in the figure below.
The slowdown in progress on energy intensity began already at the end of the 13th five-year plan period (2016-2020), resulting in that target being missed.
China’s progress on reducing energy and CO2 intensity of GDP compared to five-year plan targets, converted into required annual rates of progress. All previous targets since the 11th five-year plan (2006–11) have been met, but now progress has fallen short on both targets for three consecutive years. Source: Calculated from National Bureau of Statistics annual data on energy and GDP; 2022 calculated based on preliminary information released by the NBS. Figures for the latest five-year plan are shown as reported and as corrected for coal quality. Chart by Carbon Brief.
The coming surge of low-carbon energy would put the country on track for the CO2 intensity target, if similar levels are added next year.
The energy intensity target, in contrast, will not be met on current trends. Only a sharp shift to consumption-driven growth – which the government says it prefers, but has found the required measures hard to implement – could allow this target to be hit.
Permitting of new coal power plants continued, with at least another 25GW given the go-ahead in the third quarter, based on a compilation of permits reported by Polaris Network.
The resurgence of coal-plant construction contradicts a policy pledge that China’s president Xi Jinping personally announced. Xi pledged to “strictly control new coal-fired power generation projects” in China in 2021–25.
This pledge was made in the Leaders Summit on Climate in April 2021 and consequently added to China’s NDC, just months before the current wave in coal power plant permitting and construction began.
The State Council Development Research Center recently projected that China’s coal power capacity should peak at 1,370GW in 2030, up from 1,141GW at the end of June.
As 136GW was already under construction at the end of June, another 99GW had already been permitted, and a further 25GW has been permitted since, realising this projected peak would mean stopping new permits immediately.
Alternatively, retirements of existing capacity would have to be accelerated significantly, or some already permitted projects would have to be cancelled or shelved.
Solar, wind and hydropower set to surge in 2024
While emissions have climbed in 2023, it has also seen a historic expansion of low-carbon energy installations. The most striking growth has been in solar power, where expected installations in 2023 – some 210 gigawatts (GW) – are twice the total installed capacity of solar power in the US and four times what China added in 2020.
The newly installed solar, wind, hydro and nuclear capacity added in 2023 alone will generate an estimated 423 terawatt hours (TWh) per year, equal to the total electricity consumption of France.
About half of the solar panels added this year will be installed on rooftops, largely driven by China’s “whole county solar” model, where a single auction is carried out to cover a targeted share of the rooftops in a county with solar panels in one fell swoop.
Under this model, the developer negotiates with building owners and arranges contracts with the grid, financing, procurement, contracting and installations. This model – which could be described as centralised development of distributed solar – has enabled rooftop solar deployment at a vast scale.
The other half of solar installations are set to be in large utility-scale developments, particularly in the gigawatt-scale “clean energy bases” in western and northern China.
All in all, 210GW of solar, 70GW of wind, 7GW hydro and 3GW of nuclear are expected to be added in China this year. This is shown in the table below, along with expected electricity generation assuming newly added capacity performs in line with the existing fleet.
Expected capacity additions in 2023 and added annual generation
| Source | GW | Average utilisation | TWh |
|---|---|---|---|
| Solar | 210 | 13.6% | 251 |
| Wind | 65 | 23.0% | 130 |
| Nuclear | 3 | 83.4% | 21 |
| Hydro | 7 | 36.7% | 21 |
| Total | 284 | 17.0% | 423 |
In addition to the electricity generated by this newly added capacity, China is likely to see a large year-on-year increase in output from its massive hydropower fleet in 2024.
The utilisation of this fleet plumbed historical lows from August 2022 until July 2023, as a result of record droughts and heatwaves in summer 2022, followed by low rainfall into 2023.
The year-on-year drop in power generation was compounded as hydropower operators were conserving water in the spring and early summer of 2023, building up the water levels in their reservoirs for the peak demand season in August.
(This behaviour is clear in CREA analysis of hydropower generation data and water levels at 13 major hydropower reservoirs across China, reported by Wind Financial Terminal, showing water levels approaching historical highs while output remained low until July.)
This was in stark contrast with 2022, when spring and early summer had good rains and hydropower was generating at very high rates.
In addition to the electricity generated by this newly added capacity, China is likely to see a large year-on-year increase in output from its massive hydropower fleet in 2024.
The utilisation of this fleet plumbed historical lows from August 2022 until July 2023, as a result of record droughts and heatwaves in summer 2022, followed by low rainfall into 2023.
The year-on-year drop in power generation was compounded as hydropower operators were conserving water in the spring and early summer of 2023, building up the water levels in their reservoirs for the peak demand season in August.
(This behaviour is clear in CREA analysis of hydropower generation data and water levels at 13 major hydropower reservoirs across China, reported by Wind Financial Terminal, showing water levels approaching historical highs while output remained low until July.)
This was in stark contrast with 2022, when spring and early summer had good rains and hydropower was generating at very high rates.
In China’s rigidly regulated power system, hydropower operators do not have an economic incentive to time their output to the peak demand season. However, after the electricity shortages of summer 2022, administrative intervention appears to have replaced economic incentives and compelled generators to ensure high reservoir levels.
Now water levels in reservoirs have climbed up to or above their seasonal averages, based on data from Wind Financial Terminal. Long-term weather forecasts point to above-average rains lasting until February, the end of the forecast period, consistent with predictions for the current El Nino.
If these forecasts hold out, hydropower utilisation will not only recover but come in above historical averages in 2024. Meanwhile, another 29GW of hydropower has been added from the beginning of 2022 to September 2023, marking a 7% increase in capacity.
The hydropower generation rebound had already begun in August-September and will continue through this year. However, electricity demand growth at the end of last year was very weak due to strict Covid lockdowns, so emissions are unlikely to fall year-on-year.
Total CO2 emissions fell 4% from the last quarter of 2020 to the last quarter of 2022, setting up a very low base of comparison for the last quarter of this year.
Continued clean-power growth can peak emissions in 2024
Given the low-carbon electricity capacity already installed this year – and the outlook for hydropower generation – a drop in power-sector emissions in 2024 is essentially locked in, barring a major acceleration in electricity demand growth.
From 2025 onwards, the development of power-sector emissions depends on whether low-carbon energy additions are maintained or accelerated.
Looking at the added annual generation from low-carbon energy installations in 2023, the total comes out to more than the average annual increase in China’s power demand, for the first time, marking a potential inflection point.
At this point, the growth of low-carbon electricity (columns in the chart below) would outweigh the overall growth of electricity demand (dots). As a result, the amount of electricity generated using fossil fuels – and the associated emissions – would decline.
Columns: Annual increase in expected electricity generation from new low-carbon installations, terawatt hours, broken down by source. Dots: Annual increase in electricity demand overall. Dashed line: Average increase in demand during 2010-2023. Figures for 2023 are forecast. Data sources: China Electricity Council (CEC) and Ember, with 2023 capacity additions from CEC and Bloomberg. Chart by Carbon Brief.
As long as low-carbon energy installations are maintained at the projected 2023 level, the growth in low-carbon power generation would enable China to peak and decline coal use in the power sector imminently, with 2023 remaining the peak year.
How will power-sector emissions develop if the 2023 level of low-carbon energy additions is maintained?
A simple projection – assuming that electricity demand follows its historical trend of rising 5% per year and hydropower utilisation returns to historical averages – points to a significant drop in fossil fuel-based (thermal) power generation in the spring and summer of 2024, shown by the bottom left segment in the chart below, and zero growth thereafter.
If China’s current and expected economic slowdown results in slower electricity demand growth – or non-fossil energy additions accelerate further – power generation from fossil fuels will continue to fall, rather than stabilise.
Under these assumptions, hydropower generation would see steep increases already in October 2023 – January 2024, but power generation from fossil fuels still climbs year-on-year, due to the low base set under the zero-Covid policy.
A return to average demand growth rates after the post-Covid rebound, (top left), continued strong growth in solar (centre right) and wind (centre left) output, combined with rebounding hydropower output (bottom right), would push fossil-fuel power generation down from February 2024 onwards (bottom left). This would mean fossil fuel-fired electricity generation falling 3% in 2024 and remaining at similarly reduced levels in 2025.
Past and projected future year-on-year changes in monthly electricity generation, %. Top left to bottom right: Overall electricity demand; nuclear; wind; solar; thermal (coal and gas); and hydro generation. Data sources: China Electricity Council (CEC) and Ember, with 2023 capacity additions from CEC and Bloomberg. Chart by Carbon Brief.
Moreover, rapid electrification has meant that almost all of the recent growth in China’s CO2 emissions has taken place in the power sector.
Therefore, when power-sector emissions peak, total emissions are likely to follow, as falling coal use outside the power sector balances out increases in oil and possibly gas demand, which are also mitigated by electrification.
Why did clean energy investments surge during and after Covid?
China’s output of solar cells is set to exceed 600GW this year, up from 375GW last year and enough to produce 500GW of solar panels. For comparison, only 240GW of panels were installed globally last year.
The output of batteries in China will reach 800 gigawatt hours (GWh), up from 550GWh last year and enough to power 20m electric vehicles (EVs).
Electric vehicle output exceeded 8m units over the 12 months to September, representing more than 30% of all vehicles produced in China. The share of EVs in all vehicles sold in China is also on track to reach 30% in 2023, while production for the calendar year is set to reach 9m vehicles.
This is only the beginning of the industry’s expansion plans. By 2025, solar-panel production capacity is expected to break 1,000GW (1 terawatt, TW), and battery production capacity to reach 3,000GWh.
What is causing this surge?
The announcement of the 2060 carbon neutrality target provided the political signal, but wider macroeconomic conditions have delivered low-carbon capacity growth far in excess of policymakers’ targets and expectations, with this year’s solar and wind installation target met by September and the market share of EVs already well ahead of the 20% target for 2025.
The clampdown on the highly leveraged real-estate sector, starting in 2020, led to a steep drop in the demand for land, commodities, labour and credit for apartments and associated infrastructure. This left a hole in the finances of local governments – which rely on land sales for a lot of their revenue – and hit economic growth rates.
Local governments were, thus, searching for alternative investment opportunities to drive economic growth. Yet, at the same time, their investment spending was under scrutiny due to debt concerns. China’s high-level environmental and industrial policy goals made cleantech one of the acceptable sectors for their investment.
At the same time, the government made it easier for private-sector companies to raise money on the financial markets and from banks, as part of measures to stimulate the economy during the pandemic.
The low-carbon energy sector, in contrast with the fossil fuel and traditional heavy industries, is largely made up of private companies. Access to credit had earlier been a major bottleneck for them in a financial system that has heavily favoured state-owned firms.
As a result, much of the bank lending and investment that previously went into real estate is now flowing to manufacturing – largely cleantech manufacturing – as well as to cleantech deployment.
Local government enthusiasm for attracting investments to their regions meant that they often also offered major direct or indirect subsidies. Reportedly, it is common for local governments to build an entire factory and associated infrastructure, with the private company going on to occupy the site only covering the cost of machinery and operations.
All of this happened at a time when falling costs driven by technological learning and subsidies resulted in many low-carbon energy technologies becoming economically competitive against fossil fuels.
China’s policymakers had favoured “green” investments previously, as in the 2009 stimulus package launched in response to the global financial crisis. Yet the sector had been too small to absorb the huge amount of credit mobilised as a part of China’s stimulus cycles. After experiencing extremely rapid growth since 2020, this has changed.
The construction of low-carbon energy manufacturing capacity, production of low-carbon energy equipment and construction of railways have been significant drivers of commodity demand this year, as the only areas of investment showing substantial growth.
This demand explains, among other things, why China’s steel output has continued to grow despite the ongoing contraction in real-estate construction.
Conversely, the precipitous drop in demand for commodities from the real estate and conventional infrastructure sectors explains why the breakneck expansion of low-carbon energy sectors – and their commodity demand – has not resulted in a spike in prices.
The unprecedented investment in low-carbon technology manufacturing supply chains also means that China has, in effect, placed a major economic and financial bet on the success of the global energy transition, which could affect its diplomatic positioning.
What comes next for China’s emissions peak and decline
Now that low-carbon energy expansion has reached the scale needed to start driving down China’s emissions, the most important question is: will its growth continue?
China’s low-carbon energy boom resulted from the confluence of numerous factors. There was – and is – clear political commitment and direction. The contraction of the real-estate market provided a push and an opportunity for the redirection of capital and investments into the renewable energy sector.
Technological learning and aggressive industrial policy improved quality and cut costs to the point where the market for low-carbon energy technologies started to expand rapidly.
It is also clear that the wave of manufacturing investment has resulted in significant overcapacity in the production of solar panels, batteries and EVs, among others, though the scale of this excess depends on the pace of the global energy transition.
This overcapacity is likely to be resolved – as in previous rounds of expansion – through consolidations and outright failures of individual players. Meanwhile, however, it will continue to depress the prices of low-carbon energy equipment.
Politically, the major challenge will only come when low-carbon energy begins to substantially cut into the demand for coal and coal-fired power.
This shift threatens the interests of the coal industry and local governments with a high exposure to the coal sector. These stakeholders could be expected to resist the transition, raising concerns about potential roadblocks.
When contraction in demand and capacity additions resulted in overcapacity in coal-fired power around 2015, coal power interests successfully argued that low-carbon energy deployment had been too fast.
As a result, the rate of low-carbon energy capacity additions slid down from 2015 until 2019, as seen in the figure above, making more space for excess coal capacity to generate power.
A similar balancing act could come into play once again, as coal and low-carbon generating capacity both continue to expand, competing to meet limited rises in demand.
The Chinese government and its advisers have argued that new coal power plants will not result in a surge in emissions, as they will be used for flexible operation at low utilisation.
China’s climate targets do not yet reflect this belief, however. Its combination of intensity and low-carbon deployment targets would allow emissions to increase by another 10-15% from 2022 levels and only peak at the end of this decade.
If the government wanted to more firmly cement the low utilisation of newly built coal plants, it could do so by moving towards an absolute cap on power-sector emissions under its emissions trading system – or by setting a limit on China’s total CO2 emissions.
As the government weighs these decisions, it is faced with a dramatically larger set of economic drivers and interests in the low-carbon energy sector, as compared with 2015.
These conditions could offer the motivation for policymakers to push a faster domestic transition away from fossil fuels. They also mean that China has an increasingly significant financial stake in the success of the low-carbon transition worldwide.
Data sources
Data for the analysis was compiled from the National Bureau of Statistics of China, National Energy Administration of China, China Electricity Council and China Customs official data releases, and from WIND Information, an industry data provider.
Power sector coal consumption was projected based on power generation, to avoid the issue with official coal consumption numbers affecting 2022–23 data. September 2023 data on apparent coal consumption was not available at the time of publication, so coal consumption in different sectors was projected based on the output of relevant industrial products – for example, coke for the consumption of coking coal; cement and glass for building materials industry. Coal consumption for heating was projected based on population-weighted average heating degree days calculated from NCEP gridded daily weather data.
When data was available from multiple sources, different sources were cross-referenced and official sources used when possible, adjusting total consumption to match the consumption growth and changes in the energy mix reported by the National Bureau of Statistics.
CO2 emissions estimates are based on National Bureau of Statistics default calorific values of fuels and IPCC default emissions factors. Cement CO2 emissions factor is based on 2018 data.
For oil consumption, apparent consumption is calculated from refinery throughput, with net exports of oil products subtracted.


The post Analysis: China’s emissions set to fall in 2024 after record growth in clean energy appeared first on Carbon Brief.
Analysis: China’s emissions set to fall in 2024 after record growth in clean energy

Climate Change
Kevin Parker, Hugh Jackman, Tina Arena and over 150 Australian artists sign open letter to save Scott Reef from Woodside gas plans
SYDNEY, Monday 16 November 2026 — More than 150 Australian entertainers and creatives have signed an open letter calling on Federal Environment Minister Murray Watt to reject oil and gas drilling plans at Scott Reef, Australia’s largest oceanic reef system.
- Artists have supplied images for use here
- High res images and footage of Scott Reef can be found here
The open letter to Minister Watt concerns risks to Scott Reef, 270 kilometres from the Kimberley coast of Western Australia, posed by multinational Woodside which plans to drill up to 57 wells for its Browse gas project. The project is forecast to emit 1.6 billion tonnes of climate pollution and risk a catastrophic oil spill in endangered whale migratory pathways.
Australian signatories calling on the government to save Scott Reef include 2026 ARIA nominees Kevin Parker (Tame Impala), Tkay Maidza and G Flip, Hollywood actors Hugh Jackman and Simon Baker, and prolific musicians Tina Arena, Paul Kelly and “Down Under” legends Men at Work.
About the open letter, Australian musician Jessica Mauboy said: “Caring for Country means caring for our oceans and all the life they hold. Places like Scott Reef are precious, and we have a responsibility to protect them for future generations. I’m adding my voice to the call to protect Scott Reef and keep it safe from gas drilling.”
Australian singer-songwriter and ARIA award winner Missy Higgins signed the open letter and said: “Scott Reef is an ancient coral reef off WA’s Kimberley coast, home to endangered whales, vulnerable turtles and hundreds of other marine species. Woodside’s plans to drill up to 57 wells under and around it put this extraordinary place at risk. We need to preserve these beautiful places for our kids. If not now, then when?”
Australian singer-songwriter Sarah Blasko said: “Scott Reef off Western Australia’s Kimberley Coast is not the place for a massive new gas project by Woodside. It’s our responsibility to protect our beautiful reefs and rare marine life. They are, after all, what this country is best known for around the world. If we don’t protect them, what does it say about us to our children and the world?”
Scott Reef supports thousands of species including vulnerable turtles and endangered whales that are particularly threatened by Woodside’s proposal. Greenpeace has nominated Scott Reef for National Heritage listing for its ecological and scientific importance, and the WA Environment Protection Authority (WA EPA) has warned Woodside’s plans could cause “serious, significant and irreversible” harms to the 15-million-year-old ecosystem.
Senior Campaigner at Greenpeace Australia Pacific, Hannah Schuch, said: “I am heartened to see so many Australian artists amplifying the call for a better future, one where places like Scott Reef are rightfully protected from greedy corporate interests.
“Scott Reef is an iconic, irreplaceable piece of Australian nature, and Woodside’s plans to drill 57 toxic wells and turn Scott Reef into an industrialised gas zone risk threatened species and this unique, ancient ecosystem.
“Murray Watt and the Albanese Government have an opportunity to make history and write their legacy: save Scott Reef and stop Woodside’s reckless gas plans. Australia is watching.”
-ENDS-
Media contact
Emma Sangalli on 0431 513 465 or emma.sangalli@greenpeace.org
Efe Baysal leads the Türkiye team of global climate advocacy group 350.org.
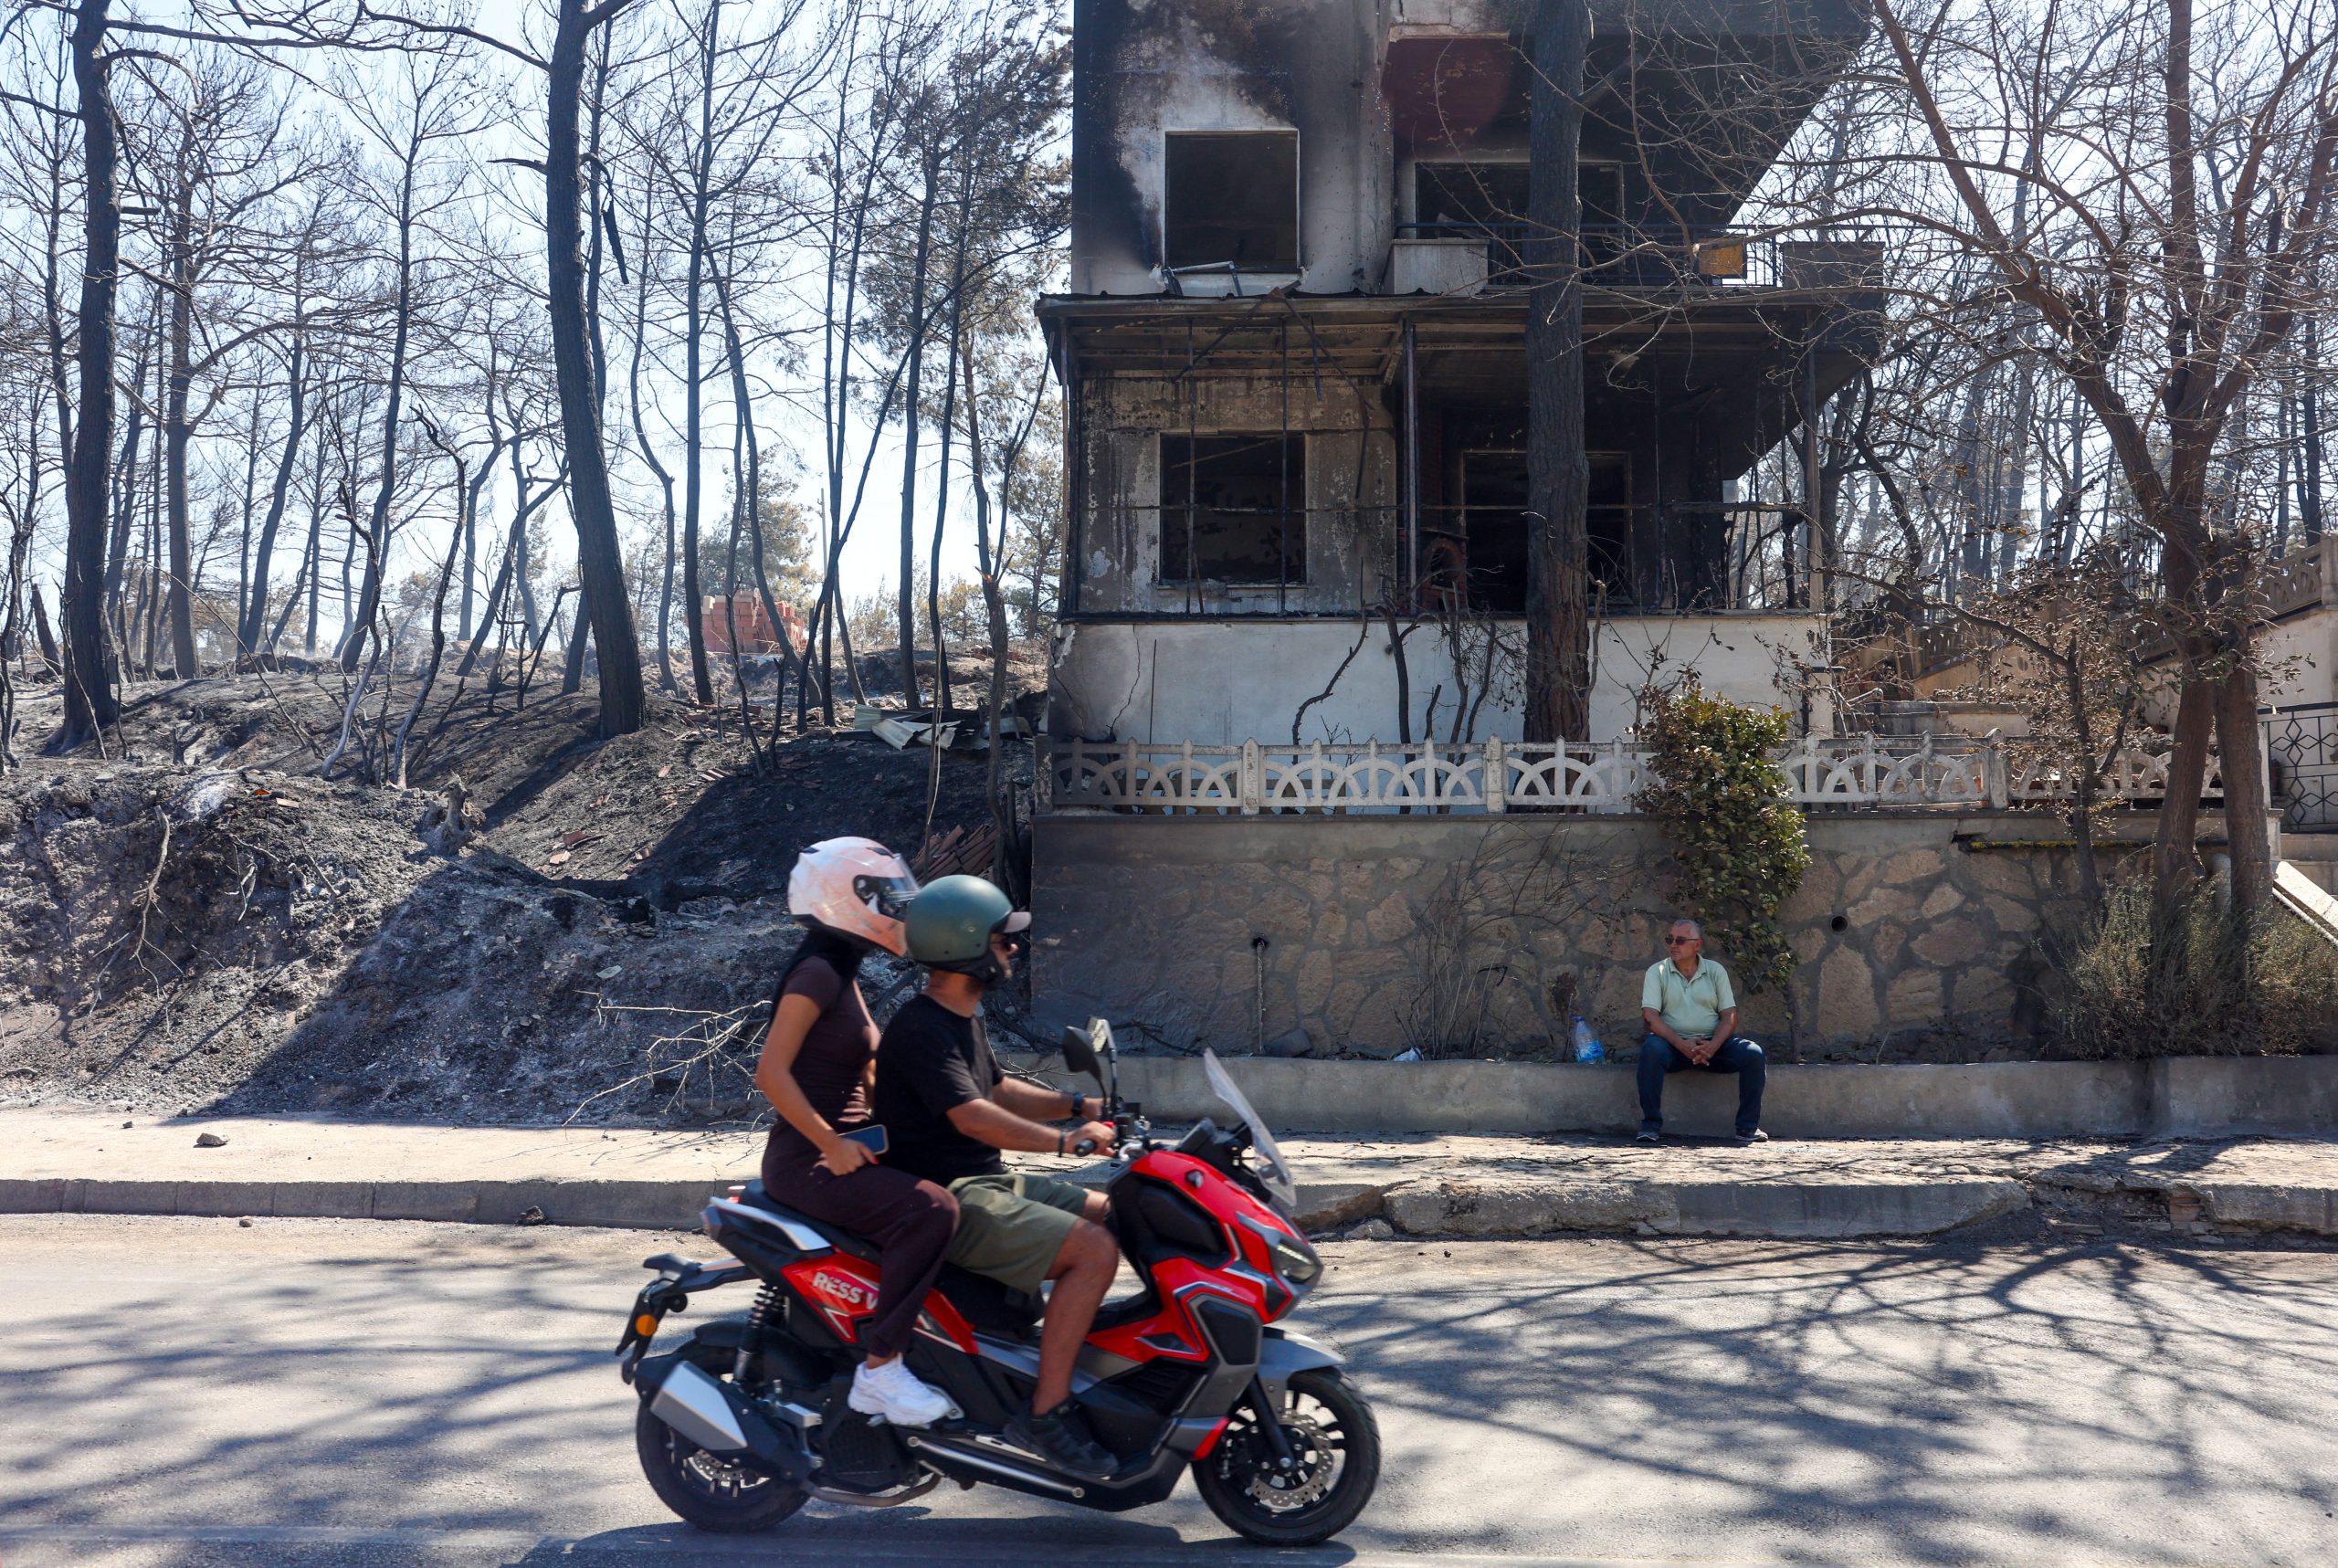
As Türkiye welcomed world leaders in Antalya during the first week of the UN climate summit, few were probably aware that wildfires raged just a few kilometres from the COP31 venue in September, injuring several people and forcing hundreds to flee their homes.
Wildfires are one of the signs of a rapidly heating planet. Prolonged heatwaves and drought create ideal conditions for fires to start and to spread. In the coastal province of Antalya, 8,000 hectares have already been lost to forest fires this year alone.
It is a crucial moment for climate diplomacy. This year we have seen the human cost and mounting economic damage of climate impacts, from Europe’s heatwaves to Nepal’s deadly glacial floods. Scientists warn that the world will breach the 1.5C temperature limit within a few years.
-
Turkish giant sponsoring COP31 cut climate goals then cashed in on oil boom
COP31 sponsors should be screened for “climate integrity”. Yet Koç Holding has become a top partner while its oil refiner runs flat out and its climate targets slip -
Africa wants adaptation finance on COP31 agenda, raising risk of a fight
The African Group wants dedicated space on tripling adaptation finance, the Green Climate Fund and trade, setting up a possible clash -
European nations signal support for fossil fuel roadmap, says COP30 president
André Corrêa do Lago told Climate Home News that it’s up to other nations to decide how the fossil fuel and deforestation roadmaps are used


The stakes have never been higher as the Turkish government takes its turn hosting the Conference of the Parties (COP) to the UN climate convention. Türkiye has a lot riding on the summit, and not only its ability to stage one. Many in the country hope COP31 will put a spotlight on its own climate and environmental crisis.
Extreme weather in Türkiye is becoming far more frequent. In 2011, the country recorded more than 300 extreme weather events. By 2023, according to the Turkish State Meteorological Service, the figure had reached almost 1,500.
Dried-up lakes and sinkholes
For a semi-arid country, drought is a particular threat. Half of Türkiye’s population is at risk of water shortages by 2030, and last year brought the lowest rainfall in 61 years.
Perhaps the starkest sign of this is the alarming rate at which Türkiye’s lakes are vanishing. Three-quarters of its lakes have dried up in the past 50 years, many of them just in the last decade, marking the loss of ecological systems that have sustained generations of farmers and fishermen.
An example is Lake Iznik, the country’s fifth-largest natural lake and the site of the Byzantine Basilica of Saint Neophytos, a fifth-century site whose ruins were first discovered underwater. When Pope Leo visited last year, they stood exposed on dry land as the shoreline had dramatically retreated.
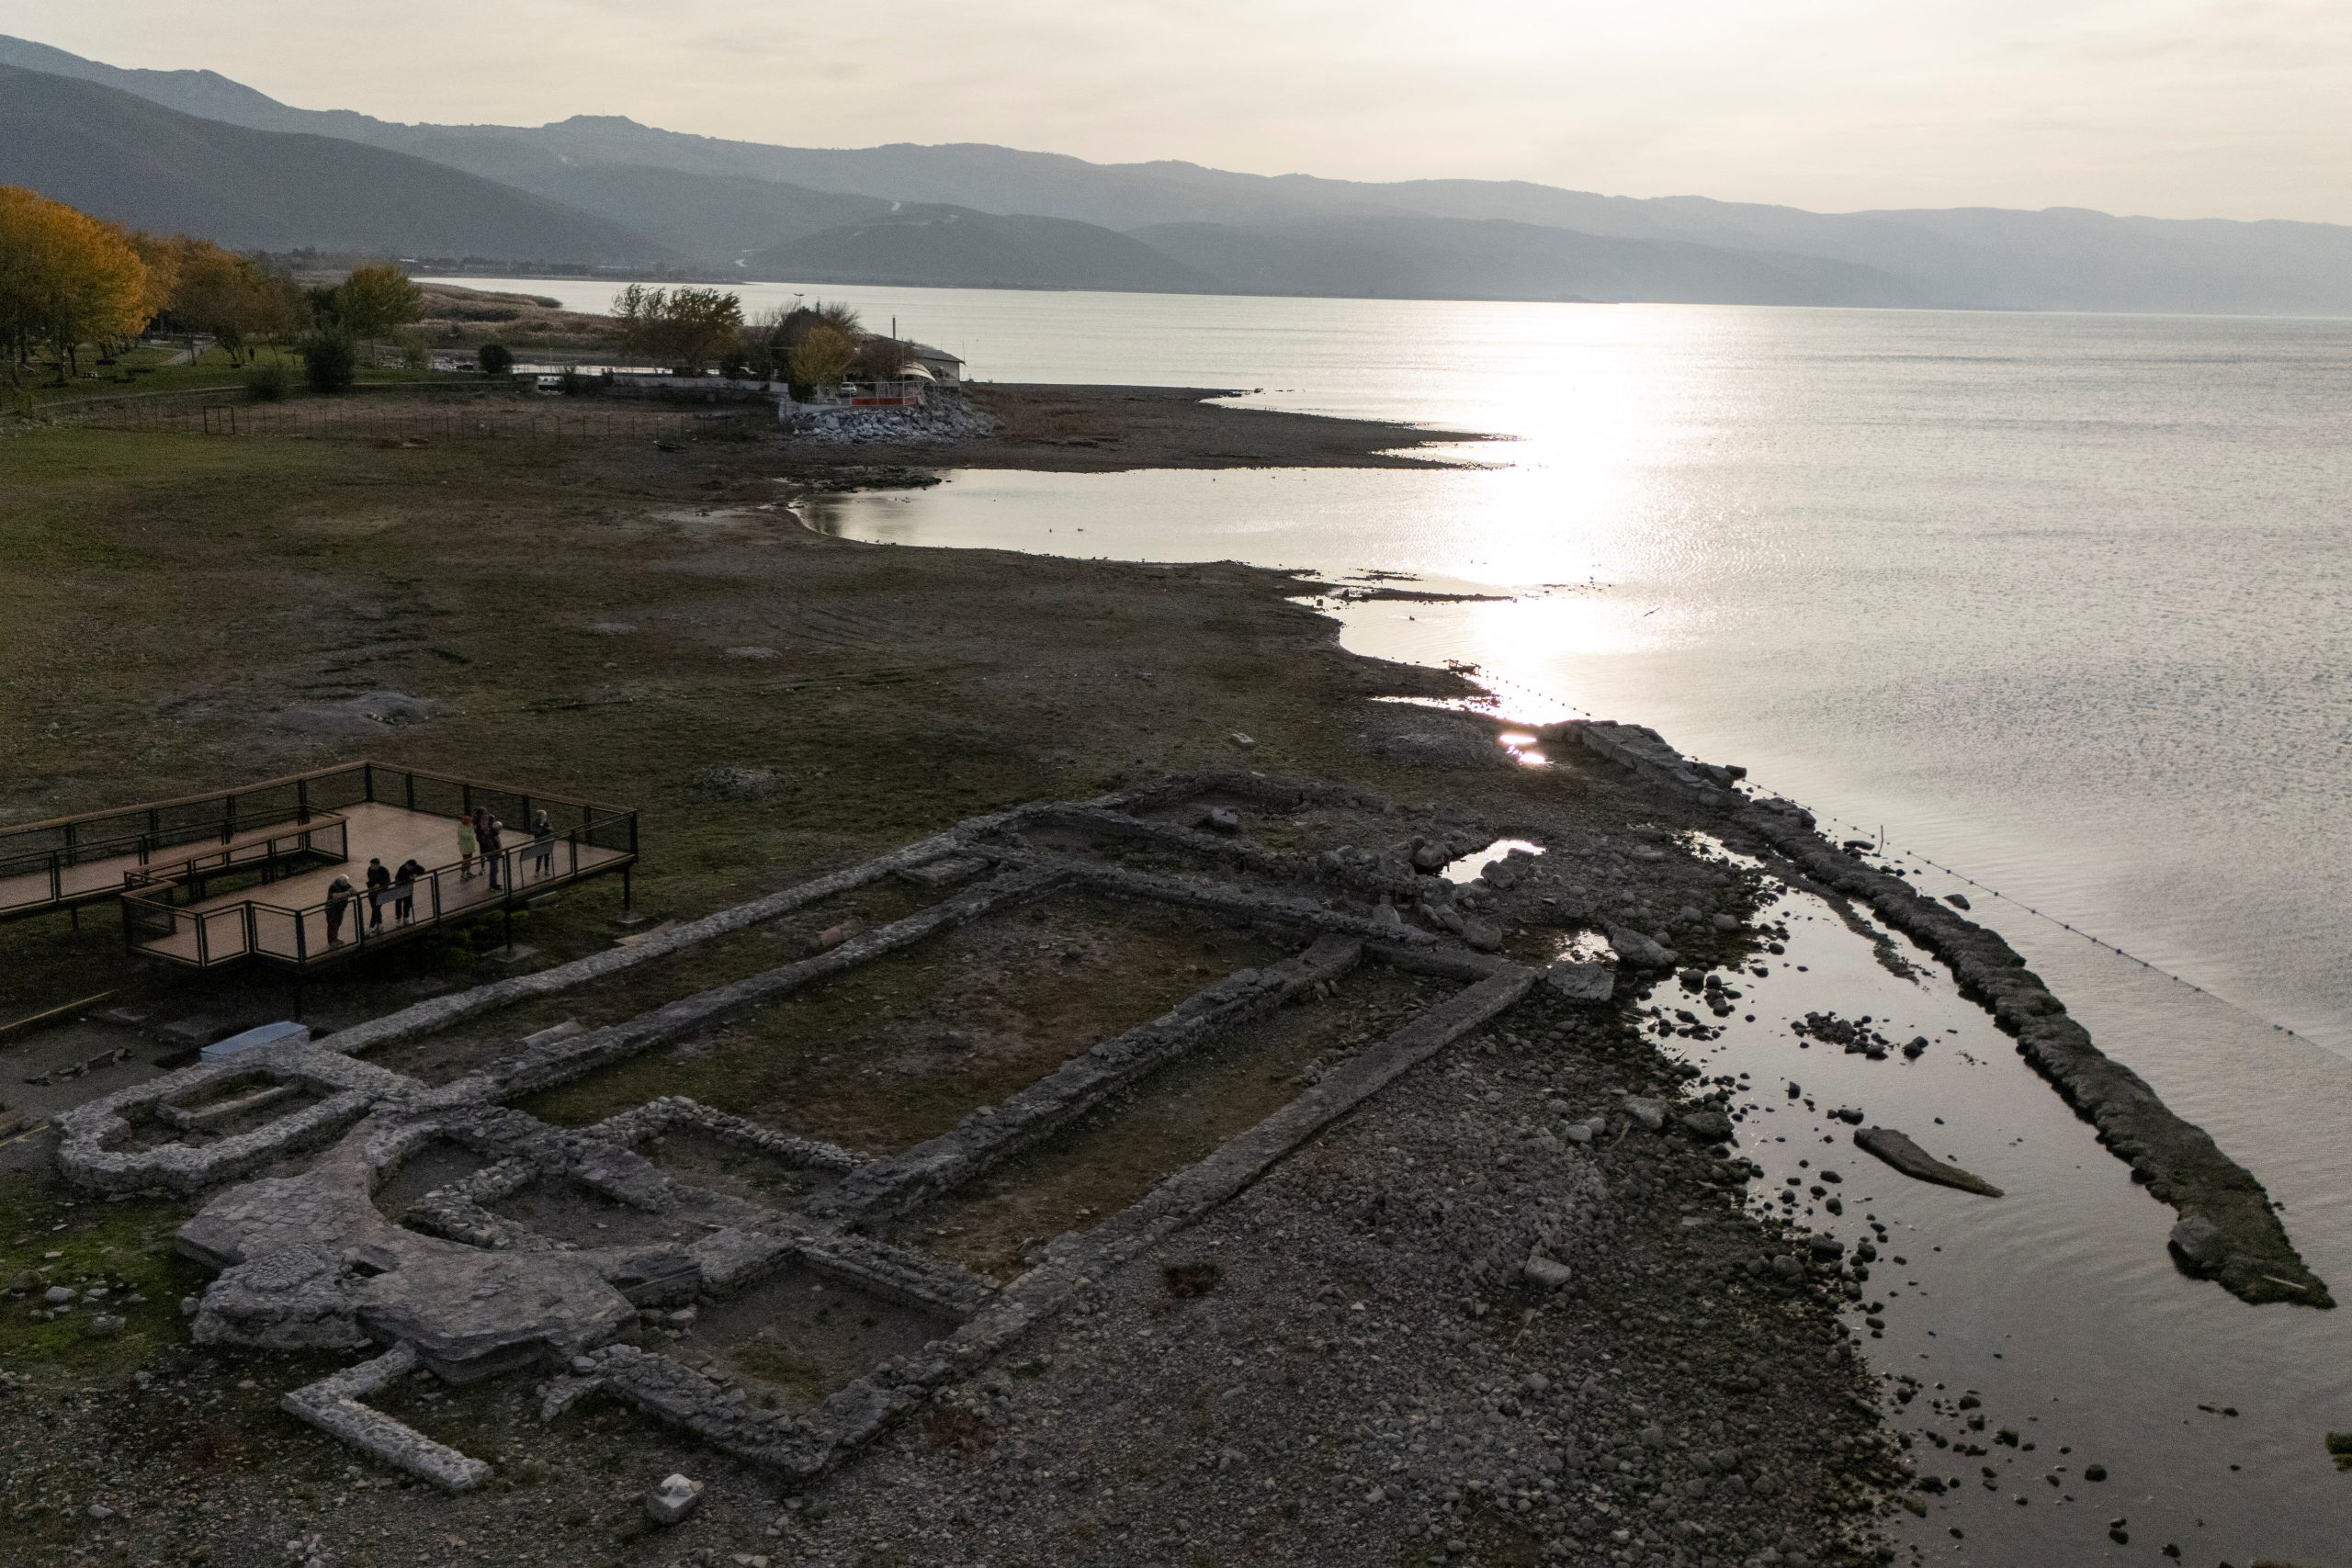
Locals fear that due to drought, as well as the pumping of large volumes of water by big agricultural companies, Lake Iznik will disappear. As Iznik recedes, the coastal water wells that irrigate olive groves have run dry.
“Everyone stands over their phones waiting for weather forecasts, wondering, ‘Will it rain today?’,” one 65-year-old olive farmer told me. “It used to snow waist-deep, and roads would remain closed for weeks. Today, children have forgotten what snow is.”
Agricultural stress isn’t limited to Iznik. In 2025, Türkiye’s crop and field production fell by 9%, while fruits, beverage and spice plants lost nearly a third of their output. According to the agriculture ministry, drought and frost were the main causes.
Visible scars of climate crisis
Sinkholes are also rapidly increasing, now numbering more than 1,000. Most of them are located in the Konya Basin, where groundwater levels fall by about 2 metres a year due to reduced rainfall and excessive extraction.
Türkiye’s sinkholes aren’t just a hazard to human life and infrastructure. They’re a graphic representation of how two human-made phenomena – groundwater exploitation and the climate crisis – combine to weaken the land, causing it to collapse upon itself.
Burnt forests, disappearing lakes, gaping sinkholes: many of these reminders of the climate crisis will remain hidden from visitors in Antalya this month. But the clamour for action will be on full display.
Since last year’s climate summit, a growing number of countries have rallied around a way forward: roadmaps to transition away from fossil fuels. More than just emission-reduction targets, these transition roadmaps are concrete plans on how to end dependence on fossil fuels, the main driver of climate change, in a just and orderly way.
As the Hormuz crisis has shown, not having to rely on oil and gas is no longer just about saving future generations from climate catastrophe – it’s also about saving next month’s household budget.
Electrification milestone
Türkiye is highly dependent on imported fossil fuels, spending an average of $42 billion annually on oil, gas, and coal over the last 10 years. The Hormuz crisis has increased these costs, with Turkish households and businesses losing an additional $3 billion in just two months’ worth of fossil fuel price spikes.
In launching the “35 by 35” electrification target, Türkiye’s COP President Murat Kurum acknowledged the need to protect citizens from high energy prices. This new global target for electricity to meet 35% of final energy demand by 2035 is shaping up to be one of the milestones of this year’s climate talks.
It’s a good target because electrifying transport, buildings and industry significantly cuts not just pollution, but daily expenses too. But electrification alone is not enough. Without an accompanying fossil fuel phase-out, electrification won’t be able to stop further climate and economic catastrophe.
Comment: Turkey must make COP31 a turning point for global climate action
A case in point is Türkiye’s new National Energy Plan 2040. The plan’s emphasis on electrification and the expansion of renewable energy capacity is welcome – these are positive steps that align with the messages coming from Türkiye’s COP31 presidency. However, for the plan to represent genuinely ambitious climate action, it must include a clear commitment and timeline to phase out coal.
Türkiye still relies on mostly imported coal for around one-third of its energy. A 350.org report has revealed that the coal trade between Türkiye and Australia – with which it shares the COP31 presidency – has been responsible for roughly 75 million tonnes of carbon emissions since the Paris Agreement was signed. Neither country has a coal phase-out date.
COP31 is an opportunity to change course. The Turkish government has made good progress on expanding solar and wind energy. In 2025, Türkiye surpassed its solar target as capacity had more than doubled in recent years. It must now build on this progress.
The world will be watching Türkiye as the climate summit heads into its second week. The Turkish government must ensure that global leaders implement real solutions that won’t leave its own citizens high and dry.
The post Behind the COP31 fanfare, Türkiye is worried about water appeared first on Climate Home News.
Scientists behind a landmark UN report on overshooting the 1.5C warming limit have defended its credibility, after Saudi Arabia and other large developing countries questioned its scientific legitimacy and sought to keep it out of the main political decision expected from COP31.
The UN Environment Programme’s (UNEP) Limiting Overshoot report, published in September, examines how to minimise an almost certain breach of the Paris Agreement’s temperature goal, what crossing it will mean for people and ecosystems and how temperatures could be brought back down.
The European Union, the UK, the Least Developed Countries (LDCs) and small island states are among those pushing for COP31 to make the response to overshoot of 1.5C one of the summit’s priorities.
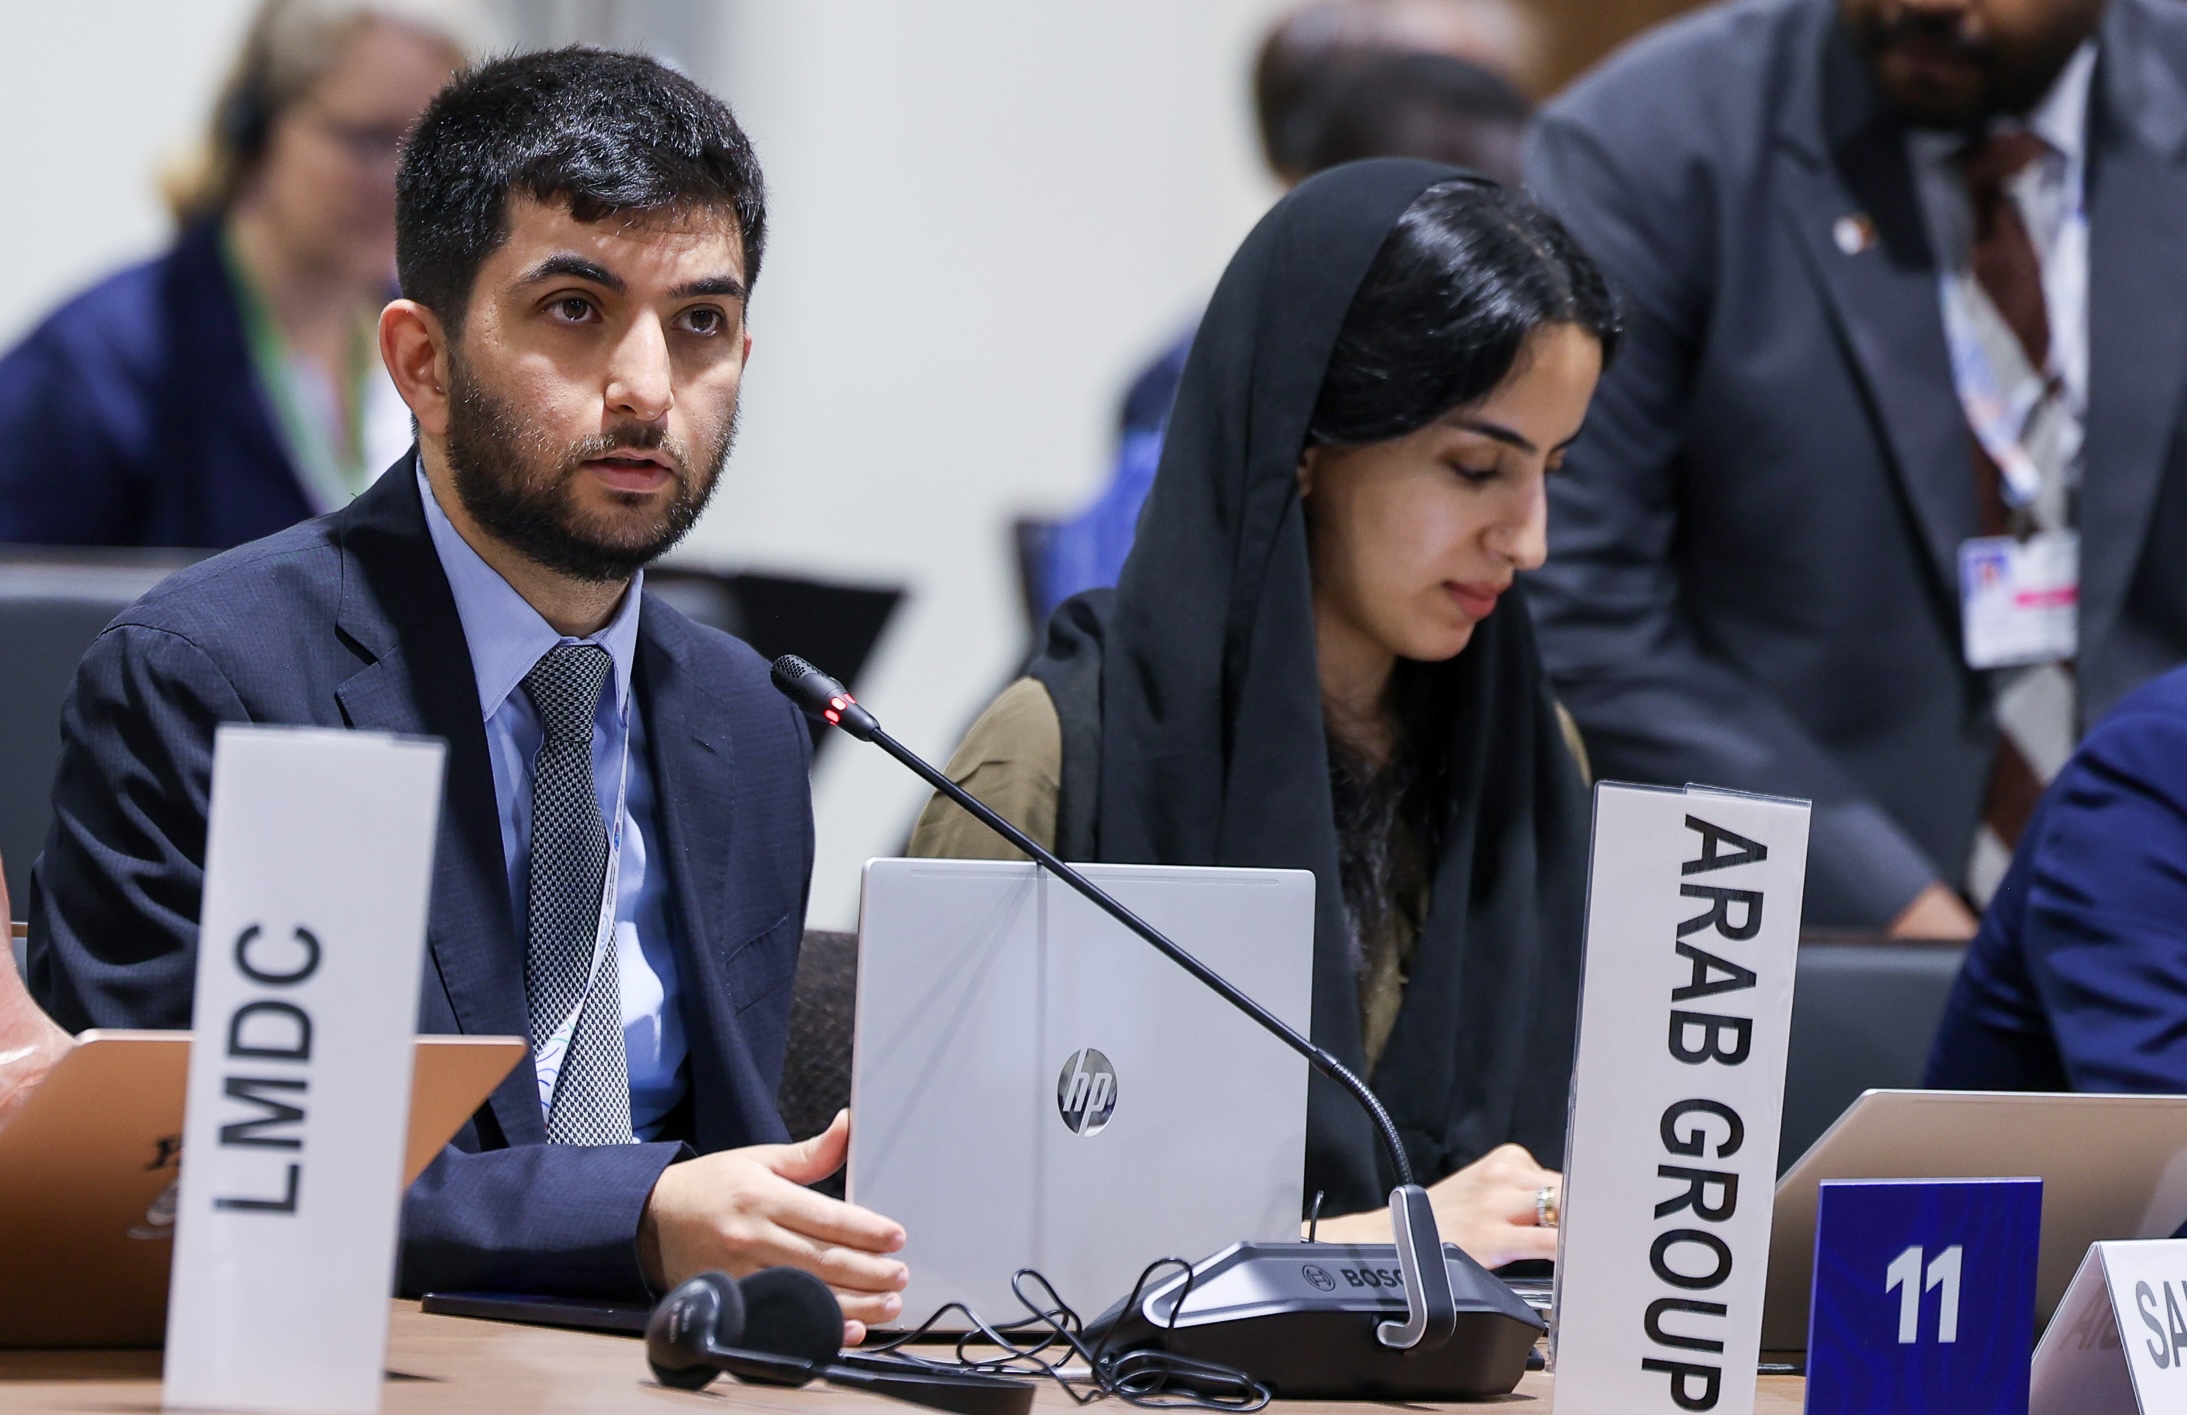
But during closed-door consultations on the cover decision this week, the Arab Group, led by Saudi Arabia, have tried to cast doubt on the report’s scientific rigour, arguing it had not been peer-reviewed, according to sources familiar with the discussions.
Meanwhile, the bloc of Like-Minded Developing Countries (LDMCs), which included India and China, called for the cover decision to avoid references to reports produced outside the UN climate process, seen by observers as a thinly-veiled reference to the UNEP report.
Laurence Tubiana, CEO of the European Climate Foundation and one of the key architects of the Paris Agreement, said the overshoot report “tells us a truth some would rather hide”.
“We are on course to exceed 1.5C and limiting how far and for how long is a matter of survival for us all,” she told Climate Home News. “The attacks on climate science are an attempt to delay action. They target intergovernmental institutions that give countries a shared scientific basis for acting together.”
-
Science ‘under attack’ from fossil fuel interests at UN climate talks
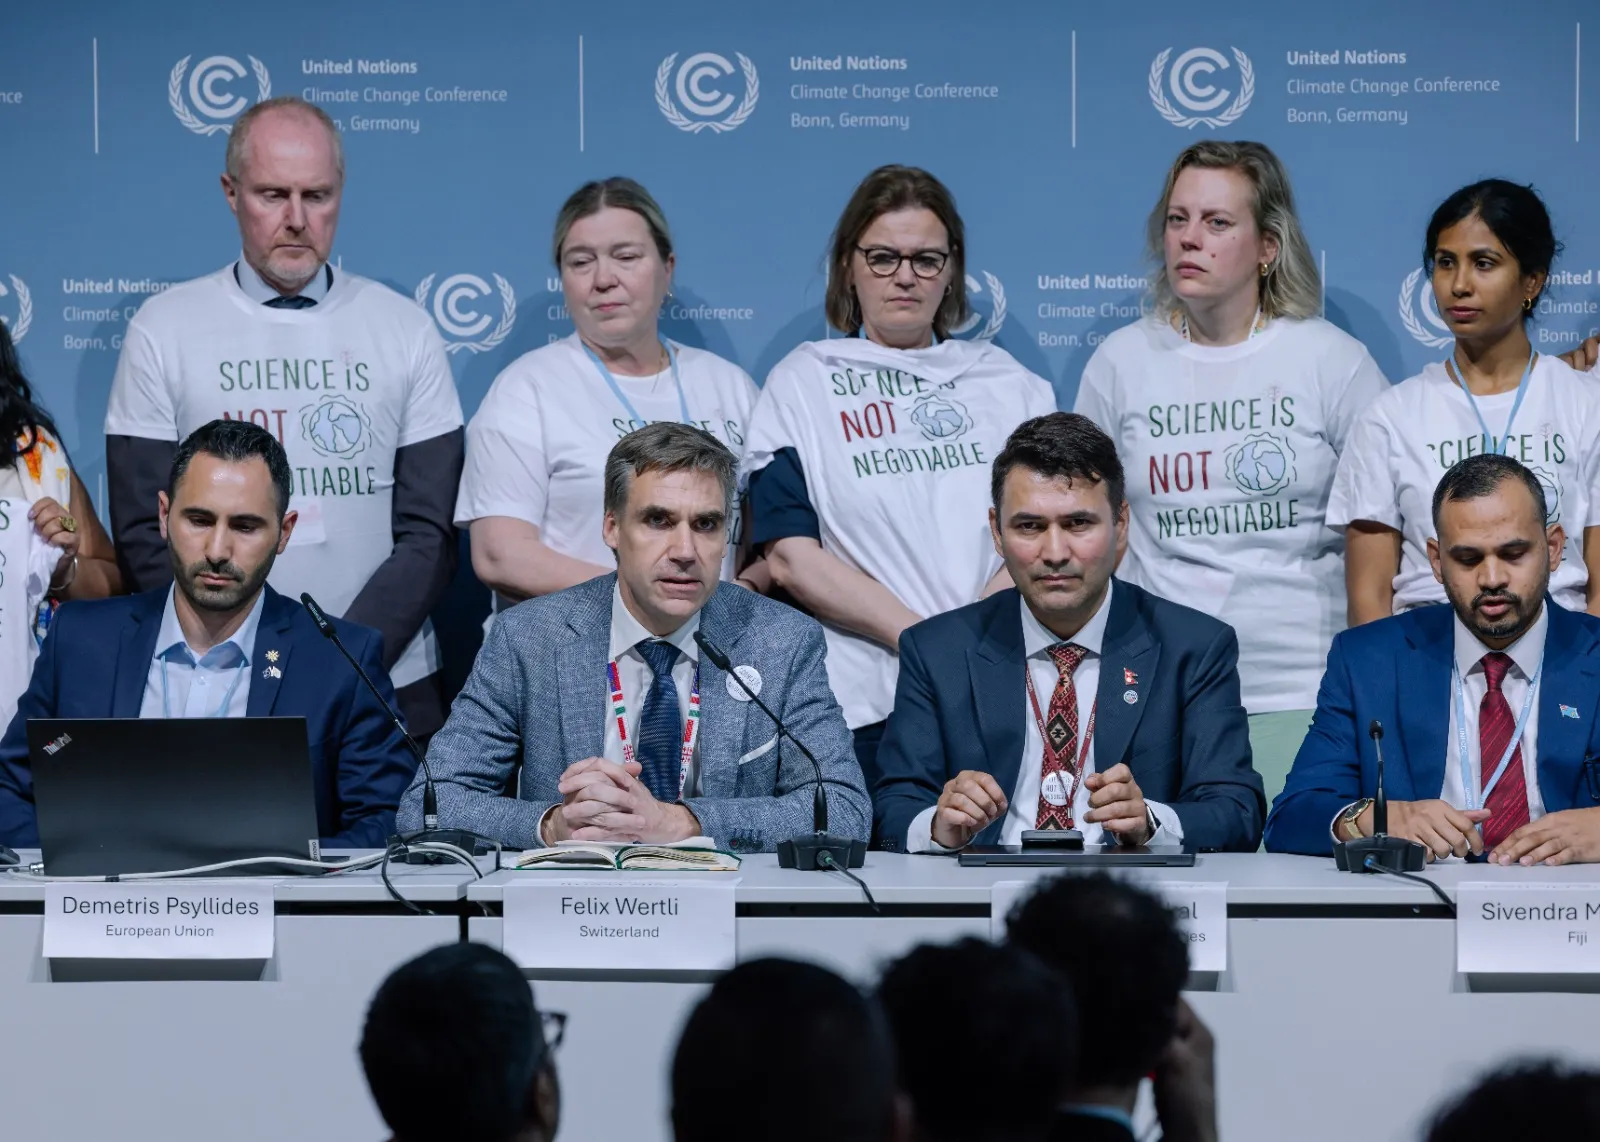
A coalition of some rich nations and the world’s most vulnerable have vowed to protect climate science in UN negotiations -
Framing the climate science debate as a binary battle isn’t just wrong – it’s dangerous
Achieving the Paris Agreement goals requires robust science that fully integrates the experiences, economic realities and academic contributions of the Global South

Rigorous approach
Speaking at an event in Antalya on Saturday, scientists involved in the report also pushed back.
Debra Roberts, a South African scientist who co-chaired the IPCC’s Working Group II in its last assessment cycle and was part of the UNEP report’s core coordinating team, said the authors had followed the standard process for a global assessment of existing science, in line with the practices of the Intergovernmental Panel on Climate Change (IPCC). The only difference, she said, was that governments did not review the outputs.
“It was certainly reviewed internally by the authors, external peer-reviewers were brought into the process, and UNEP also reviewed it,” she told Climate Home News.
Forty-four experts from across the globe authored the report, which largely synthesises existing literature, and their work was scrutinised by a further 44 reviewers in a year-long exercise.
“Let’s be straightforward here: the reports are being attacked because some people don’t like the conclusions and it’s fairly obvious why,” Bill Hare, CEO of Climate Analytics and one of the report’s reviewers, told Climate Home News.
“If you as a government are basing your economy on burning and selling fossil fuels, then the last thing you want to do is accept that we are overshooting 1.5C, because then obviously you will take on some responsibility for paying for the damage,” he added.
“Grey literature” debate
In Antalya, some big emerging economies have also called for “grey literature”, including the overshoot report, to be kept out of the cover decision. The term refers to scientific products that are published outside of traditional academic journals.
While that applies to the UNEP report, some of its authors said it should not mean “grey literature” is of lower quality and cannot be used to inform policy-making.
They added that other forms of “grey literature”, including the UNEP Emissions and Adaptation Gap reports or the work of the International Energy Agency (IEA), are routinely used in the IPCC climate science assessment cycles and sometimes referenced in COP decisions.
Manjeet Dhakal, a Nepalese advisor to the LDCs, told Climate Home News those reports have previously been very useful to inform policy-makers. He added that the overshoot report is comprehensive and countries should be guided by it in Antalya.
‘A distraction’ amid bigger science spat
One of the UNEP report authors said the attempts by some countries to cast doubt on the overshoot report is just “a distraction”.
Clashes over climate science and its role in policy-making have escalated over the last few years amid a long-running stand-off at the IPCC. Most governments want the panel to produce all of its key assessment reports in time to inform the next UN Global Stocktake of climate action, due to be completed in November 2028.
But a smaller group of countries, led by Saudi Arabia, India and Russia, have resisted, claiming that timeline would be too rushed for scientists and governments from developing countries to contribute to and review the reports.
The IPCC will reconvene in an online meeting in early December in a last-ditch effort to find a solution.
As well as the IPCC assessments, Tubiana said the findings of the overshoot report must also inform the next global stocktake.
The post Scientists defend UN overshoot report after Saudi-led push to sideline it at COP31 appeared first on Climate Home News.
Scientists defend UN overshoot report after Saudi-led push to sideline it at COP31



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19
-

 Climate Change1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Green Living2 years ago
Our Picks for the Top 2024 Black Friday and Cyber Week Sales From Sustainable Brands
-
Renewable Energy1 year ago
US Grid Strain, Possible Allete Sale