

British International Investment (BII), a UK government-owned and aid-funded company, has a portfolio of overseas fossil-fuel assets worth hundreds of millions of dollars, Carbon Brief can reveal.
In 2020, BII committed to “aligning” its “future” investments with the Paris Agreement and since then it has doubled its renewable-energy funding.
But, as of 2023, the last year for which data is available, it also still had a large portfolio of gas-fired power plants across Africa and south Asia.
Multiple freedom of information (FOI) requests by Carbon Brief reveal fossil-fuel energy and related projects worth nearly $700m (£526m) on BII’s books, which represents about 6% of its assets in 2023.
The FOI results also show that, at the end of last year, BII still had $70m (£53m) of unspent funds earmarked for foreign fossil-fuel companies in the coming years.
BII has not breached its own investment guidelines and says its fossil-fuel exposure fell further in 2024 as it aims to “manage and responsibly exit” these assets.
However, MPs and campaigners have criticised BII’s legacy fossil-fuel investments for “conflicting” with UK climate goals and diverting increasingly scarce aid resources.
Climate pledge
BII is the UK’s development finance institution (DFI), a publicly owned, for-profit company that invests in businesses in developing countries.
These investments are meant to promote economic development, especially via projects – including new energy infrastructure – deemed “too risky” for private investors.
BII largely supports itself using financial returns from its existing portfolio, which was worth approximately £7.3bn ($9.2bn) in 2023.
However, the UK government has also provided BII with billions of pounds from its aid budget. This support has grown even amid massive cuts to UK aid, with BII receiving an extra £400m last year due to reduced government spending on housing asylum seekers.
The government has also been leaning more on BII to reach its international climate finance goals.
Despite being wholly owned – and partly funded – by the Foreign, Commonwealth and Development Office (FCDO), BII has an “arm’s length” relationship with the UK government and makes its own investment decisions.
In 2020, the previous Conservative government committed the UK to ending new overseas fossil-fuel funding beyond March 2021.
This came after BII – then known as CDC Group – had pledged in its 2020 climate strategy that it would not make any new investments that were “misaligned with the Paris Agreement”, based on a Task Force on Climate-related Financial Disclosures framework.
Then-chief executive Nick O’Donohoe stated that the climate strategy would “shape every single investment decision we make moving forward”.
This was hailed as an end to fossil-fuel financing by the institution, despite some remaining “loopholes”. Notably, its fossil-fuel policy allowed for new investments in gas projects if they were deemed “consistent with a country’s pathway to net-zero by 2050”.
Since making its pledge, BII has repeatedly come under fire from MPs and campaigners for continuing to hold “active investments” in fossil-fuel companies.
Fossil assets
BII says that its fossil-fuel portfolio, which mainly consists of gas-fired power plants in “power-constrained” African nations, “has been on a steady downward trajectory since 2020”.
However, the company has not released data on the value of its fossil-fuel assets since 2021, citing “commercial sensitivities”.
In September 2024, Carbon Brief filed an FOI request with BII to obtain data on the company’s fossil-fuel and renewable-energy investments, as well as their asset value.
Following more than six months of back-and-forth – including Carbon Brief requesting an internal review of its FOI request – the company provided much of the information that was originally requested at the end of March 2025.
This included annual data on projects that BII has already committed to support, such as the Sirajganj 4 gas plant in Bangladesh and the Amandi Energy gas plant in Ghana.
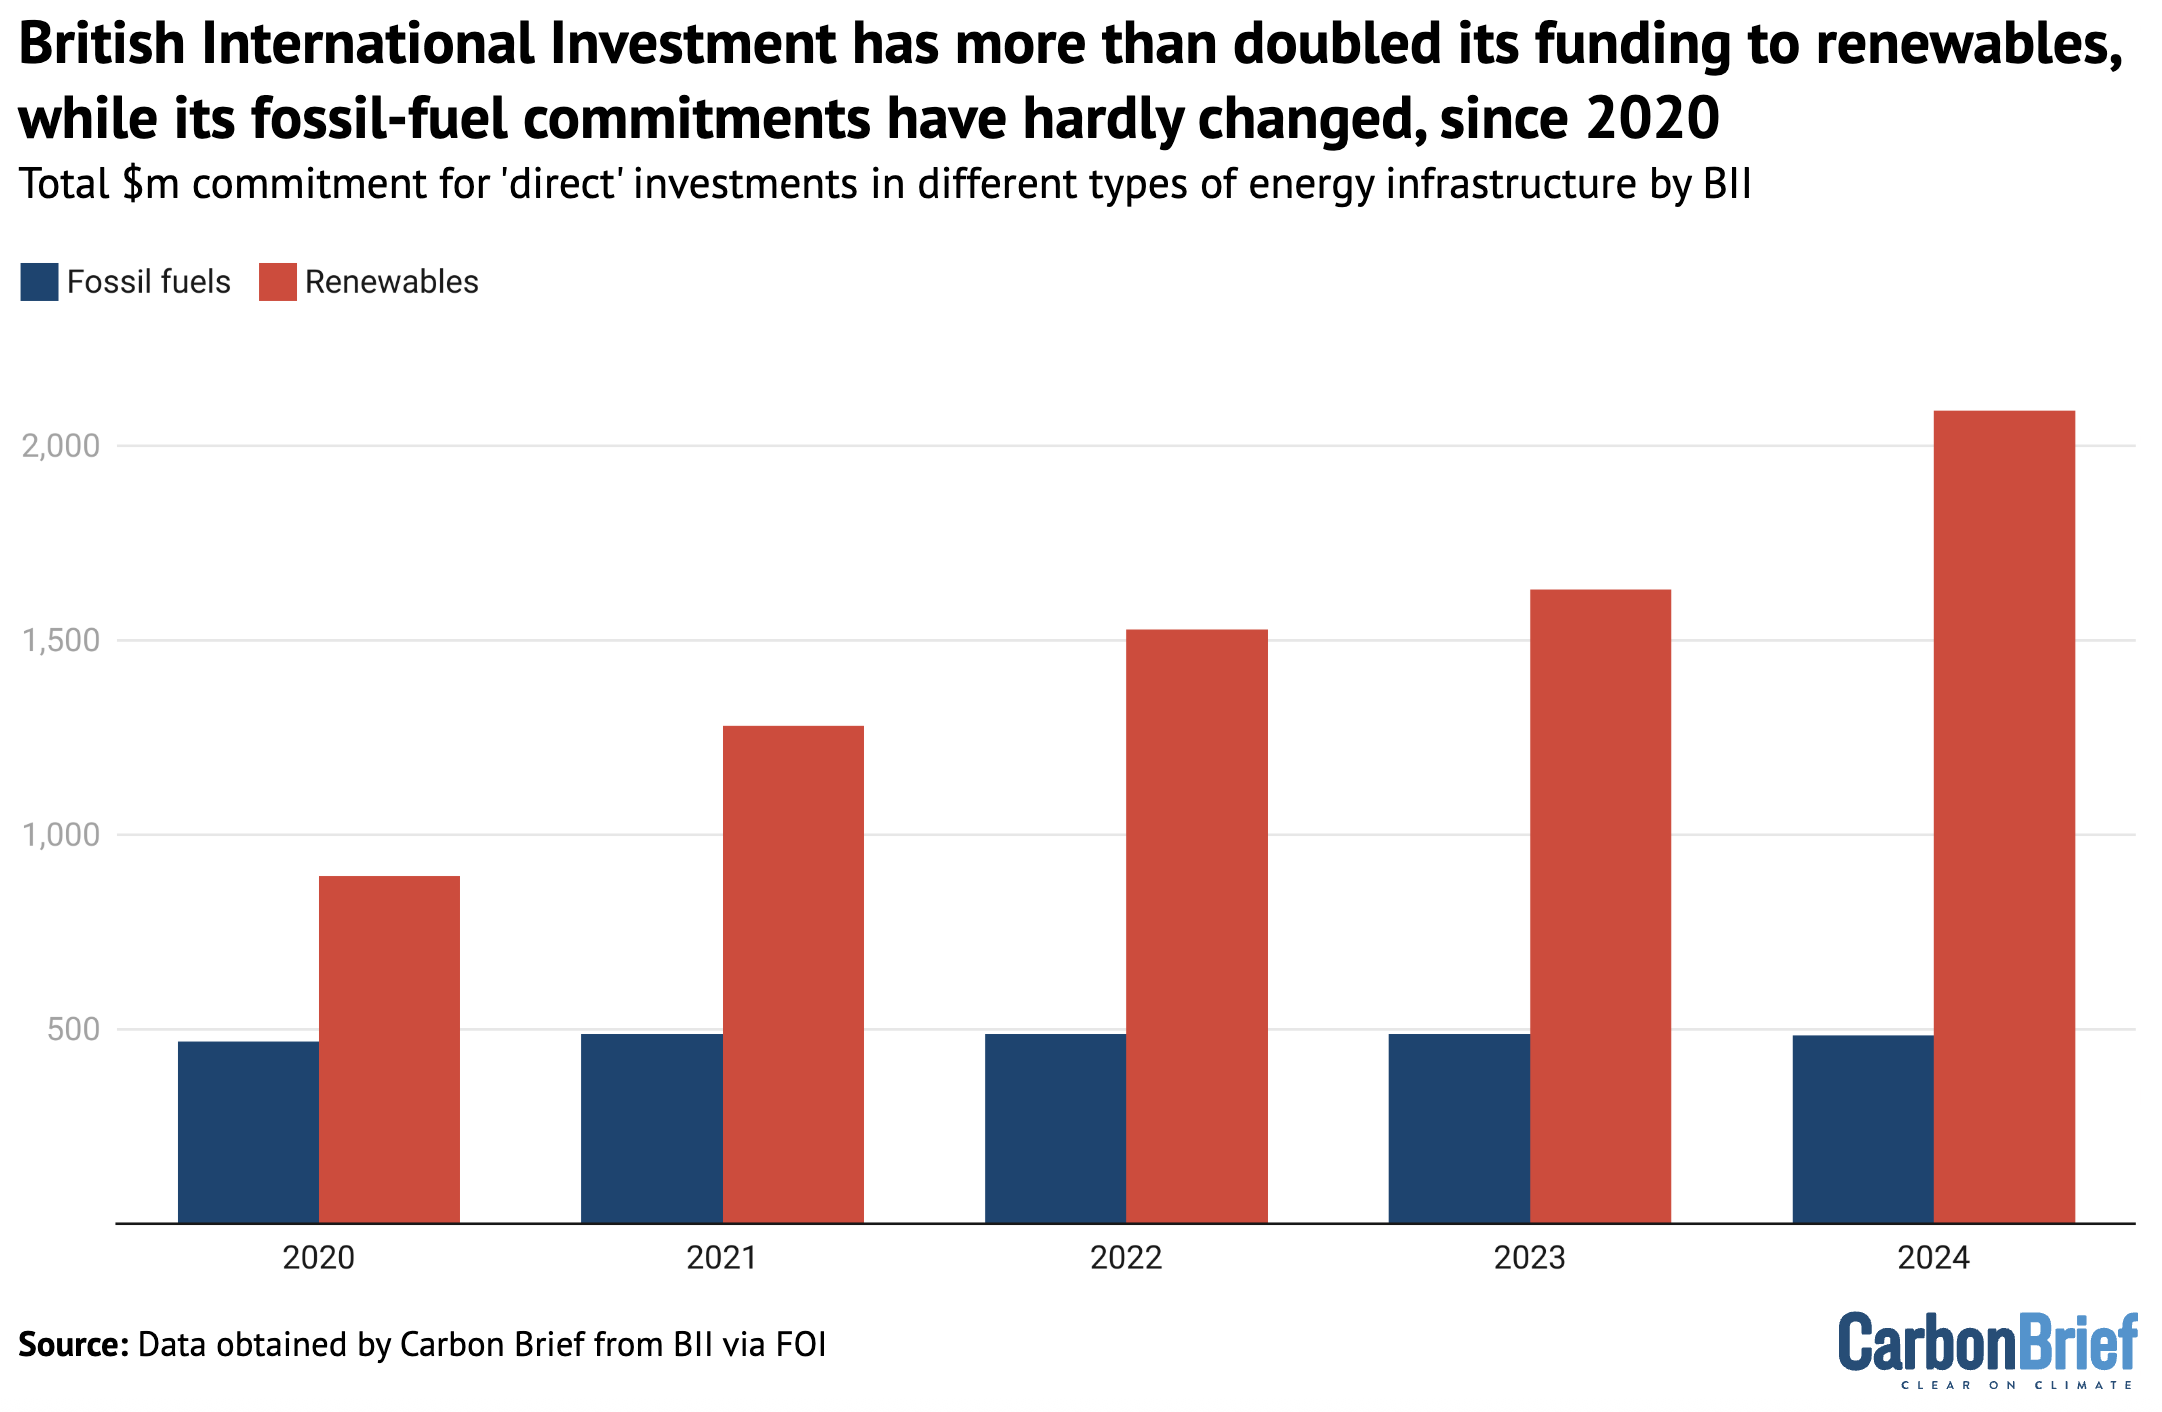
As the chart below shows, BII’s cumulative commitments to fossil-fuel companies have remained roughly the same since its climate strategy in 2020. This is in line with its pledge to provide no “new commitments” to most fossil-fuel projects.
One exception is an extra $20m (£15m) in 2021 for Globeleq, a company controlled by BII that primarily supports gas power in Africa. An investment in a Mozambique gas project that year by Globeleq was deemed “Paris-aligned” and, therefore, allowed under BII’s rules.
Meanwhile, BII’s total commitments to renewable energy projects have more than doubled, from $894m (£672m) to $2.1bn (£1.6bn), between 2020 and 2024.
Once funds have been “committed”, they can remain “undrawn” for many years. This means that money committed before 2020 can still be distributed without breaching BII’s pledge. Carbon Brief asked BII how much of these “commitments” remained undrawn each year.
This revealed that BII has continued sending money to fossil-fuel projects since its 2020 pledge, disbursing around $57m (£43m) over this period. At the end of 2024, there was still $67m (£50m) of “undrawn” fossil-fuel finance waiting to be spent.
BII tells Carbon Brief that, as “commitments” are legal contracts, it is obliged to provide these funds as and when they are required.
Beyond “direct” investments in energy projects, BII has also made “indirect” commitments to fossil fuels via private financial institutions. The company tells Carbon Brief it does not have details of how much these third-party funds invest in fossil-fuel projects.
Daniel Willis, finance campaign manager at the NGO Recourse, points to examples such as Gigajoule and Ademat, companies that have received new finance injections for fossil-fuel projects beyond the 2020 date, on BII’s behalf. (Again, this is allowed under BII’s guidelines.)
Willis tells Carbon Brief that these investments and the continued payments from existing commitments “clearly go against the spirit of the UK government’s fossil fuel policy”.
BII initially rejected Carbon Brief’s request for the “net asset value” of every fossil-fuel investment in its portfolio. It argued that disclosure could weaken its commercial position.
However, the company eventually agreed to disclose the aggregate value of its fossil-fuel assets for the period 2020-2023.
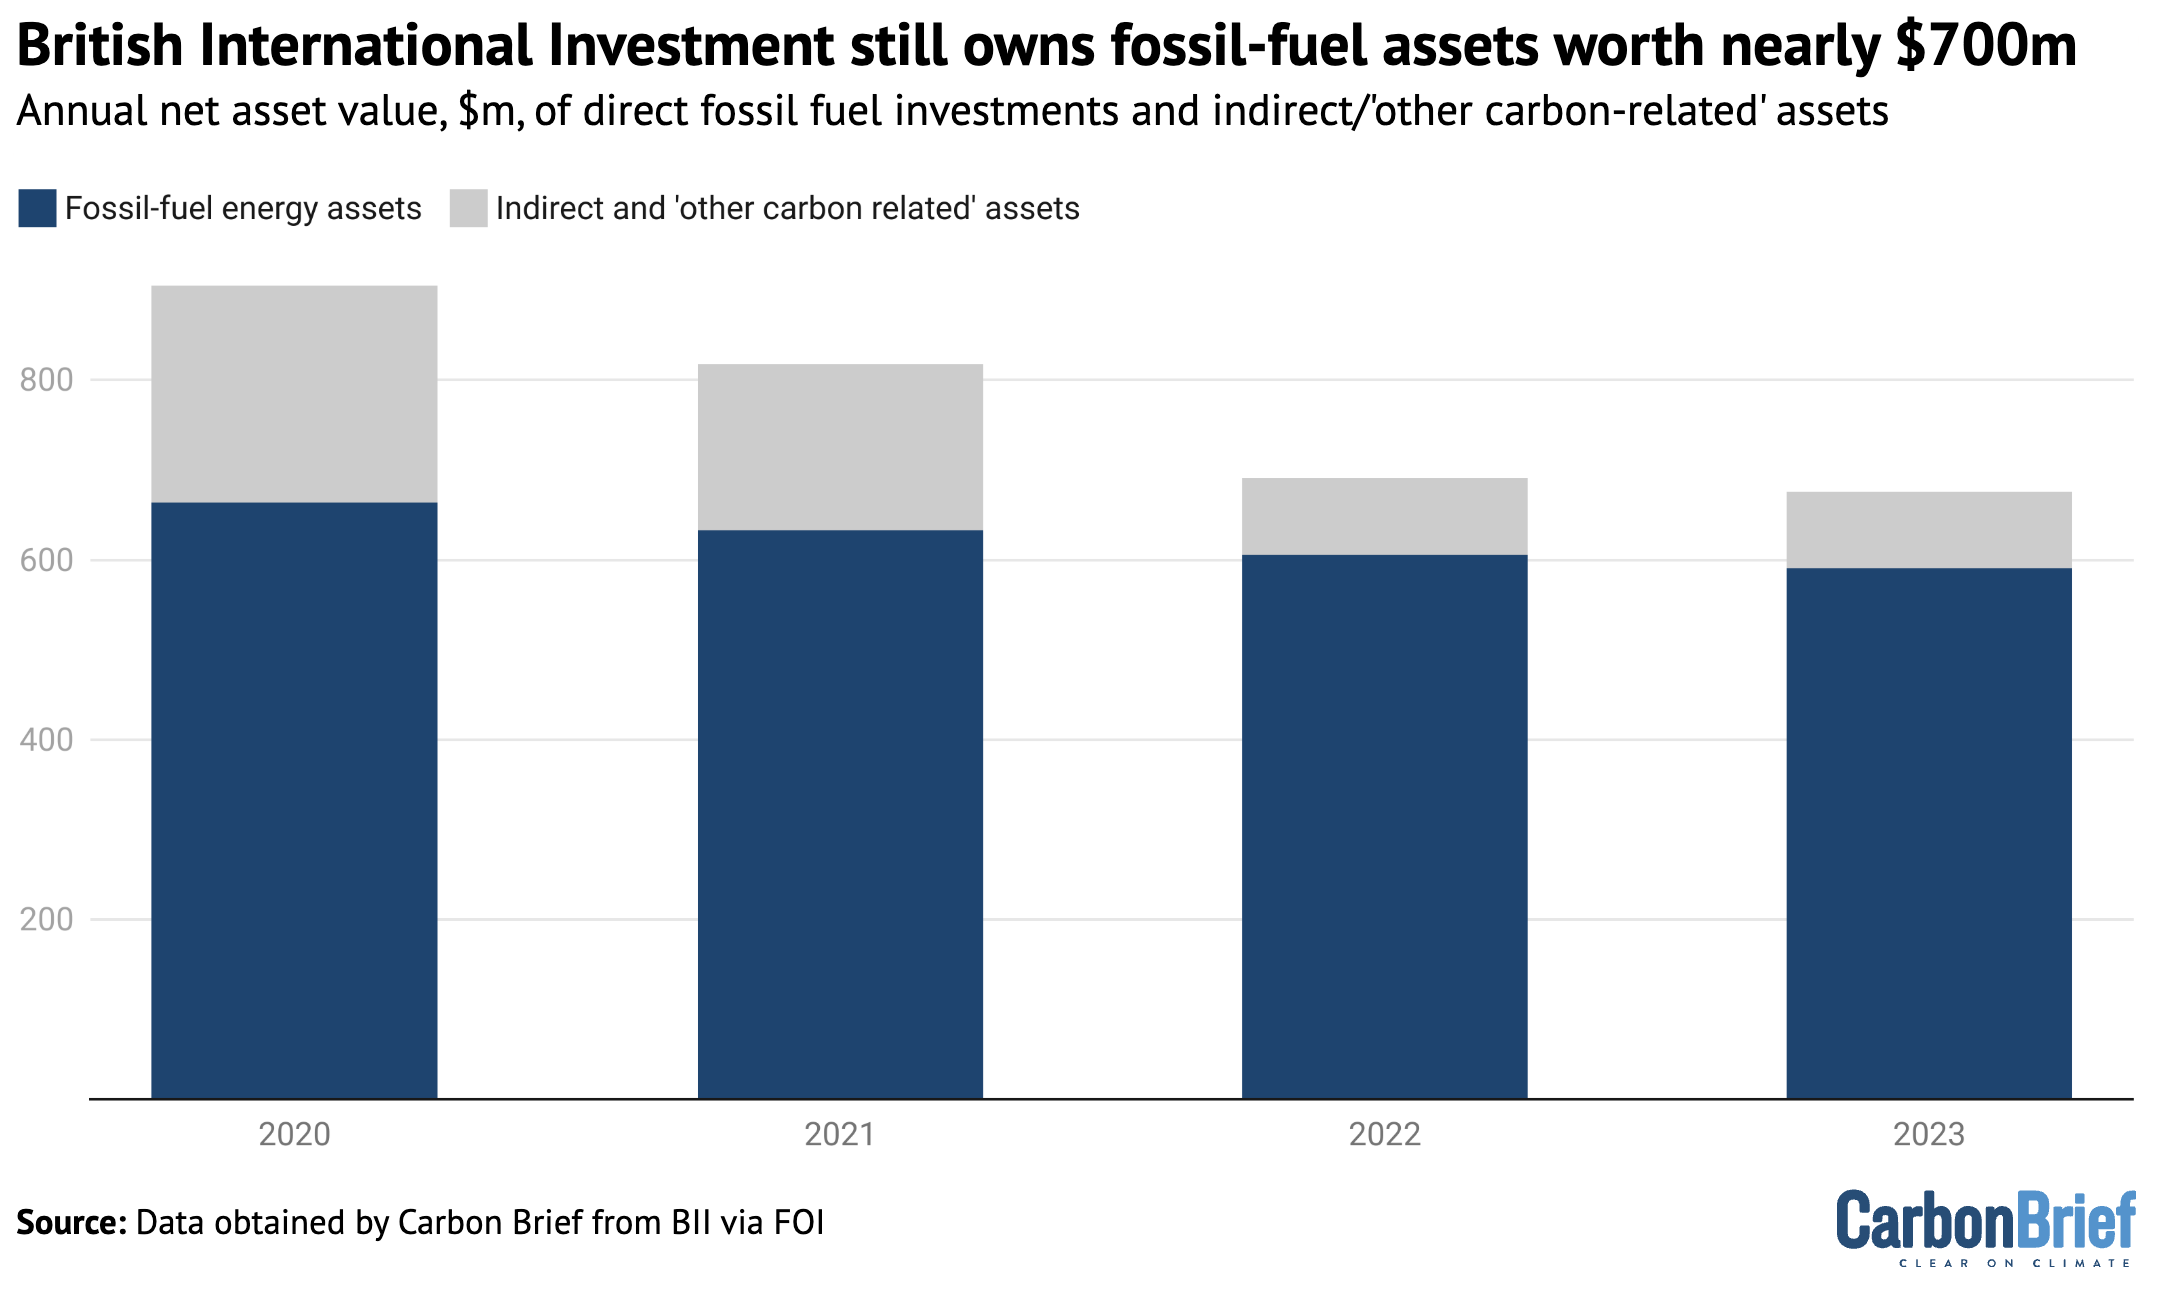
The data reveals that, as of 2023, BII still owned $591m (£444m) worth of gas-fired power plants and other fossil-fuel energy assets, rising to $676m (£508m) when indirect assets are included. This amounts to around 6% of BII’s assets.
While BII declined to provide Carbon Brief with the 2024 figures, a company spokesperson tells Carbon Brief that they plan to release them “this summer”, adding:
“Our 2024 annual report and accounts…will show that our exposure to fossil-fuels assets has fallen 39% since 2020 and now makes up just 6% of our total portfolio. Over the same period, the value of our climate-finance portfolio has increased by 122% to $2.5bn [£1.9bn] and now accounts for 26% of our total portfolio.”
As the chart below shows, there has already been a gradual drop in the value of BII’s direct fossil-fuel energy investments since 2020. The decline can likely be attributed to investees paying off debts to BII, fossil-fuel assets losing value and – to some extent – BII exiting smaller investments.
With evidence that BII’s fossil-fuel portfolio is declining in value, Sandra Martinsone, policy manager at the international development network Bond, tells Carbon Brief that “sooner or later” these will likely become stranded assets:
“The longer BII holds on to these fossil-fuel investments, the higher the risk of losing the invested aid pounds.”
The drop in the value of BII’s indirect fossil-fuel and “other carbon-related” assets – which includes non-energy companies that serve fossil-fuel companies – has been sharper. This can be largely attributed to BII ending support for fossil-fuel trade and supply chains in 2022.
‘Worrying trajectory’
In its FOI response, BII says that it “seeks to manage and responsibly exit fossil-fuel assets”. However, NGOs and politicians have raised concerns about the pace of change.
Natalie Jones, a policy advisor specialising in fossil-fuel phaseout at the International Institute for Sustainable Development (IISD), tells Carbon Brief that while BII has not breached its own climate guidelines:
“The fact that fossil fuel investments remain on BII’s books is not a good look for the organisation, bearing in mind its 2020 commitment to aligning its activities and investments with the Paris Agreement and the UK’s 2021 policy to end all international public support for fossil fuels.”
Civil-society groups have repeatedly called for BII to set a timeline for divesting from fossil fuels. They have even argued that, in the context of “drastic” UK aid cuts, BII should not receive more aid funding and instead reinvest funds from some of its existing assets.
Criticism of BII’s approach to fossil fuels is captured in a 2023 report by the International Development Committee of MPs. It refers to BII legacy investments “conflicting” with UK policies, including the alignment of all aid with the Paris Agreement.
The report also notes that there “does not appear to be a definitive path for BII exiting those fossil-fuel investments or transitioning its existing investment portfolio to green energy”.
Committee chair and Labour MP, Sarah Champion, says that, while the most recent data is not yet publicly available, the figures released to Carbon Brief point to a “worrying trajectory” in BII’s fossil-fuel investments. She tells Carbon Brief:
“It appears that BII has stayed on this worrying trajectory. This must change: as the government proposes a new strategic direction for UK aid spending, focusing on poverty reduction and genuinely responsible investment must be BII’s number one priority.”
In a statement alongside its FOI response, BII says that “forced divestment increases the likelihood that buyers of such assets would be less responsible owners, thereby increasing the future risk of negative climate impact”.
It also says that “being viewed as a forced seller” could reduce the value BII could obtain from those assets. This position was supported by the previous Conservative government.
Jones tells Carbon Brief that concerns about the responsibility of new owners are legitimate:
“However, it would be great to see from BII a plan to responsibly exit or, even better, decommission their fossil fuel assets. There is a case to be made for a responsible exit that would free up funds for much-needed climate finance.”
BII argues that, with around 600 million Africans still lacking access to electricity, gas power remains “essential” for providing “baseload” power to many nations on the continent.
This position has been supported by a number of African governments. However, many civil-society groups, both in Africa and around the world, argue that developed countries should focus financial resources on expanding clean power capacity in developing countries.
Nick Dearden, director of Global Justice Now, which has previously questioned the legality of the BII-controlled Globeleq supporting gas power in Africa, tells Carbon Brief it is “inappropriate” for aid money to be spent this way:
“It’s also trapping the countries that are building this stuff into a type of energy which is on its way out.”


The post Revealed: UK development body still has $700m invested overseas in fossil-fuel assets appeared first on Carbon Brief.
Revealed: UK development body still has $700m invested overseas in fossil-fuel assets

The launch of the Africa Energy Bank (AEB) has been put back yet again, raising doubts about the institution’s future ability to finance fossil fuel projects – its main objective – as global lenders retreat from such investments over climate concerns, experts told Climate Home News.
The bank, which had been billed to launch in September after a series of delays, is now scheduled to begin operations in November, according to the head of the African Energy Chamber, an advocacy body for the continent’s oil and gas sector.
Even as the world aims to transition away from fossil fuels, many African leaders have made clear they want to continue exploring and extracting the continent’s large oil and gas deposits – estimated at around 125 billion barrels of crude and over 600 trillion cubic feet of gas – to boost economic development.
As a group, Africa sided with a number of powerful oil-and-gas producing nations in blocking progress on negotiations to craft a global roadmap to transition away from fossil fuels at last year’s UN COP30 climate talks, although some countries did individually support the proposal.
-
Campaigners oppose Dangote’s planned Kenya refinery over climate and ecological risks
Plans to build Africa’s second largest oil refinery in ecologically sensitive region criticised as “environmental recklessness” -
Tanzania pushed African nations to oppose fossil fuel transition at COP30
While chairing the African group at the summit, the gas-dependent nation advised the continent’s ministers to block language on transitioning away from fossil fuels


Meanwhile, major projects under development across the continent – including the 1,443-km East African Crude Oil Pipeline (EACOP) and Dangote’s 700,000-barrel-per-day Kenyan refinery – show that African governments see oil and gas as playing a significant role in meeting their energy and economic needs for many years to come.
In 2022, at a gathering of the African Petroleum Producers’ Organization (APPO) in oil-rich Angola, ministers from its member states adopted a resolution to create the Africa Energy Bank to finance projects for the production, use and trade of oil, gas and broader energy sources.
African control over energy resources
An article on the APPO website explains that the bank was conceived as a way to overcome “disenchantment” with fossil fuels among “the international community” which it said had crystallised around the “energy transition” concept.
“If Western countries, after having long taken advantage of the energy sources they now revile to develop, can afford the luxury of abandoning them, this is not the case in Africa,” it adds, noting that many of the continent’s economies are still largely dependent on oil and gas revenues.
A separate web page about the bank, also hosted on APPO’s website, says its objectives include financing the exploration, production and refining of oil and gas, as well as supporting member states in transitioning from fossil fuels to cleaner energy sources “while ensuring energy security”.
Said Addi, a former executive with Shell and energy commodities trading house Gunvor, said the new bank was judged necessary because financing for hydrocarbons from many traditional international lenders has become constrained.
In trying to fill this financing gap, Africa is not simply setting up another fund to support oil and gas, he added. “It is also an attempt to give African countries greater control over how their energy resources and infrastructure are financed,” he explained.
Nigeria to host the AEB
The energy bank – a joint initiative of APPO and the African Export–Import Bank (Afreximbank) – has so far suffered several delays and is almost two years behind schedule. The initial plan was to start operations in January 2025, with Nigeria as the host country, but the bank’s opening was delayed to June of that year to allow Nigeria time to finalise the construction of the bank’s headquarters in Abuja.
After the government announced the completion of the offices in late November 2025, a new launch date was set for January 2026, which was moved back to April, June and then September. Now it has shifted again to November, raising concerns that the institution may be losing momentum.
Former Shell executive Addi said that if the capital is eventually paid in, the bank becomes operational and its first projects are commercially credible, then the delays will be regarded as normal teething troubles in setting up a multilateral institution. But, he added, scepticism will be justified if it continues to stall.
Uganda may see lower oil revenues than expected as costs rise and demand falls
Baron Lamarré, an oil and gas expert and former Petronas oil trader, said that missing “three deadlines in a row is not normal”, and warned that if the timeline slips again, “the story flips from ‘ambitious institution finding its footing’ to ‘good idea that lost momentum before it found any’.”
The Nigerian government, APPO and Afreximbank did not respond to requests for comment by the time of publication.
The funding challenge
The Africa Energy Bank is targeting base capital of $5 billion, with plans to scale up to $120 billion within five years by mobilising private-sector funds. However, it is expected to start operations with initial seed capital of $500 million.
The funding plan is to have the 18 member countries of the APPO contribute $83 million each to the bank as equity for a combined $1.5 billion. Afreximbank, other non-APPO African countries and investors outside the continent are expected to provide the remaining $3.5 billion.
But even the initial $500 million has not been easy to mobilise. In May, APPO Secretary-General Farid Ghezali called on members to deliver on their pledges towards the startup goal before the end of June. But the delays suggest this may not have been met, with experts saying Africa may be finding it difficult to self-fund its oil and gas projects in the absence of international capital.
Lamarré said every extension of the deadline points to the fact that “raising fossil fuel capital in Africa without the majors and their financing networks is brutally hard”.
Why the global electrification agenda misses the point on Africa’s energy crisis
Since 2020, Western lenders, export credit agencies and insurers have been in steady retreat from African hydrocarbons, he said, while oil majors are divesting their African assets, handing over fields to smaller local operators whose credit ratings are not high enough to borrow cheaply.
Even capital from China and the Gulf, which has partially filled the gap, cannot match the volume, tenor or pricing that Western investors once offered, Lamarré argued.
“If mobilising the first $500 million of seed capital [for the AEB] has taken this long, that’s the clearest signal yet of how steep the climb to $120 billion looks,” he said, noting that the continent’s energy financing gap is as large as $30 billion-$45 billion per year.
Africa’s investment landscape, meanwhile, has been shifting. While foreign direct investment dropped from a 2024 peak, inflows remained roughly one-third above the continent’s long-term average in 2025, according to the 2026 World Investment Report from UN Trade and Development (UNCTAD). They are concentrated in a few sectors including critical minerals needed for renewable energy technologies, battery manufacturing and advanced industrial production.
At the same time, data on global energy investment from the International Energy Agency (IEA) shows that fossil fuel investment in Africa has declined over the last decade.

“Trojan horse” for fossil fuels
While the Africa Energy Bank struggles to get off the ground, climate campaigners have criticised its primary aim of financing oil and gas on the continent at a time when the world is starting to move away from high-carbon fuels to cleaner alternatives.
Bhekumuzi Dean Bhebhe, founder of Africa Change Lab, described the bank as a “Trojan horse”, arguing that its focus on fossil fuel financing runs counter to the global energy transition and the African Union’s Agenda 2063 goals of sustainable development and inclusive growth.
The energy bank, he warned, “risks locking Africa into a new cycle of debt, dependency and fossil fuel entrenchment”, adding that its financing blueprint does not pave the way for a climate-resilient future. “In truth, it is to deepen the same extractive, carbon-heavy pathways that the continent should be moving away from,” he added.
Ugandan farmers use British court to try to stop East Africa oil pipeline
Kenya-based climate and energy expert Joab Okanda said the AEB’s plan to finance oil and gas is “a misplaced priority” and it should instead back clean energy in line with the policies of some of Africa’s major export markets like Europe.
In addition, the new bank could struggle to mobilise enough resources to advance large-scale oil and gas projects, he added, noting that its proposed $5-billion initial capital is equivalent to the cost of the East African Crude Oil Pipeline alone.
The AEB’s aim of backing more fossil fuels should be flipped “to support countries that are oil-dependent to start working on their transition plans”, Okanda said.
The post Launch of Africa Energy Bank delayed again in blow to oil and gas hopes appeared first on Climate Home News.
Launch of Africa Energy Bank delayed again in blow to oil and gas hopes
A booklet published by the UK’s opposition Conservative party includes a “cost of net-zero” that appears to have been doubled by a spreadsheet error.
The “common sense” policy document argues that “what people ultimately want is a government competent enough to solve the problems for which it takes responsibility”.
In a section that says “sophisticat[ed]…modelling” should not be a substitute for “political judgement”, the “Right Way” document disparages various estimates of the cost of net-zero.
The Conservative document then claims – incorrectly – that the government’s official adviser, the Climate Change Committee (CCC), had put the cost of net-zero at close to £1tn. It says:
“In 2020, the CCC estimated that its route to net-zero would cost £957bn.”
In fact, the CCC’s 2020 estimate was exactly half this amount – £478bn – and last year it published a revised figure of £108bn, largely as a result of the falling cost of electric vehicles (EVs).
Spreadsheet error
The Conservative party’s erroneous claim appears to stem from another report that had accidentally added up numbers twice, using a spreadsheet published by the CCC in 2020.
The 2020 spreadsheet contains a table listing the additional investments that would be needed to build a net-zero economy, from low-carbon electricity generation through to heat pumps and EVs.</