

Saudi Arabia and Pakistan were among the top importers of Chinese solar panels in 2024, with more than half heading to countries in the global south.
The findings come from Ember’s China’s solar PV export explorer, which tracks shipments to more than 200 countries and was recently updated with figures for the full year of 2024.
In total, China’s solar panel exports rose by 10% in 2024, with imports by global-south countries rising by 32% and those to the global north falling by 6%.
This means Chinese exports grew less quickly than the 30% rise in solar installations outside China last year, indicating that other countries have been boosting their own solar manufacturing capacity and that already-imported stocks were being run down.
Apart from Pakistan and Saudi Arabia, which both witnessed different solar booms last year, there was also a sharp uptick in sales to many small African and Latin American countries in late 2024, suggesting that China may be finding new markets for its solar exports.
China itself – the biggest of all the global-south solar markets – installed more solar panels than it exported for the second year in a row.
This article analyses the latest trends from China’s solar export data, highlighting the markets currently seeing record growth and the trends that underlie this.
Global-south sales surge
China’s exports of solar panels to the global south have doubled in the past two years, overtaking global-north sales for the first time since 2018, according to data collated in the Ember export explorer.
Global-south imports more than doubled from 60 gigawatts (GW) in 2022 to 126GW in 2024. That surpassed global-north imports, which were only 12% more in 2024 than in 2022, as shown on the chart below.

Biggest solar importers
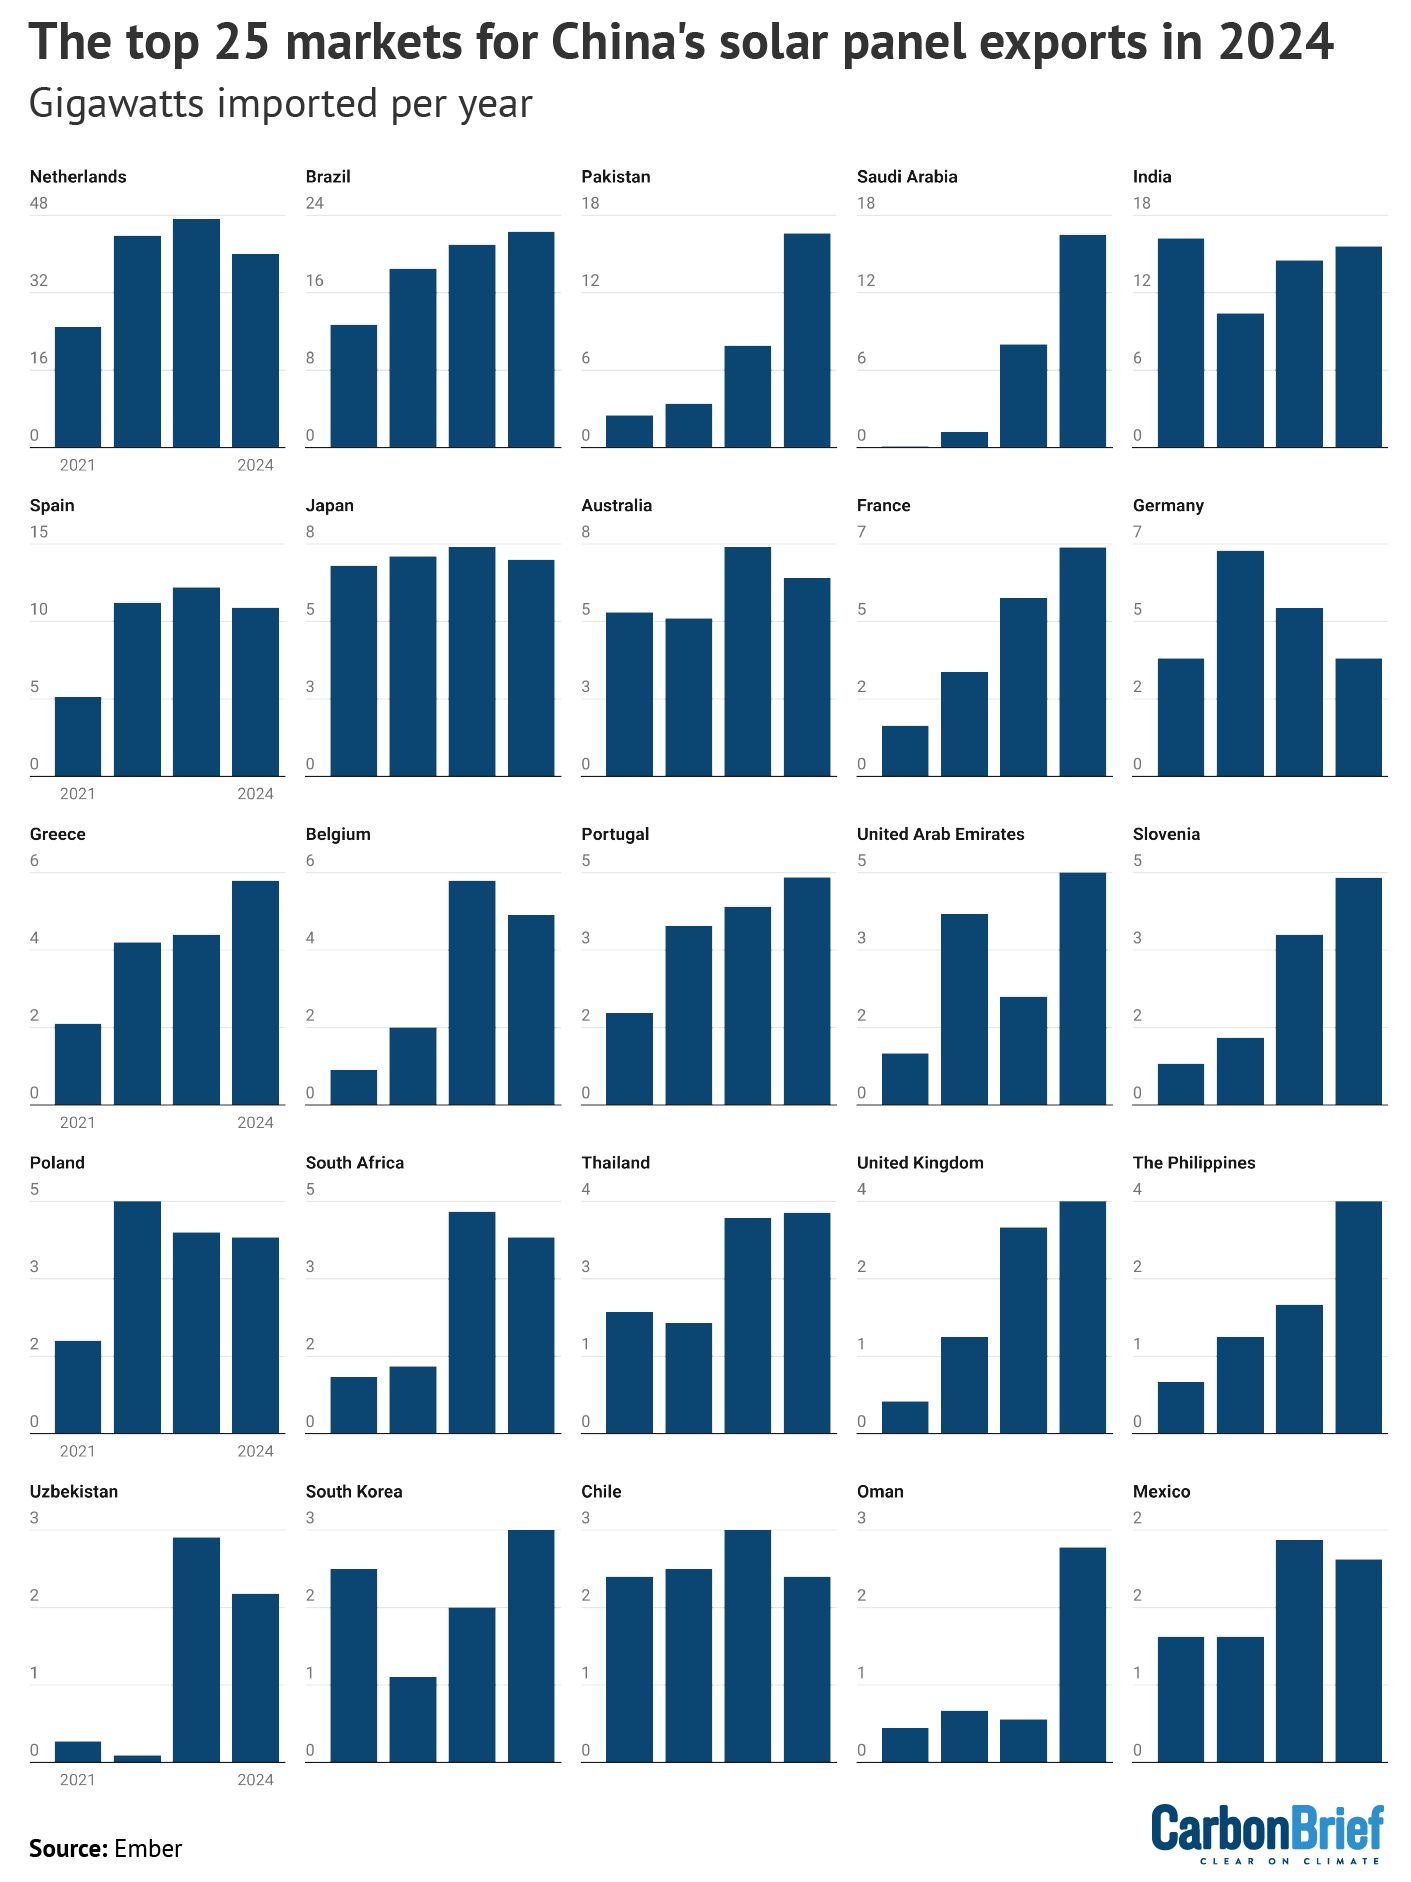
The Netherlands was the biggest importer in 2024 and has been every year since 2019, as a result of Rotterdam serving as an import hub for much of continental Europe. The following four places were all global-south countries, the data shows.
Brazil was in second place again, importing more than 20GW for the second year in a row. However, the imposition of import taxes by the government, the refusal of electricity distributors to connect new solar systems and solar “curtailment” are all causing headwinds in 2025.
Pakistan and Saudi Arabia jumped to third and fourth, respectively. (The next section charts the rise of these two very different solar giants, from the 12th and 26th biggest importers, respectively, in 2022 into the top five.)
India was in fifth place in 2024. Its module imports remained similar to those in 2023, but its installations rose to a record high, enabled by a step up in new domestic solar panel manufacturing capacity.
In January 2025, that helped India hit 100GW of solar installed, according to government figures. India is partly relying on Chinese imports, whilst simultaneously scaling up its own manufacturing industry.
The other large global-south markets – identified in the export explorer data – are also spread across the world, as shown in the figure below.
They include the UAE and Oman in the Middle East, Thailand and the Philippines in south-east Asia and then South Africa, Chile, Uzbekistan and Mexico.
Pakistan and Saudi Arabia
Pakistan and Saudi Arabia have had almost identical imports of Chinese solar panels for the past two years. They stood at 8GW in 2023 and then more than doubled to 17GW in 2024, placing them as the third and fourth largest importers in the world, the export explorer shows. Their monthly imports from China are shown in the figure below.

However, that is where the similarities end. Pakistan’s growth has come almost entirely from small-scale “distributed” installations, without co-located battery storage and paid for by consumers. Saudi Arabia’s growth has come almost entirely from desert solar farms, complete with some battery storage and paid for by international energy companies.
Pakistan’s solar boom was ignited by spiralling electricity costs and chronic power shortages, which have put energy at the heart of the country’s economic problems.
The country installed 10-15GW of solar in 2024 alone, according to Bloomberg estimates. Pakistan’s peak electricity demand was just 30GW in 2023, which gives an idea of how big solar has become in the country.
Large utility-scale solar is minimal – only 0.63GW of such capacity is operational. Instead, almost all of the new solar capacity was installed on rooftops or next to factories or fields, for direct use by consumers.
However, hardly any battery capacity was installed alongside the new solar panels, meaning people and companies still rely on the grid for electricity outside of sunny hours.
The surge in solar capacity has helped drive down electricity generation from fossil fuels, despite fast-growing electricity demand. However, it also “threatens to disrupt” the grid, where demand has created at the same time as becoming more variable.
Turning to Saudi Arabia, solar panels are used mostly in large desert renewable auction tenders. There have been five solar tender rounds in 2017, 2019, 2021, 2023 and 2024.
The latest tender round contracted 3.7GW of large-scale desert solar parks, achieving the cheapest reported electricity prices in the world of $13 (£10) per megawatt hour. (Note that these reported prices are somewhat artificial and are likely to underestimate the full cost.)
None of the winning solar parks were contracted with batteries. However, parallel battery tender rounds are now commencing.
There are estimated to be only 3.3GW of solar projects currently operational in Saudi Arabia, but a further 5.4GW are under construction. The solar plant owners are international energy firms including KEPCO, EDF Renewables, Masdar and TotalEnergies, as well as Saudi companies.
The country plans to move from near-zero renewables in 2020 to 50% of its total electricity generation coming from renewables in 2030. In relative terms, this is one of the most ambitious renewable targets anywhere in the world.
New markets
There were 15 countries that saw a large uptick in imports of Chinese solar panels towards the end of 2024, according to the export explorer data and shown in the figure below.

There were large increases in Nigeria, Algeria and Iraq, where there is clear evidence that demand for panels is growing.
For example, Nigeria’s growth was driven by blackouts in 2024 and the removal of fuel subsidies, making diesel generators more expensive to run.
Iraq is currently constructing its first large solar plant, while another 7.5GW of projects were approved by the government in 2024 to meet growing electricity demand.
Meanwhile, Algeria has a plan for 3GW of solar projects, which is now underway.
For a cluster of a further 12 countries, it is less clear if the recent uptick in solar panel imports is a structural change that will continue into 2025 and beyond.
There are large incentives for China’s solar manufacturing companies to meet year-end targets, so it is possible that containers of solar panels were sold at discounted rates to help meet these goals.
The cluster includes many small African countries – Benin, Burkina Faso, Chad, Djibouti and Guinea – and Latin American countries – Ecuador, El Salvador, Guyana and Nicaragua.
The December 2024 imports are quite large in the context of the small electricity systems of many of these countries. As such, these solar panels would provide a relatively meaningful increase in renewable electricity generation if they go on to be installed.
China installs more than exports
China has not just been exporting growing numbers of solar panels. – In 2024, it installed more solar panels than it exported for the second year running, according to Ember analysis.
Indeed, China installed 333GW of solar capacity domestically in 2024, some 38% more than the 242GW of solar panels that it exported, as shown in the figure below.

From 2019 to 2022, China had been exporting more solar panels overseas than it installed domestically. However, that changed when China’s solar panel installations surged from 103GW in 2022 to 260GW in 2023.
By the end of 2024, China had a total installed solar capacity of 1,064GW, making it the first country to achieve the 1 terawatt (TW) benchmark.
Reducing reliance on China
China’s solar exports grew for the seventh consecutive year in 2024, rising to a record 242GW, Ember’s data shows.
Exports rose by 10% year-on-year, which was a significant slowdown from the rate of growth seen in recent years. However, solar installations outside of China grew by 30%.
This demonstrates a step-up in ambitions to reduce reliance on Chinese solar panel imports by a number of countries around the world.
For example, India’s solar panel manufacturing capacity has skyrocketed in recent years. In 2023, it added 23GW and a further 11GW was completed in the first half of 2024. India’s reported module and cell production capacities stood at around 80GW and 7GW, respectively, as of March 2025.
However, the country still relies on imported Chinese solar cells. The value of shipments to India rose 30% from $970m in 2023 to $1.3bn in 2024, accounting for almost half (48%) of China’s cell exports.
This reliance is seen as a temporary but essential part of the transition to full India manufacturing capability, as solar cell manufacturing capacity steps up, with the aim that projects contracted through the government solar auctions only use locally-sourced cells from June 2026.
The EU is on track to meet its 30GW of solar panel manufacturing target in 2025. However, the numbers are relatively small compared to other regions. Europe had 22GW of solar module manufacturing capacity in 2024, with 12GW in the construction pipeline.
The US does not import Chinese panels, but it does rely heavily on imports from other Asian countries. It imported 51GW of solar panels in the first 10 months of 2024, more than 90% of which were from Vietnam, Thailand, Malaysia, India or Cambodia.
US manufacturing capacity rose from 7GW in 2020 to 50GW in early 2025, with plans announced for a further 56GW, according to trade association the Solar Energy Industries Association.


The post Guest post: Saudi Arabia’s surprisingly large imports of solar panels from China appeared first on Carbon Brief.
Guest post: Saudi Arabia’s surprisingly large imports of solar panels from China

Scientists have vowed to keep working on the next flagship set of reports for the Intergovernmental Panel on Climate Change (IPCC), after a political row over the timeline for their release saw its latest session suspended on Friday evening without agreement.
During the weekend, government officials and scientists alike expressed disappointment over the inability to reach a compromise before some delegates from developing countries and small island states had to leave the week-long meeting in Ethiopia to catch flights home.
The disagreement – which has persisted since early 2024 – turns on whether the three key parts of the AR7 assessment should all be published before the conclusion of the UN’s next Global Stocktake of global climate action, which is due to be completed in late 2028.
The IPCC issued a statement after the close of the session, saying that “key agenda items” – the timelines for the three AR7 reports, as well as the IPCC budget – remain open and under discussion. It said the IPCC’s plenary session and its deliberations on the pending agenda “will resume at the earliest opportunity”, giving no further details of when.
IPCC Chair Jim Skea told delegates in closing remarks that recent months had been some of the most turbulent for the climate science panel and that, if there were stronger words than “profound disappointment” he would use them, according to a summary published by the Earth Negotiators Bulletin (ENB). IPCC discussions happen behind closed doors.
IPCC scientists remained committed
In an open letter, issued on Monday, a group of nearly 120 scientists – from a total of 664 AR7 authors – said they “stand committed to continue working to deliver the AR7 reports in a manner that is rigorous, timely and inclusive, in line with our mandate to be policy-relevant”.
“An assessment that arrives after the decisions it is meant to inform cannot serve its purpose,” they emphasised. “The second Global Stocktake in 2028 is such a decision point, and the world should not have to face it without the IPCCʼs latest assessment.”
Europe, small islands and the least developed countries, plus many Latin American and developed nations, want the IPCC to meet this deadline, arguing that the findings from the UN climate science body are irreplaceable in the UN climate policy-making process.
However, around a dozen developing countries plus Russia have argued that the reports should come later in order to allow for greater research input from the Global South – something that, in their view, would make the findings fairer. They also claim that a shorter timeline would put excessive pressure on experts.
-
Who shapes climate science? The equity question facing the IPCC
Early completion of the next global climate science assessment reports risks excluding research from the Global South, which is key to ensuring the findings are fair -
Governments that support climate science must stand firm against naysayers
The IPCC is meeting to decide the timing of its next major report, as some countries try to delay it and weaken the case for faster emissions cuts


The most vocal of this group at last week’s meeting were India and Saudi Arabia, according to the ENB summary and a developed country diplomat. Critics see this push for a longer timeline as an excuse to deprive government decision-makers of the latest science and ease pressure on emerging economies to raise their ambition, particularly on cutting emissions.
Commenting on last week’s meeting, France’s ambassador for climate negotiations Benoît Faraco said a broad coalition of developed and developing countries from all five continents, “united in their support for science and the timeline proposed by scientists”, had withstood pressure “from a few countries” seeking to slow down the process of adopting the IPCC reports.
He added that France would not back down and would “continue to fight tirelessly for science, protect the integrity of information, and convince our partners that without the best available scientific data, we will be less effective in tackling climate change and protecting our populations”.
Inclusivity proposal stalled
In a bid to unlock a solution for the AR7 timeline, countries discussed ways to improve the inclusivity of the IPCC’s work. One option put on the table was for the IPCC to expand its funding for delegates from developing countries to attend some or all of its sessions from one to two participants, according to the ENB summary and a delegate speaking to Climate Home News.
That would increase the costs for the IPCC to complete AR7 by up to a quarter, according to an assessment shared by the secretariat. The panel’s budget is under severe strain and its officials have warned that, without additional voluntary contributions, it risks running out of money before it can deliver on this assessment cycle.
Climate Home News understands that some of the IPCC’s traditional donors – which mainly include European countries, Japan and Australia – indicated a willingness to support funding for an additional developing country participant. But without an agreement over the budget or the timeline for the reports, that option was ultimately not adopted.
‘Disappointed and worried’
The three reports are managed by working groups that collate and draw overall findings from the latest scientific studies and data on the physical effects of global warming around the world, how to adapt to it, and pathways for cutting planet-heating emissions in order to meet the temperature goals of the Paris Agreement.
Winston Chow, an urban climate professor at Singapore Management University who co-chairs Working Group II on adaptation, wrote in a LinkedIn post that he was “disappointed and worried” for the IPCC authors who have worked “extraordinarily hard” to assess the relevant climate science over the past two years.
He said he shared their concern that “the rigour, time and goodwill they’ve invested are now being put at risk by the Panel’s stalemate”.
As science comes under attack at UN talks, climate movement splits over how to respond
For Working Group II, a meeting for 250 experts writing that report is scheduled for January 2027, followed by the approval of a special report on cities and climate change in Singapore next March.
But because the IPCC’s budget has not been confirmed due to uncertainty about the AR7 schedule, travel support for those researchers is at risk, wrote Chow. “If they cannot participate, our assessments will lose vital expertise, perspectives and scientific breadth, and the collective effort of our authors will be undermined,” he warned.
Scientific work continues
Despite the political holdups, he – together with French climate scientist Robert Vautard, co-chair of Working Group 1 – agreed with IPCC head Skea who told the IPCC’s closing session on Friday: “The engine room of the IPCC is working, and it’s healthy.”
Vautard commented in a separate post on LinkedIn after it ended: “The boat is at full steam.” Working groups I and II are due to start revising the first drafts of their reports, while Working Group III on reducing emissions is finalising its first draft which will be out soon, he wrote.
“The most exciting two years of the cycle are ahead, for the authors. The momentum in the engine room is here and now. Trust the engine room!” he added.
The IPCC and some scientists report that progress has been made towards achieving an equitable balance of authors from the Global North and the Global South.
The group of researchers who signed the open letter on Monday noted that “inclusivity is at the heart of how we work”, with author teams bringing together experts from developed and developing countries with diverse backgrounds and at different stages of their careers.
Plea to overcome political differences
The signatories include several scientists from some of the countries opposed to the alignment of all IPCC reports with the Global Stocktake.
“We are committed to an assessment in which the knowledge, experience and priorities of every region are fully reflected, a commitment we share with the leadership of the IPCC.
Equity is built into how our assessment is being drafted,” they added.
They appealed to governments that make up the IPCC “to overcome their political differences and work together as we do as a global scientific community, so that we can deliver the IPCC reports the world needs to hear”.
In a statement published on Monday, IPCC chair Skea said reaching consensus on the schedule for the reports is “vital”. He added that the assessments provide authoritative scientific evidence to inform national climate policies, strengthen adaptation and resilience and support access to climate finance, as well as helping communicate the scale of the climate crisis and the urgency of efforts to tackle it.
The post IPCC scientists vow to press on with climate reports despite political deadlock appeared first on Climate Home News.
IPCC scientists vow to press on with climate reports despite political deadlock
An Lambrechts is a biodiversity politics expert at Greenpeace International with extensive experience in biodiversity-related multilateral negotiations. She is the head of the Greenpeace delegation at the Convention on Biological Diversity (CBD) COP17 happening in Yerevan, Armenia.
In 2022, COP15 delivered the landmark Kunming-Montreal Global Biodiversity Framework to halt and reverse biodiversity loss by 2030. With COP17 starting in Yerevan, we are now halfway to the deadline, and according to the first Global Review of progress, countries are not on track to meet the biodiversity targets, and implementation must accelerate fast.
One of the main findings of the Global Review is that funding falls far short of the scale needed to halt and reverse nature loss. But the crisis facing the world’s biodiversity is not an absolute scarcity of capital – it is a profound public policy distortion.
The global economy currently spends roughly $30 destroying nature for every single dollar invested in its protection. According to a report from the Intergovernmental Science-Policy Platform on Biodiversity and Ecosystem Services, a staggering $2.4 trillion is spent in public subsidies for fossil fuels, agriculture and water use, while global investment in biodiversity conservation and restoration stands at a mere $220 billion.
Countries urged to ramp up “insufficient” nature policies at COP17
Yet, discussions about how to close the biodiversity finance gap continue to claim that salvation lies in mobilising private capital, scaling offsets and “derisking” investments in nature. This is a fundamental misunderstanding of both the nature of ecological stewardship and of the global financial architecture.
Biodiversity conservation is not a speculative investment portfolio – it is the foundation of human survival. The health of our planet is a non-monetisable, non-excludable public good. Expecting profit-seeking private capital to protect nature perpetuates the structural drivers of ecosystem destruction in the first place.
But if private market mechanisms cannot save biodiversity, where will the necessar