Disseminated on behalf of Surge Battery Metals Inc.
Electric vehicles (EVs), energy storage systems (BESS), and clean energy technologies depend heavily on lithium. Yet even with fast-rising demand, the United States still produces far less lithium than it needs.
In 2024, U.S. production reached only about 25,000 tonnes of lithium carbonate equivalent (LCE) – roughly 2% of global supply, which totaled around 1.2 million tonnes. That output is enough for only about 158,000 Tesla Model 3 battery packs per year.
The gap between national demand and domestic production keeps widening. Most lithium used in the U.S. comes from imports, mainly from Chile, Australia, and China. This dependency exposes the country to supply disruptions, trade restrictions, and price volatility. If imports are interrupted, the U.S. battery and EV industries could face serious setbacks.
Growing Demand Creates a Structural Deficit
Global demand for lithium is growing quickly. Analysts expect it to quadruple by 2030 as more countries adopt EVs and build large-scale battery storage.
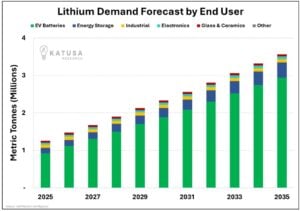
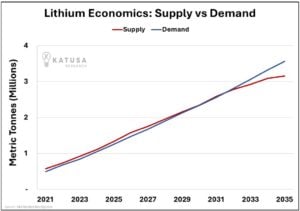
According to Katusa Research (2025), global lithium demand is projected to climb from 1.04 million tonnes in 2024 to 3.56 million tonnes by 2035 — a 3.5× increase. About 83% of that demand will come from EV batteries, while energy storage will account for another 11%.
Source: Katusa Research
Per the International Energy Agency, the U.S. alone may need over 625,000 tonnes of LCE per year by 2030, compared with only a small fraction produced domestically today.
Building new mines takes time – often 10 to 15 years from exploration to commercial production. This long timeline makes it difficult to ramp up supply fast enough to meet demand. Therefore, a lasting shortage is forming. If the U.S. does not accelerate new projects soon, it may depend on imports for decades.
Each EV battery pack uses large amounts of lithium. On average, an EV requires about 60 kilograms of LCE – or 8 to 10 kilograms per kilowatt-hour (kWh) of battery capacity. As automakers build more gigafactories, that adds up quickly.
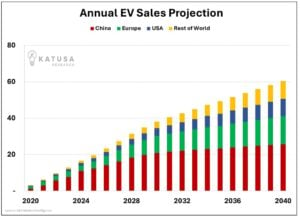
Katusa’s data also shows that global EV sales jumped from 2 million in 2020 to 11 million in 2024, a 450% surge — and could exceed 60 million units per year by 2040, more than half of all cars sold globally.
Source: Katusa Research
The U.S. is expected to have 440 gigawatt-hours (GWh) of battery manufacturing capacity by 2025 and more than 1,000 GWh by 2030. That growth alone could double or triple national lithium demand.
Introducing the Nevada North Lithium Project
One company aiming to help close this gap is Surge Battery Metals. Its flagship asset, the Nevada North Lithium Project (NNLP) in Elko County, Nevada, is one of the few high-grade lithium clay deposits in the United States.
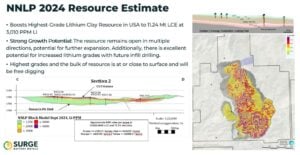
The project has an inferred resource of 11.24 million tonnes of LCE, grading about 3,010 ppm lithium, making it the highest-grade lithium clay resource in the country.
The project benefits from ideal logistics. NNLP is only 13 kilometers from major power lines and close to all-season roads. The Bureau of Land Management (BLM) has issued a Record of Decision and a Finding of No Significant Impact (FONSI), allowing expanded exploration over 250 acres. These factors make NNLP a leading U.S. candidate for large-scale lithium development.
How NNLP Helps Close the Supply Gap
Surge Battery Metals’ Nevada North project has features that position it well to help close America’s lithium gap. Its high grade and large resource size suggest it could deliver significant output once in production. Higher-grade deposits typically allow lower extraction costs and shorter payback periods.
Because NNLP already has key permits and environmental clearance, it may reach production faster than many early-stage peers. That speed is critical as EV demand accelerates and the U.S. targets more domestic battery manufacturing.
Just as important, NNLP supports U.S. policy goals for supply chain security. Producing lithium domestically reduces reliance on imports, helping stabilize supply and pricing for American automakers. It also supports the Inflation Reduction Act, which requires that most EV battery minerals come from North America or allied countries by 2027.
In March 2025, the U.S. government took direct equity stakes in several lithium ventures, including Lithium Americas’ Thacker Pass, signaling a strong federal commitment to reshoring critical mineral production. This policy backdrop reinforces projects like NNLP as part of a national security priority.
Strengthening NNLP Through Strategic Partnership
Moreover, Surge Battery Metals signed a joint venture letter of intent (LOI) with Evolution Mining (ASX: EVN), allowing Evolution to earn up to 32.5% ownership by funding C$10 million toward the Preliminary Feasibility Study (PFS) for the Nevada North Lithium Project (NNLP). Surge retains majority control and project management, keeping its long-term vision and stakeholder priorities front and center.
This partnership delivers big strategic value. By merging Surge’s lithium expertise and mineral rights with Evolution’s 75% stake in 880 acres of private land – and over 21,000 added acres nearby – the deal significantly increases the JV’s land position. The expanded acreage boosts the overall exploration area and brings in mineral rights in key southern zones, possible clay unit extensions to the north, and territory in historic mining districts and key drainage areas.
Importantly, Evolution’s staged funding speeds up completion of the PFS and helps NNLP reach development milestones while lowering capital risk for Surge shareholders. If Evolution completes its full commitment, it will own 32.5% of the JV, but Surge remains the lead partner. This setup means Surge still directs the project, while using Evolution’s operations know-how and resources. With a larger land package and a joint operating committee, NNLP is well on its way to Tier 1 status and is strengthening its spot in North America’s battery metals supply chain – vital for clean energy and EV growth.
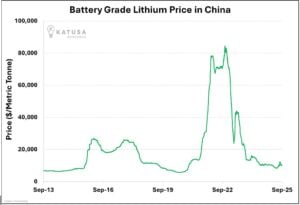
Like any mining venture, NNLP faces challenges. Lithium prices fell nearly 90% from their 2022 peak, but from June to September 2025, they rebounded 24%, showing early signs of recovery.
This cyclical pattern reflects Katusa’s “cost floor” concept — production costs in China and Australia now average around $5,000–6,000 per tonne LCE, while South American and U.S. projects need about $8,000/t to stay profitable. If prices fall near those levels, high-cost mines pause output, tightening supply again and stabilizing prices.
Another factor is resource expansion. NNLP’s current resource is inferred, but the company expects to complete its current drilling program at NNLP by the end of October 2025. Once the results are released, the lithium resource will be upgraded from Inferred to Indicated and Measured categories. This step will strengthen confidence in the deposit’s scale and quality, supporting the upcoming Pre-Feasibility Study (PFS).
Permitting and community engagement also remain important; even in a mining-friendly state like Nevada, water use and land reclamation practices must meet strict environmental standards.
Surge Battery Metals has emphasized sustainable practices, including water recycling and progressive site reclamation, as part of its exploration and development plan.
Competition is growing, too. Lithium projects across South America, Australia, and Canada are advancing quickly. Still, Nevada’s combination of stable governance, established mining laws, and proximity to major battery plants gives U.S. projects like NNLP a strong advantage.
A National View: U.S. Lithium Resources and Reserves
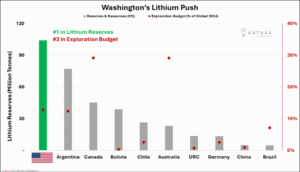
The U.S. is home to some of the world’s largest lithium reserves, but it still underdevelops them. According to the U.S. Geological Survey, global lithium reserves total around 21 million tonnes, with the U.S. holding roughly 12%. Nevada alone hosts the country’s biggest lithium resources, concentrated in the Thacker Pass region and the northern claystone belts – where NNLP is located.
Unlocking these resources is vital. Every new project that moves forward strengthens the domestic supply chain and supports national goals to lead in clean energy technology.
Surge Battery Metals plans to continue advancing NNLP through new drilling campaigns and metallurgical studies in 2025. These programs aim to expand and upgrade resources, optimize extraction processes, and confirm the potential to produce battery-grade lithium carbonate with 99.9% purity. The company is also evaluating potential offtake partnerships with battery and automotive manufacturers.
Analysts and investors will be watching for:
Updated resource estimates and grade expansion
Progress toward pre-feasibility studies
Partnerships or funding deals with strategic investors
Regulatory updates supporting U.S. critical mineral development
Positive results in these areas could accelerate NNLP’s move toward construction and help it become one of the first next-generation lithium clay projects to enter U.S. production.
Powering the U.S. Energy Future
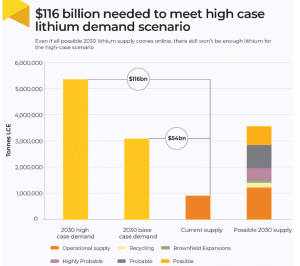
The U.S. faces a widening gap between lithium supply and demand that could slow its clean-energy transition. Katusa Research projects a 400,000-tonne global supply shortfall by 2035, roughly the world’s entire 2020 output – a deficit that could keep prices elevated long term.
Source: Katusa Research
Surge Battery Metals’ Nevada North Lithium Project provides a realistic and timely opportunity to help close that divide. With its high-grade resource, strong economics, strategic location, and environmental focus, NNLP could play a central role in building a stable, self-sufficient lithium supply for the United States.
As the nation races to electrify transportation and decarbonize energy, projects like NNLP will be critical. They are not only about producing lithium – they are about powering the next chapter of American industry and ensuring that the clean-energy future is built on secure, sustainable ground.
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Surge Battery Metals Inc. (“Company”) made a one-time payment of $50,000 to provide marketing services for a term of two months. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2024, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
For more information on the Company, investors should review the Company’s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the c