


Samsung Electronics Co. (005930.KS) has secured a major multiyear deal with Tesla Inc. (NASDAQ: TSLA) to manufacture advanced AI semiconductors at its upcoming facility in Taylor, Texas. The $16.5 billion agreement runs through 2033 and marks a crucial win for Samsung’s underperforming foundry business.
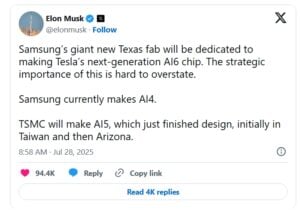
Elon Musk confirmed that the Texas fab will produce Tesla’s AI6 chip, a next-generation inference processor critical to powering autonomous vehicles and humanoid robots. Here’s a snapshot of his tweet:
Tesla Shifts from TSMC to Samsung to Diversify Supply Chain
Tesla’s decision to switch from longtime chip partner Taiwan Semiconductor Manufacturing Co. (NYSE: TSM) to Samsung reflects a broader strategy to strengthen supply chain resilience. Tensions in Taiwan and global semiconductor shortages have prompted Tesla to explore alternative partners. Samsung’s progress in 2nm gate-all-around (GAA) chip fabrication, with yields now surpassing 40% makes it an appealing option.
This move also signals Tesla’s deeper commitment to vertical integration. By co-developing chip manufacturing processes with Samsung, Tesla is embedding itself in the heart of one of the world’s largest semiconductor ecosystems.
A Boost for Samsung’s Struggling Foundry Division
The contract comes as Samsung’s chip foundry business with the Texas fab had been facing delays. According to TrendForce, its share of the global foundry market slipped to 7.7% in Q1 2025, far behind TSMC’s 67.6%.
But the Tesla deal now provides a clear pathway to scale operations by 2026. Notably, Samsung shares surged 6.8% on Monday following the announcement, their highest level since September, as indicated by Bloomberg.
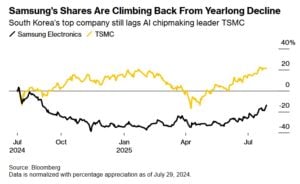
The partnership signals confidence in Samsung’s next-gen chip tech and could serve as a launchpad to secure more U.S. and global clients. Interestingly, Samsung’s role as a viable TSMC alternative also grows stronger.
New Chips, Faster Cars: Tesla’s Path to Full Autonomy
The AI6 chip, set for production at Samsung’s Texas facility, is the centerpiece of Tesla’s next-gen Full Self-Driving (FSD) platform. Elon Musk emphasized that the chip could deliver exaflop-level computing power, unlocking near-human-level decision-making for autonomous systems.
While production is still two years away, the AI6 chip plays a crucial role in Tesla’s roadmap to deploy fully driverless robotaxis and expand its AI offerings, including Optimus humanoid robots. Tesla expects these FSD-equipped vehicles could make up 30% of total sales by 2027.
Still, Musk acknowledged challenges ahead. Tesla’s current FSD offering requires driver supervision, and its early robotaxi trials in Austin have faced criticism for erratic behavior. He also noted the transition from AI4 (already made by Samsung) to AI5 (designed by TSMC) and then to AI6 could cause confusion and delays in retrofitting older vehicles.
Tesla and Samsung Eye the AI Chip Market’s Explosive Growth
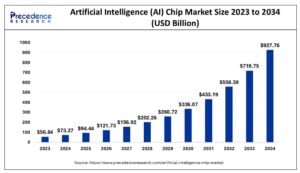
A report says the AI chip industry size was valued at USD 52.92 billion in 2024 and is predicted to reach USD 295.56 billion by 2030, at a CAGR of 33.2% from 2025 to 2030.
Another analysis forecasted USD 927.76 billion by 2034, expanding at a CAGR of 28.90% from 2024 to 2034.
Tesla and Samsung’s alliance offers two key advantages in this fast-moving space:
- Higher Efficiency and Performance: Tesla can develop more efficient FSD systems using Samsung’s advanced 2nm chips, reducing costs and improving AI capabilities.
- Stronger Supply Chains: Samsung’s dual-hub strategy spanning Texas and its planned $228 billion mega-cluster in South Korea offers Tesla a reliable chip supply free from geopolitical threats.
Global Strategy Backed by U.S. and South Korea
Bloomberg revealed that this partnership aligns well with the U.S. effort to revitalize domestic semiconductor manufacturing. Supported by the CHIPS and Science Act, Samsung is set to receive up to $9 billion in U.S. funding and tax incentives for its operations in Texas. This aligns with broader efforts to reduce dependency on East Asia and strengthen American tech supply chains.
Simultaneously, the deal reinforces South Korea’s $450 billion K-Semiconductor Strategy, positioning the country as a powerhouse in AI chip innovation. By anchoring its foundry with Tesla’s contract, Samsung strengthens its role in global AI manufacturing.
All these factors combined could significantly strengthen both companies’ positions in the race toward scalable AI.
Investors Bet Big on TSLA STOCK
Tesla’s ability to commercialize its AI5 and AI6 chips will directly influence its valuation in the coming years. As its FSD system matures and becomes more widely adopted, TSLA can boost subscription revenue and capitalize on valuable driving data.
This shows that the Samsung deal is a big win for Tesla. Experts noted that it can give the company long-term access to custom AI chips that are key for its Full Self-Driving (FSD) system, robots, and data centers.
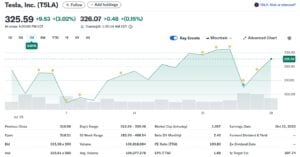
Market data showed, Tesla (TSLA Stock) shares have risen following the announcement of the major chip supply deal with Samsung. The latest available price for Tesla (TSLA) is $325.59, up about 3% from the previous close of $316.06.
This partnership also helps Tesla strengthen its supply chain and have better control over how its chips are made. And for investors, the deal is more than a headline. It’s a foundational shift in the semiconductor and AI chip tech that could redefine the self-driving and AI semiconductor race.
The post Tesla’s Game-Changing $16.5Bn Samsung Deal for AI Chips – Is This a Turning Point for Tesla Stock? appeared first on Carbon Credits.

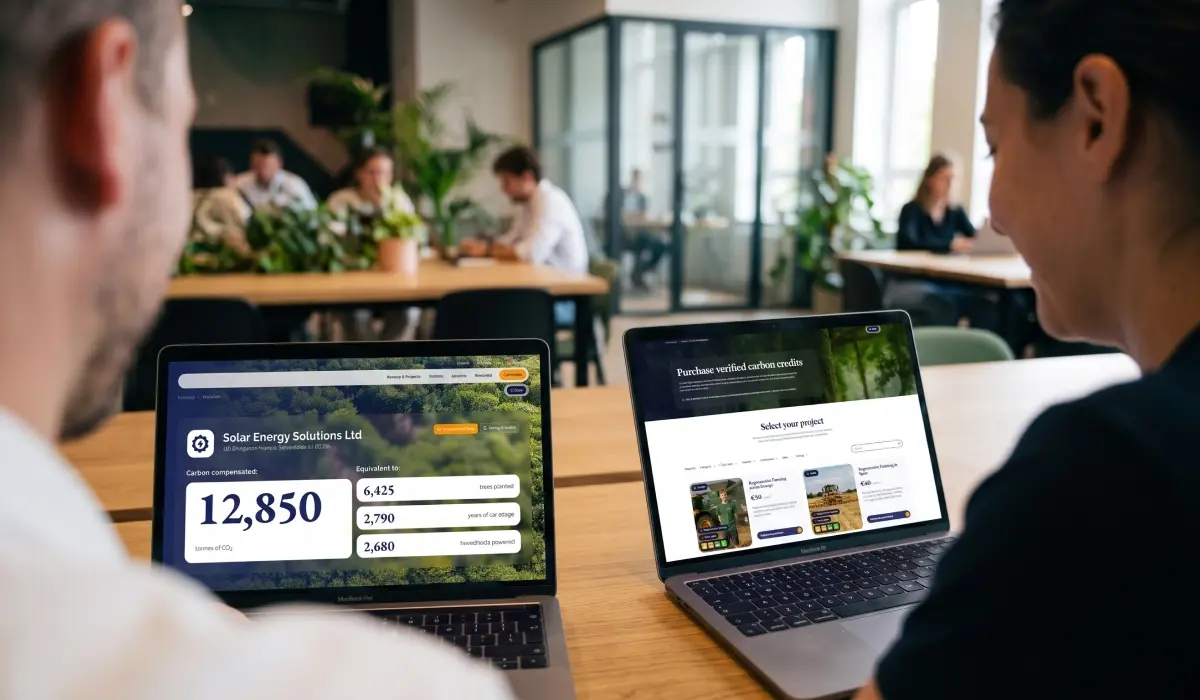
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits