

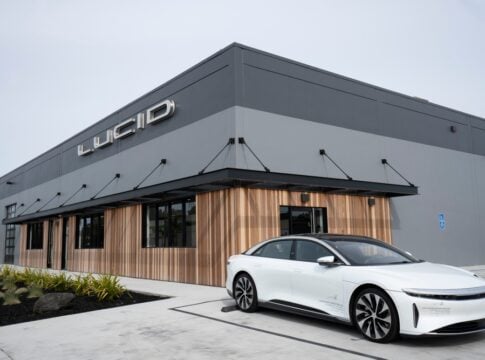
Uber Technologies has taken a deeper financial and strategic position in Lucid Group, signaling strong confidence in the future of autonomous mobility. However, despite a billion-dollar capital boost and a major robotaxi expansion plan, market sentiment around Lucid remains cautious. The latest developments highlight a widening gap between long-term vision and near-term execution risks.
Uber now holds 37.7 million shares, representing an 11.5% stake, following an additional $200 million investment in April 2026. This brings its total investment in Lucid to $500 million, making it one of the largest shareholders outside Saudi Arabia.
The controlling stake still lies with the Public Investment Fund (PIF), which owns more than 54% of Lucid. The fund also injected another $550 million into the EV maker through its affiliate Ayar Third Investment Co., reinforcing its long-term commitment.
Together, these investments form a $1.05 billion capital raise, strengthening Lucid’s balance sheet at a critical time. The funding will support production expansion, technology development, and liquidity needs.
- At the core of this partnership is a major commercial agreement. Uber has committed to purchasing at least 35,000 Lucid vehicles for its planned global robotaxi network. This marks a significant increase from its earlier commitment of 20,000 vehicles announced in 2025.
The scale of this deal is notable. Lucid delivered 15,841 vehicles in 2025, meaning the Uber order alone could double or even triple its annual production over the coming years.
Robotaxi Strategy Gains Momentum with Nuro Partnership
The collaboration goes beyond capital and vehicle supply. It forms a three-way ecosystem involving Nuro, which will provide the Level 4 autonomous driving system known as the Nuro Driver.
Each partner has a clear role. Lucid supplies premium electric vehicles, starting with the Lucid Gravity SUV. Nuro delivers the autonomous driving technology, while Uber integrates the system into its ride-hailing platform and manages fleet operations.
The first commercial deployment is targeted for later in 2026 in the San Francisco Bay Area.
Testing is already underway. Nuro has deployed nearly 100 Lucid Gravity vehicles across multiple U.S. cities to gather real-world data. Early pilot programs have also begun offering test rides to Uber employees, although safety drivers are still present.
Lucid’s upcoming midsize vehicle platform is expected to play a key role in scaling the robotaxi fleet. The company aims to deliver a competitive range using smaller battery packs while improving cost efficiency, interior space, and charging performance. The platform is expected to start below $50,000, making it suitable for both consumer and fleet markets.
Financial Backing Strong, but Execution Challenges Persist
Despite strong investor backing, Lucid continues to face operational hurdles.
For Q1 2026, the company pre-reported revenue between $280 million and $284 million, well below the market expectation of $433.8 million. At the same time, it posted an operating loss close to $1 billion and ended the quarter with roughly $700 million in cash.
Production and delivery numbers remain modest. The company produced 5,500 vehicles and delivered 3,093 units during the quarter, highlighting ongoing challenges in efficiently scaling operations.
Lucid also faced a 29-day disruption in deliveries of its Gravity SUV due to a supplier issue with second-row seating. This incident underscores supply chain fragility and the risks associated with ramping production.
While the company reported strong revenue growth of $1.35 billion in 2025, up 68% year over year, profitability remains out of reach due to high costs and continued investment.
Market Reaction: LUCID Stock Slides Despite Big News
Despite the strategic significance of the deal, market reaction has been negative.
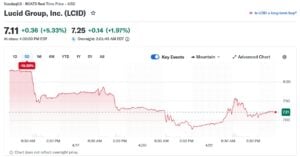
Lucid’s stock fell sharply from $9.96 on April 2, 2026, to around $6.75 by April 20, marking a decline of roughly 32% in less than three weeks. Over the past 12 months, the stock has lost about 71% of its value.
Analysts, including TD Cowen and Baird, have lowered their price targets, citing concerns over dilution, continued cash burn, and execution risks.
In contrast, Uber’s stock has shown relative resilience, gaining about 6% over the same period, according to Stocktwits. This divergence reflects stronger investor confidence in Uber’s diversified business model compared to Lucid’s ongoing operational challenges.
The Bigger Picture: High Stakes, High Risk
Uber’s 11.5% stake represents more than a financial investment. It signals a deep strategic alignment with Lucid’s future and a strong bet on autonomous mobility.
For Uber, the partnership provides access to a dedicated EV supply tailored for robotaxi operations, along with greater influence over vehicle design and platform integration. For Lucid, the deal ensures demand, strengthens its financial position, and creates a pathway beyond the luxury EV segment.
However, risks remain significant. Autonomous driving technology still faces regulatory uncertainty, and execution challenges persist. Nuro’s Level 4 system must prove its safety and scalability in real-world conditions. At the same time, Lucid must ramp up production while addressing operational inefficiencies and relatively limited consumer demand.
The recent decline in Lucid’s stock reflects investor skepticism about the company’s ability to execute its ambitious plans.
Looking ahead, the focus will remain on consistent production growth, improved financial performance, and successful deployment of robotaxi services. Until then, even billion-dollar partnerships may not be enough to restore investor confidence.
In short, Uber is making a bold bet on the future of mobility, with Lucid at the center of that strategy. The outcome will ultimately depend on one key factor: execution at scale.
The post Lucid (LCID) Stock Slides Despite $500M Uber Bet and 35,000-Vehicle Robotaxi Deal appeared first on Carbon Credits.

EU Directive: Empowering Consumers for the Green Transition (ECGT)
The EU Directive, Empowering Consumers for the Green Transition (ECGT), takes effect on September 27, 2026.(1) The goal of ECGT is to protect consumers by ensuring that environmental claims are fair, understandable, and reliable. This regulation does create a new compliance requirement for businesses, but it also provides sustainability and marketing teams with important guidance that helps create consistency in sustainability communications.
Key takeaways
- ECGT takes effect September 27, 2026, and prohibits claims that a product or service has a neutral, reduced, or positive environmental impact based on offsetting alone.
- Named example phrases the regulation prohibits include climate neutral, CO2 neutral certified, carbon positive, climate net zero, climate compensated, reduced climate impact, and limited CO2 footprint.
- ECGT does not want to deter investment in carbon credits. It wants companies to communicate the real benefits of the projects they support instead.
- SBTi’s guidance recommends framing carbon credits as taking responsibility for ongoing emissions, not as making a product or company neutral.
- Voluntary carbon projects deliver real climate progress: reducing super-pollutants, protecting and restoring ecosystems, and supporting communities.
Regarding carbon credits specifically, voluntary carbon projects deliver important climate progress and environmental benefits that provide many talking points for companies. They reduce climate super-pollutants by removing industrial emissions like methane, N2O, HFCs and others. They protect and restore valuable ecosystems and carbon sinks like forests, mangroves and grasslands. They help communities by reducing local pollution, creating employment opportunities, improving access to healthcare, and more.
The Science Based Targets Initiative (SBTi), a global leader in business climate action, concludes that alongside aggressive decarbonization, we should also use high quality carbon credits to take responsibility for our ongoing emissions. SBTi recognizes that carbon credits are important “to help limit temperature overshoot, mitigate transition risks, and support climate solutions.”(2)
ECGT language on carbon offsetting says that they do not want to deter investment in carbon credits. They just want companies to focus on communicating the benefits of the projects they support and avoid claims beyond the scope of carbon credits, which is good for everyone, companies and consumers alike.
The regulation reinforces that carbon credits do not change the sustainability of your products, so carbon credit buyers should not suggest that their products are more sustainable because of carbon credits. Instead, companies need to promote their climate contributions as a way to compensate or take responsibility for their carbon emissions by supporting projects that do great things like reducing global carbon emissions, reducing pollution, preventing deforestation, restoring forests, and more.
ECGT language related to carbon offsetting
The regulation is particularly focused on prohibiting claims, based on offsetting greenhouse gas emissions, that a product or service has a neutral, reduced, or positive impact on the environment in terms of greenhouse gas emissions. These claims are prohibited in all circumstances because they mislead consumers into believing the claim relates to the product itself, or to how it was made and supplied, or into thinking that using the product carries no environmental impact at all.
Named examples of prohibited claims include:
- climate neutral
- CO2 neutral certified
- carbon positive
- climate net zero
- climate compensated
- reduced climate impact
- limited CO2 footprint
These claims are only allowed when they rest on a product’s actual lifecycle impact, not on offsetting emissions outside that product’s value chain, since the two are not equivalent. This prohibition does not stop companies from advertising their investments in environmental initiatives, including carbon credit projects, as long as they present that information in a way that is not misleading and that meets the other requirements of Union law.(1)
SBTi also provides guidance on climate contribution language in its Corporate Net Zero Standard Version 2.0 Draft for Second Public Consultation, November 2025. While the SBTi language is fairly technical, it has a good framework for crafting a climate contribution message.
SBTi Language for Carbon Credits(3)
- Take responsibility for ongoing emissions by delivering mitigation impact contributions
- Carbon credits certify the mitigation outcomes of projects that reduce, avoid, or remove carbon emissions
- Activities that reduce emissions from emission sources not located within the company’s value chain
- Activities that conserve, protect, and enhance natural carbon sinks
- Activities that capture and store carbon in storage pools
SBTi’s draft standard also walks through sample claim language for this kind of contribution. In general, the samples move from a simple percentage statement, to naming a specific verified tonnage tied to that percentage, to a fuller statement that breaks the tonnage into reductions versus removals. Across all three, the framing stays consistent: a company took responsibility for a defined share of its ongoing emissions over a set period, by funding a specific, verified amount of mitigation, achieved through emission reductions or removals.(3)
FAQ: ECGT and Carbon Credit Claims
When does the ECGT directive take effect?
The rules apply across the EU from September 27, 2026, after member states transposed the directive into national law by March 27, 2026.
Does ECGT ban carbon offsetting?
No. It bans specific marketing claims that a product or service is environmentally neutral, reduced impact, or positive based on offsetting. Advertising investment in carbon credit projects themselves is still allowed if it is not misleading.
What phrases does ECGT specifically prohibit?
Named examples include climate neutral, CO2 neutral certified, carbon positive, climate net zero, climate compensated, reduced climate impact, and limited CO2 footprint, when those claims are based on offsetting rather than a product’s actual lifecycle impact.
How should a company describe its carbon credit purchases instead?
SBTi’s guidance recommends stating the specific verified tonnage of emissions reductions or removals funded and describing that as taking responsibility for a defined share of ongoing emissions, rather than claiming the company or product is neutral.
Does this rule apply to company level sustainability claims too?
ECGT is focused on claims about specific products and services in consumer marketing. Broader company level sustainability communication is a separate matter still governed by other existing rules.
While ECGT does add a new compliance burden for businesses, it helps create consistency in sustainability messaging that is important to building confidence in voluntary carbon projects and scaling the industry to help us achieve progress on global carbon emissions.
Disclaimer: Terrapass does not provide legal or regulatory advice. Any interpretation of regulation must be approved by your legal representative.
References:
(1) https://eur-lex.europa.eu/eli/dir/2024/825/oj
(2) https://files.sciencebasedtargets.org/production/files/Corporate-Net-Zero-Standard-version-2.pdf
(3) https://files.sciencebasedtargets.org/production/files/CNZS-V2-Second-Consultation-Draft.pdf
The post The EU’s New Green Claims Rules and Carbon Credits appeared first on Terrapass.
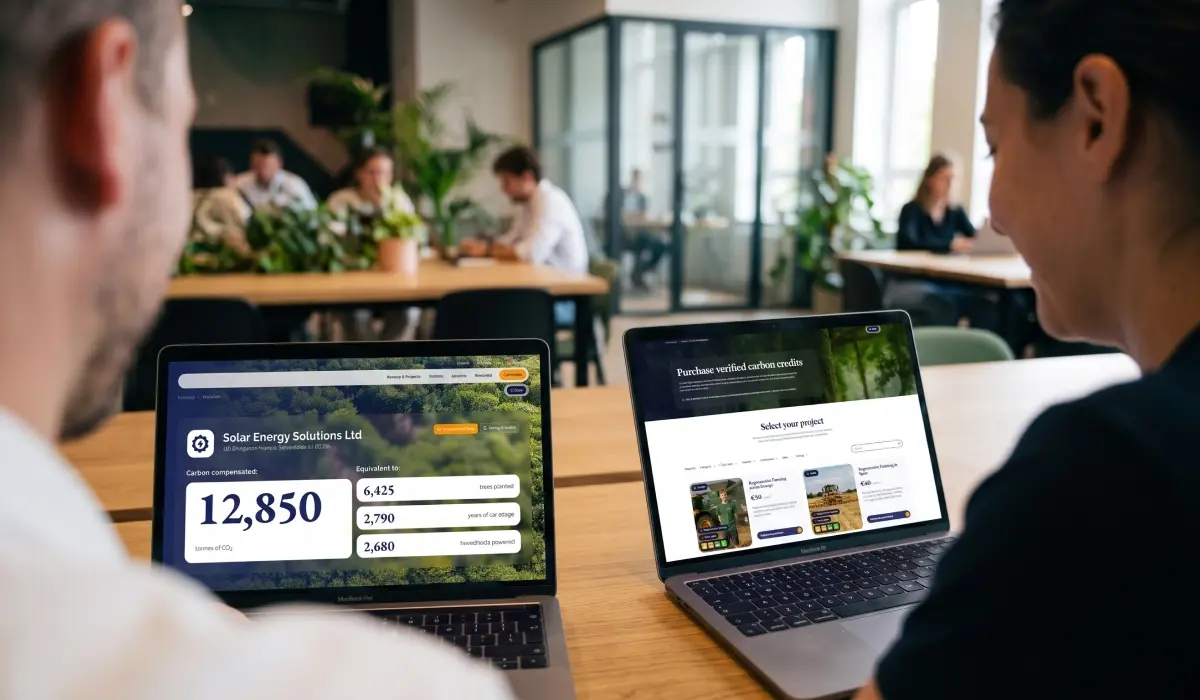
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits