

Logging companies have “acquired” roughly 1m hectares of Indigenous peoples’ territory in the Democratic Republic of the Congo since 2000, according to a new study.
This is part of a wider trend in which companies and governments take advantage of weak or unclear land rights to lease out swathes of communal land in the global south.
Many of these deals involve foreign companies using the land for logging, intensive agriculture, fossil-fuel extraction and mining. Increasingly, firms are also seeking land that they can use to sell carbon offsets.
The research, published in Land Use Policy, identifies around 18m hectares of land in Cambodia, Colombia and the DRC that have been acquired in large-scale deals.
Overall, around 6% of the acquired land overlaps with areas that are either legally recognised as belonging to local and Indigenous communities or, in the case of the DRC, are traditionally managed by Indigenous groups.
‘Vast land resources’
Large swathes of land in the global south have traditionally been managed by local communities and Indigenous people. However, their claims to these areas – their land tenure rights – have long been under threat.
Between the 15th and 20th centuries, European powers seized territory from many Indigenous people across the global south. During decolonisation, many of these “land grabs” were never reversed and much of the formerly communal land passed straight into the hands of newly created countries, particularly in parts of Africa and Asia.
There has been growing recognition of traditional ownership in recent years. Over 2015-20, 103m hectares of communal lands in 73 countries were given legal status, according to analysis by the Rights and Resources Initiative, a global coalition of groups that advocates for the rights of Indigenous peoples and local communities.
This brings the legal recognition of traditional ownership to around 1,265m hectares, or 19% of land in the countries assessed, as of 2020.
However, this legal recognition has frequently not stopped companies from entering these regions to harvest or extract a range of commodities, from palm oil and timber to copper and gold. The study authors say communal land is often viewed as an untapped resource, writing:
“The lack of private ownership and intensive production systems probably led to the notion that countries in the global south still harbour vast land resources suitable for commercial production.”
Officials in global-south nations lease out “vast tracts of land” to these companies – many of which are based overseas – without seeking communities’ consent or guaranteeing them benefits, the authors say. These rental agreements can last for several decades.
Study co-author Dr Christoph Kubitza, a research fellow at the German Institute for Global and Area Studies, says that even in nations where communal lands are legally recognised, such claims are sometimes poorly enforced by central governments. He tells Carbon Brief:
“You have some element in [national] legislation that speaks to communal lands, but implementation just does not work.”
In order to understand the scale of conflict between communal land rights and the transfer of land to companies, Kubitza and his colleagues merged data on the location of “large-scale land acquisitions” from the Land Matrix monitoring initiative with maps of communal land ownership assembled by LandMark and Open Development Cambodia.
(The definition of “large-scale land acquisition” varies, but Land Matrix broadly defines it as an attempt to buy, lease or otherwise acquire an area of land that is 200 hectares or more in size.)
They used data covering the period 2000-22 from Colombia, Cambodia and the DRC – three rainforest nations where governments provide varying levels of protection for communal lands.
‘Alarming’
The researchers identified 18.1m hectares of land that have been targeted for large-scale acquisitions in Cambodia, Colombia and the DRC since 2000.
The vast majority of this land – 14.2m hectares – is in the DRC, amounting to roughly 6% of the nation’s surface area.
In Cambodia, 2.3m hectares – roughly 13% of its land – has been involved in these deals, whereas in Colombia the figure is around 1.6m hectares, which is around 1% of its area. In total, most of the acquisitions in these three nations were by international companies.
The researchers also found that the DRC has the largest amount of communal lands under threat.
Of the 14.2m hectares targeted for large land acquisitions in the DRC, they estimate that roughly 1m hectares – 7% of the total – is land managed by Indigenous groups in the north and west of the country. These lands have predominantly been infringed by logging companies, with around 75% of these deals being struck with international entities.
The blue areas in the map below indicate Indigenous peoples’ lands and the green areas show the locations of large-scale land acquisitions in the DRC. Red indicates the areas where there is a risk of overlap between the two.

In Colombia and Cambodia, where there are more legal protections in place, the areas of communal land infringed upon are lower – 53,369 hectares and 43,150 hectares, respectively, the study says. This equates to 3% of the leased land in Colombia and 2% in Cambodia.
The authors highlight the situation in the DRC as particularly “alarming”.
However, they note that their finding of 1m hectares of overlap is only an estimate, based on the presence of Indigenous people in certain regions and extrapolations of total communal land use from detailed mapping in a smaller area. (For Colombia and Cambodia, the figures are based on legally defined communal lands.)
This is due to the lack of firm definitions of communal land in the DRC, as Kubitza explains:
“You don’t have exact numbers because if you don’t have any progressive legislation, you also don’t have a lot of mapping being done – so you have to rely on estimates.”
Dr Raymond Achu Samndong, a monitoring, evaluation and learning manager at the International Land and Forest Tenure Facility, who was not involved in the study, tells Carbon Brief that the 1m hectare figure could be an underestimate, given the size of the country and the problems it faces.
“Land grabbing is a growing phenomenon in the DRC,” he says, pointing to communities with whom he has worked where the government has allocated large tracts of land for concessions and the affected communities were not informed.
He adds that that the country’s inaccessibility makes monitoring and enforcing land rights difficult:
“You have statutory and customary law that conflicts in some areas where the government has limited access and control.”
In areas where customary local chiefs are essentially the land owners, they have also been known to participate in and profit from “land grabbing”, Samndong says.
Underestimates
The study highlights how the recognition of collective land ownership can help to insulate communities from “land grabs”. However, the researchers also acknowledge the limitations of such recognition.
As in much of Latin America, Colombia has provided clear recognition of communal rights, with roughly one-third of the nation’s land falling under Indigenous and Afro-Colombian control. Yet estimates suggest that up to 9.43m hectares of the nation’s communal lands are still not legally recognised.
In Cambodia, too, the study authors accept that their assessments of communal lands being encroached upon by business interests are likely to be underestimates.

A UN report in 2020 found that despite Cambodia being home to 455 Indigenous communities, only 30 Indigenous land titles had been handed out by the government.
Luciana Téllez Chávez, an environment researcher at Human Rights Watch who was not involved in the study, tells Carbon Brief that while the legislation exists to recognise communal ownership in Cambodia, “the implementation of that legislation is lagging and the process is onerous”. She adds:
“Any study that is only assessing overlap between formally recognised Indigenous territories and land acquisitions would be missing most of the picture, as most territories have not been formally recognised.”
The new paper notes this shortcoming. The researchers also use data on officially recognised Cambodian Indigenous groups and find that around one-third of them are based within the sites of large land acquisitions.
They note that while “more extensive and detailed data are missing”, the impact of land acquisitions on communal areas could be larger than their initial results suggest.
Kubitza and his colleagues highlight that frameworks for states and companies to guide their use of land already exist. They stress that global supply chain regulation – of the kind being rolled out for forest products in the EU – could help to protect communities from land grabs if properly enforced.
In the DRC, Samndong says there have been “baby steps” towards progress from the central government, with the development of a community forest law and a new land law in the works.
Carbon offsets
The study also highlights the mounting pressure placed on communal lands by foreign governments and companies seeking to meet their climate goals by purchasing carbon offsets from overseas.
Carbon offsetting involves an entity paying for emissions to be reduced somewhere else, for example by preserving trees that can absorb carbon dioxide (CO2), while it continues to produce its own emissions.
The researchers point to specific carbon-offsetting projects in Cambodia and the DRC that have infringed on forest communities. These communities often have little understanding of the projects and derive few, if any, benefits, the researchers say.
Téllez Chávez, whose own work has identified human-rights violations at a forest offsetting project in Cambodia, says the research is “right to note carbon-offsetting projects as a potentially important driver of large-scale land acquisitions”. The Cambodian government plans to expand offsetting projects across much of the country’s protected areas.
Kubitza says this trend does not sit well with a vision of a global “just transition”. He tells Carbon Brief:
“It cannot be that people who conserve forests for centuries don’t receive anything and investors just come in and make money with these kinds of business models.”


The post Loggers have ‘grabbed’ around 1m hectares of Indigenous land in DRC appeared first on Carbon Brief.
Loggers have ‘grabbed’ around 1m hectares of Indigenous land in DRC

Climate Change
Analysis: India’s power-sector emissions flat for two years due to clean-energy surge
A surge in clean energy has kept carbon dioxide (CO2) emissions in check across India’s power sector, with no growth from the first half of 2024 to the same period in 2026.
This guest post is by:
Lauri Myllyvirta, lead analyst at Centre for Research on Energy and Clean Air (CREA)
Anubha Aggarwal, India analyst at CREA
This is the first time in more than 50 years that there has been no growth in India’s coal power over a two-year period, even as electricity demand grew overall.
At the same time, both oil and gas consumption have fallen across the nation for two years in a row, helping alleviate the shock of the Hormuz crisis.
Nevertheless, the new six-monthly analysis for Carbon Brief shows that India’s emissions grew by 3.7% year-on-year in the first half of 2026, due to increases from steel, cement and other sectors.
Other key findings for the first half of 2026 include:
- India’s power-sector emissions flatlined at 2024 levels, after a 2.2% decline in the first half of 2025 and a 2.3% rise in the same period this year.
- Clean energy met all of the 7% rise in India’s electricity demand over the two years, adding 63 terawatt hours (TWh), equivalent to the total demand of Switzerland.
- India has added 77 gigawatts (GW) of solar in this two-year period, helping meet 60% of the rise in electricity demand overall.
- While fossil-fuel generation stagnated, generators added 8.5GW of new coal capacity, leading to fewer running hours and increased costs to electricity consumers.
- CO2 emissions from oil and gas fell by 7% year-on-year, extending a reduction that began in 2025, despite higher demand for road transport fuels.
- Steel and cement emissions grew by 8% year-on-year, reaching a 23% share of India’s total CO2 in the first half of 2026.
If the pace of India’s clean-energy expansion is to continue, it will need to upgrade its electricity grid, rapidly build out energy storage and boost the flexibility of coal power.
While clean-energy expansion is covering most or all of India’s power-demand growth, the fossil-fuel industry continues to pursue major capital investments.
This includes large amounts of new coal-power capacity, ambitious plans for the conversion of coal-to-chemicals and efforts to boost domestic coking coal production for the steel sector.
While CO2 output from the power sector is flat, with oil and gas in decline, India’s emissions still went up due to the contribution from industry.
India lags behind its competitors – including most large emerging economies – when it comes to electrifying its industrial sector.
Faster progress would enable clean electricity to substitute for fossil fuels in industry, as well as for power, offering the potential for India to cut its emissions overall.
Flatlining fossils
Last year, India’s CO2 emissions from fossil fuels and cement grew at their slowest pace in two decades, according to previous analysis for Carbon Brief.
This sharp slowdown was due to rapid clean-energy growth and flat oil demand, combined with rising emissions from steel and cement.
The first half of 2026 marks a continuation of these trends.
Most strikingly, the ongoing surge in clean-energy generation means that emissions have flatlined in India’s power sector for two years, as shown in the figure below.
Power-sector CO2 was the same in the first half of 2026 as two years earlier, with a small decline in 2025 having been reversed over the same period this year.
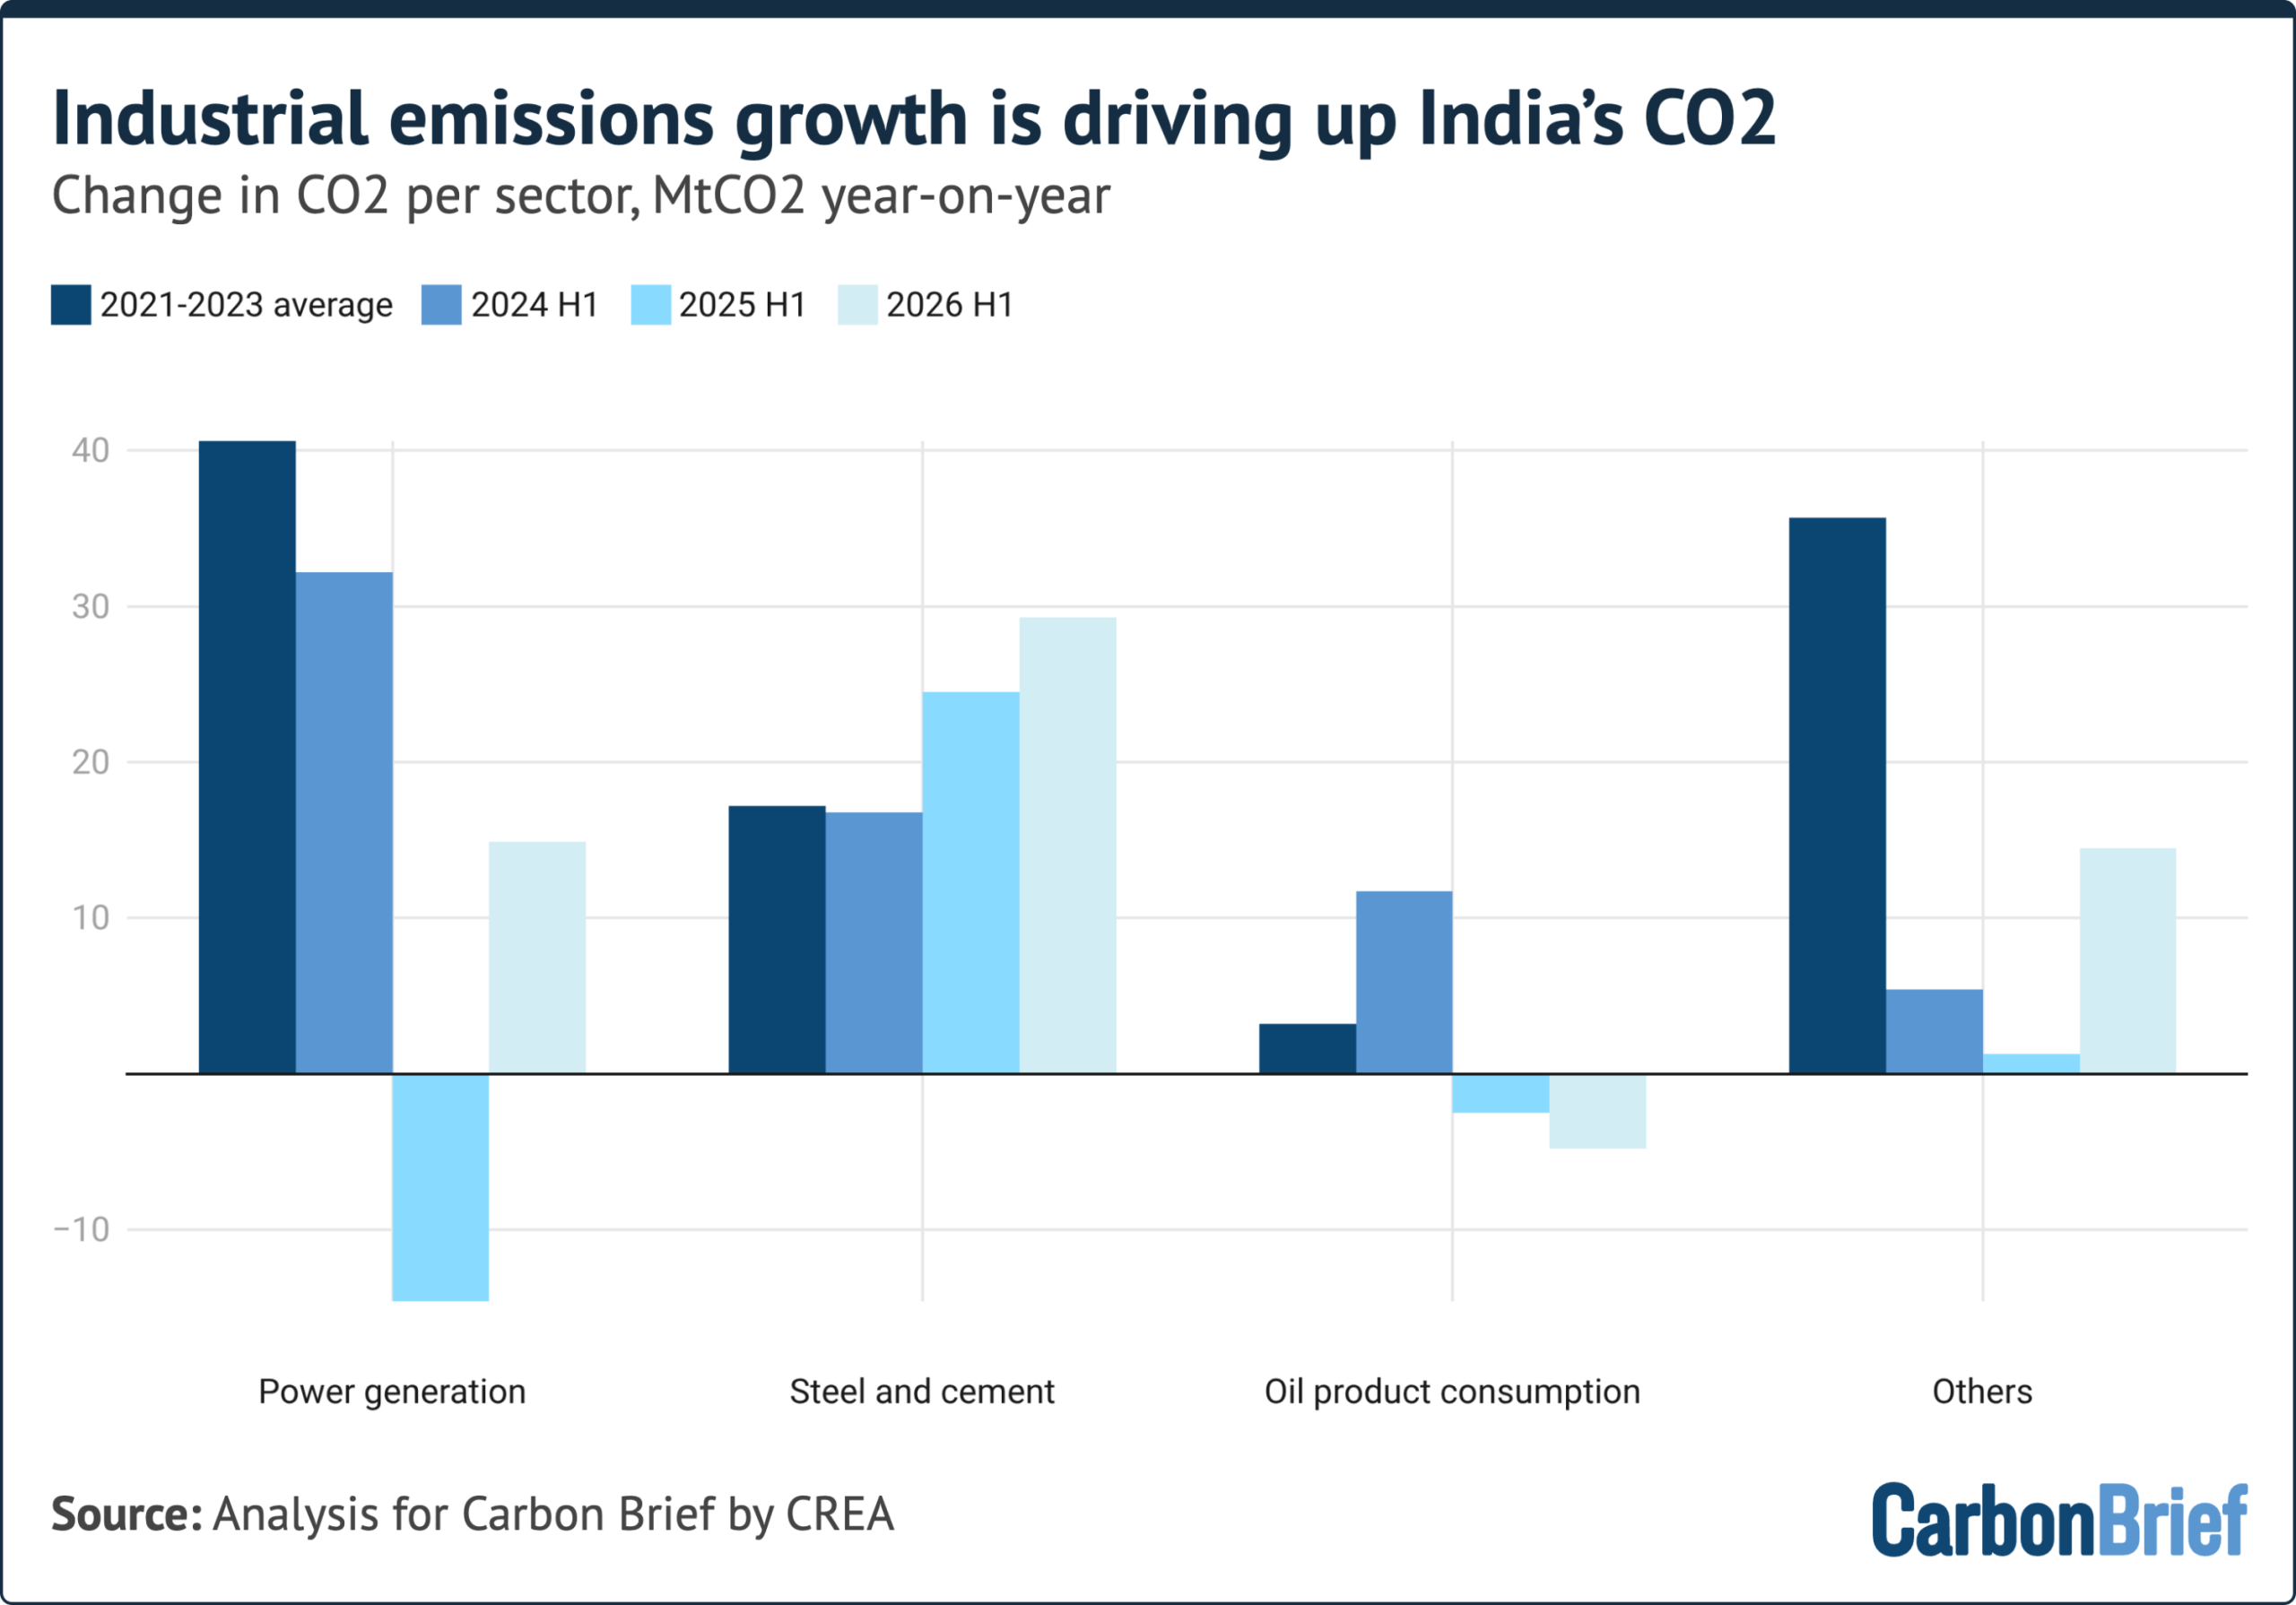
Beyond electricity generation, India’s key emitting sectors continued to see divergent trends in the first half of 2026, as some saw ongoing decline while others reached new heights.
This is shown in the figure below, which compares year-on-year changes in emissions during the first half of 2026 with the same periods in 2025, 2024 and the average for 2021-23.
Specifically, emissions grew by 2.3% in the power sector, reversing last year’s decline, while demand for gas and oil products fell for another year.
The biggest increases were for steel and cement, where emissions growth accelerated to 8% year-on-year in the first half of 2026, well above the recent trend.
Clean-energy growth matches power demand
The period from the first half of 2024 to the first half of 2026 saw the largest increase in non-fossil power generation on record in India.
This enabled fossil-fuel consumption and CO2 emissions from the sector to stay flat, even as electricity consumption increased.
Indeed, this is the first time in more than 50 years that there has been no growth in coal power over a two-year period, even as electricity demand grew overall, as shown below.
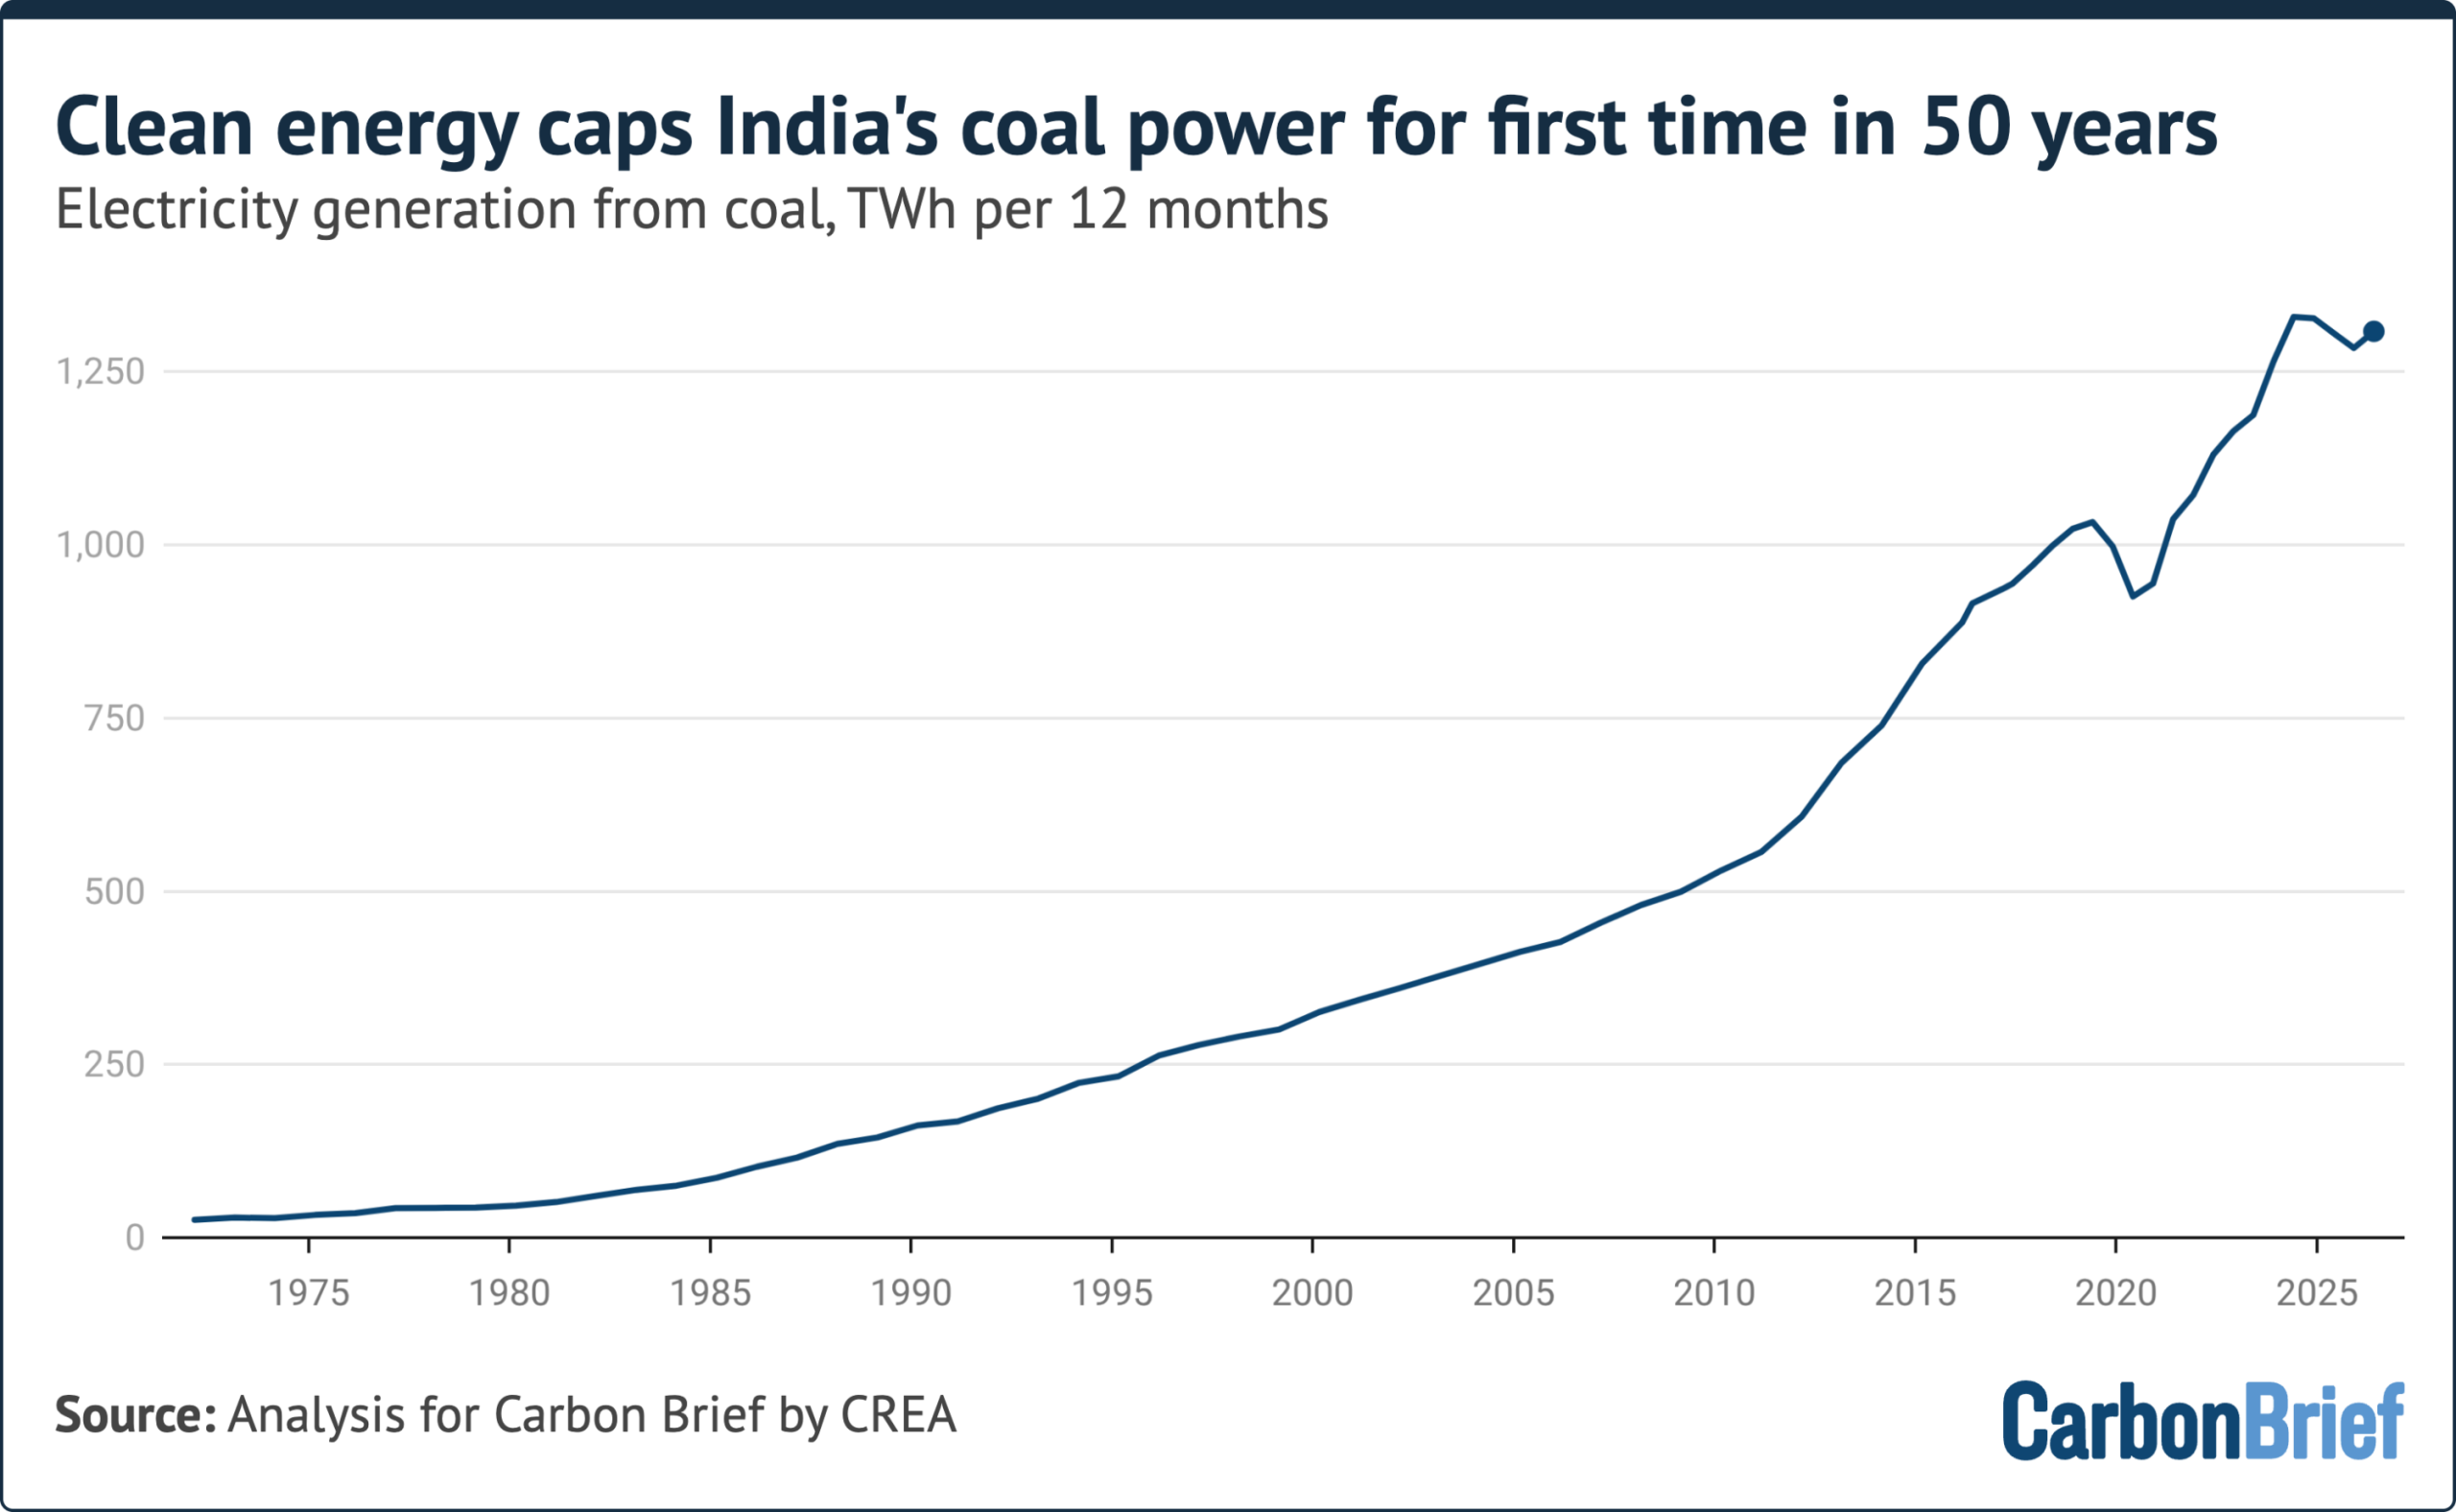
Over this two-year period, India’s total power generation increased by 7%, some 63TWh, equal to the total consumption of Singapore or Switzerland.
The additional power requirement of 63TWh was met entirely by clean energy. Solar grew by 44TWh, alongside growth from wind (13TWh), nuclear (7TWh) and hydro (8TWh).
Together, clean-energy sources added 70TWh over two years, more than the net increase in demand.
(For comparison, China’s nuclear, wind and solar output increased by 485TWh in 2025.)
The figure below shows that new investments are more than sufficient to maintain this trend, as added power generation from new clean power capacity has stayed above average demand growth for the past 18 months.
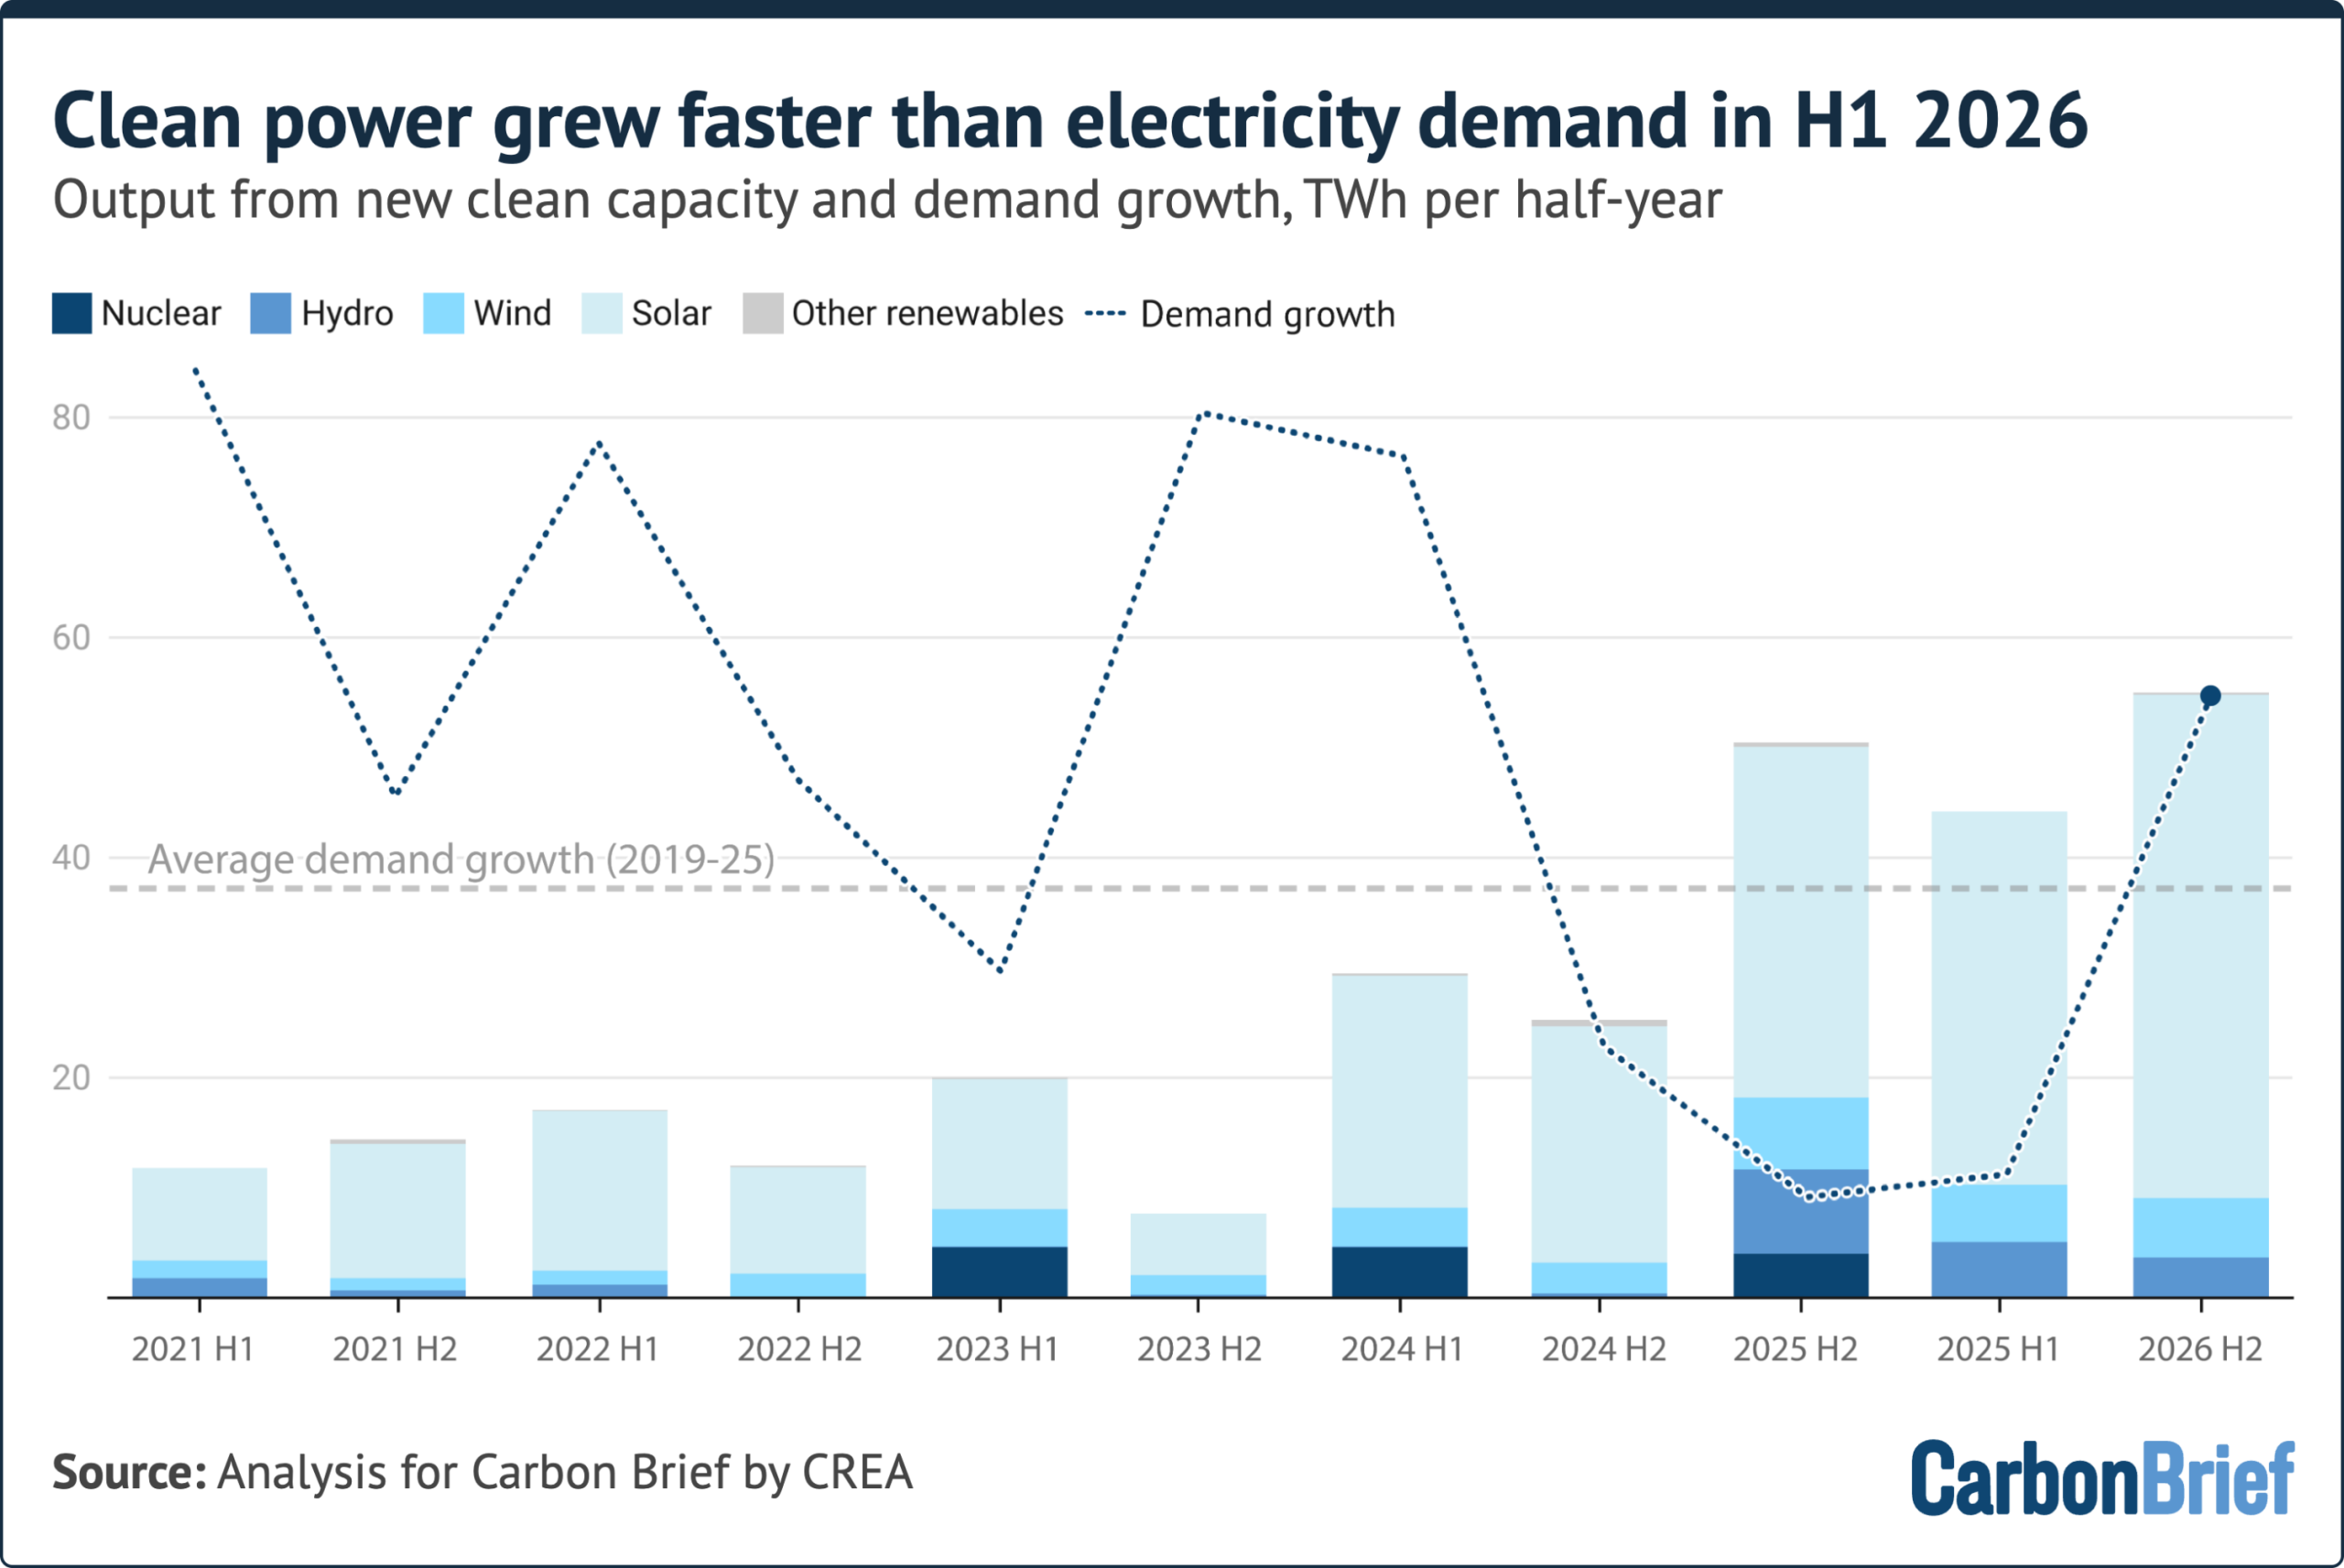
Over the past two years, India added 77GW of new solar capacity, 11GW of wind, 5GW of hydro and 0.6GW of nuclear capacity.
Solar power continues to dominate clean-energy growth, but, collectively, the other non-fossil sources still contributed 40% of the overall increase in generation.
One factor in electricity demand growth in 2026 is the El Niño, which delayed the monsoon and intensified heatwaves, driving up cooling demand.
India is accelerating investment in energy storage, which will support further growth in clean power. The National Electricity Plan projected a requirement of 82 gigawatt-hours (GWh) of energy storage capacity by 2026-27 and 411GWh by 2031-32.
As of May 2026, the government has issued tenders for around 272GWh of energy storage capacity, including 142GWh of pumped hydro and 133GWh of battery storage systems. Current capacity is 7.5GWh of battery storage and around 60GWh of pumped hydro.
Which states led the clean-power shift?
The fall in power generation from fossil fuels from the first half of 2024 to the same period in 2026 was concentrated in a few states.
Gujarat saw both the largest reduction in fossil-fuel generation and the largest expansion in clean power, as shown in the figure below.
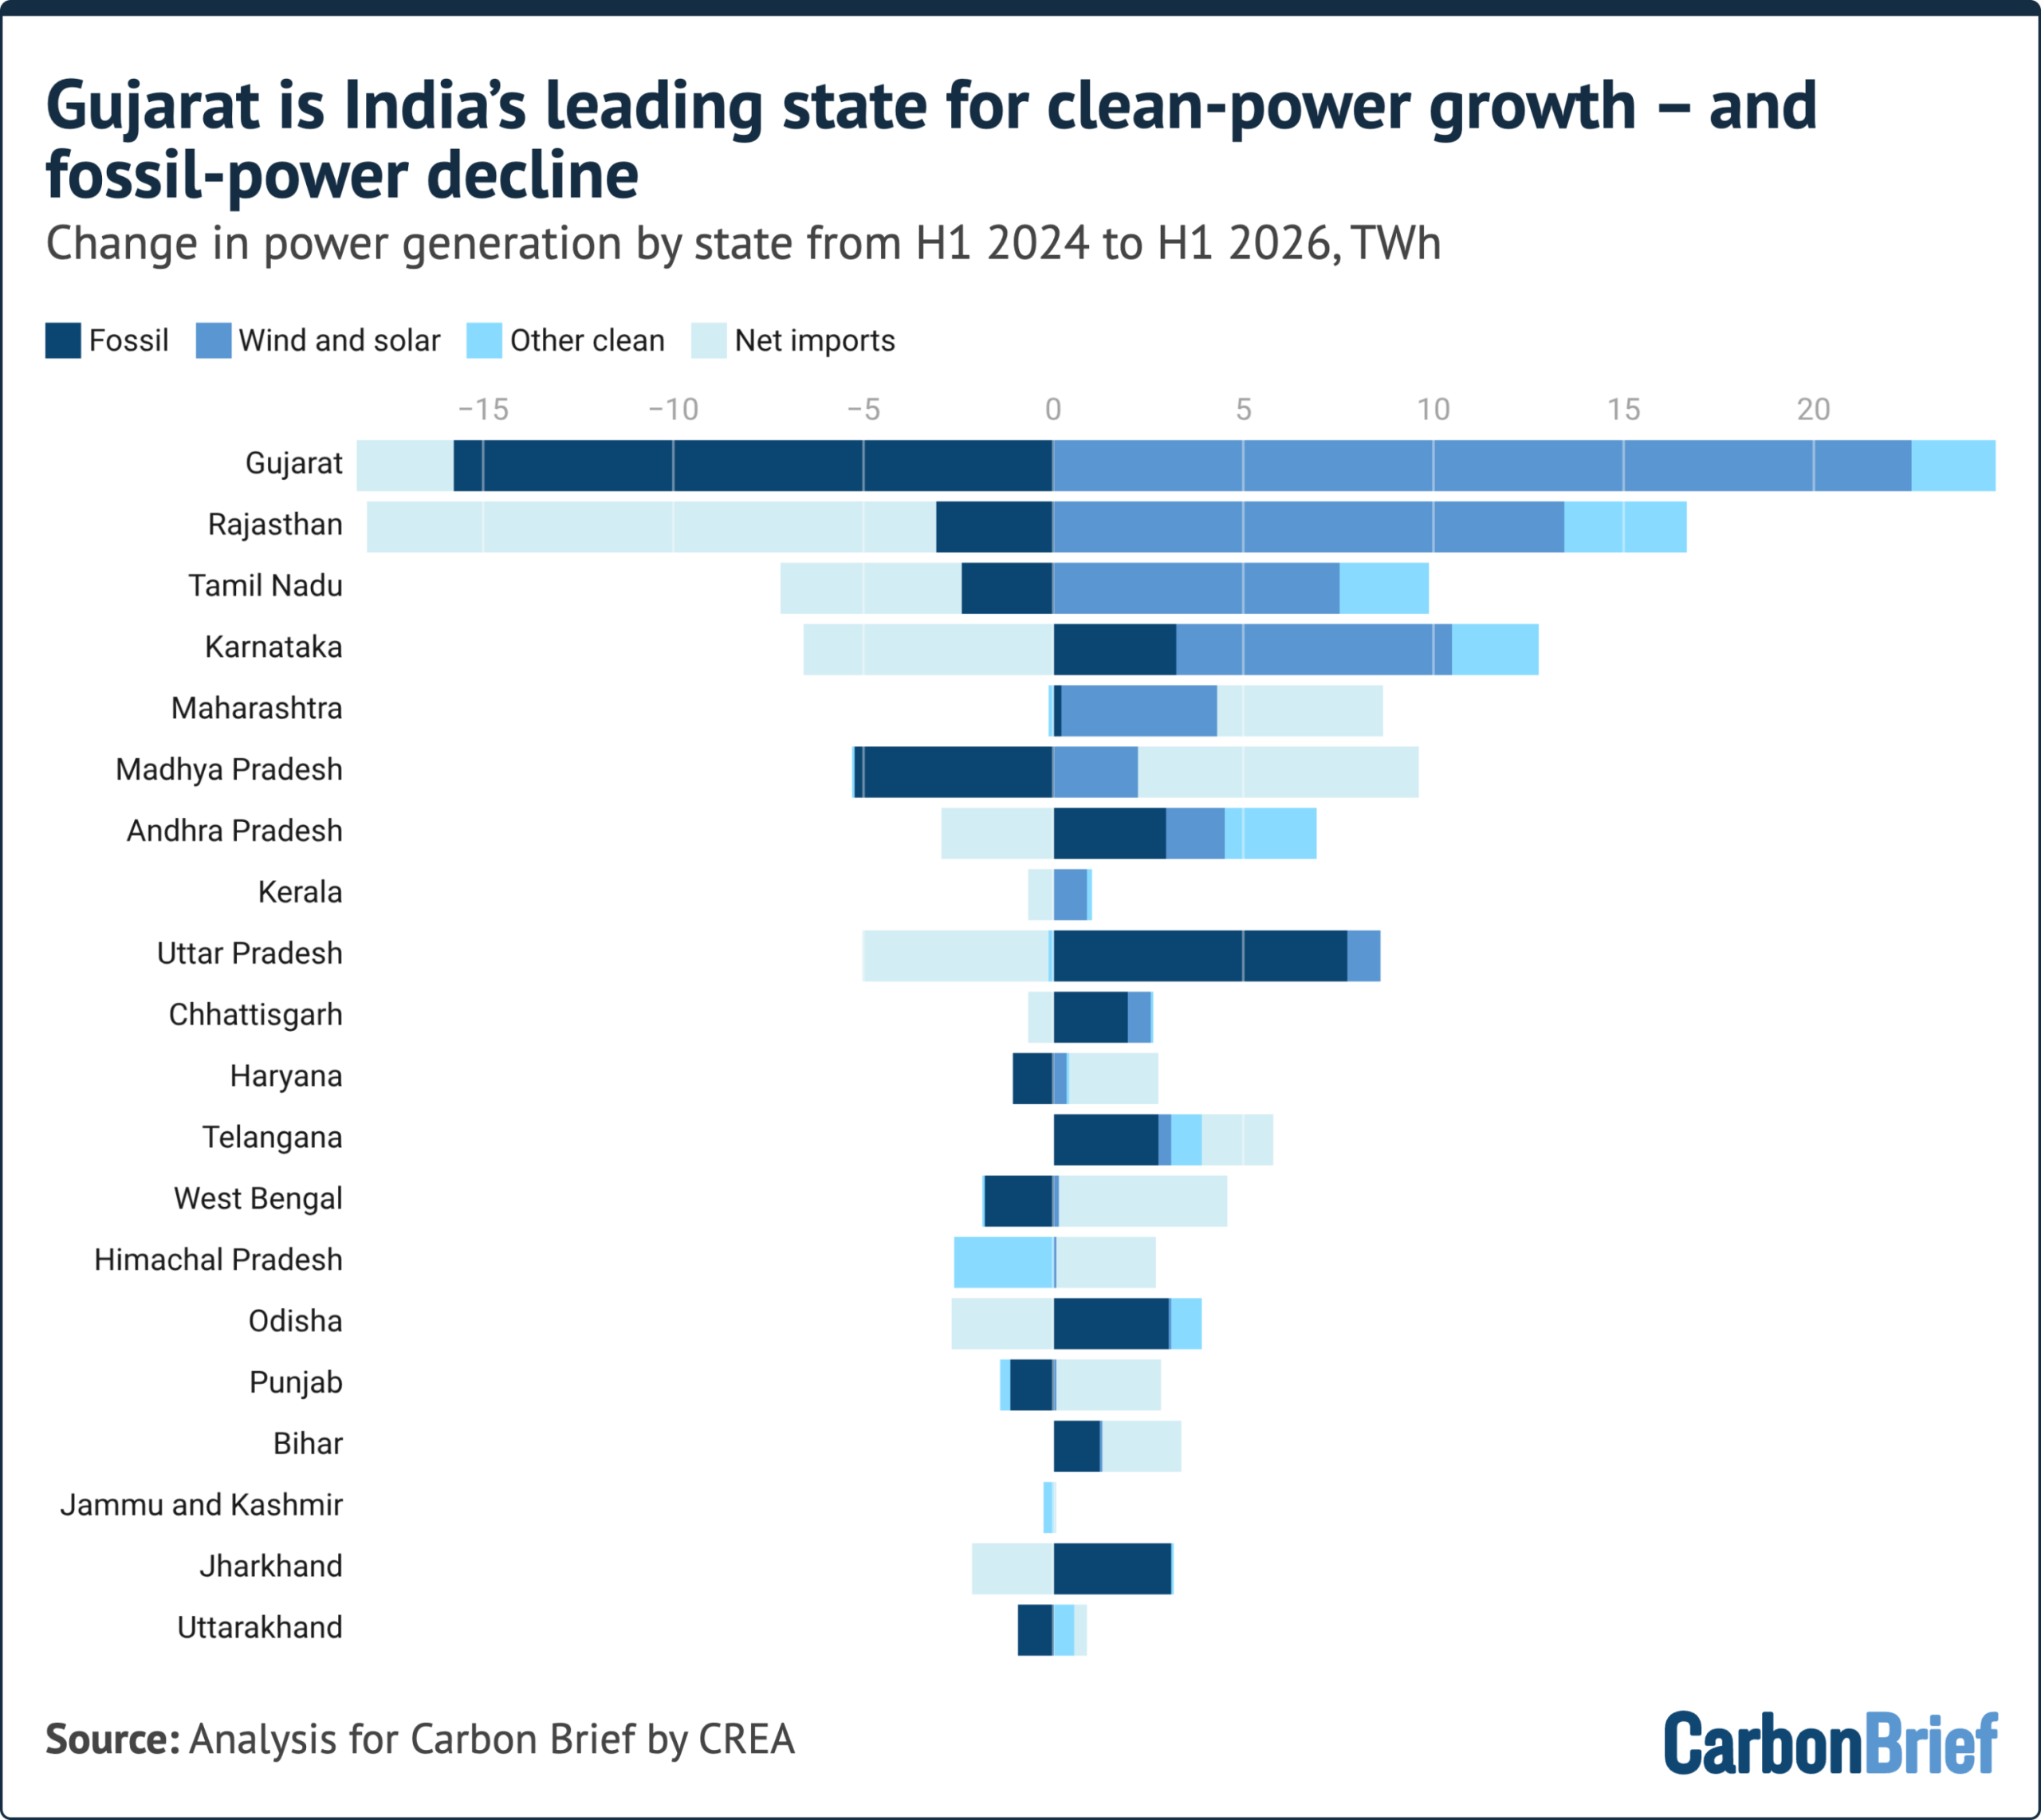
After Gujarat, the largest increases in clean-power generation were seen in Rajasthan and Tamil Nadu, which also saw reductions in power generation from fossil fuels.
Several other states saw declines in fossil-fuel generation due to higher net imports, rather than local clean power. These included Madhya Pradesh, West Bengal and Punjab.
Karnataka and Andhra Pradesh also succeeded in increasing clean-power generation faster than power demand, thereby contributing to keeping fossil fuel-based power generation stable nationwide across the two-year period. However, they exported much of the increase and consequently saw local increases in power generation from fossil fuels.
The two states with the largest increases in power demand, Maharashtra and Telangana, managed to almost match the rise with growth in clean-power generation.
Fall in oil and gas consumption continues
India’s oil consumption continued to fall during the first half of 2026, dropping 1.3% year-on-year, a slight acceleration from the 0.7% reduction in the same period last year.
While diesel and petrol consumption continued to grow, oil consumption was pulled down overall by declines in liquefied petroleum gas (LPG), petcoke (a solid derivative of oil used in the cement industry) and industrial feedstocks. Growth of aviation fuel use eased.
Diesel consumption growth accelerated from 1.8% to 4.1% in the first half of the year, supported by higher freight movement and increased agricultural demand, as the delayed monsoon led to greater use of diesel-powered irrigation.
Petrol consumption returned to growth, increasing 6.9% year-on-year after zero growth in the same period in 2025, reflecting sustained growth in passenger and two-wheeler mobility.
A significant increase in ethanol blending shaved a full percentage point off the growth of petrol consumption. India achieved its 20% ethanol blending target five years ahead of schedule in 2025-26. (Ethanol blending has faced public opposition.)
Electric vehicle (EV) adoption in India is also gaining momentum, with EVs adopted in a widening range of categories.
In Delhi, an EV policy was launched to accelerate electrification of the vehicle fleet, with a particular focus on two-wheelers, three-wheelers (auto rickshaws), commercial vehicles and high-mileage segments, alongside expanded charging infrastructure. Higher EV adoption rates will moderate the growth in emissions from petrol consumption in India.
In contrast, aviation fuel demand growth slowed down from 5% to 2%. The slowdown coincided with the strait of Hormuz and wider crisis, which disrupted international aviation through temporary airspace closures and flight cancellations to several Middle Eastern destinations. Elevated aviation fuel prices also increased airline operating costs, contributing to lower fuel demand.
LPG consumption contracted by 7%, after 5.7% growth in the same period last year, amid disruptions in global LPG markets following the Hormuz crisis.
Petcoke consumption fell 9.9%, more than reversing a 9.3% increase in the same period last year. Rising petcoke prices encouraged cement manufacturers to switch to coal.
Consumption of other petroleum products continued to drop, although the pace of decline moderated from 14% in 2025 to 9% in 2026.
Industrial feedstock use was affected by shortages and price increases.
Naphtha demand contracted as import prices nearly doubled and domestic prices increased by around 60%, prompting petrochemical manufacturers to reduce operating rates and suppress demand for imported naphtha.
Bitumen consumption remained subdued due to slower road construction, driven by persistent land acquisition challenges and higher bitumen costs.
Meanwhile, higher light diesel oil (LDO) prices and shortage of LPG led some industrial consumers to switch back to furnace oil in boilers and heaters, despite the higher air pollutant emissions. Supply of fuel oil to industry increased for the same reason.
Rapid emission growth from heavy industry continues
Steel and cement output in India grew by 8% and 9%, respectively, year-on-year in the first half of 2026, despite rising input prices and weakening profitability.
The growth in steel and cement was supported in part by increased investment in India’s real estate sector, especially in the second quarter. Steel consumption growth outpaced production, implying that inventories built up last year were tapped.
Despite domestic demand growth, profit margins of Indian steel and cement manufacturers remained under pressure for much of the period due to elevated raw material costs – particularly imported coking coal – and higher freight costs stemming from the Hormuz crisis.
The pressure on prices could dampen growth. Cement prices are expected to rise to levels last seen in the 2021-22 financial year, when Russia’s decision to cut back gas exports to Europe drove a sharp increase in fossil-fuel prices.
Outside the steel, cement and power sectors, coal-consumption growth accelerated to 14% in the first half of 2026, up from 3% last year, as the LPG shortage prompted a shift to coal.
Gas shortages resulted in some additional burning of coal for cooking in March and April. The government officially authorised the hospitality industry to use coal, refuse-derived fuel pellets, biomass and kerosene for one month.
The ceramic and tile industry also requested that the government allow the use of coal gasifiers amid the gas shortage. State governments including Delhi NCR, Rajasthan, Tamil Nadu, Gujarat and Maharashtra also allowed industries to temporarily use alternative fuels, including coal.
India’s industrial energy use is dominated by fossil fuels, particularly coal. Indian industry has the second-lowest electrification rate in the G20, as shown in the figure below. The share of electricity in total energy consumption in the sector also lags the world average, in terms of both current levels and the rate of increase.
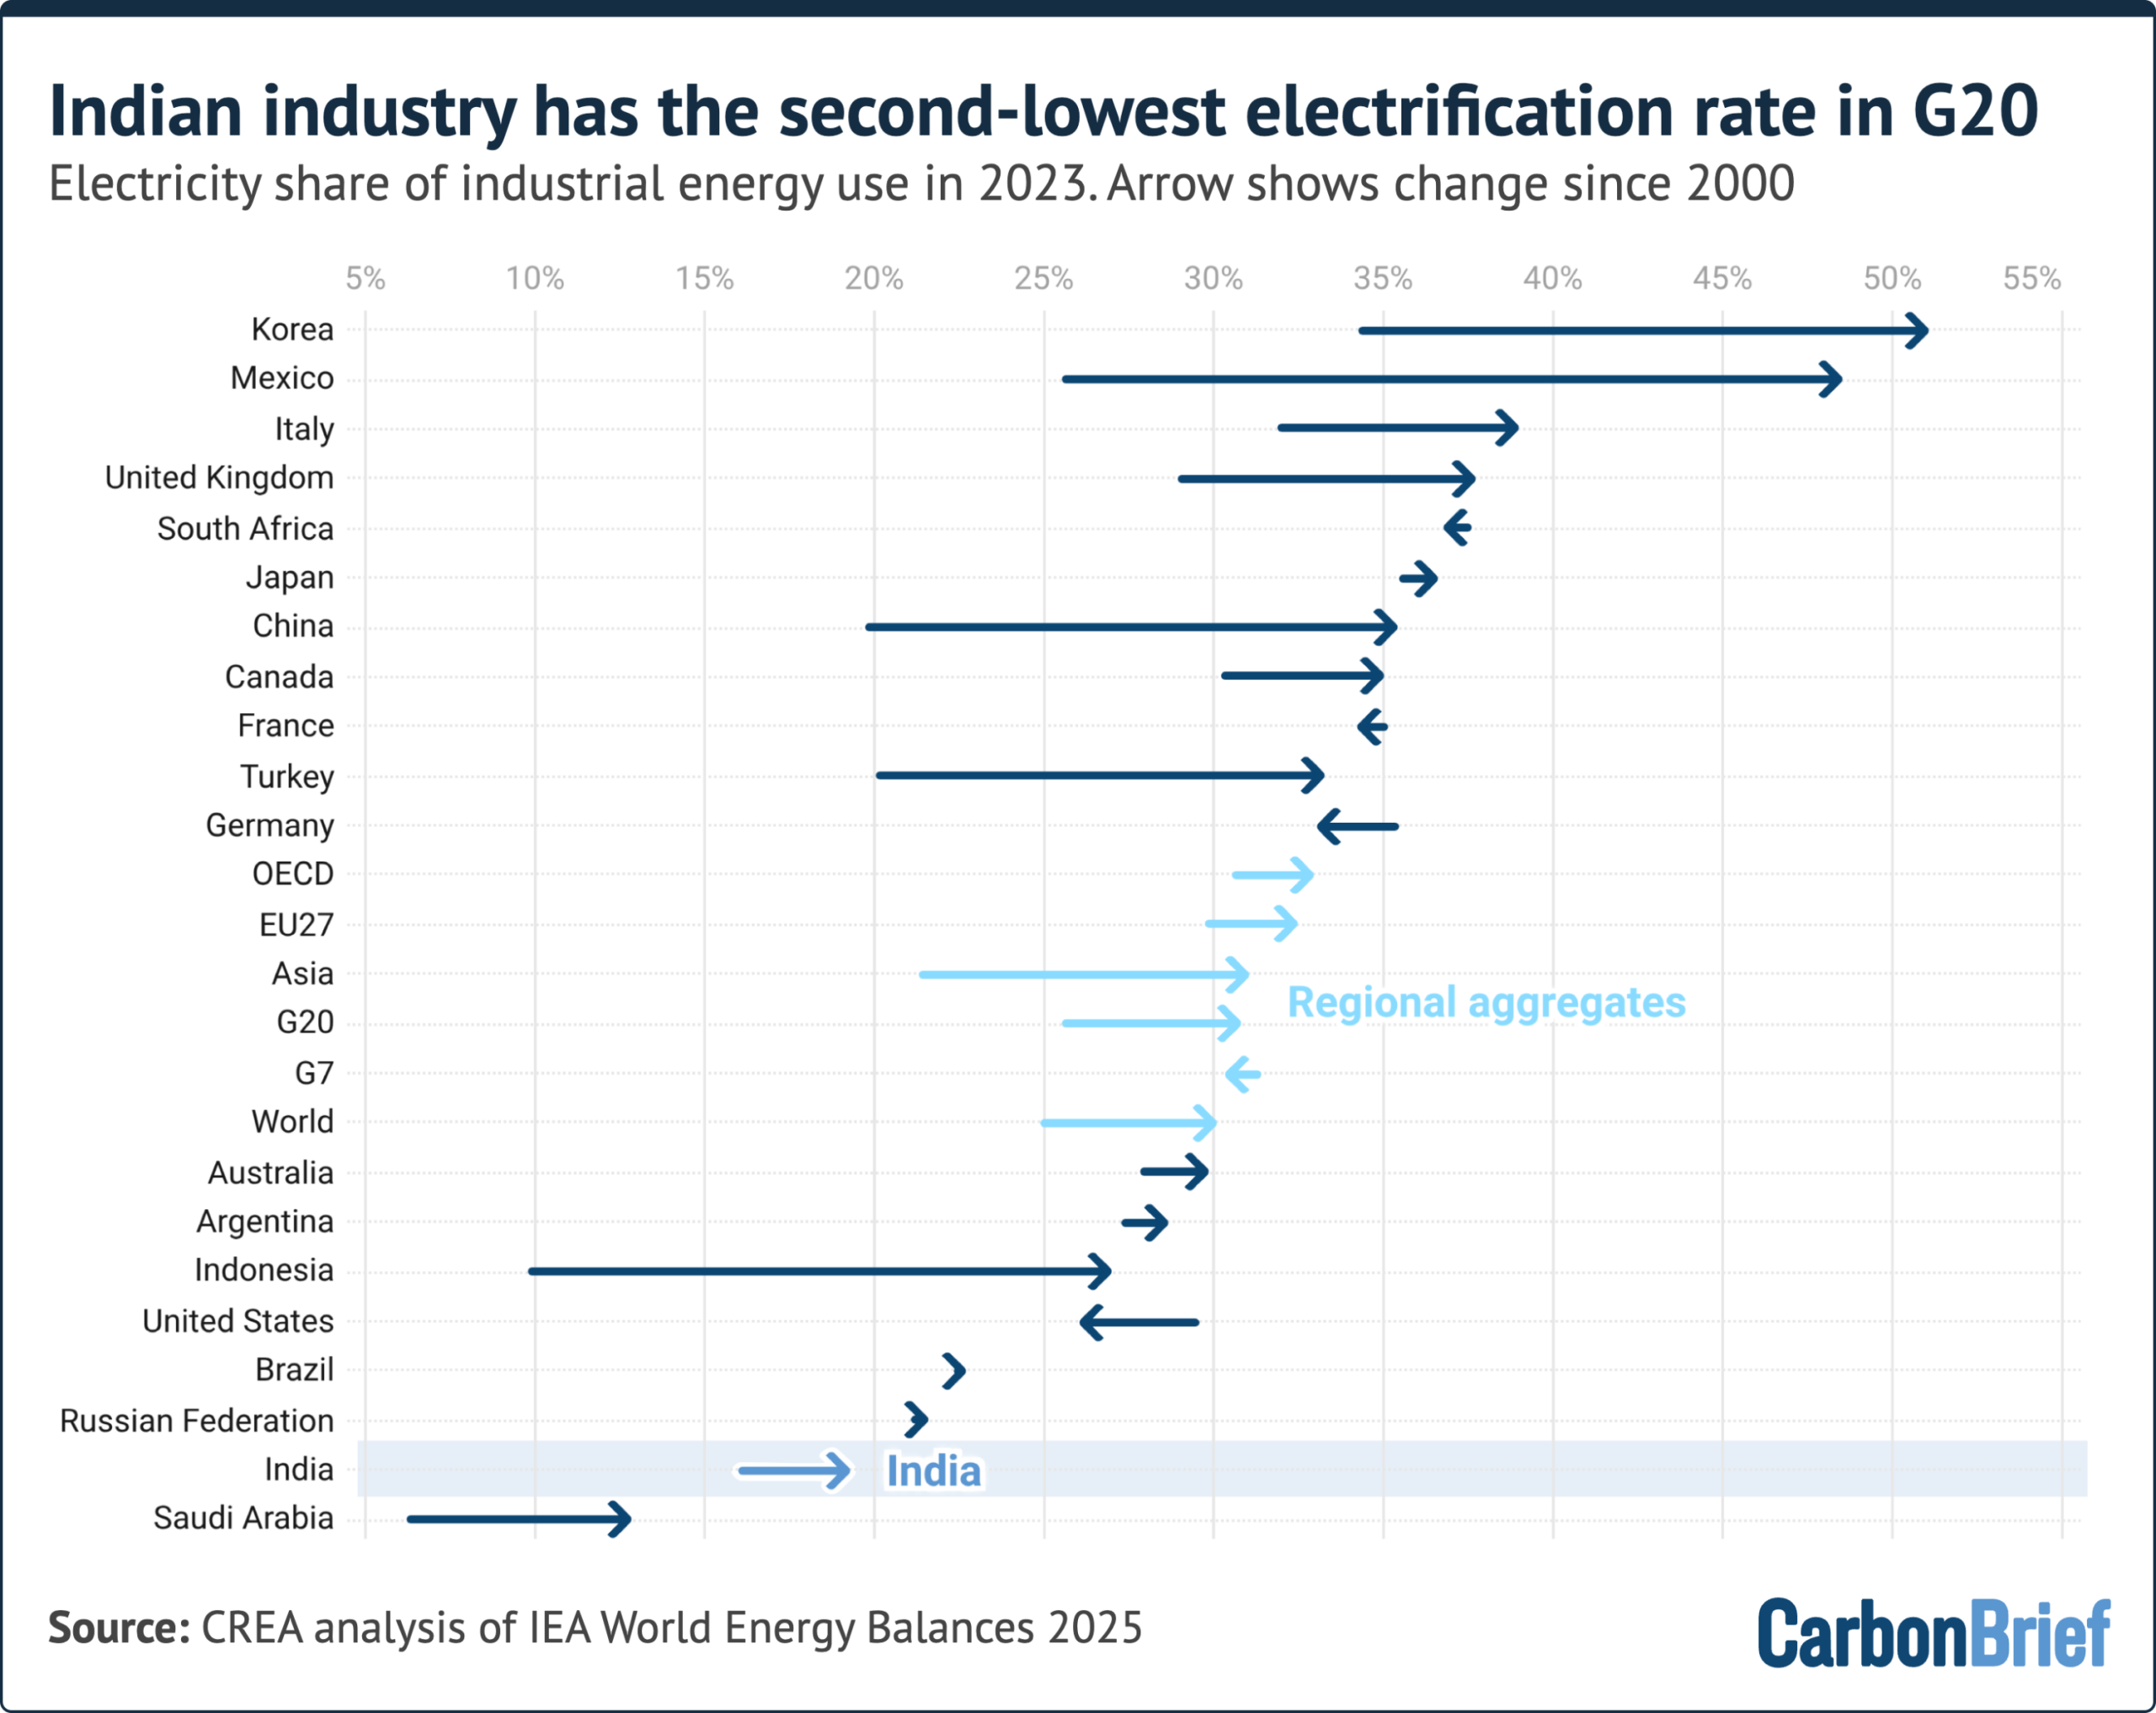
The current low rates of electricity use in Indian industry imply that there is major potential for electrification, using technologies and processes already in place in other countries.
New investments in coal
While the clean-power expansion is starting to meet most or all of India’s electricity demand growth, there are still large investment plans across the coal supply chain.
Some 43GW of coal-power capacity was under construction at the end of June. Additional coal-power capacity is seen as necessary to meet increasing peak loads, even as solar power and energy storage are already playing a role in covering daytime and evening peak demand, respectively. The expansion of energy storage will increase this contribution.
Outside the power sector, India has major ambitions to produce chemical-industry products, such as fertiliser and plastic feedstock, from coal through coal gasification, in pursuit of energy security.
The government is targeting a capacity to process 100m tonnes of coal per year in the next four years, despite the technology for coal gasification still being nascent in India. At present, the only operational use of coal gasification is at Jindal Steel Limited, which is reportedly using syngas in its steel-making process.
Meanwhile, India plans to reduce its average CO2 emissions per tonne of steel by 25% by 2025-26, mainly by reducing the share of coal-based steelmaking.
At the same time, the government is aiming to increase the use of domestic coking coal, which it notified in January this year as a “critical and strategic mineral”. Coal miners and steel companies are reportedly planning to establish additional washeries for coking coal to make it suitable for blending with imported coal for use in steel production.
India is also looking to invest in new coal mines in the near future.
These continued investments in coal gasification, domestic coking coal and new coal mining capacity could lock in coal use across industry for several decades.
Outlook for India’s emissions
Over the two-year period from the first half of 2024 to the same period in 2026, India has achieved its largest clean-energy expansion on record.
As a result, power-demand growth has been met entirely by clean electricity and CO2 emissions in the sector have flatlined.
This expansion of clean energy also allowed a reduction in fossil-fuel imports for power generation, with the use of imported coal falling 38% and the use of gas by 35%, supporting the energy security aims of the government and reducing exposure to the Hormuz shock.
In order to keep the clean-energy growth going, India would need to overcome multiple obstacles, including expansion of the electricity transmission network, improvements in grid flexibility to accommodate variable renewables and the timely completion of new projects.
For example, renewable power projects totalling 5.3GW missed completion deadlines and are having to pay penalties to the grid operator in order to retain network access.
Curtailment has emerged as an issue, particularly for projects relying on interstate power transmission, pointing to the need to upgrade the network. (Curtailment refers to electricity generation that is “wasted” because it cannot be accommodated by the power network.)
Another obstacle to be overcome if clean energy is to keep growing will be making coal-power plants more flexible, so they can ramp down during high renewable output.
A flexibility plan for coal-power plants has been delayed by more than a year due to persistent regulatory bottlenecks, contributing to the curtailment of renewable energy.
Expanding energy storage has the potential to ease grid and flexibility constraints, while reducing or eliminating the need for adding thermal-power capacity to meet peak loads.
The Central Electricity Authority has proposed that, after June 2027, all new government-owned solar and wind projects would have “mandatory” two-hour battery storage. (This mirrors a policy that was in place in China until early 2025 and was subsequently scrapped, in favour of more market-based approaches.)
For oil and gas, India’s consumption has been flatlining for the past two years, after half a century of continuous growth that was only briefly interrupted by Covid-19.
This has reduced the impacts of the Hormuz crisis on the country’s trade balance, helping close the gap between supply and consumption. But it has entailed disruptive shifts in many oil-dependent sectors.
For example, high prices and fuel shortages due to the Hormuz crisis led state governments to reverse their orders banning the use of dirtier fuels such as fuel oil, kerosene and coal in industries and commercial establishments.
Meanwhile, EV adoption has also begun to influence oil consumption.
Despite the progress in the power sector and reductions in oil consumption, India’s total emissions went up over the past two years due to a major increase in industrial emissions.
Low levels of electricity use in industry mean that growing industrial output results in increasing direct fossil-fuel use and emissions.
Unless the rate of industrial electrification picks up, increases in heavy industry output will continue to translate into increases in fossil-fuel consumption and CO2 emissions.
About the data
This analysis is based on official monthly data for fuel consumption, industrial production and power generation from different ministries and government institutes.
Coal-power emissions are estimated by combining plant-level coal consumption from the Central Electricity Authority’s (CEA) monthly coal reports with data on the calorific value and emission factors of coal used at different power plants from the CEA’s CO2 baseline database.
For each station and month, total coal consumption is split into domestic and imported coal using the imported share of coal receipts over a trailing two-month window, found to best reproduce the actual split in data available for 2023.
Consumption is converted to CO2 using each plant’s station-specific gross calorific value from the CEA database and IPCC emission factors for domestic coal, imported coal and lignite. The national-average calorific value is used for recently added plants, for which data is not available in the baseline database.
Coal use at steel and cement plants, as well as process emissions from cement production, are estimated using production indices from the index of eight core industries released monthly by the Office of Economic Adviser, assuming that changes in total fossil-fuel use follow production volumes. These production indices were used to scale fuel use by the sectors in 2022.
To form a basis for using the indices, monthly coal-consumption data for 2022 was constructed for the sectors by combining the annual total coal and petcoke consumption reported in IEA World Energy Balances with monthly production data. This work was set out in a paper by Robbie Andrew, a researcher at Norwegian research institute CICERO, on monthly CO2 emission accounting for India. Monthly petcoke consumption was available from the Petroleum Planning and Analysis Cell, while coal consumption by the cement industry was calculated by subtracting petcoke use from total fossil-fuel use.
Annual cement-process emissions up to 2025 were also taken from Andrew’s work and scaled using the production indices. This approach better approximated changes in energy use and emissions reported in the IEA World Energy Balances, than did the amounts of coal reported to have been dispatched to the sectors, showing that production volumes are the dominant driver of short-term changes in emissions.
For other sectors – including aluminium, auto, chemical and petrochemical, paper and plywood, pharmaceutical, graphite electrode, sugar, textile, mining, traders and others – coal consumption is estimated based on data on despatch of domestic and imported coal to end users from statistical reports and monthly reports by the Ministry of Coal, as consumption data is not available.
Coal consumption by “captive” coal-power plants – those supplying power to industrial sites, not to the public electricity network – was calculated based on capacity changes from Global Energy Monitor, assuming constant utilisation, as utilisation has been very stable year-to-year, as calculated from Central Electricity Authority data.
The difference between coal consumption and dispatch is stock changes, which are estimated by assuming that the changes in the amount of coal stored at end-user facilities mirror those at coal mines, with end-user inventories excluding power, steel and cement assumed to be 70% of those at coal mines, based on comparisons between our data and the IEA World Energy Balances.
Stock changes at mines are estimated as the difference between production at and dispatch from coal mines, as reported by the Ministry of Coal.
Coal consumption is estimated in two ways for sectors beyond power, steel and cement. Consumption of domestic coal in these other sectors is taken from the monthly reports by the Ministry of Coal. Their consumption of imported coal is estimated from the total imports of thermal coal reported by consultancy Kpler, by subtracting demand for imports at coal-power plants. The basis for this assumption is that steel and cement industries use little imported thermal coal, according to Ministry of Coal data.
Product-by-product consumption data for petroleum products, as well as gas use by sector, is from the Petroleum Planning and Analysis Cell of the Ministry of Petroleum and Natural Gas.
As the fuel dispatch and consumption data is reported as physical volumes – such as tonnes or litres – calorific values are taken from IEA’s World Energy Balance and CO2 emission factors from 2006 IPCC Guidelines for National Greenhouse Gas Inventories.
The emissions factor for motor oil or petrol was updated, based on the blending percentage of ethanol each year. The ethanol-blending percentage is as reported by the Ministry of Petroleum and Natural Gas.
Calorific values are assigned separately to different fuel types, including domestic and imported coal, anthracite and coke, as well as to petrol, diesel and several other oil products.
related
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
UNEP: New country climate plans ‘barely move needle’ on expected warming
Analysis: India’s power-sector CO2 falls for only second time in half a century
World’s electricity supply close to ‘peak emissions’ due to growth of wind and solar
The post Analysis: India’s power-sector emissions flat for two years due to clean-energy surge appeared first on Carbon Brief.
Analysis: India’s power-sector emissions flat for two years due to clean-energy surge
There is very little authorities in Nepal could have done to prevent the deaths and devastation caused by the flash flood on its border with Tibet in late August, scientists with the World Weather Attribution (WWA) group have said.
Launching a study that highlighted the role of climate change in causing the glacial rock and ice collapse that triggered the Himalayan flood, WWA co-founder Friederike Otto told reporters that “no amount of local adaptation can fully shield vulnerable people downstream from this scale of destruction”.
The findings released on Thursday are likely to strengthen Nepal’s case for emergency support from the UN’s Fund for Responding to Loss and Damage. Its board members met informally on Wednesday to discuss whether to grant the country a maximum of $20 million towards its estimated $4.8 billion cost of recovery and reconstruction, but no decision has yet been taken.
Nepal’s foreign minister Shisir Khanal told Climate Home News last week that the destructive flood was “exactly the kind of climate-driven catastrophe the Fund was created to address”.
Hard to predict
The WWA study found that rock-ice avalanches are very hard to predict and that moving people out of areas vulnerable to such floods is difficult as their livelihoods revolve around the rivers along which the floods travel.
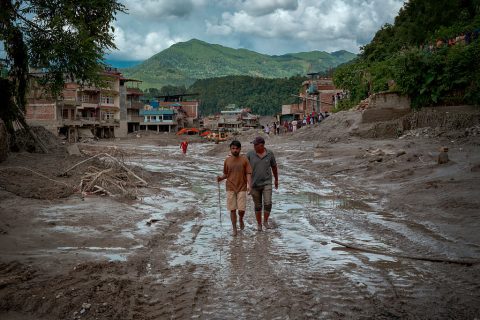
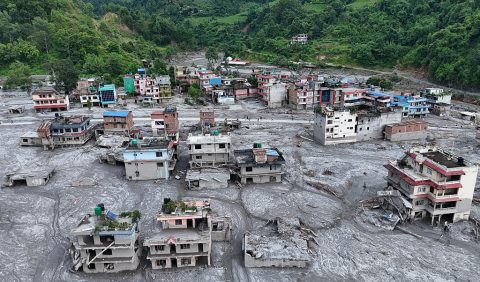
The recent disaster began on the morning of August 26, when an avalanche started falling beneath a glacier. This caused huge amounts of rocks and glacier ice to fall over a kilometre to a valley floor, where they then picked up more rock and ice and became a flood of debris heading downhill and downstream along the border of Nepal and Tibet.
The torrent entered the narrow Lhende Khola gorge and crashed through the busy Gyirong port border crossing at 170 kilometres an hour. It continued many kilometres downstream before eventually turning from rock and ice to water and slowing down.
The flood swept through villages, roads, bridges and hydropower stations, killing over 1,300 people in Nepal with more than 5,000 still missing. The flood also killed at least 40 people in Chinese-run Tibet.
Those on higher ground away from the river mainly survived but the flood’s speed meant that many people received no warning to seek higher ground or shelter.
While Nepal has early warning systems for flooding caused by rain and glacial lake outbursts, the WWA study noted that rock-ice avalanches are complex and understudied, with methods to monitor them still being explored.
Co-author Walter Immerzeel, mountain hydrology professor at Utrecht University, told journalists that with current methods, the disaster could not have been predicted.
But, he said, in the future it may be possible to use remote sensing techniques to analyse glaciers and rocks to generate a warning before a collapse occurs.
A technique called radar interferometry can detect hotspots which should be monitored with field-based sensors and drones, he said, adding that early warning systems could be installed in these areas using seismometers, water-level measurements and CCTV.
Because doing this for thousands of glaciers across the Himalayas would be difficult, authorities could monitor only the rock and ice faces that are a danger to the river valleys with the most people and infrastructure in them, he added. But this would still require lots of investment together with international collaboration and coordination, he warned.
The study found that another potential adaptation strategy – restricting development in flood-prone river valleys – is socially, economically and politically difficult.
The scientists said habitable land is scarce in these steep river valleys and economic activities like transport and hydropower generation are dependent on the river itself.
Madhab Uprety, a Nepali scientist from the Red Cross Red Crescent Climate Centre, said that, while new development should assess the risks of floods, many existing communities and buildings are already at risk.
Loss and damage
Otto said the flood should be discussed in the context of loss and damage as “there is no doubt that climate change is one of the drivers” and “it’s also one of the types of events that are absolutely outside of the limits we can possibly adapt to”.
As well as the deaths, a Nepali government’s assessment has found that a large amount of infrastructure was damaged, including more than 7,500 homes, 105 bridges, 48 public buildings, 47 cultural heritage assets, 18 schools, 13 hydropower facilities, seven health facilities, and numerous shops, hotels, restaurants, irrigation systems and farms. Over 30,000 people were affected.
Developing countries have called for the loss and damage fund’s board to hold an emergency meeting to discuss how to respond to Nepal’s request for funding. Instead of a full board meeting though, board members met only informally and online on Wednesday, Climate Home News understands. A source with knowledge of discussions said the informal nature of the meeting meant they were not able to take decisions or agree on next steps, which have been left up to the board’s co-chairs.
-
Foreign minister: Nepal needs “meaningful” international support to face climate threats
Following its recent Himalayan flooding disaster, the South Asian nation is seeking urgent help from a new UN climate fund, appealing for “stronger global solidarity” -
Loss and damage fund urged to hold crisis meeting on Nepal
The new fund is coming under pressure from developing nations to respond quickly to climate disasters rather than just financing longer-term projects -
Nepal’s EV revolution pays off as oil crisis causes pain at the pumps
Import subsidies, abundant hydropower and charging investments have spurred EV adoption, with electric vehicles now making up about three-quarters of new car sales

Speaking before that meeting started, Nepali climate negotiator Manjeet Dhakal said he had “heard of an extremely positive response” to Nepal’s request from board members. “Hopefully there will be something – a decision that the fund will do for exactly the reason that the fund was established,” he said.
Ajay Mathur, former Indian climate negotiator and now head of The Energy and Resources Institute in New Delhi, told a separate press briefing on Wednesday that the Nepal flood disaster would push loss and damage higher up the agenda of international climate talks, particularly if the United Nations Secretary-General decides to champion the cause at the UN General Assembly in New York next week.
Murat Kurum, Turkish environment minister and president-designate of COP31, told Climate Home News last week that he would be “pleased” if the fund could support Nepal and that he will keep calling in every speech for countries to give money to the loss and damage fund.
Jennifer Morgan, former German climate envoy and now a senior fellow at the Fletcher School of Law and Diplomacy, called for the loss and damage fund – which currently has around $630 million in contributions – to be topped up with new pledges from governments as well as solidarity levies on things like luxury air travel, super-rich individuals and fossil fuel firms’ windfall profits.
The post Nepal flood destruction shows “limits to adaptation”, scientists say appeared first on Climate Home News.
Nepal flood destruction shows “limits to adaptation”, scientists say
Global fossil-fuel emissions are set to fall by around 0.5% in 2026 amid the fallout from the Hormuz crisis, according to Carbon Brief analysis.
The US-Iran war has severely disrupted trade through the strait of Hormuz, causing a spike in oil and gas prices that continues to ripple around the global economy.
Each month of disruption – and each new flashpoint, such as in Yemen – is increasing the incentive to switch to alternatives.
Those alternatives include coal, with the latest forecasts pointing to a 1.2% rise in coal demand this year – apparently supporting media claims of a “return to coal” in the wake of the crisis.
Yet Carbon Brief’s analysis shows the rise in emissions associated with this increased coal use, much of which is unrelated to Hormuz, is set to be more than offset by declines for oil and gas.
The estimated overall impact on carbon dioxide (CO2) emissions from fossil fuels in 2026 is shown in the figure below and amounts to a reduction of around 0.5% from 2025 levels.
(Fossil fuels account for two-thirds of global greenhouse gas emissions.)
The emissions estimates for each fossil fuel are based on the latest forecasts from the International Energy Agency (IEA) for coal, oil and gas, in light of the ongoing global energy crisis.
For example, the agency initially estimated that global coal demand would decline this year. In its 2025 coal report, published in mid-December, it said that declining coal demand in China would outweigh the impact of pro-coal policies under US president Donald Trump.
In contrast, the latest update, published in September 2026, said that global coal demand would rise by 1.2% in 2026, instead of the small decline that had been expected.
The report highlighted the boost to coal demand from higher gas prices in the wake of Hormuz. However, there are limits to this, because few countries can switch from gas to coal at large scale.
The IEA’s latest report also noted the role of a strong El Niño, which is pushing up the need for cooling and depressing hydropower output in key markets. Other short-term factors are also affecting coal demand this year, including a rising amount of “wasted” wind and solar in China.
For gas, the IEA did not initially update its previous forecast that global gas demand would rise by 2.0% in 2026, which had been published in January of this year.
Its most recent forecast – published in July – already pointed to a 0.6% drop in demand in 2026. Since then, pressure on gas demand from high prices has only grown stronger.
For oil, there has been an even more dramatic shift in forecasts since the start of the year.
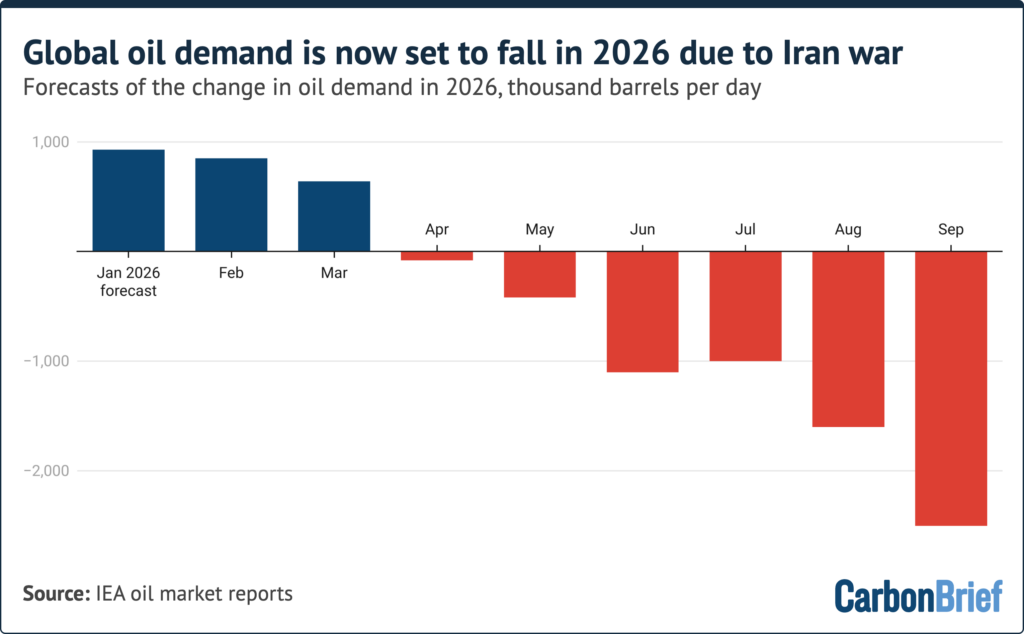
In its January 2026 oil market report, the IEA forecast a rise in demand in 2026 of 930,000 barrels per day (bpd). As shown in the figure below, this has been steadily revised downwards over the course of the year, as the Hormuz crisis was first ignited – and then extended.
By September, the IEA was forecasting a 2,500,000bpd drop in oil demand in 2026, equivalent to a reduction of 2.4% from 2025 levels.
(A 15 September research note from Morgan Stanley, not available online, found a “consensus” forecast of a 2,415,000bpd drop in demand in 2026.)
While there are many short-term factors at play in the shifting forecasts for 2026, it is clear that the latest energy crisis will also affect fossil-fuel demand in the next year and beyond.
For example, whereas the IEA initially forecast that oil demand would rebound in 2027 to well above 2025 levels, it is now expecting use of the fuel to be effectively flat for two years.
This puts a question mark over its previous expectation – published in October last year – that global oil demand would not peak until as late as 2030.
“For every month the conflict lasts, the probability of permanent [oil] demand destruction increases,” wrote Sverre Alvik, vice president at consultancy DNV in a late August analysis.
As fuel prices have surged, electric vehicles (EVs) have captured record shares of major car markets, from Australia and China through to Europe, Indonesia and Thailand.
In July, EV sales nearly doubled year-on-year in “new markets”, noted Alvik, pointing to countries outside China, Europe and North America.
The IEA says the 2027 outlooks for coal and gas are interdependent, with coal demand potentially increasing again if gas prices remain elevated – or dropping back if gas prices ease.
At the same time, governments in countries that had planned to rely on imports of liquefied natural gas (LNG) have been signalling shifts towards favouring domestic clean energy instead – or continuing to use coal for longer.
The current crisis, therefore, has the potential to not only lower fossil-fuel use and emissions in the short term, but also on a more lasting basis.
Related
CCC: Heathrow expansion could push flights to ‘80% of UK emissions by 2050’
Analysis: China’s CO2 emissions fall in Q2 2026 due to plummeting oil use
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
Q&A: What do China’s provincial five-year plans say about climate and energy?
The post Analysis: Global fossil-fuel emissions set to fall in 2026 amid Hormuz crisis appeared first on Carbon Brief.
Analysis: Global fossil-fuel emissions set to fall in 2026 amid Hormuz crisis



-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits