


The U.S. Bureau of Land Management (BLM), under President Biden’s administration, has nearly completed the regulatory process for Ioneer’s Rhyolite Ridge lithium project in Nevada, one of the largest lithium sources in the U.S.
BLM’s decision follows a six-year review aimed at boosting U.S. critical mineral production and reducing China’s dominance in battery metals. Once fully approved, the mine will become a key supplier of lithium for the U.S. electric vehicle (EV) market, with the capacity to power up to 370,000 EVs annually.
Rhyolite Ridge is one of two advanced lithium projects in the U.S. and is fully funded for a Final Investment Decision. It is expected to be a low-cost lithium site due to its valuable boron co-product and innovative cost-saving measures in its sustainable operations. Subsequently, it will produce lithium carbonate by processing materials on-site rather than shipping them elsewhere. This approach is crucial for the EV battery supply chain.
LATEST: EIA Expects Explosive Growth in U.S. Battery Storage—Can America Ascend to Dominance?
The proposed Rhyolite Ridge lithium mine by Ioneer has sparked a heated debate. While it promises economic and environmental benefits through the production of critical battery metals, it also threatens a rare plant species, Tiehm’s buckwheat. This is why conservationists and mining advocates are locked in a tug-of-war over the project’s future.
The Economic Promise
Proponents of the Rhyolite Ridge mine argue that the project is vital for U.S. energy independence and the growth of the electric vehicle market. As one of the largest lithium mines in the U.S., it could support the production of a massive number of EVs each year. Simply put, the Nevada lithium project is a major step forward to reduce carbon emissions and shift to clean energy.
Ioneer’s Chairman, James Calaway, highlighted the project’s potential contribution to the clean energy transition, stating,
“We can protect the flower and still produce the critical minerals needed for EV batteries.”

Source: Ioneer
The Environmental Challenge
Conservationists, however, have raised concerns about the mine’s environmental impact. The endangered Tiehm’s buckwheat flower, which grows only in the region near the mine site, has become a symbol of this fight. The flower was discovered in the 1980s and is found on federal land near the Nevada-California border. Environmental groups claim that the mine’s operations will endanger the fragile plant, pushing it closer to extinction.
In 2020, more than 17,000 rare flowers mysteriously died near the proposed mine site. Conservationists accused Ioneer of intentionally destroying the plants, but the company denied the allegations. Surprisingly, the U.S. Fish and Wildlife Service (FWS) later attributed the deaths to thirsty squirrels. However, environmentalists successfully pushed for the flower to be listed as endangered under the Endangered Species Act.
The FWS responded by designating 910 acres near the mine as a protected area to preserve the flower’s habitat. While this move helps protect the species, it does not completely halt the mining project. The debate continues over whether these measures are enough to ensure the flower’s survival.
Can Conservation and Mining Coexist?
Ioneer firmly believes that it can protect Tiehm’s buckwheat without compromising the mine’s operations. The company has adjusted its plans to limit the impact on the flower’s habitat. In addition, Ioneer has proposed a propagation plan to grow and transplant the flowers nearby. Calaway insists that these measures will not affect the mine’s production and remains confident that the project can proceed sustainably.
Environmental groups, however, remain unconvinced. Patrick Donnelly from the Center for Biological Diversity argues that the mine’s plans still threaten the flower’s survival, stating,
“The mining company’s plans run afoul of the Endangered Species Act.”
Donnelly further added that the project would destroy much of the plant’s critical habitat. Critics emphasize the irreplaceable nature of Tiehm’s buckwheat and argue that no amount of mitigation can undo the damage.
As the project moves through its final stages of approval, the debate between economic progress and environmental preservation is far from over. The question remains: Can the U.S. secure its lithium supply without sacrificing its biodiversity?
BLM Director Tracy Stone-Manning has also assured,
“This environmental analysis is the product of the hard work of experts from multiple agencies, to ensure we protect species as we provide critical minerals to the nation. We’re steadfast in our commitment to be responsible stewards of our public lands as we deliver the promise of a clean energy economy.”
The Road Ahead for Ioneer’s Rhyolite Ridge Lithium Project
The Rhyolite Ridge lithium project, backed by BLM’s approval, still faces hurdles before moving forward. The next phase includes a public comment period and the release of a final environmental impact statement. After these steps, a decision on the mining permit is expected within 30 days.
This project reflects the challenge of balancing economic growth with environmental protection. The BLM, in coordination with state and tribal authorities, has worked to address concerns while ensuring the project supports the Biden administration’s clean energy goals. The U.S. government has increasingly focused on critical mineral production, aiming to boost domestic supply and reduce reliance on imports.
Rhyolite Ridge, along with the Thacker Pass project, is key to increasing lithium production for EV batteries and energy storage solutions in the U.S. Reuters reported that Ford and a joint venture between Toyota and Panasonic have already agreed to buy lithium from the mine. However, the ongoing debate around environmental impacts, including the preservation of the rare Tiehm’s buckwheat flower, underscores the tension between conservation and the push for a green economy.
Disclaimer: Research sources:
- BLM issues final analysis for proposed Rhyolite Ridge lithium mine in Nevada | Bureau of Land Management
- https://www.mining.com/us-closer-to-greenlighting-ioneers-nevada-lithium-mine/
The post Ioneer’s Nevada Lithium Mine Gets Regulatory Approval Amid the Endangered Buckwheat Flower Controversy appeared first on Carbon Credits.

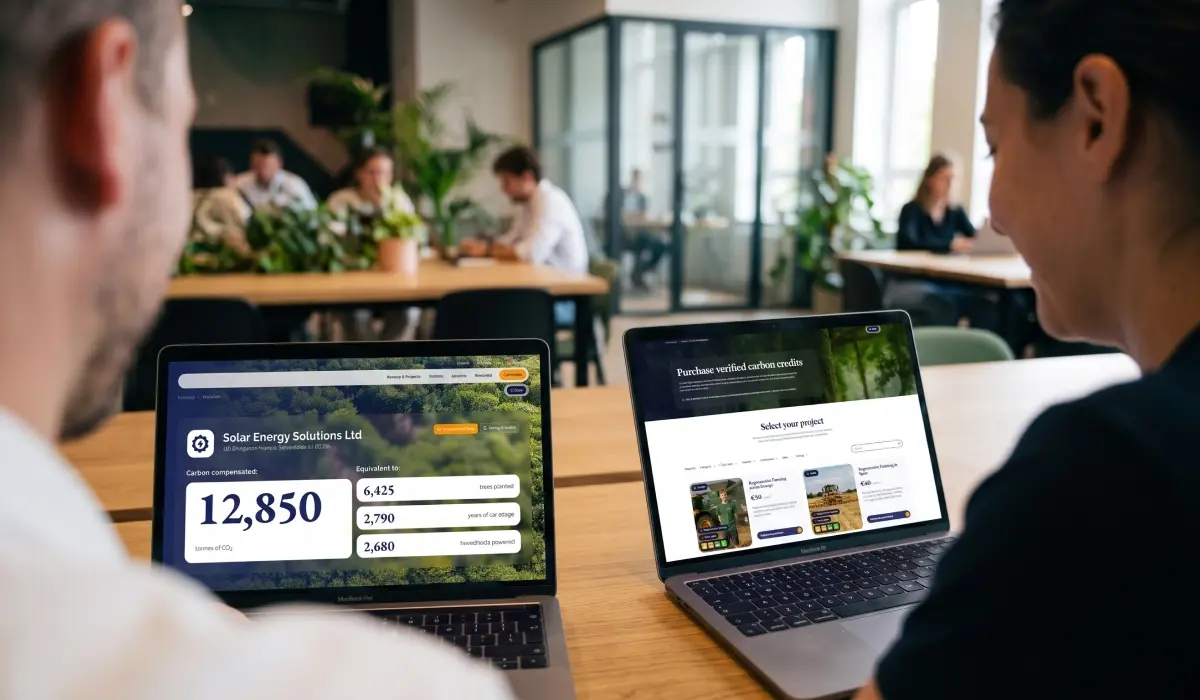
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits