


According to industry experts, the cobalt market is currently under pressure due to an oversupply and slow demand. The heat is palpable more on cobalt sulfate prices, which are gradually declining, indicating weaker demand. One reason is China’s passenger electric vehicle (PEV) sector, which strongly prefers lithium-iron-phosphate (LFP) batteries that do not rely on cobalt.
However, as revealed by S&P Global Commodity Insights, the Platts-assessed European cobalt price has held steady at approximately $11.00/lb since October 11, but with suppressed trading activity.
Let’s see what the report reveals further about the current and future cobalt market.
China’s Move to LFP Batteries Weakens Cobalt Market
The report revolved around the cobalt market in China. It highlighted that China’s cobalt metal price stabilized after hitting a low in late September. From September 25 to November 21, the price rose by 5.6% and increased another 2.0% month to November 21, despite some fluctuations.
This recovery was driven by stronger feedstock costs, as cobalt hydroxide prices remained more stable compared to refined cobalt products.

However, according to Shanghai Metals Market, margins for cobalt sulfate production using imported cobalt hydroxide turned negative in Q3 2023. This strained margin significantly impacted China’s cobalt sulfate output.
- From January to October 2023, combined production dropped by 28.1% compared to the same period last year.
The reason for the decline remains the same- a slowdown in the PEV sector. The other significant reason is automakers shifting to lithium-iron-phosphate (LFP) batteries as they are cost-effective and avoid using critical minerals like cobalt and nickel. This transition has reduced the demand for cobalt-containing batteries in China.
Additionally, S&P Global noted, that in October 2024, cobalt-containing batteries accounted for only 20.6% of vehicle installations in China. This figure is a steep drop from nearly 50% in 2021.
Unlocking Cobalt’s Role in Battery Chemistry
Cobalt remains a vital component in many battery chemistries, offering stability and safety benefits. In 2023, demand for cobalt-containing chemistries grew by 15% year-over-year (y/y) to approximately 500 GWh, accounting for 55% of total battery demand.
While this represents a decline from 63% in 2022, cobalt chemistries are expected to maintain a significant market share in the medium to long term as demand continues to grow. Let’s study how experts explain this evolving landscape…
A Shifting Landscape
Cobalt Institute’s latest report revealed that demand for cobalt was mainly driven by high and mid-nickel chemistries driving this growth in 2023. High-nickel chemistries saw a 32% increase, while mid-nickel grew by 15%. Meanwhile, low-nickel and lithium cobalt oxide (LCO) chemistries experienced declines of 11% and 13% y/y, respectively.
It further highlighted,
- Demand for cobalt-containing chemistries rose 15% y/y in 2023, to ~ 500
GWh. This equated to around 55% of battery demand in 2023, down from 63% in 2022.
High-nickel chemistries also increased their market share to 11%, while low-nickel chemistries fell behind nickel-cobalt aluminum oxide (NCA) chemistries for the first time.
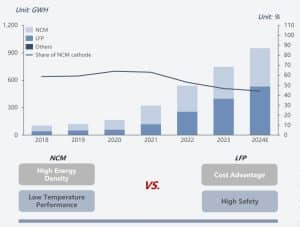
These cobalt-free chemistries now make up 45% of global cathode demand, driven largely by lithium iron phosphate (LFP) batteries. For the first time, LFP overtook nickel cobalt manganese (NCM) cathodes, claiming a 45% market share compared to NCM’s 43%. While manganese-based chemistries also contributed, their impact was minor.
Beyond batteries, cobalt is needed in aviation, energy storage, and electronics and its recyclability makes it sustainable.
Image: LFP vs. NCM: the share of NCM battery cells declines
Source: Cobalt Institute report
Pressures Facing Cobalt
Cobalt, despite its critical role in batteries, faces significant challenges in the supply chain related to cost, composition, and sourcing. Cobalt is costly, but falling prices have improved battery cell cost competitiveness.
The report highlighted that in 2023, NCM and LFP chemistries dominated the global lithium-ion battery market, making up 88% of cathode demand. Automakers in North America and Europe preferred NCM batteries for their higher energy density and longer range and they were mainly used in high-performance EVs.
On the other hand, LFP batteries have gained market share globally, particularly in China, where their lower cost and reduced reliance on critical minerals like cobalt make them a popular choice. This also means that although NCM chemistries have high energy density they are globally less widely adopted.
Image: 2023 Cathode active materials (CAM) product mix from the major ex. China CAM suppliers, %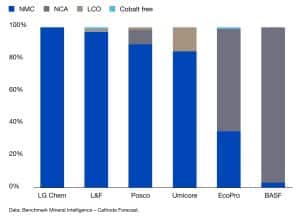
Additionally, ethical and environmental concerns regarding cobalt sourcing, particularly from the DRC and Indonesia are extensively scrutinized over its sustainability and responsible extraction practices.
Cobalt Forecast 2024: Price and Production
As cobalt demand continues to face challenges with automakers favoring lithium-iron-phosphate (LFP) batteries, cobalt-containing batteries are considerably losing market share. CMOC expects cobalt-containing batteries to eventually make up less than 10% of the total battery mix.
This declining demand is further reflected in price forecasts as rolled out by S&P Global Commodity Insights noted below:
- Analysts now estimate the cobalt market surplus will widen significantly in 2024, reaching 53,000 metric tons, which is more than 2X of its earlier predictions.
- The growing surplus has also led to a downward revision of cobalt price estimates, with prices now expected to fall to $12.72/lb by 2028.
Batteries now drive three-quarters of global cobalt demand, making the market highly sensitive to changes in cathode chemistries and technologies. As demand for EVs grows, cobalt’s role remains crucial, but the rise of alternatives like LFP will reshape the landscape.
The EV sector’s trajectory in key regions, including the US, China, and the EU, will play a critical role in shaping cobalt’s future. However, with battery technology shifting rapidly and economic policies uncertain, the path ahead remains unpredictable.
Supply Surge from CMOC, DRC, Australia, and Indonesia
The Democratic Republic of the Congo (DRC), Australia, and Indonesia are the three major countries that control about 73% of the world’s cobalt reserves. Last year, DRC topped the list, accounting for more than 70% of global production.
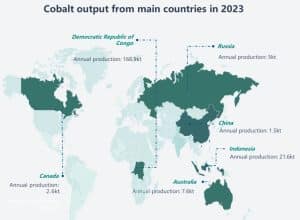 Source: Cobalt Institute
S&P Global forecasts that cobalt production is expected to soar in 2024. It will be significantly driven by Indonesia’s high-pressure acid leaching (HPAL) projects and surge in output from the DRC. Additionally, China’s CMOC, a major producer, has already surpassed its 2023 full-year cobalt production guidance by 21% within the first nine months.
In H1 2024, the company secured the position of the world’s largest cobalt producer with an impressive output of 54,024 tons, marking a staggering 178.22% year-over-year (YoY) growth. This surge not only reflects the company’s pivotal role in the global cobalt supply chain but also signifies a contribution to meet rising demand for battery-grade cobalt.
Notably, CMOC’s production surge is primarily linked to its copper-focused strategy that resulted in increased cobalt inventories.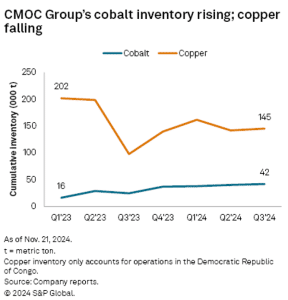
From this report, we can fairly infer that cobalt can still hold its ground as a key material in high-performance batteries, particularly in Western markets. However, its future will depend on balancing cost, sustainability, and evolving technology trends.
The post Cobalt at Crossroads: How Will Oversupply, Price Drops, and LFP Boom Impact Its Future? appeared first on Carbon Credits.

Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
CCC’s guide to finding nature-based solutions in your supply chain explains where to look. Here, the next task is to turn a broad concern into a testable proposal.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3 Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
Discuss a sourcing opportunity with CCC
Carbon Credit Capital’s nature-based supply-chain investment service uses its Dual-Value Model to examine supply-chain economics alongside potential sustainability outcomes.
Schedule a consultation to discuss your sourcing exposure and the questions to resolve before allocating capital.
Sources
- Intergovernmental Panel on Climate Change (IPCC), Climate Change 2022: Mitigation of Climate Change, Chapter 7, Agriculture, Forestry and Other Land Uses, section 7.4.3.3 (Agroforestry).
- World Business Council for Sustainable Development (WBCSD), Nature-based Solutions Blueprint, 5 June 2024.
- Science Based Targets initiative (SBTi), Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, section 3.1.4, pp. 37–38.
- United Nations Environment Programme (UNEP), State of Finance for Nature 2023, 2023.
A plastic credit funds the collection of plastic waste in places where no formal system exists to collect it. Each credit represents a measured, independently audited quantity of plastic taken out of the environment or returned to use, tracked on a public registry.

EU carbon credit claims changed on 27 September 2026, the day the Directive (EU) 2024/825 began to apply across the European Union. The change is narrow. It changes how a company can talk about the credits it buys. A product can no longer be called neutral on the strength of compensation alone; however, every specific, evidenced statement about what a company measured, reduced, and funded stays fully available.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19