

The bulk of steelmaking around the world still relies on coal-based blast furnaces.
As a result, the steel and iron industry is responsible for 7% of greenhouse gas emissions and 11% of carbon dioxide emissions globally, according to the consultancy firm Global Efficiency Intelligence.
This is more than the total emissions from all the world’s cars and vans.
With steel critical to the building out of decarbonised energy infrastructure, production is expected to continue to rise over the coming years, meaning the potential for decarbonisation is “enormous”, according to not-for-profit data organisation Global Energy Monitor (GEM).
GEM’s annual “Pedal to the Metal” report reveals that 93% of new steelmaking capacity announced thus far in 2024 promises to use lower emission electric arc furnaces (EAFs).
It also shows that 49% of the world’s steelmaking capacity under development now uses EAFs, up from just 43% in 2023 and 33% in 2022.
Of this, nearly all of the capacity announced since the beginning of 2024 operates using EAFs, the non-governmental organisation’s Global Steel Plant Tracker (GSPT) shows.
The tracker covers 2,207m tonnes per year (mtpa) of operating steelmaking capacity and an additional 774mtpa of steelmaking capacity under development globally, across 1,163 individual plants in 89 different countries, analysis of which is captured in its annual report.
However, while the report suggests a positive progression towards lower emission technologies in the sector, the increase in the announced projects is not yet leading to a construction of EAF overtaking coal-based production methods.
Coal-based blast furnace-basic oxygen furnaces (BF-BOFs) – where blast furnaces are used to produce iron from ore and oxygen converters then turn this, with some additional elements, into steel – continue to dominate the projects under construction, meaning “pressure must be maintained all the way through to project completion if real progress is to be seen”, the report finds.
Growth of EAFs
Incoming steelmaking capacity is more heavily EAF-based than ever before, according to GEM’s new report.
There is currently 774mtpa of steelmaking capacity under development, of which 223mtpa is in the advanced development stage.
Based on data from April 2024, the GSPT shows that nearly half of the capacity under development (337mtpa) is EAFs.
Just 36% of steelmaking capacity announced in 2020 with a known production route used EAFs, while in 2023 that number had increased to 92% according to GEM. This grows to 93% of capacity when looking at steelmaking capacity under development announced in 2024.
This “indicates a significant shift toward electric arc furnace steelmaking in the years to come”, the report notes.
Meanwhile, of the 212mtpa of steelmaking capacity slated for retirement, 88% if BOF-based.
However, a net increase in BOF-based capacity is expected over the coming years. If all planned developments and retirements take effect, an additional 171mptpa of BOFs is expected to be added to the global fleet, along with 310mtpa of EAF and 80mtpa of unknown technologies.
Despite this growth in BOFs, the surge of EAF means the steel sector is getting increasingly close to meeting the International Energy Agency’s (IEA) suggested 2030 target.
In its net-zero by 2050 roadmap, the IEA suggests that the share of steel produced by EAF should grow from 24% in 2020, to 37% by 2030 and then 52% by 2050.
Considering all planned capacity and retirements, GEM now estimates that the global steel fleet is expected to reach 36% EAF by 2030, noting: “This is still not sufficient to meet the IEA [net-zero] climate target, but with heightened momentum the goal is increasingly attainable.”

Continuing to construction
While EAF-steelmaking is being announced at “record rate”, GEM finds that less than 14% of this potential capacity has moved into construction.
Of those that have moved into construction, around 46% are still BOF-based. As such, “while we may be within reach of net-zero targets based on proposed electric arc furnace capacity, actually achieving these goals requires follow-through”, the report notes.
Caitlin Swalec, program director for heavy industry at GEM, said in a statement:
“The progress is promising for a green steel transition. Never before has this much lower-emissions steelmaking been in the pipeline. At the same time, the buildout of coal-based capacity is concerning. What the industry needs now is to make these clean development plans a reality, while backing away from coal-based developments.”
As well as the buildout of new coal-based capacity being out of alignment with a net-zero future, it poses a threat of carbon lock-in and stranded assets, GEM notes.
Blast furnaces are becoming riskier investments given the limited options to mitigate emissions from both the furnaces themselves and the upstream emissions from the metallurgical coal mining, it adds.
Estimating an investment of $1-1.5bn per mtpa capacity at an integrated BF-BOF site, GEM found that the future stranded-asset risk could be as high as $554bn in 2023, falling to $400bn in 2024 due to the continued fall in BOF capacity under development.
Astrid Grigsby-Schulte, project manager for steel at GEM tells Carbon Brief:
“As we grow closer to key decarbonisation milestones, coal-based developments get further out of alignment with the direction the industry is moving and present a greater risk of stranded assets to steelmakers. Coal-based, emissions-intensive blast furnaces represent significant investments that often require decades to recoup. This makes them extremely risky for developers, particularly in countries with stated net zero commitments.”

The limited options for mitigating the climate impact of BOF-steelmaking was also highlighted within a recent report from the thinktank Sandbag.
While carbon capture, utilisation and storage (CCUS) is often touted as a “catch all” solution, its effectiveness varies widely across applications, Sandbag’s “Steel & CCS/U” report finds.
For steel production, BF-BOFs with carbon capture are unlikely to be cost-competitive with EAFs, the report finds. Although given the slow pace of technological and market development, Sandbag anticipates capturing carbon will play a limited role in the steel industry.
China transitions to EAFs
India has now replaced China as the top steel developer globally, with a pipeline of 258mtpa of capacity, of which 177mtpa is BOFs, according to GEM.
China has a pipeline of 150mtpa meaning, collectively, China and India are responsible for 53% of all developments globally.
Asia operates 68% of all steelmaking capacity (1,508mtpa), the majority of which is in China (1,075mtpa), India (123mtpa) and Japan (109mtpa).
When looking specifically at emissions-intensive BOF production, Asia’s share of total operating capacity increases to 80% (1,181mtpa), of which 918mtpa is in China.
Currently, China has 157mtpa of operating EAFs (22% of the global capacity), followed by the US, Turkey, Iran and then India.
According to a new report from the Centre for Research on Energy and Clean Air (CREA), China did not issue any new permits for coal-based steelmaking in the first half of 2023. This is the first time this has happened since the nation’s “dual carbon goals” were announced in September 2020.
During the first six months of 2024, Chinese provincial governments permitted 7.1mtpa of steelmaking capacity, all of which were EAFs marking a “turning point” for the country’s steel industry, CREA notes.
Xinyi Shen, researcher at CREA and the report’s lead author, tells Carbon Brief: :
“China’s EAF steelmaking has been developing rather slowly in the past few decades, mainly due to the constraint of scrap supply. However, as China’s steel demand reaches its peak and more scrap becomes available, a major opportunity arises to reduce emissions in the next 10 years. The government has accelerated plans to expand the national ETS to include the steel sector by the second half of 2024. By implementing carbon pricing on carbon-intensive products, EAF steelmaking would become more economically competitive and continue the growth.”
Despite India now overtaking China in terms of announced steelmaking capacity, China remains the biggest developer of EAF capacity overall, GEM’s report states. And while India has the most steel in development, 84% has not moved into construction.
As such, there is still an opportunity for India’s plans to change, with the percentage of BOFs to EAFs less set.
Chris Bataille, adjunct research fellow at the Columbia University Center on Global Energy Policy and lead author at the global Net Zero Steel project tells Carbon Brief:
“India’s core demand for steel is set to increase from 125mtpa to ~450mtpa by 2050, especially to meet key building and infrastructure needs. Our modelling suggests EAFs consistently rise from ~35 to 150mtpa by 2050. So the +250mtpa BF-BOFs is just barely feasible, but only over ~25 years and with some exports of BF-BOF steel.
“The difference will be between a world where strong climate policy succeeds and fails. If it fails and coal based BF-BOFs are built, then the +258mtpa looks barely feasible. If it succeeds, India is short on the necessary gas and especially clean electricity to power this amount of steel production. While the country does build a lot of EAFs, it builds up to 250mtpa of clean iron making over time, making the short term shortfall with clean HBI iron imports.”


The post ‘Significant shift’ away from coal as most new steelmaking is now electric appeared first on Carbon Brief.
‘Significant shift’ away from coal as most new steelmaking is now electric

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
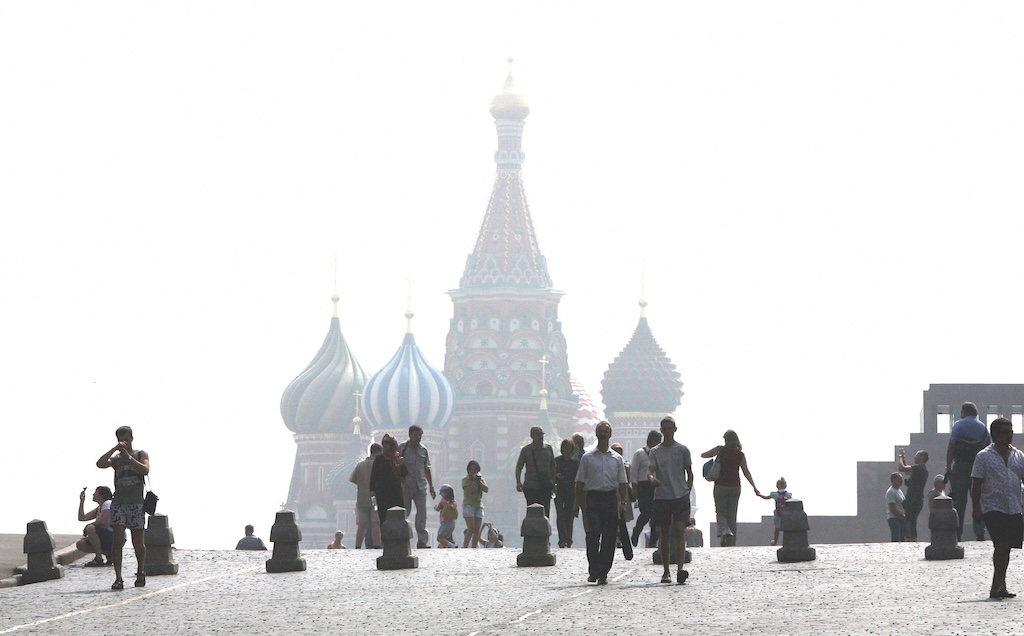
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
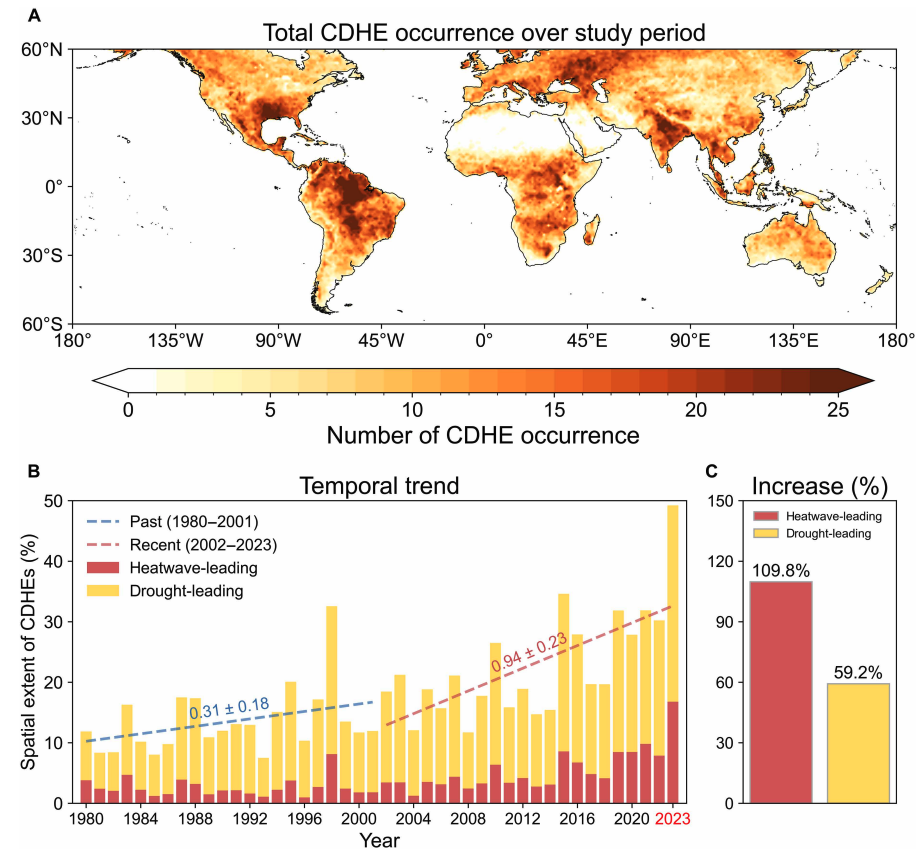
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: Bloomberg reported on increases in diesel prices in Europe and the US, speculating that rising fuel costs could be “a risk for president Donald Trump”. US gas producers are “poised to benefit from the big disruption in global supply”, according to CNBC. Indian government sources told the Economic Times that Russia is prepared to “fulfil India’s energy demands”. China Daily quoted experts who said “China’s energy security remains fundamentally unshaken”, thanks to “emergency stockpiles and a wide array of import channels”.
‘ESSENTIAL’ RENEWABLES: Energy analysts said governments should cut their fossil-fuel reliance by investing in renewables, “rather than just seeking non-Gulf oil and gas suppliers”, reported Climate Home News. This message was echoed by UK business secretary Peter Kyle, who said “doubling down on renewables” was “essential” amid “regional instability”, according to the Daily Telegraph.
China’s climate plan
PEAK COAL?: China has set out its next “five-year plan” at the annual “two sessions” meeting of the National People’s Congress, including its climate strategy out to 2030, according to the Hong Kong-based South China Morning Post. The plan called for China to cut its carbon emissions per unit of gross domestic product (GDP) by 17% from 2026 to 2030, which “may allow for continued increase in emissions given the rate of GDP growth”, reported Reuters. The newswire added that the plan also had targets to reach peak coal in the next five years and replace 30m tonnes per year of coal with renewables.
ACTIVE YET PRUDENT: Bloomberg described the new plan as “cautious”, stating that it “frustrat[es] hopes for tighter policy that would drive the nation to peak carbon emissions well before president Xi Jinping’s 2030 deadline”. Carbon Brief has just published an in-depth analysis of the plan. China Daily reported that the strategy “highlights measures to promote the climate targets of peaking carbon dioxide emissions before 2030”, which China said it would work towards “actively yet prudently”.
Around the world
- EU RULES: The European Commission has proposed new “made in Europe” rules to support domestic low-carbon industries, “against fierce competition from China”, reported Agence France-Presse. Carbon Brief examined what it means for climate efforts.
- RECORD HEAT: The US National Oceanic and Atmospheric Administration has said there is a 50-60% chance that the El Niño weather pattern could return this year, amplifying the effect of global warming and potentially driving temperatures to “record highs”, according to Euronews.
- FLAGSHIP FUND: The African Development Bank’s “flagship clean energy fund” plans to more than double its financing to $2.5bn for African renewables over the next two years, reported the Associated Press.
- NO WITHDRAWAL: Vanuatu has defied US efforts to force the Pacific-island nation to drop a UN draft resolution calling on the world to implement a landmark International Court of Justice (ICJ) ruling on climate, according to the Guardian.
98
The number of nations that submitted their national reports on tackling nature loss to the UN on time – just half of the 196 countries that are part of the UN biodiversity treaty – according to analysis by Carbon Brief.
Latest climate research
- Sea levels are already “much higher than assumed” in most assessments of the threat posed by sea-level rise, due to “inadequate” modelling assumptions | Nature
- Accelerating human-caused global warming could see the Paris Agreement’s 1.5C limit crossed before 2030 | Geophysical Research Letters covered by Carbon Brief
- Future “super El Niño events” could “significantly lower” solar power generation due to a reduction in solar irradiance in key regions, such as California and east China | Communications Earth & Environment
(For more, see Carbon Brief’s in-depth daily summaries of the top climate news stories on Monday, Tuesday