

Disseminated on behalf of Surge Battery Metals Inc.
The lithium market is experiencing a major rebound due to rising demand and tightening supply. Battery-grade lithium carbonate spot prices have jumped to about $24,086 per metric ton, based on data from Shanghai Metals Market (SMM). This marks a sharp increase from earlier lows in 2025, after a period of oversupply had weighed on the market.
What Causes Lithium Prices to Rebound
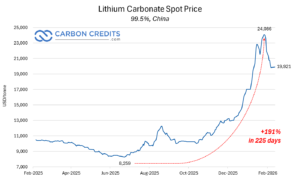
Several factors are behind the lithium price surge. First, the growth in stationary energy storage systems has been rapid. In 2025, demand for lithium in storage applications jumped about 71%, and analysts expect another 55% growth in 2026. As more utilities, data centers, and industrial players adopt battery storage, lithium demand continues to expand beyond just electric vehicles (EVs).
Second, China’s battery manufacturing sector is ramping up production to meet both domestic and global demand. Policy support for clean energy and EV adoption has helped absorb excess lithium that previously contributed to oversupply.
Meanwhile, regions like Europe and North America are boosting support for EVs and energy storage. European demand for batteries could reach 1 terawatt-hour by 2030. At the same time, U.S. incentives from the Inflation Reduction Act have already led to hundreds of new battery projects. These programs are driving additional lithium demand, putting further pressure on an already tight supply.
Third, supply constraints are becoming a concern. Forecasts for 2026 suggest a shift from surplus to a potential supply deficit of 22,000 to 80,000 metric tons, depending on how quickly new projects come online. This deficit is boosting hope among producers and investors. Prices might stay high if demand keeps outstripping supply.

Lithium’s Double Boost: AI + Data Center Batteries
Additional factors include rising interest in AI and data center batteries, which require large amounts of high-quality lithium. Emerging markets are generating new demand for battery-grade lithium. This adds to the existing need for electric vehicles. Coupled with a limited number of major lithium producers and delays in bringing new projects online, the market has become increasingly tight.
Other factors driving lithium prices up are the fast-growing need for batteries in AI data centers and energy storage systems. The global lithium-ion battery market for data centers was around $5.2 billion in 2024, per Prsedence Research. It is set to grow to nearly $17.7 billion by 2034, most of which will come from lithium batteries.
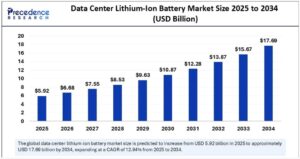
Lithium battery shipments for data center energy storage might rise over 80% in the next five years. Operators are expanding systems to support AI workloads that need steady power and load balancing. This surge in demand from new markets adds to the traditional battery needs of electric vehicles.
In short, the surge in lithium prices reflects a perfect storm of strong demand, constrained supply, and supportive policies. Investors and companies are taking note, as this environment signals higher revenues for producers. It also creates more opportunities for juniors to develop high-grade resources.
Surge Battery Metals Step Into the Spotlight
Surge Battery Metals (TSX-V: NILI | OTCQX: NILIF) is one such company advancing its position in the lithium supply chain. Surge focuses on the Nevada North Lithium Project (NNLP), which hosts the highest-grade lithium clay resource in the United States. It has a mineral resource estimate of 11.24 million tonnes of lithium carbonate equivalent (LCE) grading 3,010 ppm lithium at a 1,250 ppm cutoff.
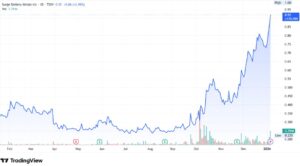
The company has also seen strong investor interest in recent trading. In early 2026, its stock rose about 35%, and over the past month, it gained nearly 46%. This rally reflects the overall optimism in the lithium market. It also matches the strong gains of major producers like Albemarle. The increase shows growing confidence in NILI’s high-grade Nevada project and its potential role in meeting rising lithium demand.
In early January 2026, Surge announced a key executive hire to strengthen its commercial leadership. The company appointed Steffen Ball as Vice President of Commercial Development for Nevada North Lithium LLC, the joint venture between Surge and Evolution Mining. Mr. Ball brings senior experience from major automakers’ battery material sourcing teams, including roles at Nissan North America and Ford.
This appointment signals Surge’s focus on preparing the project for eventual production and strategic partnerships. It also shows the company’s plan to create a team with strong industry knowledge and connections in the lithium value chain.
Alongside personnel moves, Surge has attracted increased investment from institutional groups. The Quaternary Group, for example, increased its ownership in Surge by buying shares on the open market. Now, it holds about 7.8% of the company on an undiluted basis.
Nevada North: High-Grade, High Stakes
Surge Battery Metals stands out among junior lithium miners. Its main asset, the Nevada North Lithium Project, sits in a well-established U.S. mining region with strong infrastructure.
Early exploration shows lithium clay grades up to 7,630 ppm, with updated drill intercepts as high as 8,070 ppm, considered high for clay-based deposits. A Preliminary Economic Assessment (PEA) shows an after-tax NPV of US$9.2 billion. It also has an IRR of 22.8% when lithium carbonate equivalent (LCE) is priced at US$24,000 per tonne.
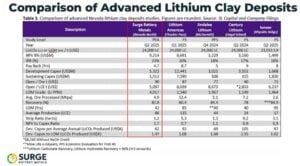
The project could produce an average of 86,300 tonnes of LCE annually, peaking at 109,100 tonnes in Year 6. Operating costs are estimated at US$5,243 per tonne of LCE, giving Surge a competitive edge.
The project is now progressing toward a Pre-Feasibility Study targeted for completion in late 2026, led by global engineering firm Fluor Corporation.
Surge is expanding its resource base through drilling across several kilometers of strike. The company recently reported additional strong drill results from Nevada North. It announced a 30.6-meter intercept grading 4,196 ppm lithium from surface in a 640-meter step-out hole to the southeast.
In infill drilling, Surge also reported 116 meters averaging 3,752 ppm lithium, including 32.1 meters grading 4,521 ppm near surface, highlighting a strong high-grade core within the deposit. These results confirm that high-grade lithium extends beyond the current resource area.
The wide step-out distance also shows strong potential for further expansion. Consistent high grades near the surface can support future resource growth and strengthen the project’s development outlook.
Moreover, Nevada’s mining-friendly environment, with access to roads, power, and skilled labor, reduces development risk. Strategic hires with experience in battery supply chains signal the company’s readiness to move toward production and partnerships.
High-grade resources, strong economics, and a strategic location put Surge in a great spot in the growing lithium market.
From Clay to Clean Energy
The recent rise in lithium prices shows how supply and demand dynamics are shifting. As energy storage and electric vehicles expand, major companies are boosting their market positions. Higher lithium prices support stronger revenue forecasts and have led analysts to raise price targets on key stocks.
At the same time, projects further upstream, including junior developers like Surge, are gaining strategic significance. Investments in early-stage lithium resources help diversify supply beyond dominant producers and geographies. Surge’s focus on commercial leadership and resource development reflects how smaller companies can play a role in meeting future demand.
If lithium prices keep rising and demand stays strong, both current producers and new developers could gain. For mining giants, this could mean the expansion of production capacity and stronger earnings. For Surge and similar companies, it could support project financing and advancement toward commercial output.
Live Nickel Spot Price
- READ MORE: Surge Battery Metals Strengthens Nevada North With High-Grade Expansion and Infill Success
DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Surge Battery Metals Inc. (“Company”) made a one-time payment of $75,000 to provide marketing services for a term of three months. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
The post Lithium Prices Climb Again in 2026, Sending Stocks Skyward appeared first on Carbon Credits.

Insetting program design starts with your supplier map. The carbon claim comes much later.
Consider a coffee procurement team that funds a farm intervention before checking its sourcing data. The supplier aggregates coffee lots from several regions. The buyer lacks farm-level traceability. Another purchaser expects to report the same outcome. A more attractive project brochure solves none of these problems.
If the distinction between a value-chain intervention and a purchased credit is still open, read CCC’s Insetting vs Offsetting guide before you set the brief.
Insetting program design begins with the purchasing relationship and works outward. You need to decide 1) where an intervention belongs, 2) what business problem it addresses, 3) who pays for it, 4) how results will be measured, and 5) what the evidence will let you say about them. This five-step playbook turns that sequence into a procurement plan.
Step 1: Insetting program design starts with supplier mapping
Start with the commodities that matter most to your Scope 3 inventory and sourcing continuity. Ask finance for spend by supplier, sustainability for the emissions baseline, and category managers for origin and volume records. Then identify which suppliers can trace material to a jurisdiction, sourcing region, producer group, or individual land-management unit.
The level of traceability affects what you can account for. Under the GHG Protocol Land Sector and Removals Standard, the spatial boundary for purchased land-based products depends on the traceability associated with each volume. Farm-specific factors or removals require physical traceability through an acceptable chain-of-custody model. A contract with a tier-one trader, by itself, does not establish a link to the farms behind its deliveries.[1]
Build a first-pass table with five columns: commodity and annual volume; supplier and origin; current traceability level; land-use and production risks; and the business owner who can change the purchasing terms. Mark missing data plainly. A blank cell is cheaper to fix before a program starts than after a claim is drafted.
If your company sets an SBTi Forest, Land and Agriculture target (FLAG), keep its land-related target boundary separate from energy and industry emissions. The current FLAG guidance also requires relevant companies to assess primary deforestation-linked commodities in their value chains.[2]
Step 2: Choose a commodity and jurisdiction for a pilot
Select one supply corridor where the sourcing connection can be established and procurement has a reason to stay. A useful pilot has repeat purchases, suppliers willing to share records, an intervention matched to a diagnosed problem, and a defined plan to measure the result. Carbon potential alone is a poor selection rule if the supplier cannot deliver the crop your business needs.
Compare candidate regions on land-use risk, supplier concentration, local rights and tenure, the availability of baseline data, and exposure to drought, erosion, or forest conversion. Check the relevant legal requirements separately. A nature project does not satisfy a due-diligence obligation merely because it has a carbon method attached.
Consider a coffee buyer sourcing from two districts. In the first, producer-group records identify the farms, while recent dry seasons have increased rejected green coffee lots. In the second, deliveries pass through several intermediaries and farm origins are unknown. Pilot shade management in the first district, with local agronomic advice and quality checks built into the plan. The buyer can trace purchases there and test the intervention against a defined sourcing problem.
Use a short decision memo to record why the selected corridor beats the alternatives, what remains uncertain, and what would stop the pilot. That memo is the first control against a project drifting toward whatever happens to photograph well.
Step 3: Design the supplier engagement and commercial model
The intervention needs an owner on each side of the contract. Decide who supplies planting material or training, who maintains the practice, who bears the cost if a harvest disappoints, and how long the buyer expects to purchase from participating suppliers. Where smallholders participate, budget cash flow and technical support for practices that offer a later return.
Put these terms in a supplier agreement or pilot addendum. It should cover eligible farms and volumes, consent to data collection, access for monitoring, any land or carbon rights that matter, benefit sharing, and what happens if the purchasing relationship ends. Ask local counsel and producer representatives to review the arrangement. The Accountability Framework is a useful reference for supply-chain work involving forests, ecosystems, and human rights.[3]
Avoid assigning an automatic carbon benefit to the buyer. The contract should say which party has the right to report each outcome, how overlapping claims will be checked, and how any issued credits will be handled. A reduction reported in a buyer’s inventory cannot simply be sold for someone else’s offset claim without an accounting review. SBTi FLAG guidance excludes purchased credits used as offsets from near-term FLAG target achievement.[2]
Set commercial measures beside environmental ones: delivered volume, rejection rate, supplier retention, and procurement cost. They tell you whether the program works as a supply-chain investment, even if carbon accounting takes longer to resolve.
Step 4: Build monitoring, reporting, and verification before rollout
Agree on the baseline and data flow before paying for a full rollout. Identify the land units or sourcing regions in scope, the practices that change, the records suppliers already keep, and the additional measurements the program requires. Decide which data can come from field visits, transaction records, or remote sensing, and who checks each source.
For carbon, separate three questions. Did the practice happen? Did emissions or removals change under an applicable method? Can the buyer attribute a defensible share to its purchased goods without double counting? The GHG Protocol’s 2026 guidance includes dedicated chapters on spatial boundaries, data and methods, evaluating actions, credited outcomes, and assurance.[1] These are distinct jobs. A photograph of a planted tree answers only part of the first.
CCC’s MRV and Additionality article explains the separate evidence questions a project reviewer will ask.
Create an evidence file for every reporting period: dated supplier and farm records, purchase volumes, methods and emission factors, uncertainty, quality checks, and changes from the baseline. Specify who can challenge the data and how corrections are recorded. If a project also seeks credit certification, keep project accounting and corporate inventory accounting separate. The GHG Protocol says its land standard focuses on entity-level inventories and does not set the rules for credit certification.[4]
Start with the minimum viable measurement design that can survive review. Add complexity when the pilot tells you which data actually changes a decision.
Step 5: Decide what can be reported and claimed
Insetting program design needs reporting rules before the marketing copy. Procurement, sustainability, finance, and legal should agree on four distinct outputs: operational performance; observed land or nature outcomes; inventory effects, if the accounting criteria are met; and any separately issued credits. One dashboard can display them, but they should not share a single unqualified headline.
SBTi FLAG guidance allows certain land-based removals within a company’s operations or supply chain to contribute to FLAG pathways, subject to criteria including permanence, traceability, data quality, and allocation. It does not allow purchased offsets to meet near-term FLAG targets.[2] Eligibility therefore depends on evidence and the applicable target rules, not on calling an activity “insetting.”
Draft a claims register. For each proposed sentence, record the period, boundary, data owner, calculation method, reviewer, and whether the result is measured, estimated, or still a goal. If the evidence supports only “we funded a pilot with 200 farms,” say that. Do not turn a funding fact into a verified emissions reduction.
What good looks like by year three
Treat year three as a review point, not a promised payback date. A mature pilot should have mapped participating supply volumes, a stable supplier agreement, a repeatable data collection process, and a comparison of commercial and environmental results against the baseline. It should also have a documented answer for outcomes that cannot be included in the buyer’s inventory.
Scale only where the pilot improves a sourcing decision and the evidence can follow the product. If neither condition holds, redesign the intervention or change the corridor. A disciplined program can conclude that a site is unsuitable. That is useful procurement intelligence.
Discuss your insetting program with CCC
Carbon Credit Capital designs nature-based supply chain investments around sourcing needs and measurable sustainability outcomes. Schedule a consultation with our carbon and sustainability experts to map your tier-one supplier network, FLAG exposure, and first pilot decision.
Sources
[1] GHG Protocol, Land Sector and Removals Standard, version 1.1, and companion Guidance, June 2026: https://ghgprotocol.org/land-sector-and-removals-standard ; https://ghgprotocol.org/land-sector-and-removals-guidance
[2] Science Based Targets initiative, Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, especially pp. 16–17, 37, and 41: https://sciencebasedtargets.org/resources/files/SBTiFLAGGuidance.pdf
[3] Accountability Framework initiative, Accountability Framework and guidance for companies: https://accountability-framework.org/
[4] GHG Protocol, Frequently Asked Questions: Land Sector and Removals Standard, questions 10 and 18: https://ghgprotocol.org/blog/frequently-asked-questions-land-sector-and-removals-lsr-standard
Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample a