


On December 19, Li-FT Power Ltd. (LIFT) announced that it had signed a definitive agreement with North Arrow Minerals Inc. to acquire three lithium projects in Northwest Territories, Canada. In this deal, LIFT will now fully own the DeStaffany, LDG, and Mackay Lithium Projects. In exchange, North Arrow will receive 250,000 common shares of LIFT.
The deal also includes the transfer of reclamation bonds, ensuring responsible environmental practices. However, regulatory approvals are pending for the transaction to close.
Francis MacDonald, CEO and Director of Li-FT Power, commented,
“The acquisition of North Arrow’s lithium portfolio further positions LIFT as the leading lithium exploration company in the Northwest Territories. The DeStaffany Project is located close to our BET and Echo pegmatites which creates synergies from a logistical standpoint, as well as increases the overall resource base for the eastern sector of the Yellowknife Pegmatite Province. The LDG and Mackay properties give LIFT a foothold in an emerging spodumene district located near the Diavik and Ekati diamond mines and provide long-term upside for the Company. We will continue to seek out accretive acquisitions within the Northwest Territories, especially around our existing resource base.”

Li-FT’s Commitment to Lithium Exploration
Li-FT focuses on acquiring and developing lithium projects in Canada, including its flagship Yellowknife Lithium Project, located in the Northwest Territories. In addition to this flagship venture, LIFT owns three early-stage exploration properties in Quebec, which show strong potential for uncovering buried lithium pegmatites.
- READ MORE:
- Li-FT Power Reveals Initial Mineral Resource of 50.4 Million Tonnes at Yellowknife Lithium Project
- Li-FT Power Secures $21 Million Through Strategic Private Placement
The company also manages the Cali Project in the Northwest Territories located within the Little Nahanni Pegmatite Group.
A MESSAGE FROM Li-FT POWER LTD.
This content was reviewed and approved by Li-FT Power Ltd. and is being disseminated on behalf of CarbonCredits.com.
Exploring Hard Rock Lithium Deposits in Canada.

Lithium, one of the most essential ingredients in the production of batteries, lithium powers some of our most important devices. As you may already know, it will also be one of the hottest resources in the coming decade. And one of the fastest-developing North American lithium juniors is Li-FT Power Ltd (TXSV: LIFT | OTCQX: LIFFF | FRA: WS0).
Moving on, let’s deep dive into these 3 lithium projects acquired by LIFT POWER.
1. The DeStaffany Lithium Project
The DeStaffany lithium property spans 1,843 hectares along the north-central shore of Great Slave Lake in the Northwest Territories. It lies just 18 kilometers northeast of the Nechalacho mine and 115 kilometers east of Yellowknife.
The property hosts two significant pegmatites—Moose 1 and Moose 2—rich in lithium, tantalum, and niobium. While these pegmatites were explored in the 1940s for tantalum and niobium, their lithium potential remains largely unexplored. Recent discoveries of additional pegmatites by North Arrow highlight further opportunities on the property.
The Moose pegmatites are located within just 1 kilometer from Great Slave Lake. This property benefits from accessibility via Yellowknife and Hay River throughout the year. LIFT plans to advance the project through mapping, sampling, and prospecting. The next phase will focus on preparing for initial drilling to assess the spodumene pegmatites further.
Moose 1 Pegmatite
The Moose 1 pegmatite stretches 370 meters, with widths ranging from 4.5 to 6 meters and a maximum of 11 meters. Although drilling has never been conducted, historical channel sampling in 2009 revealed spodumene mineralization with lithium levels of 1.5% Li2O over 7.5 meters.
Moose 2 Pegmatite
The mining potential of Moose 2 is promising. It has been mapped over a 450-meter strike length and measures up to 30 meters wide. Bulk sampling in the 1940s and 1950s focused on tantalum and niobium, producing concentrates, but its lithium content remains untapped. Spodumene mineralization is widespread, with lithium grades of up to 1.98% Li2O identified along a 250-meter stretch.
The DeStaffany Lithium Project has been blessed with abundant resources and has a strategic location. These advantages contribute significantly to LIFT’s growing portfolio.

2. The LDG Project
The LDG Project, covering 8,600 hectares is located near Rio Tinto’s Diavik diamond mine. Early exploration has identified ten spodumene pegmatites, with two having outcropping dimensions up to 20 meters wide and 400 meters long. The till-covered terrain offers favorable conditions for discovering buried lithium deposits.
3. The Mackay Project
The Mackay Project, spanning 8,661 hectares, lies south of the Diavik diamond mine. Two spodumene-rich areas have been identified. The MK1 site features pegmatite dykes with lithium grades of up to 3.74% Li2O from grab samples. Meanwhile, the MK3 site includes a 130-meter pegmatite exposure with grades reaching 5.25% Li2O. These findings highlight the high lithium potential of the region.

Experienced Oversight
The lithium miner significantly highlighted that all technical details in this update were reviewed by Dr. Ron Voordouw, a Qualified Person under NI 43-101 standards. This ensures that the information meets absolute professional and regulatory standards.
North Arrow Driving Exploration Success with Global Expertise
Based in Vancouver, BC, North Arrow Minerals is an exploration company primarily focused on advancing the Kraaipan Gold Project in Botswana. It also explores the diamond potential in the Naujaat (NU), Pikoo (SK), and Loki (NWT) projects.
The company’s leadership team, including its management, board of directors, and advisors, brings extensive and proven expertise in global exploration and mining. Kenneth Armstrong, P.Geo. (NWT/NU, ON), serves as North Arrow’s President and CEO, overseeing exploration programs. He is a Qualified Person under NI 43-101 and ensures all projects adhere to industry standards.
He expressed his opinion on this deal as well, noting,
“We are pleased to proceed with this transaction as it provides North Arrow with exposure to the continued evaluation of these NWT lithium properties as well as Li-FT’s advanced Yellowknife Lithium Project while allowing our team to focus on exploration of the Kraaipan Gold Project in Botswana, where geophysical surveys, geochemical baseline analyses, and target evaluation are currently underway.”
With these strategic moves, Li-FT strengthens its position in Canada’s growing lithium market, paving the way for sustainable energy solutions.
- MUST READ: The Lithium Paradox: Price Plummet, Supply Surge, and Demand Dip – What’s Happening Now?
- RELATED: Live Lithium prices
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: LIFT.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
Please read our Full RISKS and DISCLOSURE here.
The post Li-FT Power Strikes Deal with North Arrow Minerals to Expand Lithium Portfolio in Canada’s Northwest Territories appeared first on Carbon Credits.

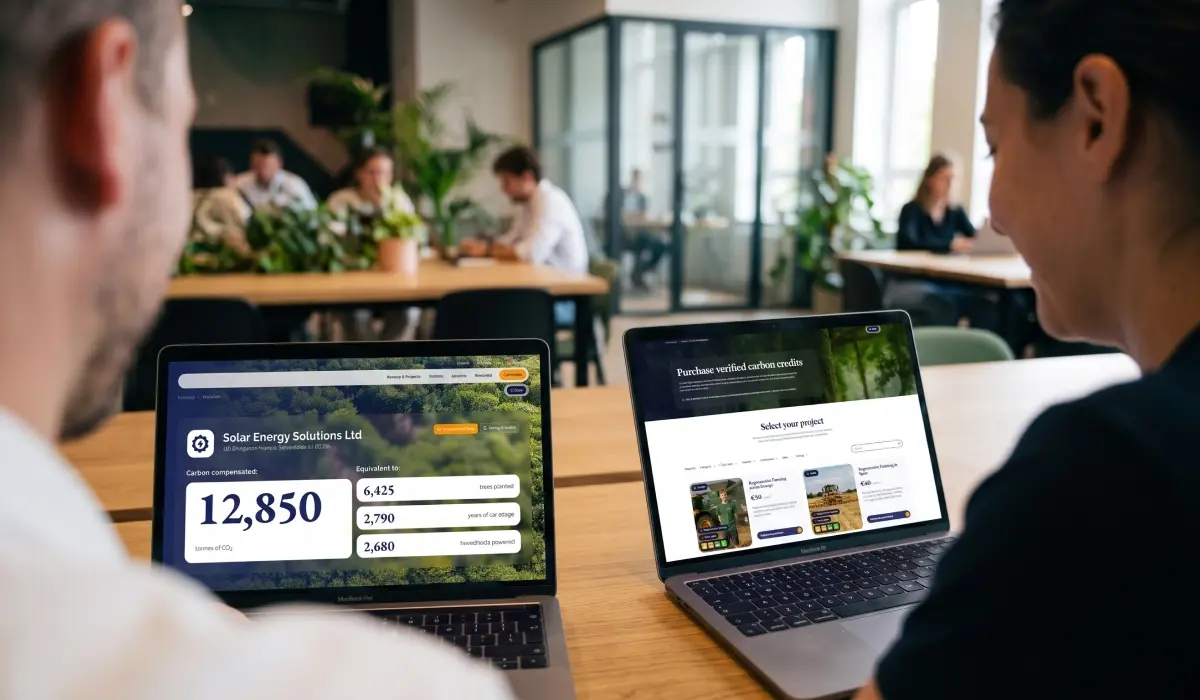
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits