

Following several years of strong growth, heat pump markets slowed in Europe in 2023.
In previous articles for Carbon Brief, we discussed this initial surge in 2021 and explored the impact of the energy crisis in 2022.
Yet, despite a drop in heat pump sales in key European regions, the trends in 2023 are more nuanced than an outright downturn.
Heat pumps generally increased their position relative to fossil heating systems and, in some of the continent’s biggest heating markets, they saw continued growth.
If policymakers want to keep the transition to low-carbon heating on track, then thorough, consistent and coordinated policy efforts remain critical to scaling up heat pump markets.
Heat pumps in Europe falling short of 1.5C path
In 2023, the heat pump market’s expansion in Europe hit a plateau, as shifts in policy, changing energy prices, a stagnating economy and backlash against climate initiatives adversely affected sales in several nations.
Across the continent, there was a general downturn in sales by about 5% compared with a year earlier, as shown in the figure below.

The impact was more pronounced in the segment of air-source heat pumps for space heating, with a 12% decrease in air-to-water and a 10% fall in air-to-air sales.
Conversely, the segment for hot water heat pumps – those used for heating water for use in the home – saw significant growth, surging by nearly 20%.
However, while still high in historical terms, these sales are far from what is required to meet climate goals.
The EU will need around 60m heat pumps by 2030 to get on track for net-zero by 2050, according to modelling from the European Commission.
The aggregated statistics presented above show that, as of the end of 2023, there were roughly 23m heat pumps across the 21 EU nations included in the data. (The figures also include, under “Rest of Europe”, three non-EU countries, the UK, Norway and Switzerland, while excluding smaller EU markets.)
This means that an average of around six million installations would be needed per year out to 2030, in order to hit the 60m milestone, whereas the current pace of growth is closer to 2.5m per year.
Trends in 2023 went in the opposite direction to what would be required. Among the countries accounting for the largest decline in sales were Italy, Finland and Poland, as shown in the figure below.
According to market statistics from the European Heat Pump Association (EHPA), Italian sales fell to around 345,000 units in 2023, compared to 514,000 the previous year, a decrease of 33%.
In Finland, some 114,000 heat pumps were sold compared to nearly 200,000 in 2022. And in Poland, the market fell to 129,000 units after reaching 208,000 in 2022.

While the European market contracted overall, several individual countries saw strong market growth. In Germany, sales increased by 60% year-on-year from 276,000 in 2022 to 439,000 in 2023.
In the Netherlands, 154,000 heat pumps were sold, a 53% increase on 2022 levels of roughly 100,000. Belgium experienced Europe’s largest market increase at 72%, breaking through 100,000 sales in one year for the first time.
In the UK, trade group the Heat Pump Association reported annual growth of 4% to reach more than 60,000 units sold. This data includes air-to-water and ground-source heat pumps, but does not account for air-to-air and is, therefore, incomplete.
Heat pumps gain market share
The decrease in the European heat pump sales in 2023 is moving in the opposite direction to what would be required to meet Europe’s decarbonisation goals. Nevertheless, the overall picture is more nuanced than this contrast suggests.
For example, in certain countries where homes are predominantly heated by fossil fuels, heat pumps have continued to gain market share.
France is the leader in this regard. The market share of heat pumps has been steadily growing over the past decade, with more heat pumps sold than gas and oil boilers for the first time in 2022.
This French trend continued in 2023 – as shown in the top left corner of the figure below. Fossil fuel boiler sales fell sharply by 23%, allowing heat pumps to reach 61% of the heating market despite also seeing a small fall in sales.
Germany (top right) has seen the heat pump market share steadily increasing year-on-year from around 10% in 2014 to 33% in 2023. Despite a booming fossil heating market, enough heat pumps were sold in 2023 that their market share continued to grow.
In Poland (centre left), although the market share of heat pumps plateaued in 2023, it has risen significantly to 40%, from just 10% in 2018. The Netherlands (bottom left) has also seen a rapid shift, with a heat pump market share of 18% in 2023, compared to just 1% in 2014.
Italy’s heat pump market share (centre right), which is more stable, contracted in 2023 after two years of growth. In the UK (bottom right), heat pumps have roughly tripled their market share in five years, but from a very low base. Excluding air-to-air heat pump sales, only around 60,000 units were sold in 2023, with a current market share of roughly 3%.
Considering all six countries together – the largest markets for heating installations, all of which still have gas boilers as their predominant heating technology – the market share of heat pumps has tripled from around 8% in 2013 to 24% in 2023.

A challenging outlook
European countries are facing diverse challenges to growing heat pump sales. The plateauing of heat pump sales in France, Europe’s largest market, is a key example of this.
On the one hand, the French government cut funding to one of the main heat pump support programmes by €1.4bn while announcing an increase in electricity tariffs. On the other, the regulator also announced a hike in gas tariffs, linking it directly to a decrease in gas consumption, among other factors, including the removal of a price cap.
This indicates an escalating financial vulnerability for customers remaining on the gas network in France. The heating industry expects a further contraction of the boiler market in 2024, although not at the pace seen in 2022-2023.
Elsewhere, the 2022-2023 heat pump market surge in Germany is not expected to continue, RAP analysis suggests. Already in the latter half of 2023, installations had slowed compared to the previous year, as had applications for the country’s subsidy programme.
This is largely linked to Germany watering down its Building Energy Act. It remains to be seen to what extent mandatory municipal heat planning, part of the EU’s revised Energy Efficiency Directive, will drive an uptake of heat pumps in the coming years.
Poland was Europe’s fastest-growing market for heat pumps in 2022, with a 120% increase in sales in a single year. The 46% contraction of heat pump sales in 2023 was largely driven by a 40% drop in the single-family home boiler market, with total sales of fossil fuel heating systems falling in turn. As a result, heat pumps maintained their market share in 2023.
However, the unfavourable price ratio in Poland, typically more than three times as expensive for electricity as for gas, remains a key challenge. The recently elected government is considering policy reform options to address this, however.
Italy’s steep market decline, especially for air-to-water heat pumps, which fell by more than 50%, moves the country in the wrong direction for decarbonising its heating sector. The country’s 2023 heat pump sales were even lower than in 2021.
Key reasons for this include changes to the Superbonus energy efficiency support program, which lowered its reimbursement rate from 110% to 90% and a tightening of eligibility for the scheme.
The heat pump market in the Netherlands was one of Europe’s fastest growing in 2023.
While there was a decline in sales in the country during the last quarter of 2023, due to supply chain constraints, the long-term outlook is for further growth. The market is expected to remain at similar levels throughout 2024.
However, regulation expected to come into effect in 2026 that would have phased out installations of stand-alone fossil fuel heating systems is now expected to be scrapped. The new Dutch right-wing coalition government announced a u-turn on the policy along with a raft of other climate measures in May.
In the UK, the heat pump market expanded slightly in 2023 compared to 2022. With around 60,000 units installed, however, it is well off the government’s target of 600,000 installations per year by 2028.
In October, heat pump grants under the boiler upgrade scheme were increased from £5,000 to £7,500.
The government also recently confirmed that, from 2025, new homes will no longer be allowed to install fossil fuel heating systems or so-called “hydrogen-ready” boilers. This will result in a substantial market boost of more than 150,000 additional units per year, RAP analysis suggests, assuming most new homes will include heat pumps.
However, there is continued uncertainty around the clean heat market mechanism, the main instrument expected to drive heat pump installations in existing buildings.
A one-year postponement of the scheme – which will set a rising standard for heat pumps as a proportion of fossil fuel boiler sales – was recently announced following pressure from the gas boiler industry.
At EU level, previously strong indications of support have begun fading. The European Commission has delayed its heat pump action plan, which would have continued to lay the groundwork for the rapid expansion of the technology across the EU.
More than 60 chief executive officers across the heat pump industry criticised the decision, warning that it risked billions of euros in investments.
At the same time, the European Parliament and the European Council recently passed the revised Energy Performance in Buildings Directive, which will prohibit subsidies for standalone fossil fuel boilers after 2025 and aims for a full phaseout of fossil fuel boilers by 2040.
Consistent policy remains key
Heat pumps are the “central technology” for low-carbon heat and rapid growth in their market share is crucial for meeting national and international climate goals.
After expanding rapidly in 2021 and 2022, the plateau in the European heat pump market in 2023 highlights the impact of inconsistent policies in denting their long-term growth.
The variance in market performance across countries – stemming from a mix of policy shifts, funding cuts and regulatory changes – underscores the complexity of scaling heat pump technologies rapidly enough to meet Europe’s decarbonisation goals.
Nonetheless, far more heat pumps are being installed than in previous years and heat pumps are continuing to gain market share in Europe’s largest heating markets.
RAP analysis shows that consistent and forward-thinking policy packages are likely to be key to boosting this trend. Such interventions could lower the upfront cost of heat pumps and ensure their running cost competitiveness, as well as providing the industry with the market certainty necessary to spur investment, innovation and consumer confidence.


The post Guest post: Heat pumps gained European market share in 2023 despite falling sales appeared first on Carbon Brief.
Guest post: Heat pumps gained European market share in 2023 despite falling sales

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
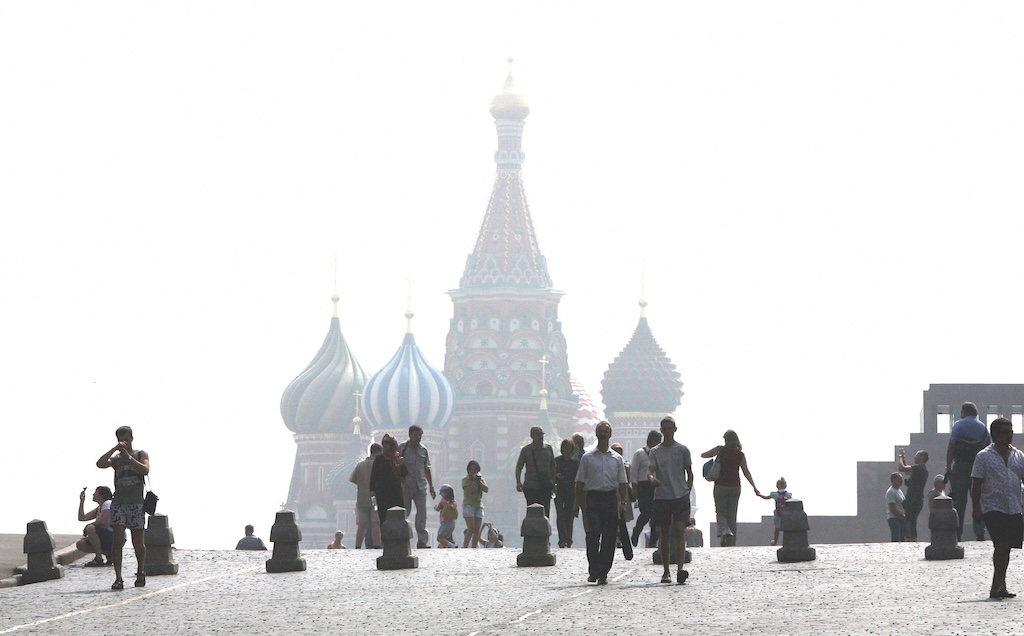
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
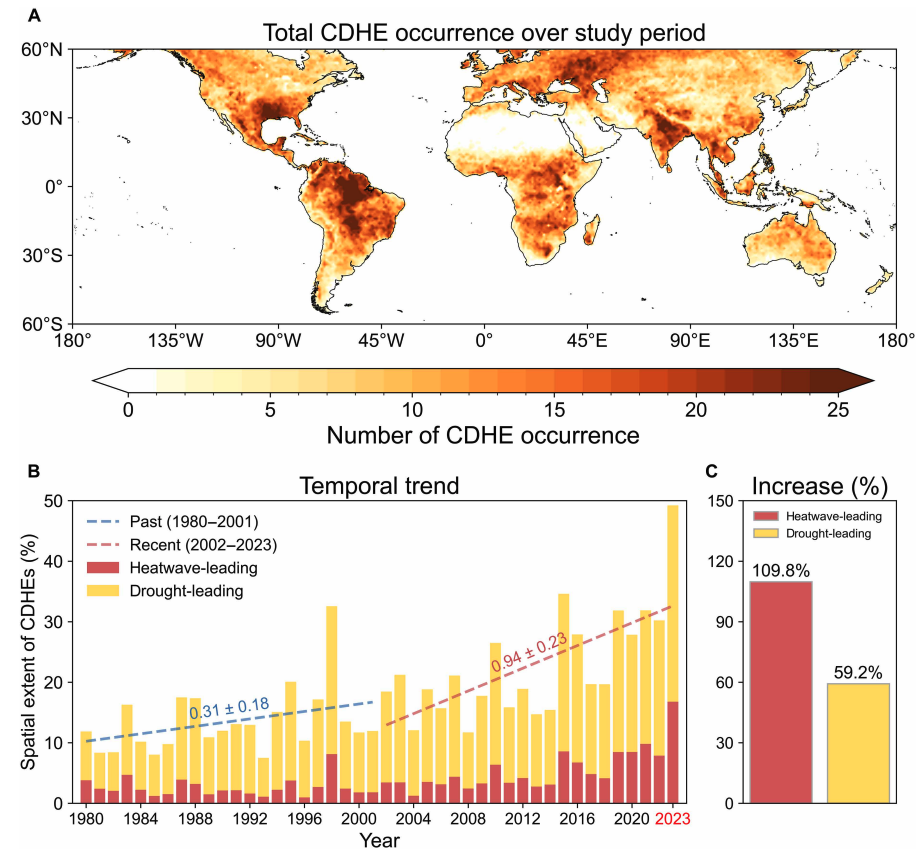
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: