


Alaska Energy Metals Corporation (AEMC) has announced promising assay results from its 2024 resource expansion program at the Eureka Deposit, part of its Nikolai Project in Alaska. These findings signify a major milestone for the company, extending the Eureka Zone mineralization by an impressive 1.8 kilometers (km) to the southeast.
With a total drilled extent now reaching approximately 5.5 km, AEMC continues to solidify its position as a leading developer of critical and strategic minerals essential to the energy sector.
Driving the Energy Future: AEMC’s Groundbreaking Nickel Discoveries
Alaska Energy Metals specializes in exploring and developing strategic mineral deposits vital to energy independence and sustainability.
Its flagship Nikolai Project is uniquely positioned to become a major domestic source of nickel and other critical metals, directly supporting the U.S. government’s Defense Production Act Title III goals.
The project has a location advantage, and benefits from proximity to infrastructure, reducing development costs and timelines. In addition to nickel, the deposit also contains cobalt, chromium, platinum, palladium, and other critical materials vital for batteries, renewable energy, and defense applications.
AEMC Nikolai Project – Property Location Map

AEMC is always committed to environmental, social, and governance (ESG) excellence. The company prioritizes environmentally responsible mining, fostering positive relationships with stakeholders, and ensuring compliance with rigorous quality assurance protocols.
Eureka Moment: Key Achievements from the 2024 Drilling Program
The results of the program, as outlined in AEMC’s press release showcase the significant potential of the Eureka Deposit, which are as follows:
- Expansion of Mineralization: The drilling campaign extended the deposit’s strike length by 1.8 km, confirming its continuity and increasing its inferred resource potential.
- Enhanced Resource Base: The new data will likely result in a substantial update to the Mineral Resource Estimate (MRE), expected in Q1 2025.
- Polymetallic Promise: Nickel remains the primary commodity, but the deposit also includes valuable critical metals such as cobalt, chromium, platinum, palladium, copper, and iron.
- Notable Intersections:
- Hole EZ-24-011 delivered 107.5 meters of mineralization at 0.29% nickel equivalent (NiEq), with high-grade chromium (0.27%) and iron (10.10%).
- Hole EZ-24-012 yielded 330.9 meters of mineralization with 0.28% NiEq, plus significant chromium (0.28%) and iron (9.49%).
Detailed Results from Key Drill Holes


Hole EZ-24-011
Located approximately 650 meters southeast of a previously drilled hole, EZ-24-011 focused on verifying near-surface extensions of the Lower Eureka Zone.
- Intercepts: 107.5 meters at 0.29% NiEq, with 0.27% chromium and 10.10% iron.
- Geology: The mineralized zone was hosted in serpentinized peridotite containing up to 4% disseminated sulfides.
- Eureka Zone 3: An additional intersection of 71.3 meters at 0.23% NiEq highlighted the deposit’s broader mineralization potential.
Hole EZ-24-012
Drilled between two historical holes, EZ-24-012 confirmed mineralization continuity and tested the zone’s full thickness.
- Intercepts: 330.9 meters at 0.28% NiEq, with 0.28% chromium and 9.49% iron.
- Geology: The main mineralized zone contained up to 10% disseminated sulfides, offering significant nickel and chromium values.
Strategic Impact of the Eureka Deposit Expansion
With the world’s growing demand for critical metals, AEMC’s success at the Eureka Zone has far-reaching implications.
The expansion plays a vital role in reinforcing U.S. energy security by:
- Contributing to the domestic supply of critical minerals,
- Reducing dependence on imports, and
- Mitigating risks posed by geopolitical uncertainties.
Beyond its strategic importance, the addition of tonnage and metal content from the 2024 drilling program could also deliver significant economic benefits for Alaska, while enhancing AEMC’s position within the energy transition supply chain.
Moreover, the Nikolai Project’s location near existing infrastructure supports an environmentally sustainable approach to material sourcing. This reduces carbon emissions and aligns with stringent ESG standards, ensuring responsible development practices.
What Comes Next for 2025 and Beyond?
AEMC plans to publish its updated MRE and metallurgical results in early 2025, building on the 2024 findings to enhance resource modeling and project feasibility, as noted by the company’s Chief Geologist Gabe Graf. These updates will pave the way for future exploration programs and development strategies.
Graf further said that:
“In light of recent alterations to the US minerals supply chain, made by China’s recent export ban of several critical minerals, this point in time remains crucial. Trade relations with China are uncertain, and should we face another more disruptive mineral ban, it could further stunt economic growth and development and even compromise national security. Thus, we remain steadfast in our efforts to uncover a domestic supply of nickel, cobalt, chromium, and other critical and energy-related metals essential to a growing number of strategic industries to ensure access to materials of great importance for the long haul.”
AEMC’s continued success at the Eureka Deposit strengthens its position as a leader in the U.S. critical minerals space. With robust assay results, ongoing exploration, and a commitment to sustainability, the company is well-equipped to meet the rising demand for strategic metals essential to the energy transition and national security.
As 2025 approaches, the forthcoming MRE update promises to be another pivotal step in AEMC’s mission to power the future with responsibly sourced minerals.
Here are the results of the previous drilling of the company:
- Alaska Energy Metals Expands Higher-Grade Mineralization and Unveils Promising Targets at Eureka Deposit
- Alaska Energy Metals Corporation Unlocks Vast Nickel and Critical Mineral Potential at Canwell Property, Nikolai Project, Alaska
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: AEMC.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
Please read our Full RISKS and DISCLOSURE here.
The post Alaska Energy Metals Expands Eureka Zone by 1.8 km, Strengthening U.S. Critical Metals Supply Chain appeared first on Carbon Credits.

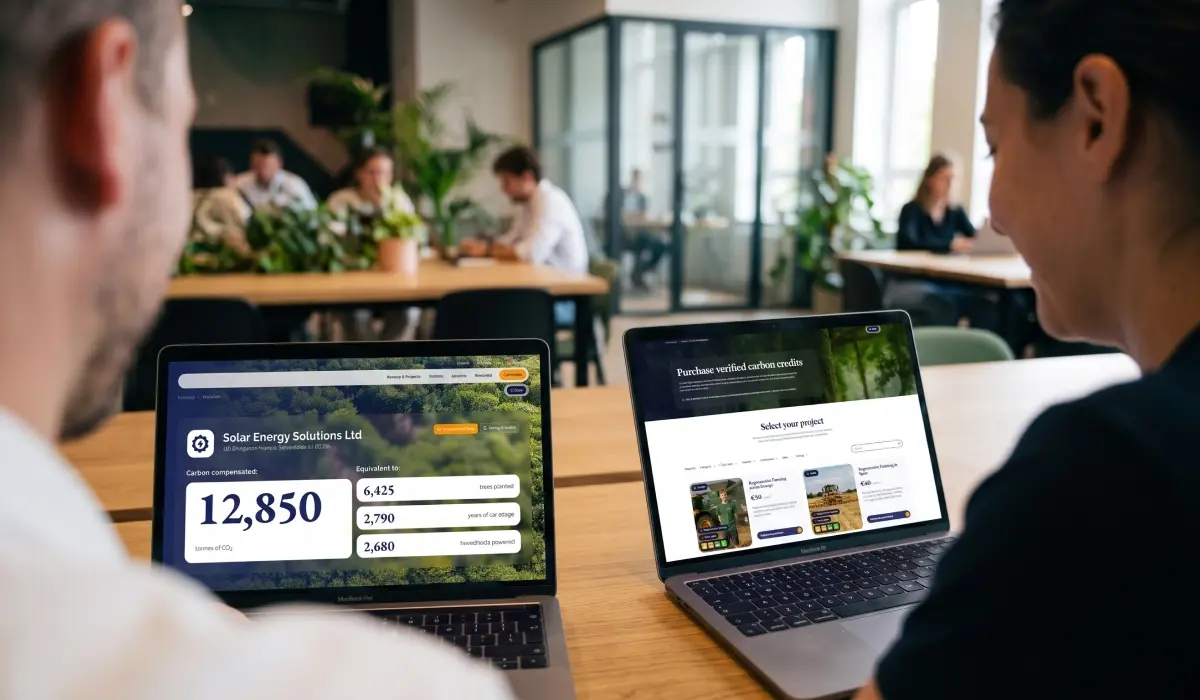
Most businesses that decide to act on their net-zero targets reach the same point of friction. Buying carbon credits has meant tracking down brokers, sitting through sales calls, and requesting a quote just to learn a price, sometimes with limited proof of what you are buying.

The earnings calls that quietly reframed climate from sustainability question to operating risk.
Three earnings calls in the last 18 months tell the story without any help from a press release.
Hershey, May 2024: cocoa price exposure compresses margin, and the company attributes part of the cost shock to West African weather. Olam, July 2024: coffee climate exposure quantified in the annual report. JBS, January 2025: supply chain climate disclosures expanded materially in response to investor pressure and regulatory expectation. None of these companies issued the announcement as climate news. They issued it as financial news. The climate-linked supply chain risk did not arrive with a sustainability framing; it arrived as a P&L line.
You are probably reading this article because you suspect the same thing is happening to your business. This piece walks through what is showing up on which earnings calls, how procurement and finance leaders are quantifying the exposure, and what serious corporates are doing about it before the regulator asks.
Where climate risk has already appeared in earnings
The pattern is consistent across resource-intensive sectors. A weather event compresses supply, the price spikes, the cost flows through the income statement, and the analyst on the call asks whether the event is anomalous or structural. Increasingly, the honest answer is the second one.
Cocoa is the cleanest example. The 2023 to 2024 West African harvest fell sharply on the back of erratic rainfall and disease. Cocoa futures more than tripled. Companies with concentrated West African sourcing absorbed the cost; companies with diversified sourcing absorbed less. The exposure was not climate as ESG topic. It was climate as cost of goods.
Coffee follows the same pattern. Brazilian and Vietnamese harvests have moved on weather more sharply across the last several seasons. Roasters with long-tenor supplier relationships and origin diversification have managed the volatility; roasters with spot-market exposure have not. Wheat, sugar, palm oil, beef: the same dynamic in different commodities, a pattern the IPCC AR6 Working Group II report projects will intensify across agricultural systems through mid-century.
What this means: climate risk is no longer a footnote in the 10-K. It is a line item the CFO has to explain on the call.
The three commodity exposures that hit margin first
For most companies with material Scope 3 exposure, three exposures dominate the near-term P&L risk.
- Concentrated single-origin sourcing in a climate-vulnerable region. If your tier-one supply for any material commodity sits in one geography, you have a concentration risk that climate amplifies. Diversification across origins is the obvious hedge, but it takes years to build and requires relationships you cannot acquire by tender.
- Supplier financial fragility under climate stress. Smallholder farmers, who supply a large share of the global cocoa, coffee, and palm oil market, do not carry the balance sheets to absorb yield shocks. When yields collapse, they exit. When they exit, your supply base shrinks, and the surviving suppliers raise prices. The risk is structural, not cyclical.
- Logistics and storage exposure to extreme weather. Hurricane disruptions to Gulf shipping, drought-driven Panama Canal restrictions, flooding in European inland waterways: each of these has moved input costs in the last three years, a pattern documented in Munich Re’s natural catastrophe data. The exposure shows up as a one-quarter event in the financial press but accumulates over time on the cost line.
TCFD and ISSB disclosure changes
The disclosure architecture has now caught up with the risk. The Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in the ISSB’s IFRS S2 climate standard, requires companies to disclose climate-related risks across physical and transition categories, with quantification where possible.
For physical risk specifically (the climate-linked supply chain risk you are reading about), the disclosure must address both acute exposures (extreme weather events) and chronic exposures (gradual changes in temperature, precipitation, and growing seasons). The disclosure must address the time horizon over which the risk is material, the parts of the value chain exposed, and the financial impact under different scenarios.
The CSRD imposes similar requirements under European law, with double materiality (both financial and impact materiality) embedded in the assessment. The practical effect: your auditors and your investor relations team now need a defensible answer to the climate-linked supply chain risk question, and the answer needs to be quantified.
What procurement and finance can do now
Three actions matter near-term.
Map your exposure. Most companies do not have a clear view of which tier-one and tier-two suppliers sit in which climate-vulnerable geographies. Without the map, you cannot quantify the risk, and without the quantification, you cannot disclose it credibly. The map is the foundation, and World Resources Institute climate risk research provides useful public tooling to start.
Diversify and deepen, in that order. Diversification across origins reduces concentration risk, but the deeper move is to invest in the resilience of the suppliers you already have. Regenerative practices, agroforestry, soil health interventions: these reduce yield volatility under climate stress and protect your input cost trajectory.
Embed the climate spend inside procurement, not outside it. Treating climate risk as a sustainability cost line subordinates it to the ESG budget. Treating it as a procurement and resilience investment puts it in the budget that matters, which is the cost-of-goods budget that the CFO defends quarterly.
Nature-based supply chain investments are the asset class designed for exactly this purpose. They sit inside the value chain, they reduce climate-linked supply risk, they generate verifiable Scope 3 reductions, and they produce the documentation an auditor and a regulator can both test.
If you are quantifying climate-linked supply chain risk in advance of the next earnings cycle or the next disclosure period, the carbon and sustainability experts at Carbon Credit Capital can help you map your exposure and structure a Dual-Value Model response that addresses reduction, resilience, and disclosure-readiness in a single program. Schedule a consultation.
More and more small and medium-sized businesses are hearing the same question from their larger customers: What is your carbon footprint? That question now travels down entire supply chains, and it arrives next to tender requirements, certification criteria, and rising customer expectations.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy11 months ago
Sending Progressive Philanthropist George Soros to Prison?
-
Climate Change2 years ago
Bill Discounting Climate Change in Florida’s Energy Policy Awaits DeSantis’ Approval
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Carbon Footprint2 years ago
US SEC’s Climate Disclosure Rules Spur Renewed Interest in Carbon Credits