

Disseminated on behalf of Surge Battery Metals Inc.
Grade matters because it affects how much lithium a project can produce and how costly it is to operate. Higher grades generally mean more lithium can be recovered with lower costs. This matters for projects that want to compete in the fast‑growing electric vehicle (EV) and energy storage markets.
Let’s explore why grade is essential for lithium clay projects and learn how it affects economics, operations, and investor interest. More notably, we highlight how Surge Battery Metals’ Nevada North Lithium Project (NNLP) stands out in this context.
What “Grade” Means in Lithium Projects
In mining, “grade” refers to how much lithium is present in a deposit. It is usually reported in parts per million (ppm) or as lithium carbonate equivalent (LCE). A higher grade means there is more lithium per tonne of rock.
For lithium clay, grades can vary widely. Some clay deposits have grades below 1,000 ppm. Others reach several thousand ppm. The higher the grade, the more lithium metal is available to extract.
U.S. lithium clay peers usually range from 800 to 2,540 ppm Li. Some areas are lower, at 120 to 766 ppm, like American Lithium’s Tonopah claims. Others can reach 1,690 to 2,900 ppm in drilling. Common cutoffs start at 1,000–1,250 ppm for economic viability, far above the <500 ppm in some global clays like Australia’s Kaolin resources.
Grade affects several key project factors:
- Revenue potential – Higher grade means more lithium output per tonne of material moved.
- Cost efficiency – Projects with a higher grade may spend less on mining and processing per unit of lithium produced.
- Product quality – Higher-grade feedstock can result in higher‑purity lithium products, which are valuable in battery markets.
Investors and developers pay close attention to grade because it is a strong indicator of future project performance.
- SEE LIVE LITHIUM PRICES HERE
Why Grade Matters More Than Ever
The global lithium market is changing fast. EV production is growing quickly. Energy storage systems are expanding. Demand for lithium is outpacing supply in many markets. This puts pressure on producers and developers to find the most competitive resources.
In this environment, grade has become a key differentiator among lithium clay projects. Several market trends explain why grade now matters more than ever:
-
Rising Demand for Battery‑Grade Lithium
Battery manufacturers require consistent, high‑purity lithium feedstock. Higher-grade deposits can deliver more lithium for refining into battery materials. They can also reduce the amount of waste material that needs to be processed.
Global lithium demand is forecast to reach 2.4–3.1 Mt LCE by 2030 (from ~0.7 Mt in 2022), with batteries driving >90% growth. High-grade clays minimize waste in refining to meet this.
-
Cost Pressures in Battery Supply Chains
Global competition in battery manufacturing pushes producers to lower costs. Projects with higher grades can reduce lithium production costs. This improves project economics and makes supply chains more resilient.
Higher grades cut opex by reducing tonnage processed. For instance, >3,000 ppm clays enable <US$6,000/t LCE vs. lower-grade brine equivalents >US$10,000/t.
-
Shift Toward Domestic Supply Security
Countries like the United States are prioritizing domestic lithium production. This is part of a broader energy and industrial policy.
U.S. holds ~115 Mt lithium resources, per USGS 2025 data, up from 98 Mt in 2024. However, production is <1% global. IRA mandates 80% domestic or allied sourcing by 2027, favoring high-grade projects for faster permitting/offtakes.
Projects with strong grades are more likely to secure investment, permit approvals, and supply agreements. They offer clearer pathways to sustainable production.
In this landscape, projects with both good size and high grade stand out. They can produce more lithium with fewer inputs. They also attract stronger interest from investors and manufacturers looking for reliable sources of battery metals.
Nevada North: High-Grade Lithium in Action
Among lithium clay projects in the United States, Surge Battery Metals’ (TSX-V: NILI | OTCQX: NILIF) Nevada North Lithium Project (NNLP) is a standout example of why grade matters. NNLP hosts one of the highest‑grade lithium clay resources in the country. It also shows strong potential for expansion and future development.
According to the 2024 resource estimate, NNLP now has an inferred resource of 11.24 million tonnes (Mt) of LCE at an average grade of 3,010 ppm lithium using a 1,250 ppm cutoff. This represents a significant increase in both size and quality compared to earlier estimates. It also positions NNLP as one of the highest‑grade lithium clay deposits in the United States.
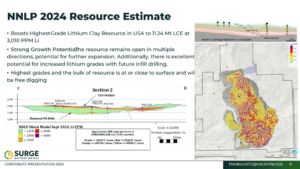
Within that total resource, a core portion of 7.43 Mt of LCE grades 3,843 ppm lithium at a higher cutoff level. Higher cutoffs generally indicate more concentrated lithium zones, which are especially valuable for economic studies and future mine planning.
NNLP’s strong grades have grown progressively through drilling campaigns. In 2023, early drilling returned exceptionally high lithium values, including intervals that ranged up to 8,070 ppm lithium in specific clay horizons. These high grades were encountered close to the surface, which could simplify mining logistics.
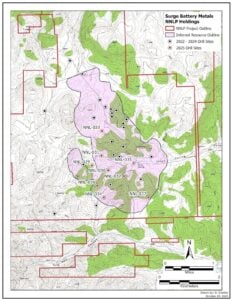
Surge recently reinforced this grade advantage with new drilling results at NNLP. The company reported a 31-meter intercept grading 4,196 ppm lithium from surface in a 640-meter step-out hole to the southeast. This intercept is nearly 40% higher than the project’s current average grade of 3,010 ppm lithium.
The 640-meter extension also confirms that high-grade mineralization continues well beyond the existing resource boundary. Near-surface grades above 4,000 ppm further support low stripping ratios and efficient future development.
Mr. Greg Reimer, CEO, President, and Director of Surge, said,
“These drill holes materially enhance the scale of the Nevada North Lithium Project. Intersecting nearly 4,200 ppm lithium in a 640‑meter step-out to the southeast in NNL‑037 is a significant achievement. Not only is the system continuous, but we are encountering some of our highest grades at the very edges of the known footprint. It is increasingly clear that we have only begun to tap the true potential size of this premier lithium asset.”
NNLP’s resource is also shallow and laterally extensive. The deposit extends over kilometers of strike and remains open for expansion in several directions. This suggests that further drilling could add more tonnes or improve the average grade even further.
These characteristics give NNLP a competitive advantage. High grades can translate into lower production costs per tonne of lithium. They can also support strong economic outcomes as the project progresses toward prefeasibility and eventual development.
Economics Speak for Itself
High lithium grades help improve the economic profile of a project. For developers like Surge Battery Metals, this means stronger project metrics in studies such as preliminary economic assessments (PEAs).
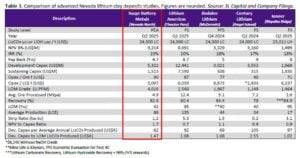
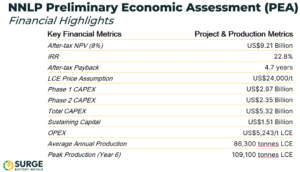
In the case of NNLP, the high-grade and large resource support robust economic results. A recent PEA shows an after‑tax net present value (NPV) of US$9.21 billion and an internal rate of return (IRR) of 22.8% at a lithium price of US$24,000 per tonne LCE. These figures reflect the project’s ability to generate strong cash flows over its lifespan.
High grade also means that a project can produce significant lithium volumes without requiring excessively large mining operations. This can reduce environmental footprint, capital cost, and permitting complexity. The Nevada North deposit’s grades help make future processing and extraction more efficient.
For investors, grade is a key signal of potential project strength. Projects with grades well above the global average often trade at premium valuations relative to peers with lower grades.
NNLP’s resource quality has attracted notable attention from analysts and market observers because it combines a strong grade with domestic location in a mining‑friendly jurisdiction.
The Strategic Edge in a Competitive Market
The lithium market will continue to evolve over the next decade. Global EV adoption and energy storage deployment are expected to drive demand for lithium to new highs. This will require reliable supply sources that can deliver consistent volume and quality.
In this context, grade will remain a core metric for comparing lithium clay projects. Deposits with higher grades are more likely to attract the capital, partnerships, and offtake agreements needed to advance through development phases. They also offer clearer economic paths compared to lower‑grade alternatives.
For Surge Battery Metals and its Nevada North Project, high grade is more than a number on a chart. It is a core advantage that differentiates NNLP from many peer projects. It supports strong resource economics, efficient processing potential, and a compelling narrative for domestic supply chain relevance in electric vehicle and battery markets.
As global competition for lithium intensifies, projects with both size and quality will stand out. NNLP’s high‑grade resource positions it as a leading example of how grade can influence outcomes in modern lithium clay development.
DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Surge Battery Metals Inc. (“Company”) made a one-time payment of $75,000 to provide marketing services for a term of three months. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
Please read our Full RISKS and DISCLOSURE here.
The post Why Grade Matters More Than Ever in Lithium Clay Projects appeared first on Carbon Credits.

Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
CCC’s guide to finding nature-based solutions in your supply chain explains where to look. Here, the next task is to turn a broad concern into a testable proposal.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3 Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
Discuss a sourcing opportunity with CCC
Carbon Credit Capital’s nature-based supply-chain investment service uses its Dual-Value Model to examine supply-chain economics alongside potential sustainability outcomes.
Schedule a consultation to discuss your sourcing exposure and the questions to resolve before allocating capital.
Sources
- Intergovernmental Panel on Climate Change (IPCC), Climate Change 2022: Mitigation of Climate Change, Chapter 7, Agriculture, Forestry and Other Land Uses, section 7.4.3.3 (Agroforestry).
- World Business Council for Sustainable Development (WBCSD), Nature-based Solutions Blueprint, 5 June 2024.
- Science Based Targets initiative (SBTi), Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, section 3.1.4, pp. 37–38.
- United Nations Environment Programme (UNEP), State of Finance for Nature 2023, 2023.
A plastic credit funds the collection of plastic waste in places where no formal system exists to collect it. Each credit represents a measured, independently audited quantity of plastic taken out of the environment or returned to use, tracked on a public registry.

EU carbon credit claims changed on 27 September 2026, the day the Directive (EU) 2024/825 began to apply across the European Union. The change is narrow. It changes how a company can talk about the credits it buys. A product can no longer be called neutral on the strength of compensation alone; however, every specific, evidenced statement about what a company measured, reduced, and funded stays fully available.




