

Now that it’s summer, it’s time to shine a light on solar progress in the Southeast. In SACE’s latest edition of our “Solar in the Southeast” report series, you can read up on which utilities and states can expect to see solar growth. Overall, the Southeast can now claim about 22 gigawatts (GW) of solar (22,183 megawatts, MW) on a full-year operational equivalent basis, or an average solar ratio of 665 watts per customer in 2023. The Southeast is projected to nearly double the amount of solar in the region to almost 44 GW for 2027.We also detail how key policy developments such as recent utility resource plans and the influx of federal funding from the Inflation Reduction Act (IRA) to Southeastern states help inform and grow the solar market.

How do we track solar progress for different states and utilities?
We can start by looking at the overall amount of solar measured in megawatts (MW) of capacity that are operating or planned in a state or utility. Solar projects can be categorized as either utility-scale solar or distributed solar. Distributed solar is smaller and is typically installed on the rooftops of residential or commercial customers, while utility-scale solar is larger and is installed in ground-mounted arrays owned by a utility or a developer.
Utility-scale solar capacity figures include both projects that have been reported to federal data collectors, as well as the aggregate capacity of future solar resources in a utility’s integrated resource plan (IRP) that have yet to be sited at a specific location. In both cases, the utilities may purchase power from a solar developer to receive the solar project’s output for a 20–30-year period instead of owning it outright, but the capacity itself is still attributed to the utility for that time period.
Distributed solar is interconnected to the utility in a variety of different program stylings, such as net-metered solar, virtual solar, and tariffed solar, which are included in all of our figures.

Altogether, the Southeast is able to claim more than 22 gigawatts (GW) of solar (22,183 MW) as of 2023. In order to compare hundreds of different utilities in the Southeast, SACE ranks utilities on the basis of solar watts per customer (W/C). This illustrates the overall amount of solar power sourced to a utility or state relative to the number of that specific utility’s retail customers. To use 2023 as an example, the Southeast regional average would equate to an average solar ratio of 665 watts per customer for the region’s 33 million customers served by electric utilities. That measurement is for the entire region, and every utility within the region in turn has its own metric that may be higher or lower than the regional number.
The latest figures show solar growth despite some unrealized potential
Overall, the Southeast is projected to nearly double the amount of solar to almost 44 GW over the next four year, rising to 1,350 watts per customer in 2027. In general, utilities across the Southeast have made larger capacity deployments in shorter time frames than ever. As an example, Florida Power & Light deployed approximately a gigawatt of solar capacity in 2023. This is a trend that can only continue to improve with stronger planning processes for utility resources and transmission.
Yet, there is still some unrealized potential in recent utility resource plans and regulatory approvals. For example, Georgia Power ranks above the regional average in watts per customer (W/C) at 1,168 W/C in 2023 despite its latest resource plan, and not because of it. Georgia Power unexpectedly filed an updated IRP in 2023 outside the regular schedule due to unanticipated load growth, but instead of adding any incremental solar in the near-term, it has instead pushed for more fossil gas. Likewise, even though Alabama Power has received approval to build 2,400 MW of additional renewable energy generation by 2029, a prior approval of 400 MW went largely unused for most of its timeframe before being extended, meaning Alabama Power did not end up siting most of the solar that was approved.
There are also some utilities that are currently undergoing resource planning process, or expected to start soon: Duke’s utilities in the Carolinas filed an update to their resource plan in January 2024 that unfortunately does not allow new incremental solar before 2028; and the Tennessee Valley Authority (TVA) was set to release its IRP in March, but that has now been delayed to the fall of 2024. However, both of these resource plans would be unlikely to be reflected in the near-term forecast that is the focus of this report.

This year’s report reflects several SunBlockers: utilities whose four-year forecast remains below last year’s regional average. The Tennessee Valley Authority (TVA) unfortunately fell just short of the benchmark needed to avoid making the this year. And despite a promising increase from new solar capacity expected to provide power to the grid, Alabama Power has yet to make it off the SunBlocker list. The North Carolina Electric Cooperatives, Seminole Electric, and PowerSouth are all at the bottom of the list this year.
However, there is hope for utilities that that are on the SunBlocker list. Many provisions of the Inflation Reduction Act (IRA) are aimed at providing certainty to developers and expanding financing options for non-traditional utilities, such as direct pay of the ITC (Investment Tax Credit) and PTC (Production Tax Credit) as well as the New ERA (Empowering Rural America) funding. So utility resource plans and other solar programs offered by states or utilities still have unrealized potential they should consider cashing in on.
In subsequent blogs we we will unpack the utility rankings and watts per customer forecast for major utility systems further. Additionally, we will explore the SunRisers from this year’s report, the utilities exhibiting the highest total increase in W/C solar ratio between the baseline year (2023) and the four-year forecast (2027). Stay tuned for more!
The post Solar in the Southeast: Seventh Edition Report appeared first on SACE | Southern Alliance for Clean Energy.

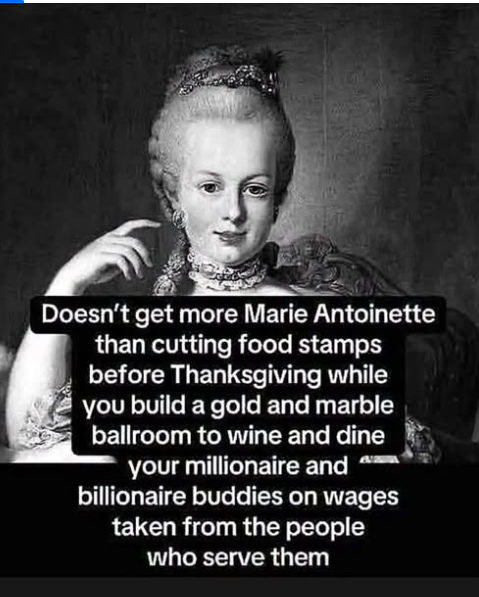 To many of use, the holidays serve as a reminder that most Americans (61%) live paycheck-to-paycheck, and many have trouble paying for groceries. All this in a nation where the top 0.1% have more wealth that the bottom 50%.
Perhaps most egregious is the fact that people (like me) who write posts like this are regarded as “communists” by the far-right.
Renewable Energy
Statement on the Bipartisan American Affordability and Jobs Act Passing the Senate from ACORE President and CEO Ray Long
-
Policy -
Press Releases
Statement on the Bipartisan American Affordability and Jobs Act Passing the Senate from ACORE President and CEO Ray Long
WASHINGTON, D.C. — ACORE congratulates the U.S. Senate on the passage of the Bipartisan American Affordability and Jobs Act (BAAJA), legislation that is an essential step to achieving affordable and reliable power across the United States.
BAAJA comes at a critical time when we need to build out our energy infrastructure to help reduce escalating power prices and prevent expected shortages in just the next few years. This legislation is expected to reduce residential electricity bills by $19 billion, create over 100,000 new jobs, invest $55 billion from data centers into energy infrastructure, and reduce CO2 emissions from the power sector by 20 percent in the next decade.
There’s no time to waste. We need to improve our electric grid and build out 15 times the peak power of New York City in just the next four years. Let’s get this bill passed in the House so we can get building.
###
About ACORE
ACORE is a nonpartisan nonprofit organization that operates at the intersection of affordability, reliability, and clean energy deployment. Our work is focused on stabilizing energy prices, strengthening the electric grid, and driving investment in cost-effective technologies to ensure that clean energy delivers for people, businesses, and the U.S. economy.
ACORE convenes a membership spanning the full clean energy value chain—investors and financiers, developers and EPCs, hyperscalers and energy buyers, manufacturers and advisors. Our members were directly involved in more than 80% of the American clean energy infrastructure projects added to the grid in 2025. We champion all clean energy technologies including transmission, solar, wind, storage, geothermal, hydropower, nuclear, and beyond. ACORE members are the companies investing in and building tomorrow’s electric power system, accelerating infrastructure development, strengthening grid reliability, and enhancing domestic competitiveness.
Media Contacts:
Tamari Palmer
Associate, Communications
palmer@acore.org
Chris Higginbotham
VP, Communications
higginbotham@acore.org
The post Statement on the Bipartisan American Affordability and Jobs Act Passing the Senate from ACORE President and CEO Ray Long appeared first on ACORE.
https://acore.org/news/statement-on-the-bipartisan-american-affordability-and-jobs-act-passing-the-senate-from-acore-president-and-ceo-ray-long/
 I would say it’s the vicious circle that goes like this: ignorance –> electing authoritarian leaders –> leaders further destroy the educational system –> greater ignorance.
Given that there are still tens of millions of Trump supporters living among us, it’s really a miracle that we didn’t elect a criminal sociopath much earlier.

COP31 Bulletin Day 13: New draft retains electrification goal but delays adaptation finance and science decisions

How “Marie Antoinnete” Can We Get?

COP31 Bulletin Day 12: ‘Don’t ignore us,’ Panama warns as COP31 runs into overtime

-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19
-

 Climate Change1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Renewable Energy5 months ago
Send a Bible to a Starving Child
-

 Green Living2 years ago
Our Picks for the Top 2024 Black Friday and Cyber Week Sales From Sustainable Brands