

Weather Guard Lightning Tech

Microsoft Develops 10.5 GW, Siemens Gamesa Reports Loss in 2nd Quarter, WEG brings 7 MW Turbine Manufacturing to USA
Microsoft is partnering with Brookfield Asset Management to develop 10.5 GW of new wind and solar, Siemens Gamesa reports a €365 million loss in the 2nd quarter of 2024, WEG will begin manufacturing their 7 GW turbine platform in Minnesota, and Canadian Pension Plan Investment Board and Global Infrastructure Partners acquire Allete.
Sign up now for Uptime Tech News, our weekly email update on all things wind technology. This episode is sponsored by Weather Guard Lightning Tech. Learn more about Weather Guard’s StrikeTape Wind Turbine LPS retrofit. Follow the show on Facebook, YouTube, Twitter, Linkedin and visit Weather Guard on the web. And subscribe to Rosemary Barnes’ YouTube channel here. Have a question we can answer on the show? Email us!
Pardalote Consulting – https://www.pardaloteconsulting.com
Weather Guard Lightning Tech – www.weatherguardwind.com
Intelstor – https://www.intelstor.com
Allen Hall: I’m Allen Hall, president of Weather Guard Lightning Tech, and I’m here with the founder and CEO of IntelStor, Phil Totaro, and the chief commercial officer of Weather Guard, Joel Saxum. And this is your News Flash. News Flash is brought to you by our friends at IntelStor. If you want market intelligence that generates revenue, then book a demonstration of IntelStor at intelstor. com.
Microsoft has partnered partner with Canada’s Brookfield Asset Management to develop new wind and solar farms aiming to bring 10. 5 gigawatts of generating capacity online. The partnership is expected to help finance renewable electricity projects to be built between 2026 and 2030. 30 starting in the U.
S. and eventually Europe. The deal is estimated to cost over 10 billion U. S. dollars, and it highlights the race to meet clean energy commitments while satisfying the growing energy demands of cloud computing and A. I. Now, Phil, we all know that A. I. is going to be expensive in the electricity world.
Everybody is worried about it. Microsoft is trying to hedge their bets at the minute. Do you expect others like an Amazon to do something similar?
Philip Totaro: Amazon’s been up until this deal, once it officially closes and they actually build and start procuring all this. This is going to be the biggest corporate renewables procurement in history.
Amazon’s been doing their fair share and was leading up until this point. But this is this is massive. So it let’s put it this way. It looks like, deals like this are going to finally get the tech sector in the mood to say, all right, we like, fixed price contracts with, some degree of certainty and, proven technology now between wind and solar particularly for cloud applications or AI applications where, it’s going to be, power intensive, I think, the tech sector in general needs needed to, and is getting more on board with this.
Even, my own company builds on AWS. We’ve, contributed to them procuring some renewables capacity as well. And we’re taking the benefit of that too.
Joel Saxum: It’s nice to see Microsoft getting involved in an early stage here, right? At the pipe, not even during the pipeline exercise, but during the pipeline build out of guys, we were going to want this, we’re going to partner with a major developer being Brookfield Renewables, who has a large capital base behind them, of course.
But at the start of it saying we want to do this because you do see the virtual PPAs and those on the corporate PPAs being, But it’s usually like when they’re about built, of course, along the time, the sales people from that energy company are shopping them. But you don’t see the agreements happen at an earlier stage like this very often.
So with Microsoft, of course, being a large consumer of power for, of course, computing, but also the cooling of these centers is going to be a large cost as well. Being a looking in, into their crystal ball and seeing that energy usage going up and up and up, they’re getting to getting engaged with a major developer at an early pipeline stage, I would look to see the next evolution of this thing being like what RWE did last year and sign a large deal with a turbine manufacturer to say, hey, we will want one gigawatts or one, one or two gigawatts of turbines in the next four years.
Can we guarantee our prices on that as well for a development pipeline? Thanks everyone.
Allen Hall: Siemens Gamesa has reported a 365 million euro loss for the second quarter of 2024. A slight improvement from the 386 million euro loss in the same period last year. The turbine manufacturer’s orders were down sharply at 881 million euros compared to 3.
6 billion euros the year prior. Onshore orders were impacted by the pause in sales activities for the 4X and 5X turbans, and profit continues to be impacted by quality issues, increased product costs, and ramp up challenges in the offshore area. Now, Phil, this has had some ramifications within the management of Siemens Gamesa also.
Philip Totaro: So they’ve Announce their CEO is leaving and they’re going to be restructuring the company, including layoffs, probably in core areas within Spain. And they’ve also announced a couple of things. One is that they’re going to be re evaluating their presence in markets like India, for instance.
You saw GE do the same thing when they started looking at pulled out of Brazil because they were looking at margins and profitability and wanted better financial returns and better financial performance. India may become a market that is, left to the the Indian players and the Chinese and Siemens Gomez is going to try and regroup in in core markets.
The other piece of this that came out was that they’re anticipating starting up sales again in August of this year. There are thereabouts so we all look forward to that and hope that they can get themselves back on track because unfortunately with this, 350 million euro, or I’m sorry, 365 million euro loss indicates is that they’re still not getting enough services revenue that’s offsetting.
Their expenses around having to fix all these blades and pay out all the liquidated damages and interruptions that they’ve had to pay out on as a result of, this quality issue.
Joel Saxum: I think in this quarterly report, the numbers that stick out to me is that 880 million in orders as compared to 3. 6 million. Billion from last year. So that’s 25 percent of the order book. That’s live right now within Siemens since this quarter last year. So expect to see them have larger loss numbers. When Q3 or Q4 revenue gets realized as compared to the year before. Now we all saw this coming. We knew it was going to happen.
Of course, when you stop selling your flagship turbine model on shore you’re going to have some revenue issues, but I think it, it actually extends a little bit further into the market than just the 4x, 5x platforms. Example, I had a conversation last week at, or this week at ACP with an operator.
Who said yeah, we’re looking at some wind farms. We regularly either by Vestas or GE. And that’s probably what we will stick with for one thing. We don’t work on it. We don’t have any Siemens in our fleet, so we don’t work on them. And also at this point in time, we’re not willing to jump into the ring.
on with a company that’s having issues. So there’s not only not selling that 4x, 5x, but the feeling around them is that the operators still aren’t looking at them during their RFPs.
Allen Hall: Brazilian industrial machinery manufacturer WEG is to enter the wind generation market in the United States. The company will utilize his factory in Minneapolis, Minnesota to manufacture its seven megawatt wind turbine platform.
Like it’s not disclosed the investment figure, but states it is not significant and is part of the approved capital budget. The Minneapolis plant with 45, 000 square meters and around 200 employees will start supplying equipment from 2026. In the meantime, we will commence commercial activities to secure sales contracts and develop the local supply chain while maintaining its commitment to win.
generation in Brazil and India. Now, Phil, we were just in Minneapolis for American Clean Power. This is a big discussion on the show floor.
Philip Totaro: Absolutely. And it’s actually pretty interesting news for a couple of reasons. One obviously WEG’s been developing turbines down in Brazil for a little more than 12 years now.
And started off with a license from Northern Power Systems on a turbine, evolved it into a three and then a four and then jumped up to a seven now there’s plenty of kind of opportunity down in Brazil for. A seven megawatt turbine because they’ve got a lot of open space where they can stick those things.
So bringing it to the US market is going to be interesting to see what the appetite is for a turbine that big. However, the one thing that came out of the clean power event was the fact that every. I spoke to said, we want a third option, knowing that GE and Vestas are dominating the U S market at this point.
And that I don’t know what their perception issue is with Nord X, even though it looks like Nord X actually seems fine. It might be some issues with their their services division, but their turbines actually perform pretty well. But like we just talked about with Siemens Gamesa pulling back from selling.
an opportunity open for companies like Weg to step into the U S market. And it’s, it will be something that’s welcomed by the entire market if and when they can get Something bankable and proven into this market. So that’s going to start with them, getting a prototype site up and running, getting their, type certification for, that would be applicable for the U. S. market in place and making sure that the financiers understand that, they’re a third bankable option besides just GE and Vestas.
Joel Saxum: Yeah, interesting thing here is that to enter the market, you almost have to find a gap in it, right? So there, we know that there’s 2 megawatt, 2. 5, 2. 8, 3, 3. 4, 4x, 5x, and now even GE announcing a 6 megawatt quote unquote, workhorse machine at ACP last year.
This 7 megawatt machine fills a hole that doesn’t exist in the market in the U. S. right now. Because I think the big Nordex one, correct me if I’m wrong, fills a hole. That one’s six, isn’t it? Or five and a half? Correct. Not saying it’s filling a gap, because there isn’t a gap there, they’re actually in a spot where there is nobody right now.
That seven megawatt space, if someone wants a seven megawatt machine, This is the machine they got to buy. There’s an opportunity there, but we’ll see how it develops.
Allen Hall: Canadian pension plan investment board and global infrastructure partners have entered into an agreement to acquire us energy firm elite for 6.
2 billion, including the assumption of debt elite. And it’s. Subsidiaries focus on driving clean energy transition through expanding renewables, reducing carbon emissions, enhancing grid resiliency, and driving innovation. The partnership with CPP Investments and GIP will provide Elite with access to significant capital for its planned investments while remaining committed to its existing customers, communities, and employees.
The acquisition is expected to generate substantial value for Elite stakeholders and further GIP’s commitment to serving growing market needs. Now, Phil, this one was unexpected when it was announced. Elite obviously has a really good reputation in the United States. It seems like a nice investment for CPP and GIP.
Philip Totaro: Absolutely, and it gives the Canadian Pension Plan Investment Board and GIP an opportunity to continue growing their footprint, particularly the CPP IB because they’ve got, obviously investments in Canadian renewables and renewables. all over
the place, so the, this, just continues a theme that we’ve been talking about probably for about nine months on the show where infrastructure funds are definitely plowing a lot more money into acquiring. Pipelines of deals sorry, acquiring pipelines of projects through these acquisition deals, acquiring operating portfolios and even companies that can compliment, we go back to a deal like Macquarie acquiring a company like Onyx Insight somebody who can provide them with, some insight into asset management and performance.
This deal for elite is a solid one. 50, more than 52 percent of their portfolio operates at or above a P50 energy yield, according to our analytics at Intel store. It’s a pretty healthy and robust portfolio. It was just wind alone was about $3 billion worth of CapEx investment.
Plus when you add in the solar, I think, the 6 billion plus is a pretty good price tag for for what Elite brings to the table.
Joel Saxum: Something to remember here that Phil actually touched on briefly there is G. I. P. is backed by BlackRock. Okay? BlackRock, of course, one of the, is the biggest investment vehicle in the world, trillions of dollars in assets.
But they recently came out and said, we’re going to put 12 billion into the renewable energy space and purchasing G. I. P. So what we’re seeing here is G. I. P. and the BlackRock money continuing to filter down through other markets and being the capital being utilized to further the clean energy transition.
https://weatherguardwind.com/microsoft-siemens-gamesa-weg-manufacturing/

 It’s easy to understand how Trump has great appeal to the hateful idiots and the amoral rich.
It’s much harder to see how it’s possible that a huge number of eligible voters are uninvolved in guiding the future of the United States, with many of them saying that “both sides are the same.”
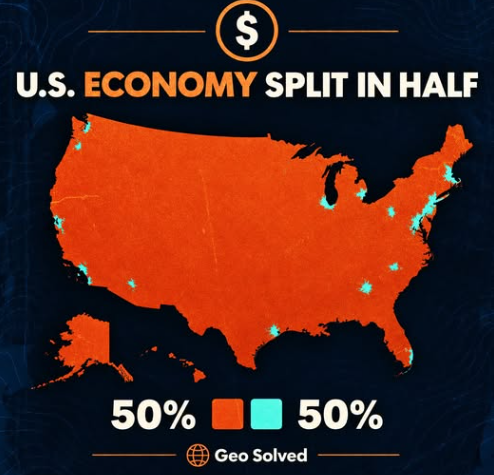 We often hear the MAGA folks claim that voting in the U.S. disproportionate favors the people in big cities, mostly along the coasts.
The obvious response: People vote, not acres of land.
And yes, it’s true that Trump has little appeal to the well-educated, highly productive people in Southern California, the Bay Area, the Mid-Atlantic, New England, other large cities like Chicago, Phoenix, Houston, and Seattle.
Weather Guard Lightning Tech
Global fleet, local knowledge: closing wind’s expertise gap
This exclusive article originally appeared in PES Wind 3 – 2026 with the title, Global fleet, local knowledge: closing wind’s expertise gap. It was written by Allen Hall and other members of the Weather Guard Lightning Tech team.
As wind fleets expand across increasingly diverse operating environments, the expertise needed to solve their problems is becoming more dispersed. Closing the industry’s knowledge gap means connecting local challenges with specialist experience from across the global wind sector and beyond.
An operator finds something on a blade they have not seen before. Who do they call? The engineer who designed that blade moved on years ago. The service provider has not seen the problem either. Somewhere in the world, there’s probably a person who has spent 15 years working on precisely that failure mode. But there’s no reliable way to find them.
That scenario plays out again and again. It’s rare that a problem is unsolvable. A solution exists somewhere. The bigger problem is finding that solution, or the person close to solving it.
Wind has become a large, geographically dispersed industry with roughly 1.3 TW of installed capacity. The technical knowledge required to keep it running has dispersed with it. The knowledge is real, deep and often highly specialized, but it is scattered across the globe in small teams working in different markets.
This is not the first global industry to discover that no single organization can hold every discipline, and that different parts of the world present different problems.
Two answers, one problem
In January 2023, Andrew Billingsley took a call from Ørsted asking whether his company could recycle wind turbine blades. Billingsley is CEO of Plaswire, a polymer processor in Northern Ireland. It was not a wind company. Plaswire’s business had been built on finding a way to use plastics from aircraft seat manufacturing and other waste nobody else would handle: residue pulled out of biodigesters and municipal waste plants.
He said yes before he was certain the company could do it.
Plaswire had a proprietary process for combining polymers that materials engineers said couldn’t be combined. Ground blade fiber mixed well with the combined polymer. Plaswire says it now has capacity to process up to 11,000 tonnes of blades a year and has increased blade content in its product from ten percent to thirty percent. The company also reports that the resulting structural components can outperform the concrete and timber alternatives they replace.
The same waste stream produced an entirely different answer on the other side of the Atlantic. Everpoint Services in Houston, Texas decommissions wind and solar assets, leaving the company tasked with repurposing fiberglass blades. At a birthday party, Everpoint CEO Tyler Goodell put that problem to James Timmins, a drilling engineer who had spent his career planning and overseeing drilling operations for major oil companies.
Timmins realized that ground blade fiber might work as a fluid loss additive in oil, gas, and geothermal drilling, where fluid escaping into the formation can cost tens of thousands of dollars a day. Everpoint spent the next two years turning that idea into a product. The company says BladeBlok is patented and shipping globally from Houston.
Two regions, two answers, both effective. And in retrospect, it makes perfect sense. Northern Ireland has decades of depth in polymers and injection molding, so its answer was a polymer. Houston is a center of the global oil and gas industry, so its answer was drilling mud. Neither answer came out of the wind industry. Both came from regional industrial expertise meeting a problem that happened to land next to it.
Looking beyond Denmark
Modern wind turbine engineering grew up in Denmark, and in many ways it still lives there. The most prevalent turbine design was refined by Danish engineers. DTU Wind and Energy Systems still anchors much of the research on wind turbines. Ask a hard aerodynamic question today and there is a fair chance the answer comes from within Denmark.
What has changed is that designing turbines and operating them are different problems. They no longer happen in the same places. A machine is designed in a small number of locations. It is then operated wherever the wind blows: West Texas, Queensland, Gujarat, the North Sea, and the Spanish meseta.
The fleet is also getting older and more varied as it grows. Machines commissioned during the last boom are aging in ways nobody modeled, on sites with conditions nobody anticipated. That combination generates operational questions faster than any single organization can answer them. Those questions are local, specific, and urgent. Now, companies all over the world are being asked to solve wind’s problems with legacy knowledge, often from an adjacent industry, that originated a long way from where the turbine was built.
The same blade, four climates
The industry’s leading-edge erosion wisdom is shaped largely by northern European conditions. It is a real problem, well studied and well understood. It is also not the same problem in West Texas, where the air carries dust and insects, and where inspections routinely find turbines one to three years old that look as though they have run for far longer. Will Howell of Armour Edge describes one site near an open-cast mine where airborne marble particulates were destroying blades within two seasons.
India produces a variant that exists nowhere in Europe. During the northern dry season, a sticky, tar-like dirt builds on the blades until the flow separates and the blade effectively stalls. The monsoon washes it away. PowerCurve reports that the use of vortex generators in India has produced some of the largest energy gains it has recorded, exceeding five percent across a full year. India is now the fourth-largest wind market on earth, surpassing 56 GW; last year it added more capacity than Germany did.
Rosemary Barnes worked for a Danish blade manufacturer before returning to Australia in 2021 to work in operations. There, she found blades behaving unlike the ones she had known in Europe. The standard method of predicting erosion severity combines annual rainfall with tip speed. But when Barnes plotted Australian sites with known erosion problems against those two axes, she got a random scatter. The model had no predictive value in Australia.
Her firm, Pardalote Consulting, is now placing scientific-grade sensors in Australian wind farms to establish what actually drives erosion there. [Barnes is also a regular host of The Uptime Wind Energy Podcast.]
A library of experts
Today, finding the right specialist can be difficult.
After six years hosting the Uptime Wind Energy Podcast, I increasingly think of the podcast as a library. In the past year alone, we’ve highlighted solutions from companies in Latvia, Denmark, Northern Ireland, Spain, Australia, Scotland, and the United States. As an organizer of the Wind O&M Australia event, one of our goals has been to bring international expertise to the local market. And similarly, to allow the global market to learn from knowledge that has been internal to Australia.
The answers are out there
The wind industry does not have time to solve the same problem twice. Fleets are aging, budgets are tight, and a blade defect that sits unresolved for a season costs real production. The pressure is to move faster, and the fastest way to solve a problem is rarely on your own. The fastest way to solve a problem is to find the person who has solved it. That search has to be a global one. The specialist who understands your failure mode may be in Copenhagen, Riga, Edinburgh, or Houston, working for a company you have never heard of. Geography is not a reason to rule them out. Increasingly it is the reason to go looking. The Uptime Wind Energy Podcast has become one way of documenting that dispersed expertise, bringing together specialists working on specific problems across different markets.
The answers are out there.
Unless otherwise noted, images here are from The Uptime Wind Energy Podcast.
Contact us for help understanding your lightning damage, future risks, and how to get more uptime from your equipment.
Download the full article from PES Wind here. Previous articles you may want to read:
Find a practical guide to solving lightning problems and filing better insurance claims here
See how a cohesive operational strategy can dramatically improve reliability and profitability



